
 Automotive Paint Robots Market | 2026-2036
Automotive Paint Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Paint Robots Market Analysis
Multi-sourcing of paint robot fleets is expanding as vehicle assemblers diversify vendor relationships to mitigate supply risk and capture regional service responsiveness. ABB leverages its integrated paint process control systems to anchor large European OEM contracts. KUKA AG competes through its automotive systems division, which sustains dense installer networks across German and Chinese production corridors. FANUC Corporation dominates high-volume Japanese and North American assembly plants with its arc-welding-derived motion platforms adapted for spray applications.
Automotive paint robots are programmable manipulators equipped with atomizers, electrostatic bells, or spray guns that apply primer, base coat, and clear coat to vehicle bodies with film-thickness tolerances below five micrometers. These systems execute consistent coverage across complex surfaces while reducing material waste and volatile organic compound emissions in enclosed spray booths. Articulated robots lead installed capacity due to six-axis reach envelopes that access door jambs, hood undersides, and roof rails without fixture repositioning. Collaborative robots represent the fastest-expanding technology segment as manufacturers trial human-robot shared stations for touch-up and repair tasks. System integrators capture the dominant distribution channel role by bundling robots with conveyors, booth controls, and recipe management software into turnkey paint shop contracts.
EPA emission standards and REACH chemical restrictions compel OEMs to specify low-VOC coating compatible with closed-loop robot application systems. OSHA ventilation requirements and China's MEE air quality rules further tighten spray booth specifications, directly influencing robot sealing, explosion-proofing, and washdown protocols. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and national content requirements reshape the geographic logic of paint robot procurement and aftermarket service deployment.
Market Dynamics
The transition from solvent-borne to waterborne coating systems is forcing OEMs to retool entire paint shops, driving capital deployment toward robots capable of handling thinner film-build processes with precision tolerances below five micrometers.
Growth Catalysts
- EPA VOC Emission Rules:US environmental mandates compel vehicle manufacturers to install closed-loop robot application systems that capture and recycle overspray, reducing volatile organic compound discharge from spray booths.
- Waterborne Coating Compatibility:The shift to low-viscosity water-based primers and clear coats requires robotic atomizers with recirculating spray guns that maintain consistent flow rates across temperature variations.
- Electric Vehicle Production Scaling:Battery electric vehicle assemblers in China, Germany, and the United States are commissioning greenfield paint shops with fully automated lines to meet production targets.
Market Restraints
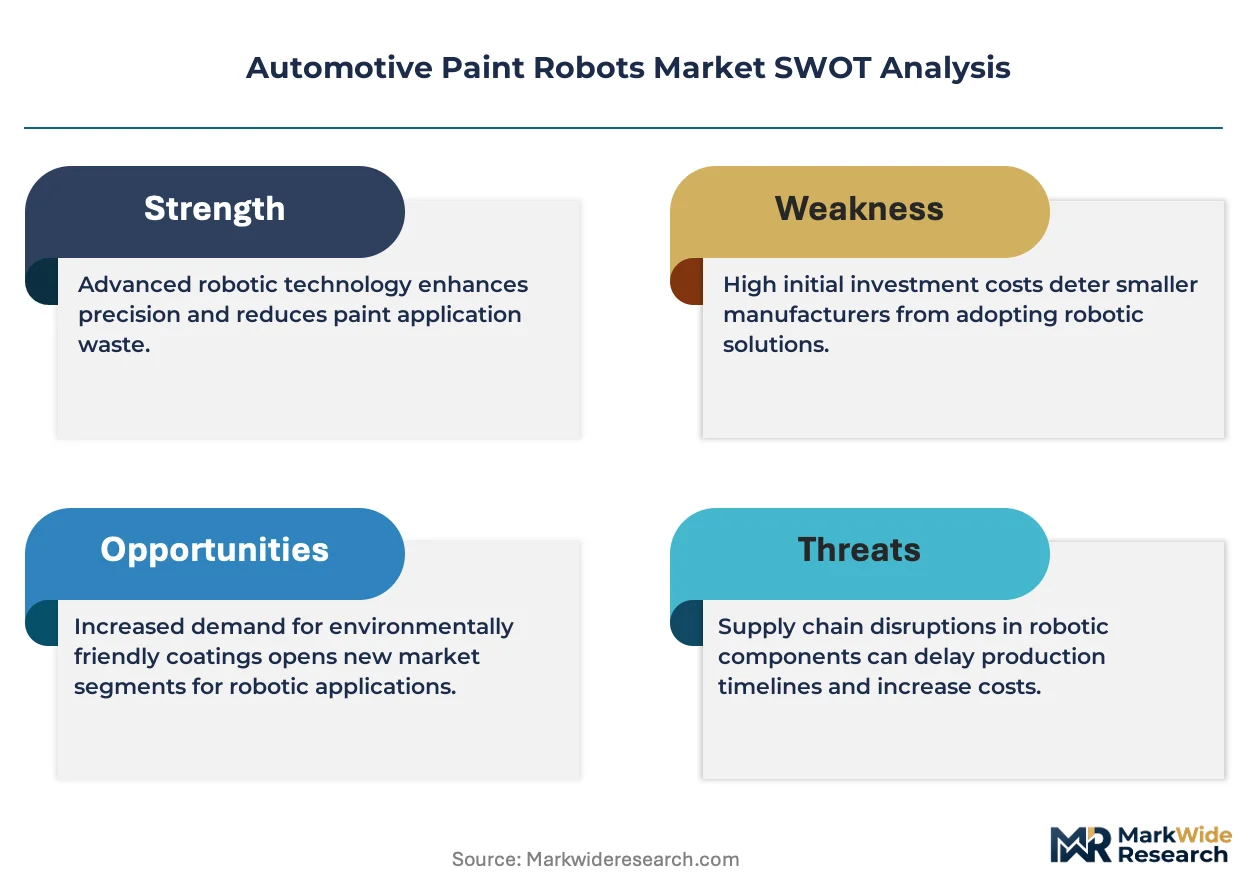
- High Capital Intensity:Complete paint shop retrofits require substantial investment in explosion-proof robot enclosures, booth ventilation upgrades, and integrated process control systems.
- Supply Concentration Risk:Precision servo motors and harmonic drives for six-axis articulated arms concentrate among Japanese and German component suppliers, creating vulnerability to regional logistics disruptions.
- REACH Chemical Restrictions:European regulations on coating raw materials limit formulation options, forcing robot programmers to adapt spray patterns to modified paint chemistries with altered drying characteristics.
Strategic Opportunities
- Collaborative Robot Touch-Up Stations:Human-robot shared workspaces for defect repair and spot finishing remain underdeployed, offering entry points for cobot specialists targeting mid-volume assembly plants.
- India Automotive Corridor:Domestic OEM expansion and contract manufacturing growth create demand for first-time robot installations in Pune, Chennai, and Gurugram production clusters.
- Carbon Border Adjustment Mechanisms:Emerging EU tariffs on embodied carbon in imported vehicles incentivize regional paint shop automation to demonstrate low-emission manufacturing credentials.
Industry Challenges
- Explosion-Proof Certification Timelines:ATEX and IECEx approvals for robot electrical systems in volatile spray booth environments extend product launch schedules by twelve to eighteen months.
- Paint Process Engineer Scarcity:The specialized knowledge required to program film-thickness recipes across complex body geometries outpaces vocational training pipeline output in manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Paint Robots Market |
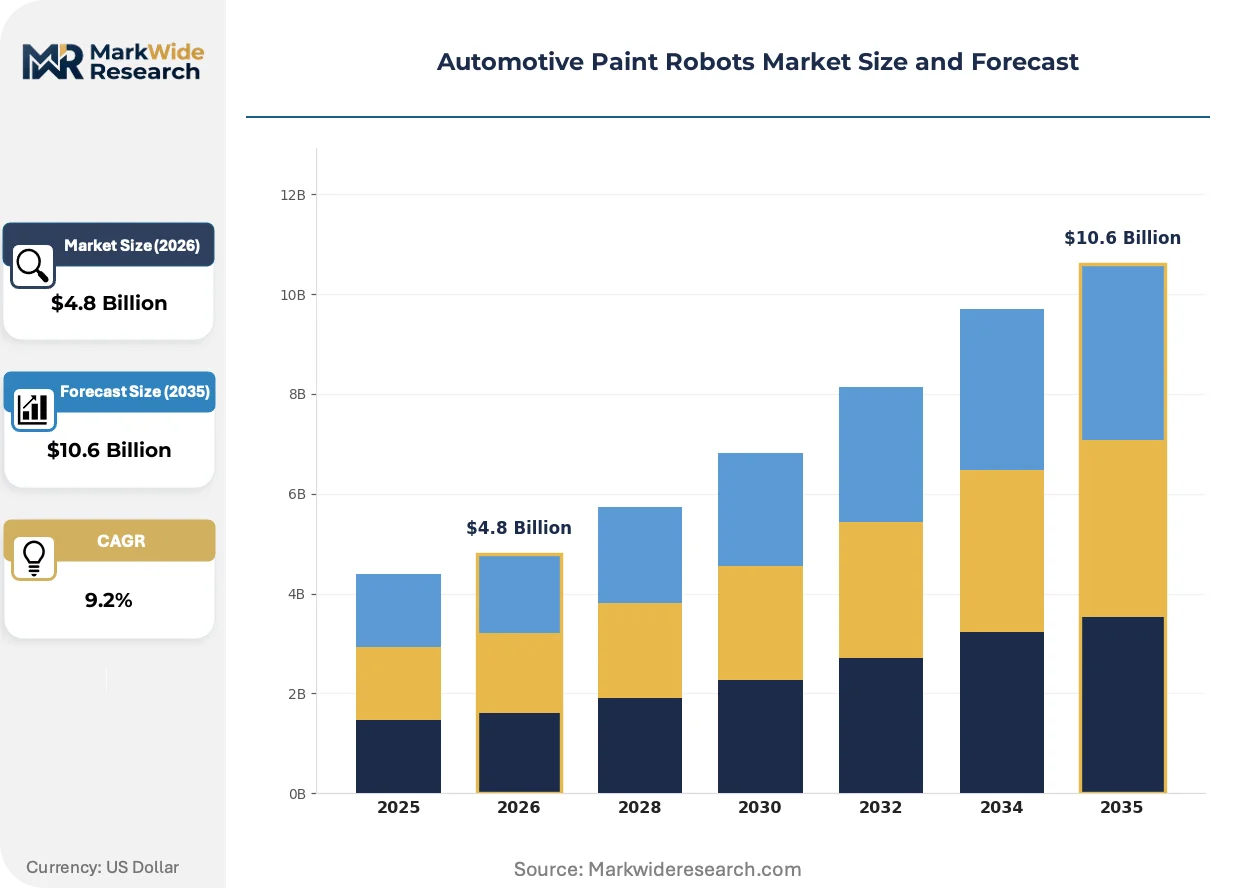
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Articulated Robots, Robotic Arms, Collaborative Robots, 3D Printing Robots End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Base Coating, Clear Coating, Priming, Touch-Up Distribution Channel: Direct Sales, Online Retail, Distributors, System Integrators |
| Companies Covered | Yaskawa Electric Corporation, Kawasaki Heavy Industries, ABB, Comau S.p.A., Staubli International AG, FANUC Corporation, Dürr AG, CMA Robotics Spa, KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Paint Robots Market Emerging Trajectories
Digital thread integration is collapsing the boundary between design simulation and shop-floor execution, enabling real-time adjustment of spray parameters based on body-in-white dimensional data captured upstream.
Integrated process control software is unifying robot motion planning with booth environmental management and conveyor tracking into single-platform architectures. Tier-one suppliers in Germany and Japan are deploying these unified systems at new electric vehicle facilities. The consolidation eliminates data latency between coating application and quality feedback loops.
China's MEE air quality enforcement is tightening permissible particulate and VOC discharge limits for automotive manufacturing zones. Paint shops in Shanghai and Guangdong must now demonstrate continuous emissions monitoring tied to robot operating parameters. Facilities are responding by installing sealed robot cabinets with positive-pressure nitrogen purging.
Fleet standardization across multiple OEM plants is compressing vendor qualification cycles and favoring integrators with proven multi-site deployment records. System houses that delivered turnkey paint shops in Stuttgart and Spartanburg now compete for replication contracts in emerging production corridors. This pattern concentrates procurement authority with central engineering teams rather than regional plant managers.
Automotive Paint Robots Market Segmentation
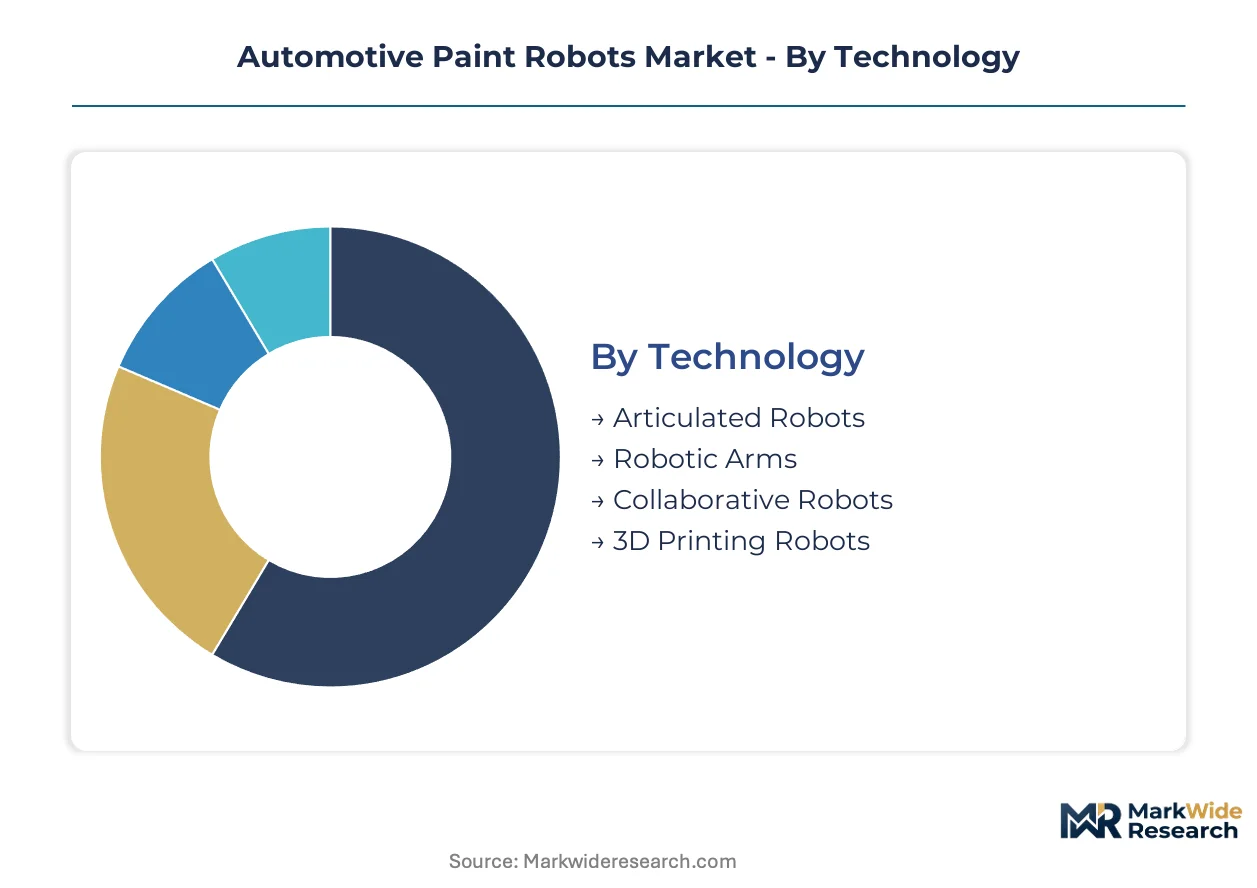
Automotive paint robot procurement varies sharply by production scale, coating chemistry, and integration complexity. Understanding these segment boundaries clarifies why six-axis articulated systems dominate OEM installations while collaborative platforms penetrate repair operations.
Technology:
The customization-to-standardization spectrum runs from fully configurable six-axis systems to plug-and-play collaborative units with limited payload ranges.
- Articulated Robots:Six-axis configurations with harmonic drive precision deliver sub-five-micrometer film-thickness tolerance across door jambs and roof rails. Demand concentrates at BMW, Mercedes-Benz, and Volkswagen Group facilities in Germany where waterborne clear coat processes require complex motion envelopes.
- Collaborative Robots:Force-limited platforms with ISO/TS 15066 safety certification enable human-robot shared stations for defect repair. These systems are expanding most quickly in Japanese and South Korean assembly plants trialing touch-up automation without full booth isolation.
- Robotic Arms:Cartesian and SCARA configurations provide linear precision for primer application on flat body panels.
- 3D Printing Robots:Hybrid deposition-spray systems remain experimental for custom coating thickness modulation.
Leading the category by volume: Articulated Robots. Expanding most quickly: Collaborative Robots.
End User:
Margin structures diverge between capital-intensive OEM paint shop retrofits and service-oriented aftermarket installations.
- OEMs:Original equipment manufacturers specify explosion-proof integrated systems with ATEX certification for greenfield electric vehicle paint shops. Volkswagen, BYD, and Tesla commission turnkey lines with unified process control software.
- Tier-1 Suppliers:Magna, Plastic Omnium, and Yanfeng demand standardized robot platforms for bumper and fascia coating cells serving multiple OEM customers.
- Vehicle Assemblers:Contract manufacturers require rapid reconfiguration capabilities for mixed-model production.
- Aftermarket Providers:Collision repair chains deploy compact robotic cells for spot refinishing with reduced booth footprint.
Dominant procurement authority: OEMs. Fastest volume acceleration: Tier-1 Suppliers.
Application:
Process sequence position determines robot sealing specifications and washdown protocol intensity.
- Base Coating:Electrostatic bell atomizers with 90-kV charging systems deposit metallic and pearl effect layers with 98% transfer efficiency. German and Chinese OEMs drive specification updates for thinner film-build compatibility.
- Clear Coating:High-flow spray guns with recirculating solvent recovery apply UV-curable and two-component polyurethane finishes. EPA VOC rules compel closed-loop overspray capture at US facilities.
- Priming:Cathodic electrocoat deposition uses submerged robotic anode arrays for corrosion protection.
- Touch-Up:Manual-assist cobot stations address post-bake defect repair with reduced material waste.
Highest installed base: Base Coating. Steepest technology refresh cycle: Clear Coating.
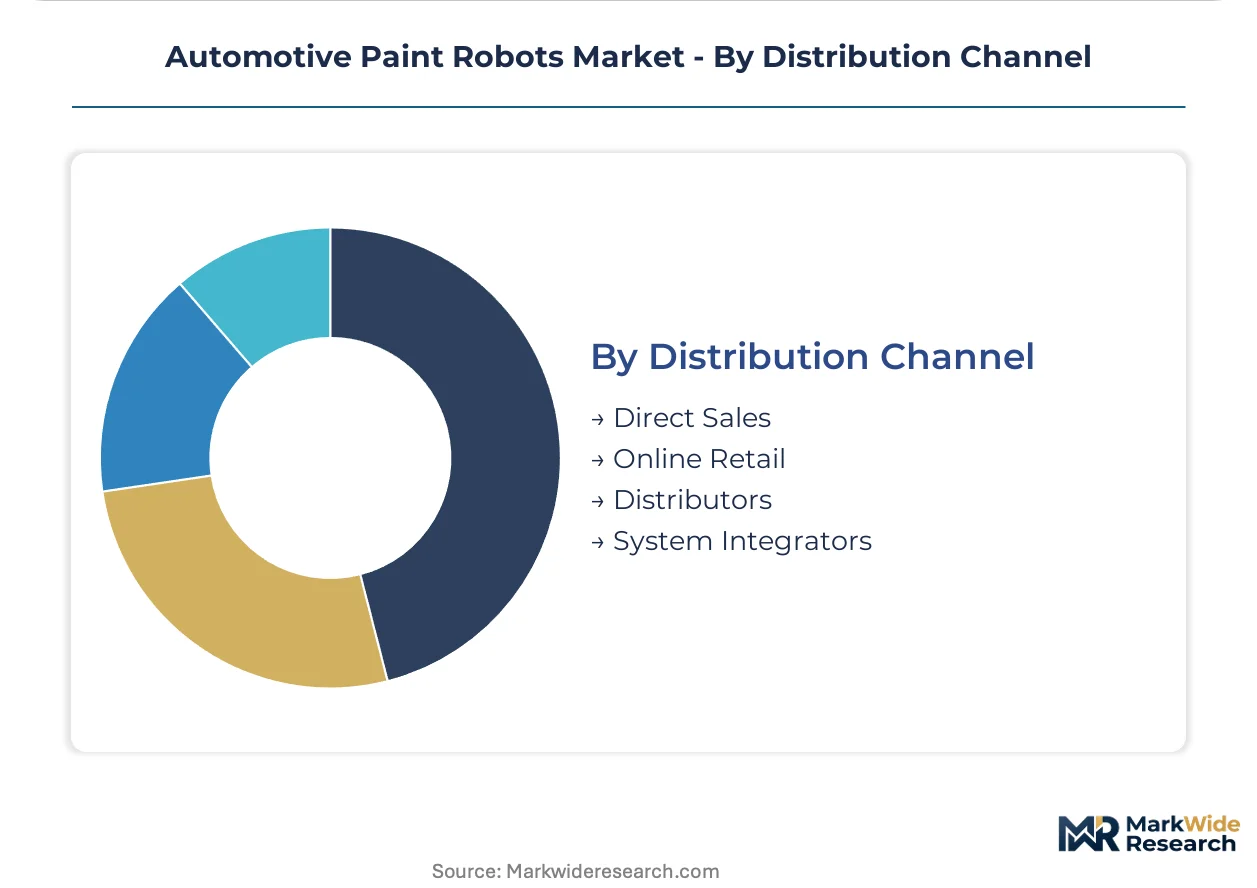
Distribution Channel:
Supply chain proximity to engineering expertise shapes channel selection across production corridors.
- System Integrators:Turnkey paint shop bundlers such as Dürr and Eisenmann anchor European procurement by combining robots with booth controls and conveyor tracking. These firms capture the dominant revenue share by delivering single-platform architectures.
- Direct Sales:FANUC and ABB maintain factory-direct relationships with high-volume Japanese and North American OEMs for fleet standardization across multiple plants.
- Distributors:Regional stocking dealers serve mid-volume assembly plants with shorter lead time requirements.
- Online Retail:Spare parts and consumables platforms support aftermarket maintenance operations.
Primary volume channel: System Integrators. Fastest structural gain: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision servo motor clusters and Japanese harmonic drive manufacturing anchor the geographic foundation of automotive paint robot supply chains. Component sourcing from these industrial bases shapes final system assembly locations. OEM procurement decisions track regulatory enforcement intensity across production corridors.
China
BYD and Tesla Shanghai drive explosive demand for greenfield paint shop automation. MEE air quality enforcement mandates continuous emissions monitoring tied to robot operating parameters. Guangdong and Shanghai production clusters install sealed robot cabinets with positive-pressure nitrogen purging to meet discharge limits.
Germany
Volkswagen Group and Mercedes-Benz specify six-axis systems for waterborne clear coat compatibility. REACH chemical restrictions limit coating formulation options, forcing spray pattern adaptations. Stuttgart and Wolfsburg anchor the densest installer networks for integrated process control systems.
United States
EPA VOC emission rules compel closed-loop overspray capture at Michigan and Tennessee assembly plants. Tesla Nevada and Rivian Illinois commission fully automated lines for electric vehicle scaling. OSHA ventilation requirements tighten explosion-proofing specifications for robot electrical systems.
Japan
FANUC Corporation anchors high-volume supply to domestic Toyota and Honda facilities. METI industrial automation incentives support collaborative robot trials for touch-up stations. Nagoya and Tokyo Bay manufacturing corridors concentrate precision servo motor production for six-axis arms.
India
Maruti Suzuki and Tata Motors expansion drives first-time robot installations in domestic assembly. BIS certification requirements for industrial equipment extend vendor qualification timelines. Pune and Chennai production clusters attract system integrators targeting mid-volume contract manufacturing growth.
Automotive Paint Robots Market Vendor Landscape
Multi-sourcing of paint robot fleets dominates the current landscape as vehicle assemblers diversify vendor relationships to mitigate supply risk. The vendor base concentrates around integrated system houses and standalone robot manufacturers. Three archetypes define competitive positioning: turnkey paint shop bundlers, motion platform specialists, and collaborative robot innovators. Strategic partnerships and portfolio diversification represent the dominant competitive moves, with geographic expansion following OEM factory retooling cycles.
Among Japanese motion control specialists, Yaskawa Electric Corporation and FANUC Corporation exemplify the high-volume production archetype with dense presence across Toyota and Honda supply chains. ABB represents the integrated process control tier, leveraging its European base to anchor contracts with German OEMs requiring unified software architectures. KUKA AG occupies a position bridging standalone robotics and automotive systems integration, particularly across German and Chinese production corridors where its installer networks sustain replication contracts.
| Leading Market Players |
|---|
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries |
| ABB |
| Comau S.p.A. |
| Staubli International AG |
| FANUC Corporation |
| Dürr AG |
| CMA Robotics Spa |
| KUKA AG |
| Others |
Supply Flow & Price Mechanics
Waterborne coating conversion across German and Chinese assembly plants simultaneously elevates precision requirements and compresses supplier margins, concentrating procurement leverage with system integrators capable of bundling robot hardware with process control software and emissions compliance architecture.
Pricing Analysis
Warranty and service bundling separates turnkey paint shop contracts from unbundled robot-only transactions, with Dürr and Eisenmann commanding premium positioning through multi-year maintenance agreements. Three-tier pricing structure across premium ATEX-certified systems, standard industrial configurations, and economy refurb units tracks certification grade and integration complexity. Cost compression in the economy tier is intensifying because Tier-1 suppliers demand standardized platforms for bumper coating cells. Small contract manufacturers in India exhibit the highest price sensitivity, while German OEMs prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Refurbishment flows for harmonic drives and servo motors from Japanese facilities back to German robot assemblers are creating secondary supply channels for mid-volume buyers. Component manufacturing concentrates in Japan, Germany, and China, with precision motion control hardware drawing from Nagoya and Stuttgart industrial clusters. Supply chain vulnerability rests on single-source dependencies for explosion-proof electrical enclosures. Distribution runs through system integrators bundling robots with booth controls and conveyor tracking into single-platform architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive paint robot procurement is consolidating around integrators with multi-site deployment records, as EPA and MEE enforcement timelines eliminate vendors lacking certified emissions-monitoring integration.
For Market Incumbents: Lock in fleet standardization contracts with central OEM engineering teams before replication cycles accelerate in India and Southeast Asia. Defend against collaborative robot specialists by embedding force-limited platforms into existing process control architectures. Prioritize ATEX certification pipeline investments to compress eighteen-month approval timelines.
For New Entrants and Emerging Players: The price-point gap between premium German integrated systems and economy Chinese alternatives creates entry space for mid-tier cobot specialists. Target Japanese and South Korean touch-up station trials with ISO/TS 15066-certified platforms requiring reduced booth isolation. Pursue direct sales relationships with battery electric vehicle startups commissioning greenfield paint shops.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial automation conglomerates seeking paint shop integration capabilities. Long-term viability favors vendors with demonstrated multi-site deployment records across three or more production corridors. Monitor MEE enforcement intensity in Shanghai and Guangdong for demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Process Control Software Integration | Unifies robot motion planning with EPA-mandated emissions monitoring at Tesla and Rivian facilities. |
| Explosion-Proof Certification Acceleration | Compresses ATEX and IECEx timelines to match OEM retooling schedules for waterborne coating conversion. |
| Collaborative Robot Touch-Up Deployment | Enables human-robot shared stations for defect repair without full spray booth isolation requirements. |
| Regional Installer Network Expansion | Establishes service density in Pune and Chennai to support Maruti Suzuki and Tata Motors capacity additions. |
| Fleet Standardization Contracts | Locks in multi-plant procurement authority with Volkswagen Group and BYD central engineering teams. |
Methodological Framework
Document review covered SEC filings from robot manufacturers, EPA enforcement actions, and MEE discharge permits, complemented by interviews with paint shop engineers, Tier-1 supplier procurement leads, system integrator project managers, and aftermarket service heads. Secondary validation drew from vehicle production databases, customs records for precision motion components, and IHS Markit registration data. Bottom-up unit demand estimates triangulated against top-down OEM capital expenditure disclosures.
Cross-referencing historical installation patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include robot technology type, coating chemistry compatibility, end-user tier, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions calibrated to electric vehicle production scaling trajectories and paint shop retrofit cycle timing.
Inputs from MEE permit databases and EPA compliance records were available through the study window; gaps in forthcoming REACH amendment timelines introduce uncertainty bands around European coating chemistry assumptions. Practitioners should monitor carbon border adjustment mechanism finalization and BIS certification timeline updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
South America Gear Market
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Qatar Commercial Vehicles Lubricants Market
Automotive Parts
Russia Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Engine Cam Cover Market