
 Automotive Hydraulic Filter System Market | 2026-2036
Automotive Hydraulic Filter System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Hydraulic Filter System Market Intelligence
The adoption of synthetic microglass filter media with higher beta efficiency ratings is redrawing the performance benchmarks for hydraulic systems. Parker Hannifin Corporation leverages its extensive distribution network to supply these advanced filters directly to original equipment manufacturers. HYDAC Technology Corporation specializes in integrated hydraulic solutions, bundling filters with sensors and fluid condition monitoring. Donaldson Company, Inc. competes on the durability of its filtration products designed for demanding off-highway applications in mining and construction.
Automotive hydraulic filter systems are critical components designed to remove contaminants like dirt, metal particles, and degraded fluid byproducts from hydraulic oil. These systems often incorporate multi-layer media capable of achieving specific ISO 4406 cleanliness codes, crucial for protecting sensitive pumps and valves. Cartridge filters represent a dominant filter type due to ease of service, while the OEM channel constitutes the primary end-user segment for initial system integration. Within applications, construction equipment and agricultural machinery show consistent demand driven by vehicle population and replacement cycles.
Equipment reliability and safety standards, such as the EU's Machinery Directive and specific GB standards in China for construction machinery, indirectly mandate high-performance filtration. In the United States, EPA regulations on non-road diesel engine emissions encourage the use of efficient hydraulic systems, which depend on clean fluid. Component suppliers must now decide whether to focus on specialized high-performance filters or compete on volume in the aftermarket service segment.
Market Dynamics
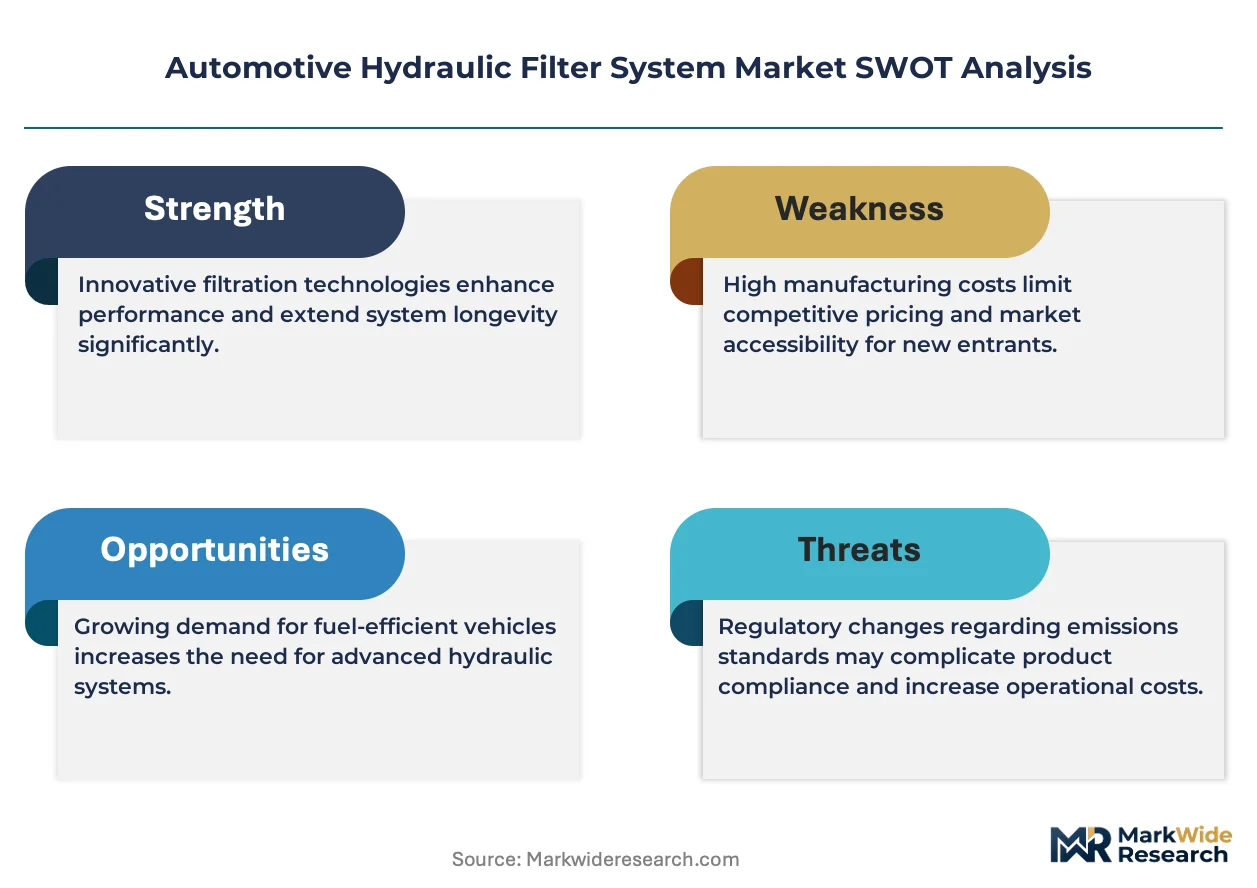
The transition toward higher-pressure hydraulic systems is the central force shaping the automotive hydraulic filter market. This engineering shift, aimed at improving vehicle performance and fuel efficiency, increases the sensitivity of pumps and valves, demanding more advanced filtration technologies to maintain system integrity and prevent premature wear.
Growth Catalysts
- Infrastructure Investment:Government-backed infrastructure projects, particularly in Asia, stimulate demand for new construction equipment. This directly drives the market for OEM-installed hydraulic filters that meet specific performance criteria, such as China's GB standards for machinery.
- Higher-Pressure Systems:The adoption of hydraulic systems operating at higher pressures requires cleaner fluid to protect sensitive components. This necessitates filters with advanced media capable of achieving stringent ISO 4406 cleanliness codes, boosting demand for premium products.
- Environmental Regulations:Emissions standards, like the EPA's Tier 4 rules for non-road diesel engines in the United States, encourage the development of more efficient hydraulic systems. Clean hydraulic fluid is essential for the reliability of these optimized systems.
Market Restraints
- Higher Input Costs:Advanced synthetic microglass filter media offers superior performance but comes at a significant cost premium compared to traditional cellulose media. This price difference can slow adoption in cost-sensitive aftermarket segments and developing economies.
- Substitution by Electrification:The long-term trend toward battery-electric powertrains in smaller commercial and off-highway vehicles poses a direct substitution threat. Fully electric systems eliminate the need for hydraulic circuits and their associated filtration components entirely.
- Supply Chain Concentration:A significant portion of heavy vehicle assembly and component manufacturing is concentrated in specific industrial hubs within China. This creates a potential vulnerability to regional supply chain disruptions, which could impact global filter availability.
Strategic Opportunities
- Integrated System Monitoring:There is a clear opportunity to bundle hydraulic filters with sensors for real-time fluid condition monitoring. This creates value-added "smart" filtration solutions that enable predictive maintenance and appeal to fleet operators focused on uptime.
- Aftermarket in Agricultural Sector:The large and aging global population of agricultural machinery, such as tractors and harvesters, presents a substantial opportunity. Developing specialized, durable filters for the replacement market in this sector can capture consistent revenue streams.
- Safety Standard Alignment:Stricter equipment safety regulations, including the EU's Machinery Directive, create an opportunity for suppliers of high-performance filters. Marketing products based on their ability to enhance system reliability and safety can provide a competitive edge.
Industry Challenges
- Global Standards Compliance:Manufacturers face the challenge of designing and certifying products that comply with a diverse array of regional standards. Navigating the requirements of the EU's directives, China's GB standards, and North American regulations requires significant investment in testing.
- Competition from Low-Cost Alternatives:In the aftermarket, suppliers of premium, high-efficiency filters face intense competition from low-cost, lower-specification products. This price pressure can erode margins and makes it difficult to communicate the long-term value of superior filtration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hydraulic Filter System Market |
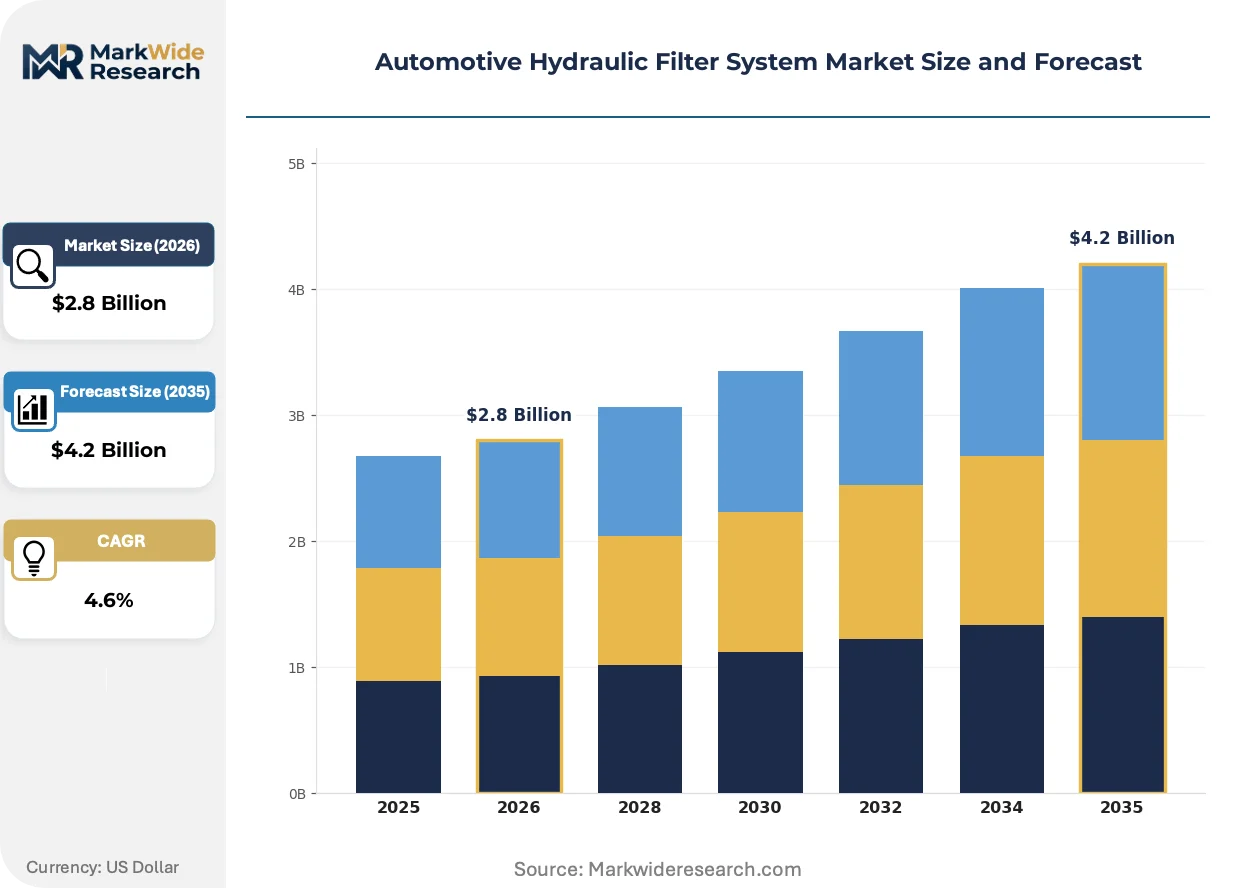
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Spin-On, Cartridge, Magnetic, Pleated Technology: Mechanical Filtration, Electrostatic Filtration, Media Filtration, Centrifugal Filtration Application: Construction Equipment, Agricultural Machinery, Mining Equipment, Material Handling Machines End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Mahle GmbH, Pall Corporation, Parker Hannifin Corporation, Filtration Group Corporation, HYDAC Technology Corporation, UFI Filters SPA, Donaldson Company, Inc., Eaton Corporation plc, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hydraulic Filter System Market Strategic Shifts & Innovations
A fundamental shift is underway from basic contamination control toward proactive system health management. This evolution is driven by the convergence of advanced filter materials, which extend component life, and the integration of digital monitoring technologies that provide visibility into fluid condition and system performance.
Synthetic microglass media provides superior filtration efficiency by capturing finer contaminants than traditional materials. Original equipment manufacturers in demanding sectors like construction and mining are adopting these filters to protect sophisticated, high-pressure hydraulic components. This advanced media is displacing conventional cellulose-based filters, particularly in applications where extending service intervals and ensuring maximum equipment uptime are critical operational priorities.
European Union regulations, specifically the Machinery Directive, indirectly influence filter design by mandating high levels of equipment safety and reliability. A hydraulic system failure can pose a significant safety risk, so the directive incentivizes the use of high-performance filtration to prevent such events. Consequently, manufacturers of off-highway equipment destined for the EU market are integrating filters capable of achieving and maintaining high fluid cleanliness levels to ensure compliance.
Fleet operators are increasingly adopting a total cost of ownership (TCO) approach to procurement and maintenance, moving beyond initial component price. This behavior disrupts the traditional, volume-driven aftermarket by placing a premium on filters that extend fluid life, reduce component wear, and minimize unscheduled downtime. This trend is most visible in North American and European logistics and construction sectors, where data analytics are used to optimize vehicle lifecycle costs.
Automotive Hydraulic Filter System Market Segmentation
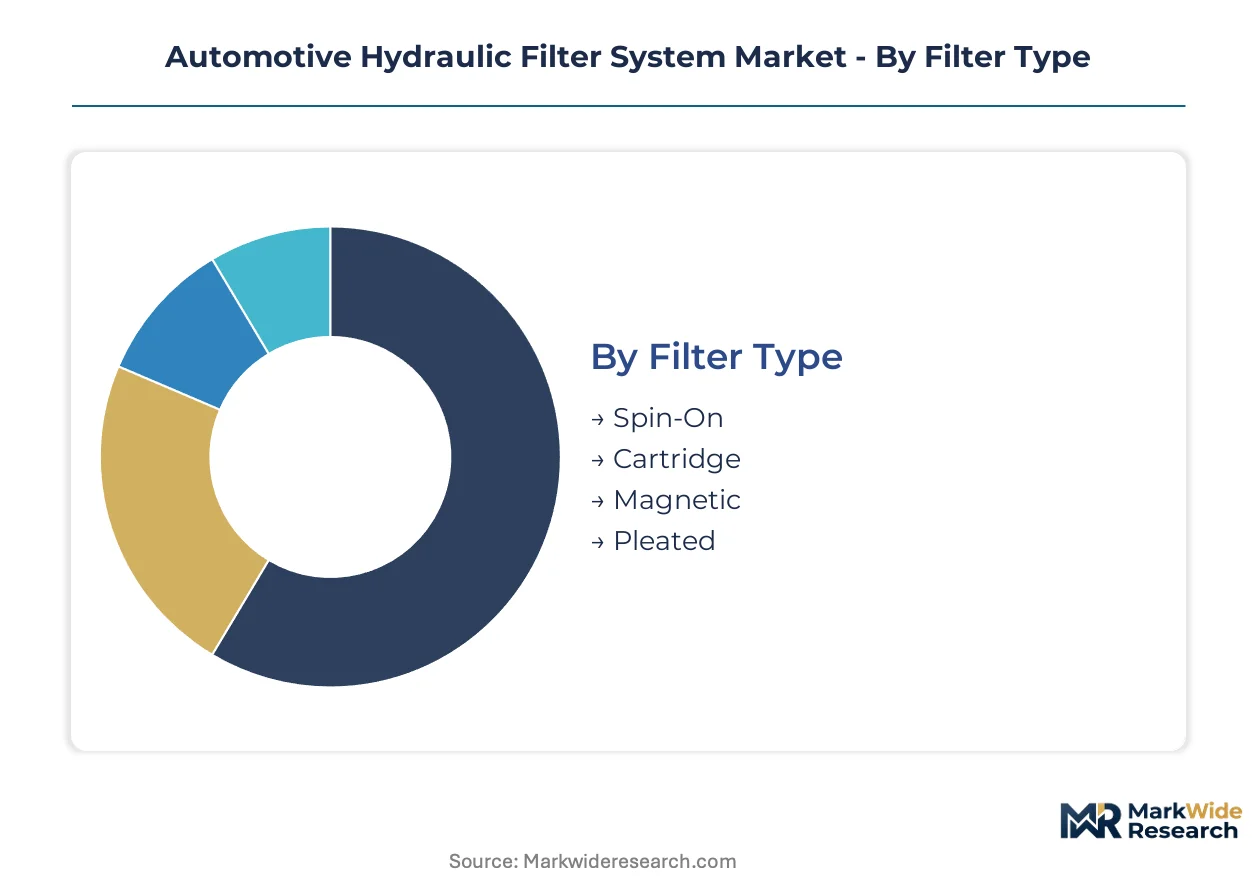
Understanding the segmentation within the automotive hydraulic filter system market reveals critical pathways for product development and market penetration. Analysis of filter types, underlying technologies, diverse applications, and distinct end-user segments provides a granular view of demand drivers and competitive dynamics. This structural breakdown informs strategic decisions for component suppliers.
Filter Type:
The distribution channels for automotive hydraulic filters vary significantly based on the filter type, influencing how they reach original equipment manufacturers and aftermarket service providers.
- Cartridge:Cartridge filters comprise a replaceable element housed within a permanent casing, designed for straightforward servicing and reduced waste. Demand concentrates within the OEM channel for initial system integration, driven by requirements for ease of maintenance and specific cleanliness codes.
- Pleated:Pleated filters feature a folded filter media, often synthetic microglass, which maximizes surface area for enhanced dirt-holding capacity and higher beta efficiency. These advanced filters see significant demand in construction equipment and mining applications, where extended service intervals are critical for operational uptime.
- Spin-On:Spin-on filters integrate the filter element and housing into a single disposable unit, offering convenience for routine maintenance tasks.
- Magnetic:Magnetic filters utilize strong magnets to capture ferrous particles from hydraulic fluid, complementing traditional media filtration in critical systems.
By volume, cartridge filters lead the market, while pleated filters are gaining share fastest due to their advanced performance characteristics.
Technology:
Different filtration technologies present varying cost structures, influencing their adoption rates across premium, standard, and economy segments within the automotive hydraulic filter market.
- Media Filtration:Media filtration employs porous materials like synthetic microglass or cellulose to physically trap contaminants based on particle size and shape. This technology is essential for achieving stringent ISO 4406 cleanliness codes in modern high-pressure hydraulic systems, particularly for sensitive pumps.
- Mechanical Filtration:Mechanical filtration involves physical barriers or screens to remove larger particles from hydraulic fluid, serving as a primary or pre-filtration stage. Demand for this foundational technology remains consistent across all heavy machinery, providing essential protection against gross contamination.
- Electrostatic Filtration:Electrostatic filtration uses an electric charge to attract and capture sub-micron particles, offering high efficiency for fine contaminant removal in critical applications.
- Centrifugal Filtration:Centrifugal filtration separates heavier particles from hydraulic fluid through rotational force, often used for coarse contaminant removal or as a bypass filter.
Media filtration holds a substantial share within the technology segment, while electrostatic filtration exhibits considerable expansion as systems demand higher cleanliness.
Application:
The volume of hydraulic filters consumed directly correlates with the population and operational intensity of various heavy equipment applications across the globe.
- Construction Equipment:Construction equipment, including excavators and loaders, represents a significant application for hydraulic filters due to demanding operational environments and high usage rates. Infrastructure projects in Asia, particularly China, drive substantial OEM demand for these filtration systems.
- Agricultural Machinery:Agricultural machinery, such as tractors and harvesters, requires robust hydraulic filtration to protect critical components from dust and debris encountered during fieldwork. The extensive global installed base of agricultural vehicles creates a consistent and substantial aftermarket for replacement filters.
- Mining Equipment:Mining equipment operates under extreme conditions, necessitating highly durable and efficient hydraulic filters to prevent premature wear in harsh environments.
- Material Handling Machines:Material handling machines, including forklifts and cranes, rely on hydraulic filters to maintain clean fluid, ensuring precise operation and extending component lifespan.
Construction equipment remains the largest application segment for hydraulic filters, with agricultural machinery contributing significantly to aftermarket revenues.
End User:
Different end-user types exhibit distinct purchasing behaviors and product requirements, shaping the supply strategies for automotive hydraulic filter manufacturers.
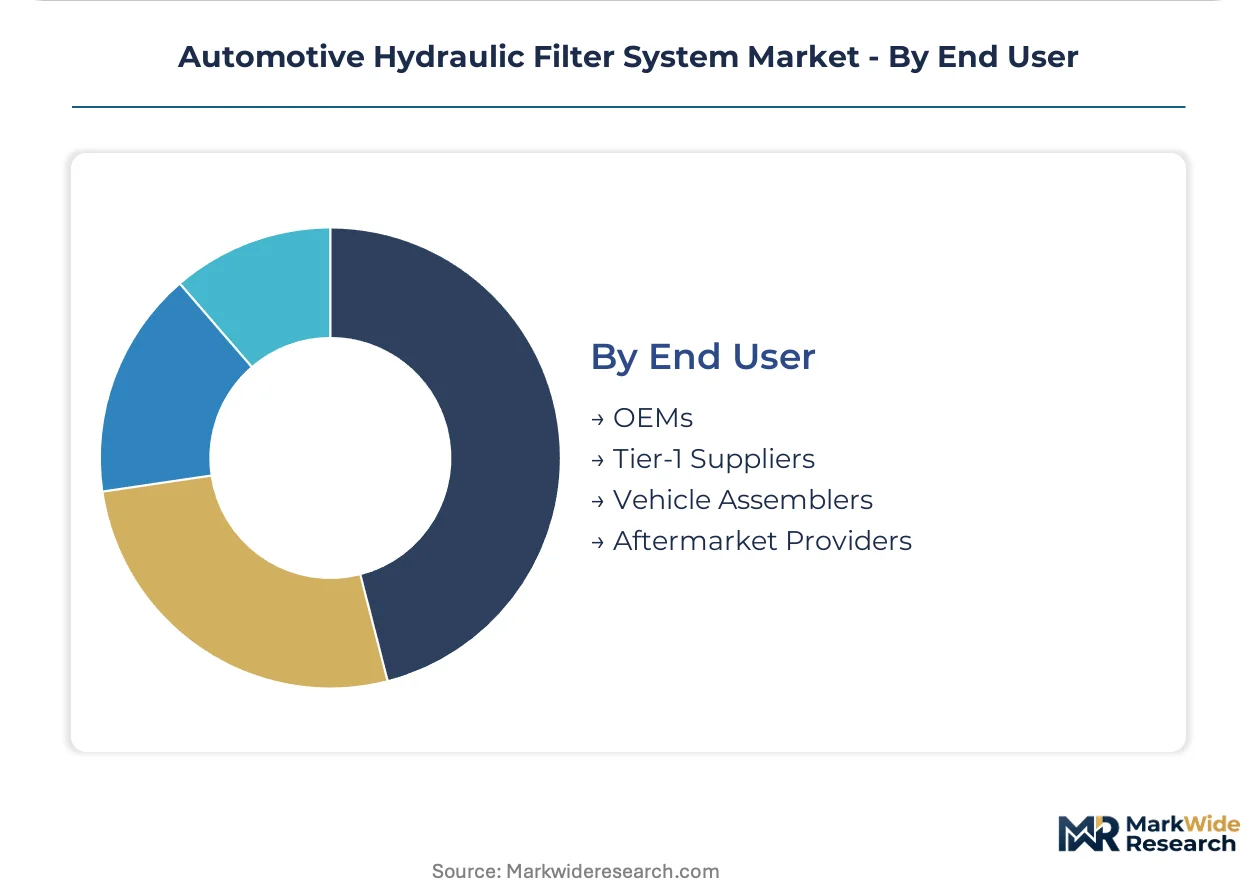
- OEMs:Original equipment manufacturers integrate hydraulic filter systems directly into new vehicles during assembly, demanding high-performance, custom-engineered solutions that meet stringent specifications. This segment prioritizes system compatibility, reliability, and adherence to regulatory standards like GB standards in China.
- Aftermarket Providers:Aftermarket providers supply replacement hydraulic filters for existing machinery, focusing on accessibility, competitive pricing, and broad product compatibility. This segment serves fleet operators seeking cost-effective maintenance solutions and extended equipment uptime.
- Tier-1 Suppliers:Tier-1 suppliers source hydraulic filters for integration into larger sub-assemblies before supplying them to vehicle assemblers, emphasizing reliability and volume consistency.
- Vehicle Assemblers:Vehicle assemblers procure hydraulic filter systems as part of their final production process, requiring just-in-time delivery and adherence to quality control protocols.
OEMs represent the primary channel for initial system integration, while Aftermarket Providers drive consistent demand for replacement units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for automotive hydraulic filter systems is evident in key manufacturing regions, driven by robust industrial bases and significant vehicle production. These hubs support both initial equipment integration and the extensive aftermarket for replacement components. Demand is shaped by infrastructure development and stringent regulatory frameworks.
China
China's substantial heavy machinery manufacturing hubs drive a significant portion of global OEM demand for automotive hydraulic filters. The country's GB standards for construction machinery implicitly mandate high-performance filtration to ensure equipment reliability. Industrial clusters in the Yangtze River Delta and Sichuan-Chongqing regions are central to vehicle assembly and component production.
United States
Demand for hydraulic filters in the United States stems from its large off-highway and agricultural machinery sectors. EPA regulations concerning non-road diesel engine emissions encourage the use of efficient hydraulic systems, requiring clean fluid. Manufacturing centers in the Midwest, particularly around Illinois and Michigan, serve as key areas for heavy equipment production.
Germany
Germany's advanced engineering and manufacturing capabilities support a strong market for high-performance hydraulic filters. The EU's Machinery Directive influences filter design by mandating high safety and reliability standards for equipment. Baden-Württemberg and Bavaria host significant industrial machinery manufacturers, integrating sophisticated filtration solutions.
India
India's ongoing infrastructure projects and large agricultural sector generate consistent demand for automotive hydraulic filters. Government initiatives promoting domestic manufacturing, such as the PLI scheme, further stimulate the local production of heavy equipment. Industrial zones in Maharashtra and Gujarat are emerging as critical centers for vehicle assembly and component supply.
Japan
Japan's focus on high-precision manufacturing and advanced hydraulic systems creates a market for technologically sophisticated filters. JIS standards ensure quality and performance for hydraulic components used in construction and material handling equipment. The Kanto region, including Tokyo, remains a key hub for engineering and automotive component innovation.
Automotive Hydraulic Filter System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the automotive hydraulic filter market. The market exhibits a tiered structure, with specialized innovators coexisting with high-volume manufacturers. Strategic archetypes include integrated solution providers, component specialists, and aftermarket suppliers. Competitive moves often involve strategic partnerships to expand technological capabilities and portfolio diversification across various application sectors.
Specialists in integrated solutions like HYDAC Technology Corporation exemplify the trend towards bundled offerings, providing comprehensive fluid condition monitoring alongside filtration. Parker Hannifin Corporation, a US-based entity, represents extensive distribution capabilities, leveraging its network to supply advanced synthetic microglass filters directly to original equipment manufacturers. Donaldson Company, Inc., another US-based firm, occupies a strong position in durable filtration products, catering to demanding off-highway applications in sectors such as mining and construction. These firms collectively demonstrate distinct competitive strategies focused on either system integration, broad market reach, or application-specific ruggedness within the global market.
| Leading Market Players |
|---|
| Mahle GmbH |
| Pall Corporation |
| Parker Hannifin Corporation |
| Filtration Group Corporation |
| HYDAC Technology Corporation |
| UFI Filters SPA |
| Donaldson Company, Inc. |
| Eaton Corporation plc |
| Bosch Rexroth |
| Others |
Cost & Logistics Intelligence
Economies of scale in synthetic microglass filter media production directly influence supply concentration within specific manufacturing hubs. This scale advantage drives down unit costs for high-volume players, establishing competitive price floors across the automotive hydraulic filter market.
Pricing Analysis
The EU's Machinery Directive dictates the pricing tier structure for high-performance hydraulic filters, emphasizing safety and reliability. Pricing stratifies across premium, standard, and economy tiers, driven by certification levels like ISO 4406 cleanliness codes and brand premium from established suppliers. Pricing softness runs through the aftermarket segment due to intense competition from low-cost alternatives. OEM buyers are less price-sensitive, prioritizing performance and system compatibility.
Supply Chain Analysis
Inventory management for automotive hydraulic filters often involves strategic stockpiling to mitigate lead-time variability for specialized components. Supply concentrates in China, Germany, and the United States, which host major heavy machinery and filter manufacturing operations. The market draws from synthetic microglass, specialized polymers, and precision metal casings. Regional supply chain disruptions, particularly in China, pose a structural risk, while distribution runs through direct channels to OEMs and a fragmented network of aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive hydraulic filter market operates with a defensive moat, largely due to regulatory entrenchment. Equipment safety standards, such as the EU's Machinery Directive, mandate high-performance filtration, creating significant switching costs for qualified suppliers.
For Market Incumbents:Fortify core market share by investing in advanced synthetic microglass media R&D to meet evolving cleanliness standards. Expand distribution network presence in emerging markets to counter competition from low-cost alternatives. Emphasize certification investment for compliance with stringent regulations like China's GB standards. Maintain strong channel control with OEMs to defend against the long-term threat of electrification.
For New Entrants and Emerging Players:Differentiate on value-added services by bundling filters with fluid condition monitoring sensors for predictive maintenance. Target the underserved aftermarket in the agricultural sector with durable, cost-effective replacement units. The agricultural machinery segment offers a penetrable entry point due to its large installed base and consistent replacement cycles. A strong go-to-market angle involves emphasizing total cost of ownership benefits through extended component life.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized filter manufacturers with strong intellectual property in advanced media. The long-term viability of this market rests on its essential role in protecting high-pressure hydraulic systems and regulatory-driven cleanliness requirements. Acquisition targets should be high-performance filter producers with established OEM relationships and compliance certifications. A key signal to watch is increased M&A activity involving companies specializing in integrated fluid condition monitoring technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Integrated Smart Filters | Bundles filtration with sensors, enabling predictive maintenance for fleet operators. |
| Expand Synthetic Microglass Production | Secures supply of high-efficiency media, meeting demand for advanced hydraulic systems. |
| Strengthen Aftermarket Distribution in Agriculture | Captures consistent revenue from replacement cycles in a large, aging vehicle population. |
| Pursue Global Regulatory Certifications | Ensures market access and compliance across diverse regional standards like GB and EU directives. |
| Form Strategic Partnerships with OEMs | Guarantees early integration into new vehicle designs and long-term supply contracts. |
Research Approach
A spread of perspectives from OEM procurement managers, aftermarket distributors, heavy equipment engineers, and regulatory compliance officers converged on the working assumptions for this study. Primary interviews with these industry stakeholders were triangulated with secondary validation from industry association reports, government trade statistics, and company financial filings. This approach ensured a robust understanding of market dynamics. Both bottom-up and top-down analyses were employed to cross-verify data points.
The segmentation dimensions modeled include filter type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected growth drivers across the analysis window. Key industry-specific forecast inputs included global infrastructure spending projections and heavy vehicle production forecasts. This framework provides a comprehensive outlook for the automotive hydraulic filter market.
Material uncertainties — including accelerated electrification adoption, unforeseen supply chain disruptions, and new emissions regulations — sit outside the modeled envelope. Forecasts reflect assumptions documented through extensive research, but these external factors could significantly alter market trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Automotive Forging Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
Powerglide Shifter Market