
 Brazil Automotive Parts Zinc Die Casting Market | 2026-2036
Brazil Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Parts Zinc Die Casting Market Outlook
Aftermarket software-defined diagnostics and predictive maintenance modules is recalibrating how zinc die casting suppliers monetize component longevity. Pace Industries leverages captive toolmaking capabilities to reduce lead times for complex transmission housings. Sandhar Technologies Ltd anchors its Brazilian position through dedicated R&D centers serving passenger vehicle OEMs. Dynacast competes on thin-wall casting expertise for lightweight engine brackets.
Brazil automotive parts zinc die casting involves injecting zinc alloys with aluminum, copper, and magnesium additions at pressures exceeding 10 MPa into hardened steel molds to produce net-shape components with tolerances near 0.05 mm, primarily serving structural and cosmetic applications where corrosion resistance and dimensional stability matter. Engine components dominate current volume given thermal management demands, while specialty alloys command premium positioning due to INMETRO fatigue-testing requirements. The machined form segment captures higher value-add as OEMs specify tighter tolerances for transmission interfaces.
ANVISA governs material composition disclosure for automotive components in contact with fluids, while INMETRO mandates dimensional certification for safety-critical chassis castings, and ABNT NBR standards align with Mercosur technical regulations to enable cross-border supply. These frameworks elevate entry costs for imported die casters while rewarding domestic producers with certified laboratory infrastructure. Stakeholders must monitor Mercosur-EU trade agreement implementation timelines for potential duty restructuring on European alloy feedstock.
Market Dynamics
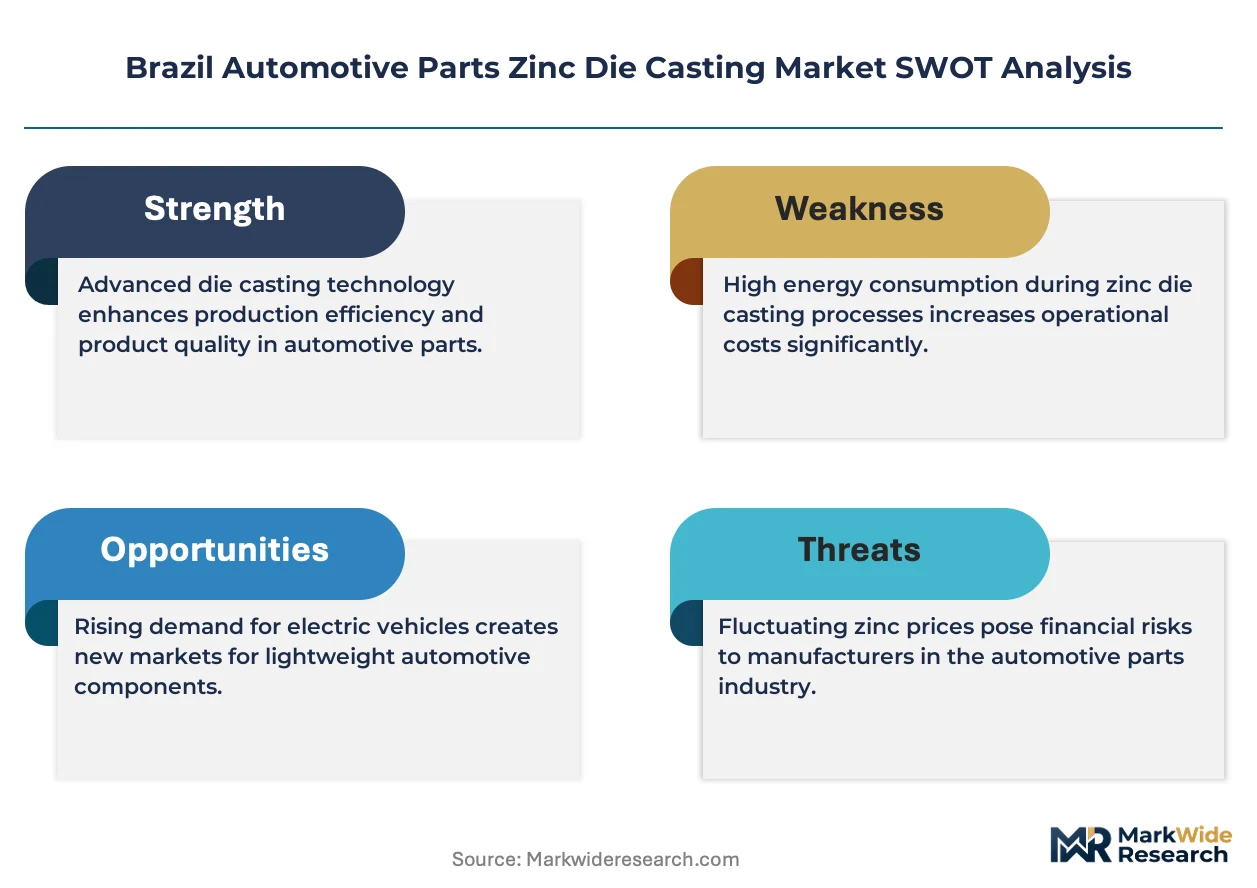
INMETRO fatigue-testing mandates and ANVISA material traceability protocols are compressing supplier qualification timelines while elevating capital requirements for domestic foundry operations across São Paulo's ABC Paulista corridor.
Growth Catalysts
- Localization mandates:Brazilian OEMs including Fiat and Volkswagen are accelerating domestic sourcing quotas for transmission housings and chassis components, redirecting procurement from import-dependent supply chains toward certified local die casters.
- Alloy innovation:Specialty zinc-aluminum-magnesium formulations with enhanced thermal conductivity are capturing specification share in engine management modules where corrosion resistance thresholds have tightened.
- Cluster concentration:Foundry agglomeration within Greater São Paulo's industrial corridor generates tooling cost efficiencies and shared metrology infrastructure that compress lead times for complex thin-wall castings.
Market Restraints
- Aluminum price volatility:Primary aluminum feedstock cost swings transmit directly into zinc alloy pricing, eroding margin predictability for producers locked into annual OEM supply agreements.
- Import dependency:High-purity zinc ingot supply concentrates among a narrow band of international smelters, exposing Brazilian foundries to exchange rate friction and maritime logistics bottlenecks.
- Substitution pressure:Magnesium die casting advances in powertrain brackets threaten zinc's position in non-structural applications where weight reduction carries premium valuation.
Strategic Opportunities
- Aftermarket diagnostics convergence:Integration of sensor-embedded castings with predictive maintenance platforms creates recurring revenue streams beyond component sale, with São Paulo-based Tier 1s piloting telemetry-enabled transmission housings.
- Minas Gerais expansion:Underpenetrated foundry capacity in Belo Horizonte's automotive satellite corridor offers land and labor cost arbitrage for suppliers facing São Paulo state tax compression.
- ABNT NBR harmonization:Alignment with Mercosur technical regulations opens duty-advantaged supply into Argentina and Paraguay assembly plants, particularly for standardized chassis brackets.
Industry Challenges
- Metrology talent scarcity:Certified dimensional inspection technicians capable of operating coordinate measuring machines for 0.05 mm tolerance verification command wage premiums that strain mid-cap foundry payroll structures.
- Dual certification timelines:Simultaneous INMETRO safety-critical approval and ANVISA fluid-contact disclosure creates six-to-nine month qualification windows that delay revenue recognition on new transmission housing programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Parts Zinc Die Casting Market |
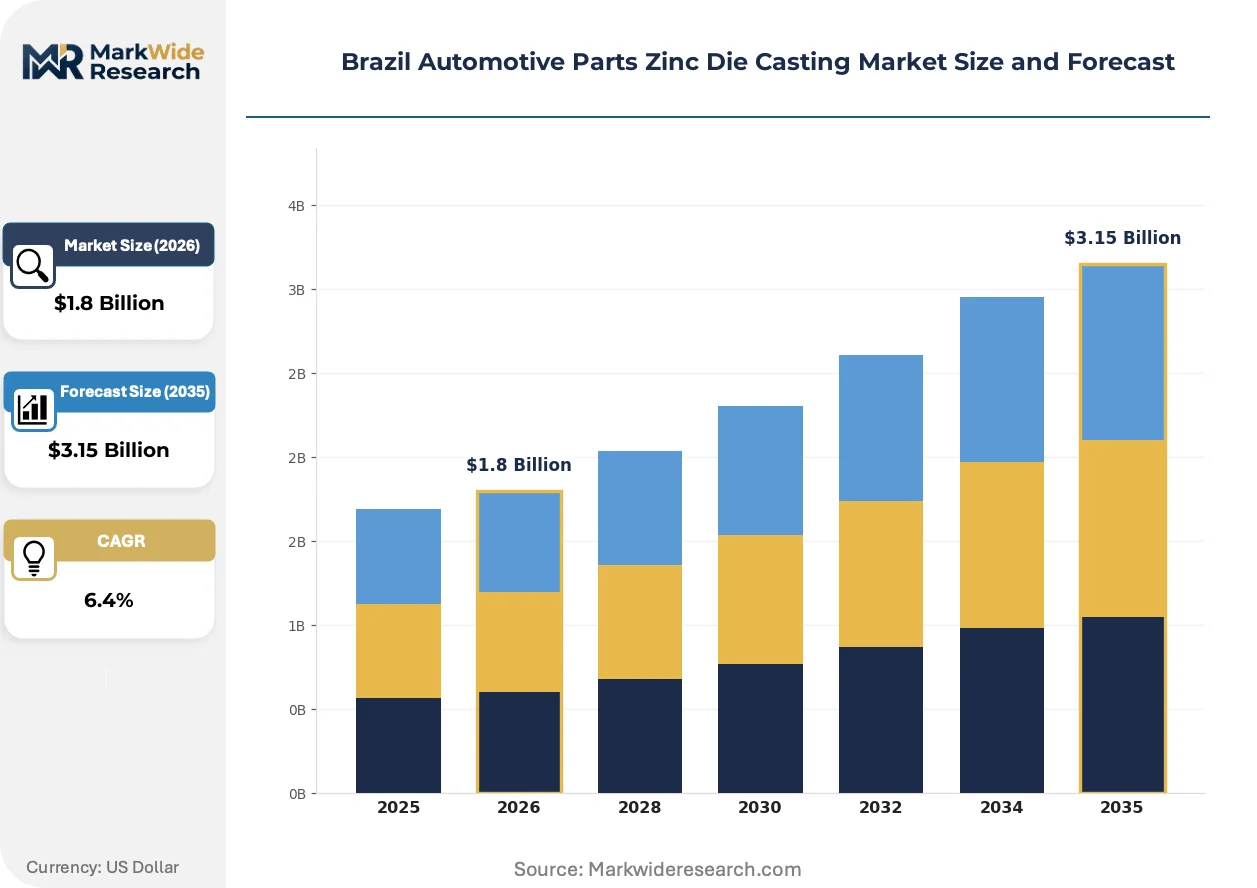
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Chassis Parts, Body Parts Form: Die-Cast, Machined, Plated, Coated Application: OEM, Aftermarket, Commercial Vehicles, Passenger Vehicles Material Grade: High Purity, Corrosion Resistant, Standard Grade, Specialty Alloys |
| Companies Covered | Pace Industries, Empire Casting Co, Sandhar Technologies Ltd, Ningbo Die Casting Company, Kemlows Diecasting Products Ltd, Brillcast Manufacturing LLC, Ashok Minda Group, Cascade Die Casting Group Inc, Dynacast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Parts Zinc Die Casting Market Strategic Shifts
Software-defined component architectures and predictive alloy formulation are compressing traditional die casting value chains while elevating the technical bar for supplier qualification across Brazilian automotive manufacturing.
Multi-axis hot chamber die casting systems with real-time pressure modulation are unifying previously separate trimming and machining operations into single-cycle net-shape production. Tier 1 suppliers serving Volkswagen's Taubaté assembly plant are adopting these integrated cells to meet transmission housing tolerance specifications without secondary finishing. This unification is compressing capital deployment timelines while concentrating capability among foundries with advanced automation infrastructure.
ANVISA's updated material composition disclosure framework for automotive fluid-contact components is mandating batch-level traceability from ingot source through final machining. Foundries must now maintain serialized alloy certificates spanning aluminum and copper additive percentages, with audit documentation extending seven years post-production. Chassis casting specialists in the ABC Paulista corridor are responding by captive-integrating spectroscopy laboratories to accelerate certification turnaround.
OEM technical teams are consolidating supplier panels around vertically capable die casters offering concurrent engineering support during transmission housing design phases. This pattern displaces traditional arm's-length procurement of commodity brackets, favoring partnerships where foundries contribute mold flow simulation expertise prior to tooling commitment. The behavioral shift is most pronounced at General Motors' Gravataí complex, where localized engineering collaboration now precedes volume allocation decisions.
Brazil Automotive Parts Zinc Die Casting Market Segmentation
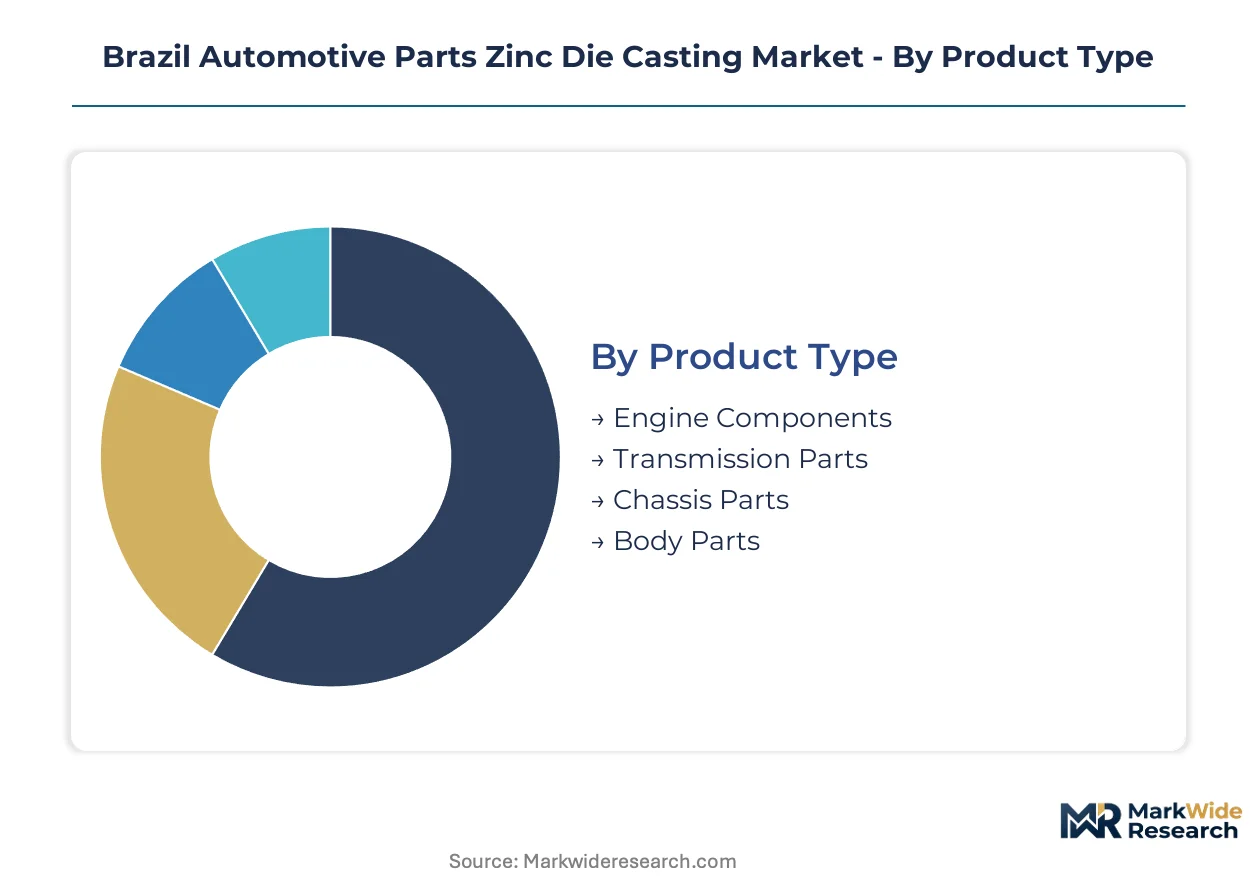
Zinc die casting suppliers in Brazil navigate divergent certification burdens across product categories, with INMETRO safety-critical approval timelines and ANVISA material traceability requirements reshaping how foundries allocate capital across segment portfolios. Segmentation discipline separates commodity bracket producers from vertically capable transmission housing specialists capable of concurrent engineering collaboration.
Product Type:
INMETRO mandates dimensional certification for chassis castings and transmission housings, while ANVISA governs material composition disclosure for engine components in fluid-contact applications.
- Engine Components:Thermal management modules and valve covers demand zinc-aluminum-magnesium formulations with enhanced conductivity. Demand concentrates at Fiat and Volkswagen assembly plants in Greater São Paulo where corrosion resistance thresholds have tightened for engine management systems. OEMs specify these for under-hood applications where dimensional stability under thermal cycling is non-negotiable.
- Transmission Parts:Housing castings for manual and automated transmissions require 0.05 mm tolerance verification through coordinate measuring machines. The ABC Paulista corridor dominates procurement as GM's Gravataí complex and Volkswagen's Taubaté plant localize supply chains for gearbox enclosures. INMETRO fatigue-testing extends qualification timelines to six-to-nine months for new programs.
- Chassis Parts:Structural brackets and suspension anchors carry safety-critical certification burdens under INMETRO protocols.
- Body Parts:Cosmetic trim and decorative hardware face less stringent approval pathways but compete with plastic substitution in cost-sensitive applications.
Leading the category by volume: Engine Components. Growing fastest: Transmission Parts.
Form:
Cost tier separation runs deepest here, with net-shape die-cast volumes competing against higher-value machined and surface-finished alternatives.
- Die-Cast:Hot chamber injection at pressures exceeding 10 MPa produces near-net-shape components with tolerances approaching 0.05 mm. Foundries in São Paulo's industrial corridor capture economies through multi-axis systems with real-time pressure modulation.
- Machined:Secondary finishing operations command premium positioning as OEMs specify tighter tolerances for transmission interfaces and engine mounting points. The value-add concentrates among foundries with captive CNC capacity serving Volkswagen and GM programs.
- Plated:Decorative and corrosion-resistant surface treatments for body hardware and exterior trim applications.
- Coated:Protective layer applications for under-hood components exposed to thermal and chemical stress.
Highest margin capture: Machined. Fastest capacity expansion: Die-Cast.
Application:
Customer type fragmentation separates arm's-length commodity procurement from embedded engineering partnerships.
- OEM:Direct supply relationships with Fiat, Volkswagen, and GM dominate volume allocation, with technical teams consolidating supplier panels around vertically capable die casters offering mold flow simulation expertise prior to tooling commitment.
- Aftermarket:Predictive maintenance convergence creates recurring revenue streams through sensor-embedded transmission housings, with São Paulo-based Tier 1s piloting telemetry-enabled diagnostics platforms.
- Commercial Vehicles:Heavy-duty chassis and powertrain applications for truck and bus manufacturers.
- Passenger Vehicles:Lightweighting priorities in sedan and SUV segments drive thin-wall casting specifications for engine brackets.
Volume concentration: OEM. Fastest value expansion: Aftermarket.
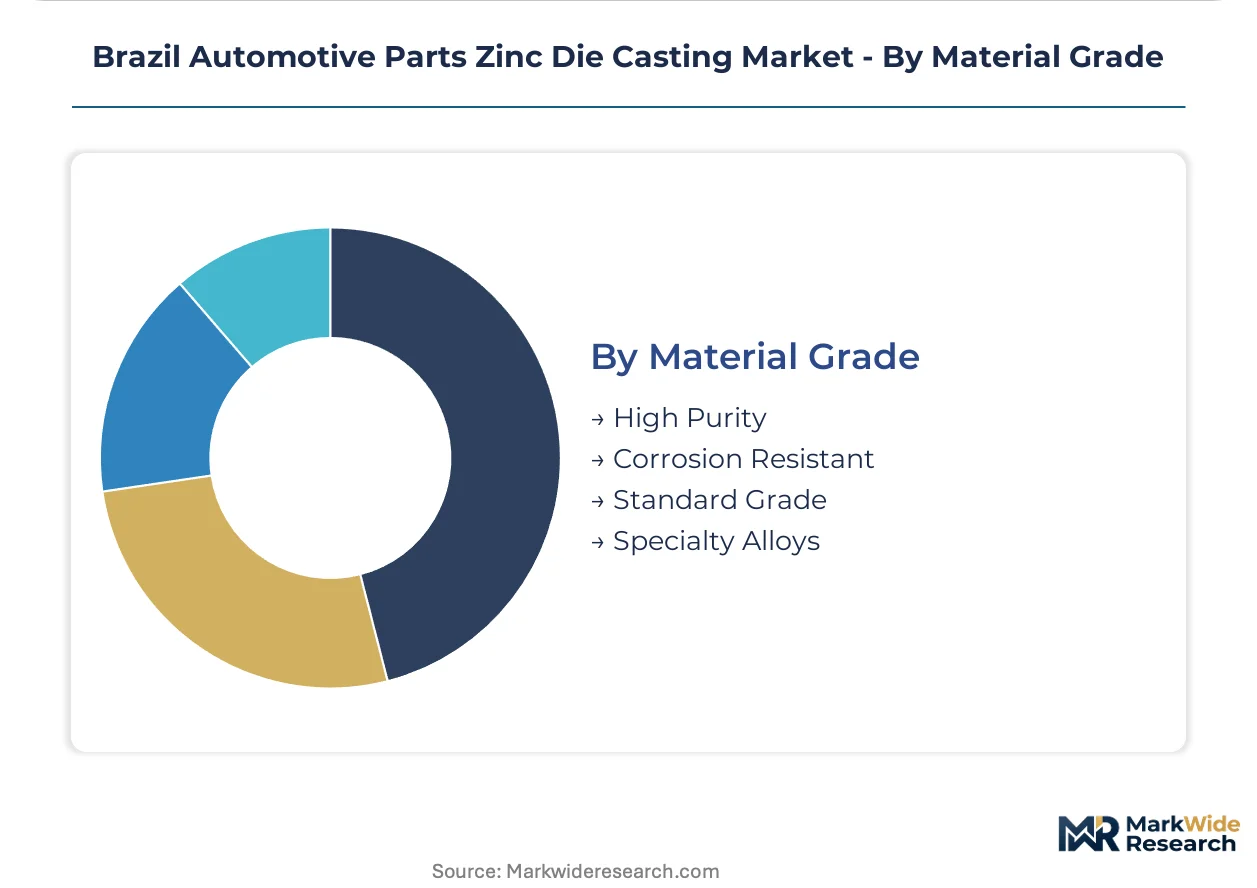
Material Grade:
Supply concentration in high-purity zinc ingot creates tiered access based on smelter relationships and laboratory infrastructure.
- Specialty Alloys:Zinc-aluminum-magnesium-copper formulations command premium positioning due to INMETRO fatigue-testing requirements and enhanced thermal conductivity specifications. Foundries must maintain serialized alloy certificates with seven-year audit documentation.
- High Purity:Smelter-grade feedstock with controlled impurity profiles for safety-critical structural applications. Brazilian foundries face import dependency on a narrow band of international suppliers, exposing operations to exchange rate friction.
- Corrosion Resistant:Formulations optimized for under-hood and underbody exposure environments.
- Standard Grade:Commodity zinc alloys for non-structural brackets and interior hardware where cost minimization dominates specification.
Fastest specification growth: Specialty Alloys. Volume anchor: Standard Grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's zinc die casting production concentrates in São Paulo's industrial corridor while consumption distributes across assembly plants in multiple states, creating a supply geography that differs from demand geography.
São Paulo
The ABC Paulista corridor hosts the densest foundry cluster serving Fiat, Volkswagen, and GM assembly plants with transmission housings and chassis components. ANVISA material traceability requirements and INMETRO certification standards elevate compliance costs for operators in this region. Multi-axis hot chamber die casting systems with real-time pressure modulation dominate capital deployment in Greater São Paulo's tooling-intensive operations.
Minas Gerais
Belo Horizonte's automotive satellite corridor offers underpenetrated foundry capacity with land and labor cost arbitrage for suppliers facing São Paulo state tax compression. The state's mining heritage provides proximity to non-ferrous metal processing infrastructure. Emerging supplier migration to this region targets cost restructuring while maintaining ABNT NBR certification alignment with Mercosur technical regulations.
Rio Grande do Sul
General Motors' Gravataí complex drives localized engineering collaboration for transmission housing programs with concurrent design-phase foundry involvement. The state's automotive supplier density supports tiered procurement networks for safety-critical chassis castings. INMETRO fatigue-testing mandates extend qualification timelines for new component introductions in this southern manufacturing hub.
Paraná
Curitiba's industrial zone anchors Volkswagen's regional supply chain with demand for thin-wall engine brackets and thermal management modules. The state's logistics infrastructure connects to Mercosur export corridors into Argentina and Paraguay. Foundry operators here leverage ABNT NBR harmonization to capture duty-advantaged supply opportunities across southern cone assembly plants.
Brazil Automotive Parts Zinc Die Casting Market Competitive Environment
Top-tier vendors anchor OEM direct supply relationships, while mid-cap specialists populate the indirect tier serving aftermarket and commercial vehicle channels. The market exhibits moderate concentration around vertically capable die casters with captive toolmaking and metrology infrastructure. Two strategic archetypes dominate: integrated foundries offering concurrent engineering support, and commodity bracket producers competing on cycle time. Competitive moves concentrate on backward integration into alloy feedstock sourcing and geographic expansion into underpenetrated state corridors.
Among North American-based operators, Pace Industries and Dynacast occupy positions representing toolmaking-integrated and thin-wall specialization archetypes respectively. Sandhar Technologies Ltd anchors the India-origin contingent with Brazilian R&D center investments. These three exemplify how foreign-headquartered groups structure local presence to navigate ANVISA and INMETRO dual certification requirements while accessing OEM technical collaboration programs.
| Leading Market Players |
|---|
| Pace Industries |
| Empire Casting Co |
| Sandhar Technologies Ltd |
| Ningbo Die Casting Company |
| Kemlows Diecasting Products Ltd |
| Brillcast Manufacturing LLC |
| Ashok Minda Group |
| Cascade Die Casting Group Inc |
| Dynacast |
| Others |
Value Chain & Pricing Dynamics
Primary aluminum feedstock cost swings transmit directly into zinc alloy pricing, eroding margin predictability for producers locked into annual OEM supply agreements while compressing tier separation between commodity bracket suppliers and transmission housing specialists. Brazilian foundries absorb exchange rate friction through contract escalation clauses tied to London Metal Exchange benchmarks, with São Paulo's ABC Paulista corridor operators commanding premium positioning through INMETRO-certified laboratory infrastructure.
Pricing Analysis
Cost-down pressure on standard-grade alloy castings accelerates because OEM procurement teams consolidate supplier panels around vertically capable die casters offering concurrent engineering support. Pricing stratifies across premium, standard, and economy tiers based on INMETRO fatigue-testing certification status and captive CNC machining capability. Margin tightening in commodity brackets traces to magnesium substitution threats in non-structural powertrain applications. Aftermarket sensor-embedded transmission housings exhibit lowest price sensitivity due to recurring telemetry revenue streams, while body hardware trim faces severe plastic substitution pressure.
Supply Chain Analysis
Dual-sourcing mandates from Fiat and Volkswagen procurement teams require qualified secondary suppliers for transmission housing programs, compressing single-source dependency risks. High-purity zinc ingot supply draws from Peru, Australia, and Kazakhstan smelters, exposing Brazilian foundries to maritime logistics bottlenecks and currency volatility. Specialty alloy formulations with aluminum-magnesium-copper additives hinge on import channels through Santos port. Distribution runs through Tier 1 supplier consolidation points in Greater São Paulo before final assembly delivery to GM's Gravataí complex and Volkswagen's Taubaté plant.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's zinc die casting sector is becoming a vertical-integration race as foundries captive-source spectroscopy laboratories and toolmaking capabilities to compress INMETRO-ANVISA dual certification timelines. Players pursuing upstream alloy feedstock relationships and downstream predictive maintenance platform partnerships will capture disproportionate margin expansion.
For Market Incumbents: Extend captive metrology infrastructure investments to defend against emerging Minas Gerais cost-arbitrage entrants targeting Belo Horizonte's underpenetrated automotive corridor. Deepen mold flow simulation capabilities to secure concurrent engineering roles at General Motors' Gravataí complex ahead of transmission housing program renewals. Consolidate backward integration into high-purity zinc ingot sourcing through long-term offtake agreements with Peruvian and Australian smelters. For New Entrants and Emerging Players: Commercial vehicle aftermarket distributors represent the most penetrable buyer archetype for telemetry-enabled chassis casting pilots, with sensor-embedded suspension anchors offering white-space entry before OEM qualification barriers solidify. Target Minas Gerais land and labor cost arbitrage for foundry greenfield deployment while maintaining ABNT NBR certification alignment. Lead with predictive maintenance platform partnerships rather than commodity bracket price competition. For Investors and Strategic Acquirers: INMETRO fatigue-testing laboratory accreditation delays exceeding nine months are the leading indicator that certified dimensional inspection capability scarcity will drive acquisition premiums for mid-cap foundries with captive CMM infrastructure. Long-term viability centers on suppliers bridging OEM direct supply and aftermarket diagnostics convergence. Watch for Mercosur-EU trade agreement implementation triggering duty restructuring on European alloy feedstock as the signal for portfolio reallocation toward domestic smelter relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Spectroscopy Laboratory Integration | Accelerates ANVISA batch-level traceability certification turnaround for fluid-contact engine components. |
| Multi-Axis Hot Chamber Automation Deployment | Unifies trimming and machining operations for Volkswagen Taubaté transmission housing tolerance compliance. |
| Minas Gerais Geographic Expansion | Captures land and labor cost arbitrage while serving Belo Horizonte's emerging automotive satellite corridor. |
| Predictive Maintenance Platform Partnership | Creates recurring revenue streams through sensor-embedded transmission housings with telemetry-enabled diagnostics. |
| Specialty Alloy Formulation R&D Investment | Commands premium positioning via zinc-aluminum-magnesium-copper thermal conductivity specifications. |
Study Parameters
Multi-period observation of INMETRO certification timeline compression, ANVISA material traceability mandate implementation, and OEM localization procurement shifts anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, foundry operations managers, aftermarket distributors, and ABNT NBR certification auditors. Secondary validation drew from ANVISA regulatory filings, INMETRO dimensional certification databases, Mercosur technical regulation harmonization records, and Brazilian customs alloy import statistics. Bottom-up foundry capacity utilization estimates triangulated against top-down OEM production schedules.
Input-output matrix modeling connected zinc alloy feedstock pricing volatility to foundry margin structures across the projection horizon, with segmentation dimensions spanning product type (engine components, transmission parts, chassis brackets, body hardware), form (die-cast, machined, plated, coated), application (OEM direct, aftermarket, commercial vehicles, passenger vehicles), and material grade (specialty alloys, high purity, corrosion resistant, standard). CAGRs derived from production volume trajectories at Fiat, Volkswagen, and GM assembly plants weighted by content-per-vehicle specifications for thermal management modules and gearbox enclosures.
Revisions become necessary when Mercosur-EU trade agreement implementation timelines accelerate, magnesium die casting substitution rates in powertrain brackets exceed baseline assumptions, or INMETRO fatigue-testing protocol updates extend qualification windows beyond current six-to-nine month baselines. Deviation in high-purity zinc ingot import dependency ratios would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
HCV Brake Components Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Wheel Arch Liner Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Automotive Lubricants Market
Automotive Parts
Suspension Spring Market
Automotive Parts
Timing Gear Market
Automotive Parts
Global Automotive Leaf Spring Market