
 Canada Automotive Parts Zinc Die Casting Market | 2026-2036
Canada Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Parts Zinc Die Casting Market Outlook
Aluminum is shifting from engine blocks and structural brackets into territory once held by zinc die castings, forcing Canadian suppliers to defend zinc's cost advantage in complex thin-wall geometries. Dynacast leverages its multi-slide technology leadership to retain high-volume interior-component contracts. Brillcast Manufacturing LLC anchors its position through captive tooling design and proximity to Great Lakes automotive corridors. Sandhar Technologies Ltd competes on integrated finishing and machining capabilities that reduce downstream assembly steps for OEM customers.
Canada automotive parts zinc die casting involves injecting zinc alloys at pressures exceeding 10 MPa into hardened steel molds to produce net-shape components with dimensional tolerances near 0.05 mm, serving primarily as corrosion-resistant, castable alternatives to machined steel or stamped aluminum in vehicle interiors, closures, and underhood assemblies. Engine Components and Transmission Parts dominate current volume as legacy internal-combustion platforms sustain replacement-part demand, while Electric Vehicles represents the fastest-growing application segment as zinc's electromagnetic shielding properties gain relevance in battery-housing and power-electronics enclosures. OEMs capture the deepest margin pools through long-term platform contracts, whereas Aftermarket Providers face pricing pressure from offshore competitors.
Health Canada and Transport Canada shape product standards through crashworthiness and materials-safety mandates that govern fastener integrity and interior emissions, while Environment and Climate Change Canada enforces foundry air-quality rules that elevate capital costs for molten-metal operations. The Canadian Environmental Protection Act restricts certain heavy-metal additives in zinc alloys, pushing suppliers toward certified virgin and recycled feedstock streams. Stakeholders must monitor how federal zero-emission vehicle mandates reshape component demand across powertrain architectures.
Market Dynamics
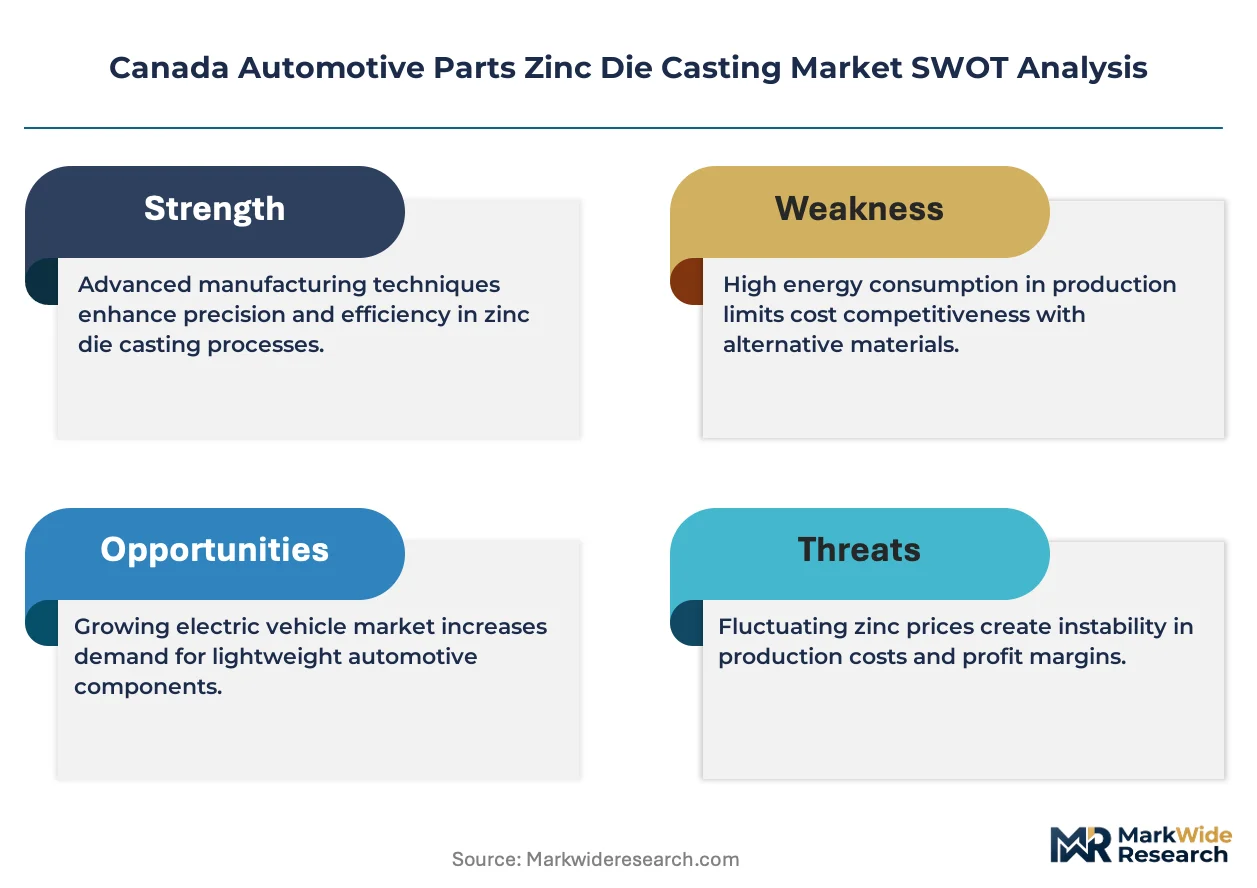
Aluminum's encroachment into zinc's traditional automotive strongholds is forcing Canadian foundries to defend their cost position in complex thin-wall geometries while Health Canada's tightening emissions standards demand cleaner molten-metal processing investments.
Growth Catalysts
- OEM lightweighting mandates:Automakers pursuing fuel-efficiency targets specify zinc alloys for interior hardware and closure mechanisms where corrosion resistance outweighs aluminum's density advantage.
- Transport Canada crashworthiness standards:Updated fastener-integrity and structural-safety requirements sustain demand for zinc's dimensional stability in critical safety components.
- Southern Ontario supplier clustering:Tier-1 foundries concentrated in the Windsor-Toronto corridor capture just-in-time contracts from Detroit-facing assembly plants.
Market Restraints
- Aluminum substitution pressure:Magnesium-aluminum alloys penetrate transmission housing applications where zinc historically dominated due to castability.
- Environment and Climate Change Canada air-quality enforcement:Foundry emission controls elevate capital expenditure requirements for molten-metal operations.
- Feedstock certification costs:The Canadian Environmental Protection Act's heavy-metal restrictions force suppliers toward audited virgin and recycled zinc streams.
Strategic Opportunities
- Electric vehicle battery enclosures:Zinc's electromagnetic shielding properties open design-in opportunities for power-electronics housings as zero-emission vehicle mandates expand.
- Quebec and British Columbia sub-regions:Underpenetrated western Canadian manufacturing bases offer geographic diversification beyond Ontario's saturated corridor.
- Integrated finishing-to-assembly contracts:Downstream machining and surface-treatment capabilities reduce OEM supplier counts and capture margin pools.
Industry Challenges
- Tooling engineer scarcity:Captive die-design expertise concentrates among legacy operators, constraining new entrants' speed-to-production.
- Multi-slide equipment lead times:High-pressure casting machinery procurement cycles extend 12-18 months, compressing foundry expansion windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Parts Zinc Die Casting Market |
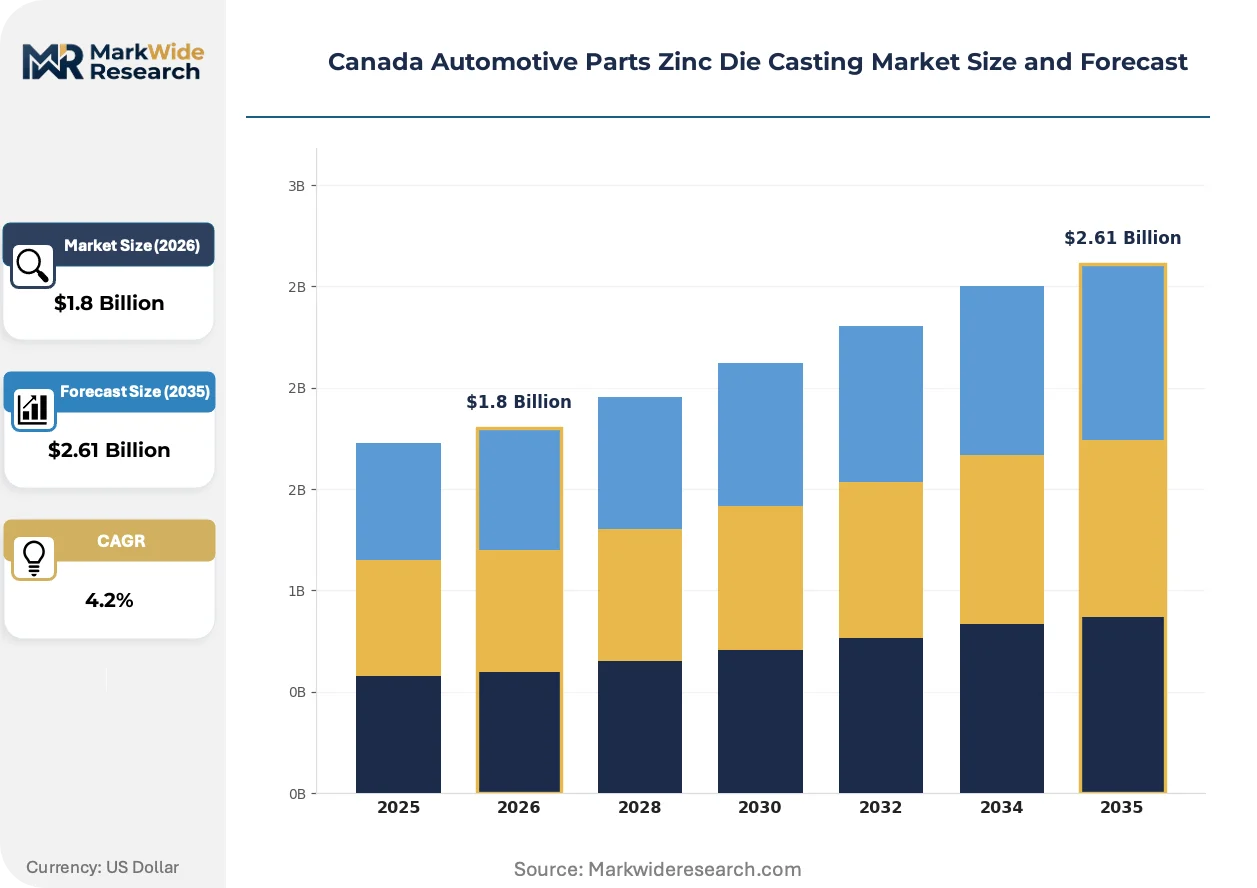
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Chassis Parts, Body Parts Material Grade: Zinc Alloy, Aluminum Alloy, Copper Alloy, Magnesium Alloy Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Sandhar Technologies Ltd, Brillcast Manufacturing LLC, Empire Casting Co, Dynacast, Pace Industries, Cascade Die Casting Group Inc, Ashok Minda Group, Ridco Zinc Die Casting Company, Northwest Die Casting Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Parts Zinc Die Casting Market Strategic Shifts
Canadian zinc die casting is pivoting toward higher-value electromagnetic applications while regulatory pressure and buyer consolidation reshape competitive requirements.
Multi-slide zinc injection technology is consolidating high-volume interior-component production around automated cell configurations that reduce cycle times and labor content. OEMs adopting platform-standardized hardware families specify these systems for door-lock mechanisms and seat-adjustment housings. The technology is consolidating supplier tiers by rewarding capital-intensive operators with dedicated tooling libraries.
Health Canada's evolving vehicle emissions standards now govern interior air quality and volatile compound release from metal-finishing processes. Foundries face accelerated compliance timelines for molten-metal fume capture and alloy-additive disclosure. Southern Ontario operators bear the heaviest retrofit burden given their concentration near densely populated corridors.
Fleet procurement teams now bundle zinc hardware into multi-year platform contracts that span design, tooling amortization, and volume guarantees. Traditional spot-buying through tier-2 distributors contracts as OEMs reduce supplier bases. This concentration is most pronounced among Detroit Three operations sourcing through Windsor-area manufacturing clusters.
Canada Automotive Parts Zinc Die Casting Market Segmentation
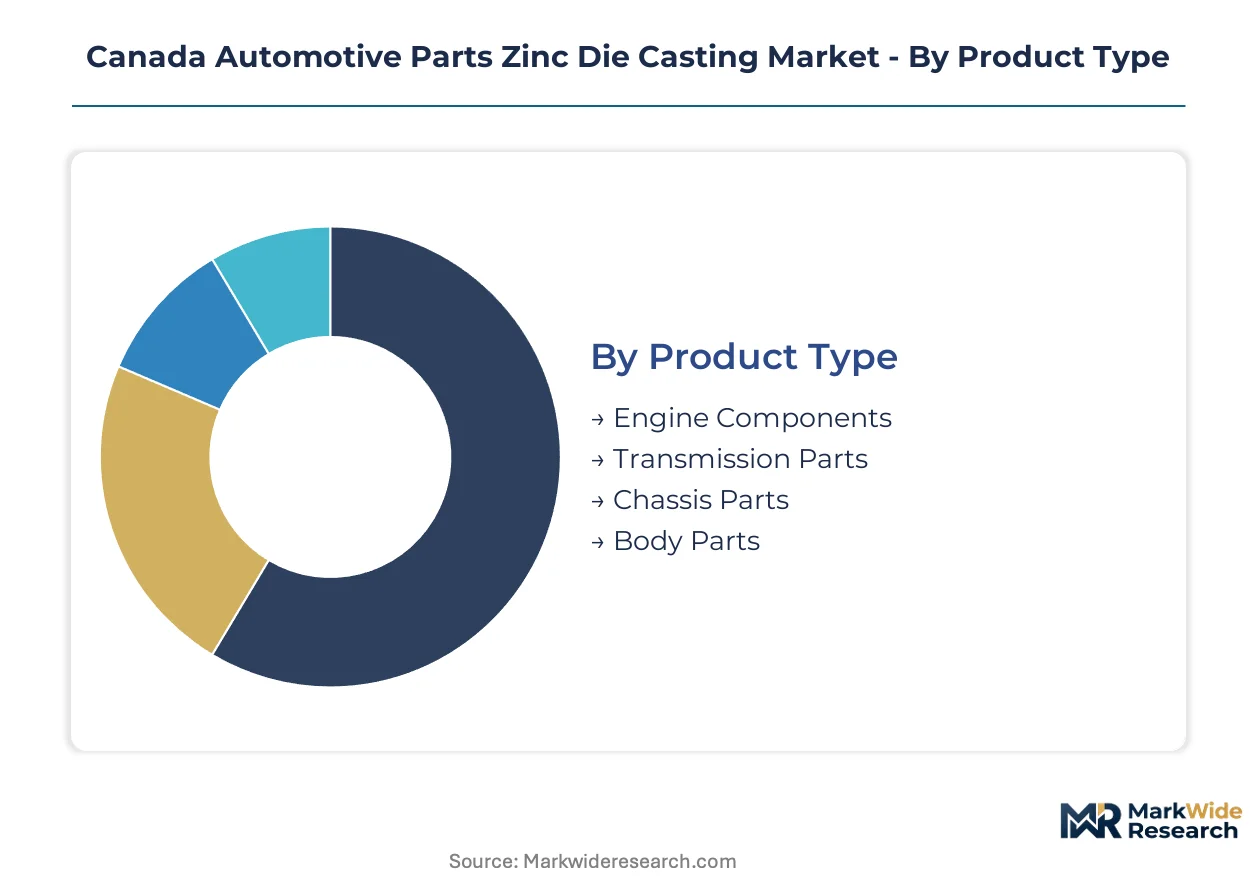
Zinc die casting procurement in Canada fragments across material specifications, vehicle platforms, and supply chain tiers. Understanding these divides reveals where foundries capture premium pricing versus commodity volume plays.
Product Type:
Standalone chassis hardware commands distinct tooling investments compared to engine-embedded castings that must integrate with thermal management systems.
- Engine Components:These castings include valve covers, timing chain housings, and oil pump bodies requiring heat resistance above 150°C. Windsor-area foundries supply Detroit Three assembly plants with legacy internal-combustion platforms sustaining replacement-part demand.
- Transmission Parts:Gear selector forks, clutch housings, and transmission cases demand dimensional tolerances near 0.05 mm for smooth power transfer. Health Canada's evolving vehicle emissions standards pressure suppliers to adopt cleaner molten-metal processing for these high-volume components.
- Chassis Parts:Steering knuckles and suspension brackets absorb road-load stresses.
- Body Parts:Door handles, mirror housings, and fuel filler caps prioritize surface finish quality.
Engine Components lead volumes today; Electric Vehicles powertrain hardware is gaining share fastest.
Material Grade:
Cost tiers separate certified virgin feedstock from recycled streams, with alloy chemistry dictating corrosion performance in road-salt environments.
- Zinc Alloy:Zamak 3 and Zamak 5 formulations dominate automotive interiors with 95% recyclability and electromagnetic shielding properties. Southern Ontario suppliers leverage proximity to Great Lakes automotive corridors for just-in-time delivery of certified virgin and recycled feedstock streams.
- Aluminum Alloy:A380 and ADC12 grades penetrate transmission housings where density reduction outweighs zinc's castability advantage.
- Copper Alloy:Electrical busbars and grounding terminals exploit conductivity.
- Magnesium Alloy:AZ91D serves steering wheel cores and seat frames seeking maximum mass reduction.
Zinc Alloy retains the deepest OEM contract penetration; Magnesium Alloy climbs the fastest as lightweighting mandates intensify.
Application:
Volume concentration varies sharply between fleet procurement cycles and retail replacement demand across powertrain architectures.
- Passenger Vehicles:Sedans, SUVs, and light trucks generate the bulk of interior hardware demand for door-lock mechanisms and seat-adjustment housings. The Windsor-Toronto manufacturing corridor clusters tier-1 suppliers near Detroit-facing assembly plants serving this segment.
- Commercial Vehicles:Heavy-duty trucks require reinforced chassis castings with thicker wall sections.
- Two-Wheelers:Motorcycle engine covers and foot peg brackets represent a niche import-competitive segment.
- Electric Vehicles:Battery enclosures and power-electronics housings exploit zinc's electromagnetic shielding properties as zero-emission vehicle mandates expand.
Passenger Vehicles anchor current procurement volumes; Electric Vehicles shows the steepest expansion trajectory.
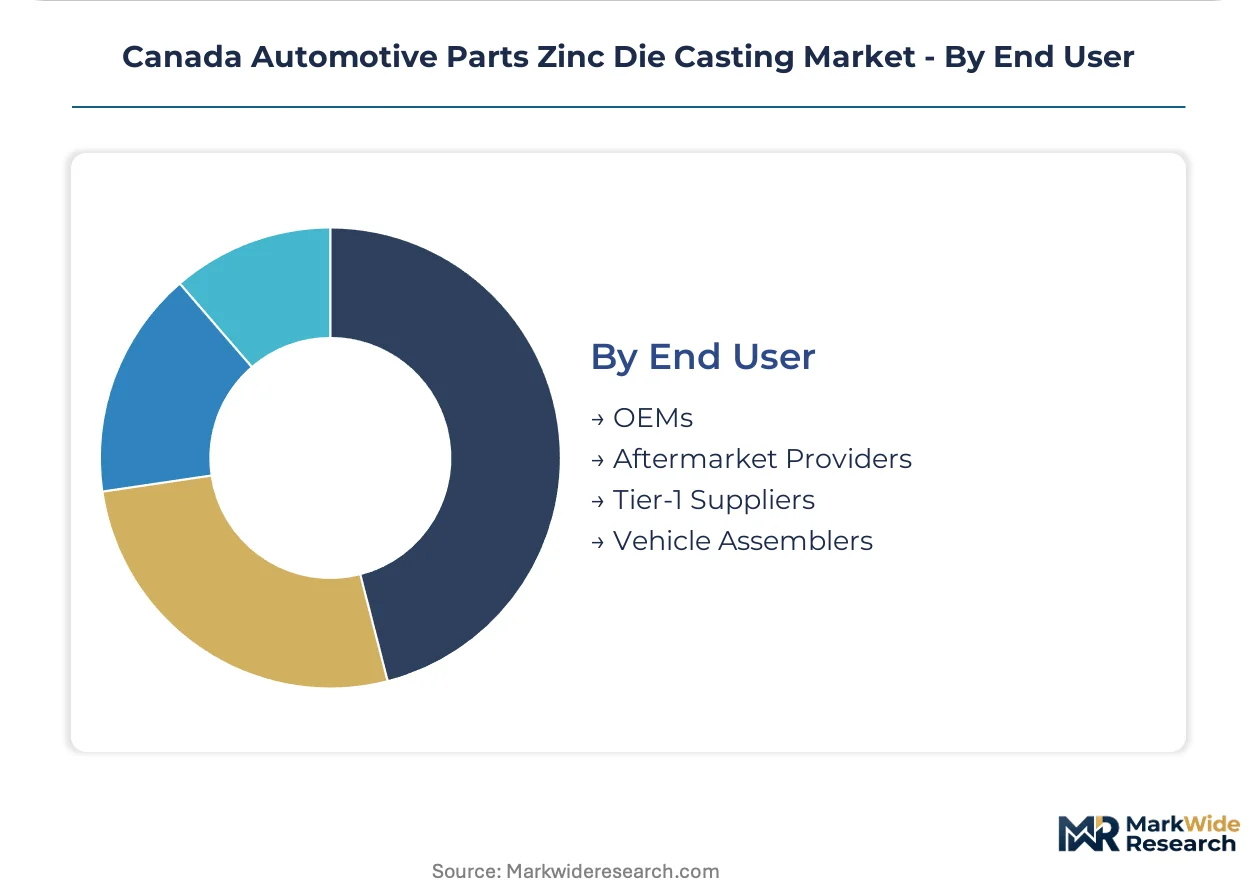
End User:
Margin capture diverges between long-term platform contractors and spot-market distributors facing offshore pricing pressure.
- OEMs:Ford, Stellantis, and General Motors issue multi-year platform contracts spanning design, tooling amortization, and volume guarantees. These agreements concentrate among Windsor-area manufacturing clusters with dedicated tooling libraries.
- Aftermarket Providers:Independent distributors and repair chains source replacement hardware through tier-2 channels.
- Tier-1 Suppliers:Magna, Linamar, and Martinrea bundle zinc castings into larger module assemblies.
- Vehicle Assemblers:Contract manufacturers and specialty builders procure small-batch custom components.
OEMs dominate value capture today; Tier-1 Suppliers are consolidating share fastest through integrated finishing-to-assembly contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Windsor-Toronto manufacturing corridor anchors Canadian zinc die casting capacity, clustering tier-1 suppliers within just-in-time reach of Detroit-facing assembly plants. Health Canada and Transport Canada regulations governing vehicle emissions and crashworthiness shape foundry investment patterns across provincial manufacturing bases. Sub-regional specialization reflects proximity to OEM assembly networks, feedstock logistics, and provincial environmental enforcement intensity.
Ontario
Windsor and Toronto-area foundries supply transmission housings and door-lock mechanisms to Stellantis, Ford, and General Motors assembly lines. Environment and Climate Change Canada enforces stringent air-quality standards on molten-metal operations concentrated near densely populated corridors. The Windsor-Essex region hosts the densest clustering of multi-slide zinc casting capacity serving North American automotive platforms.
Quebec
Montreal and Quebec City manufacturing zones process Zamak alloys for interior hardware and closure mechanisms on light-truck platforms. The Canadian Environmental Protection Act restricts heavy-metal additives in zinc alloys, pushing Quebec foundries toward certified virgin and recycled feedstock streams. Eastern Townships suppliers are expanding finishing-to-assembly capabilities to reduce OEM supplier counts.
Alberta
Calgary and Edmonton metalworking facilities serve western Canadian commercial vehicle builders with chassis castings requiring thicker wall sections. Provincial environmental regulators monitor foundry emissions under delegated federal authority. The Calgary-Edmonton corridor remains underpenetrated relative to Ontario, offering geographic diversification for suppliers seeking lower regulatory density.
British Columbia
Vancouver-area fabricators specialize in small-batch custom components for specialty vehicle assemblers and electric vehicle startups. Transport Canada mandates on fastener integrity and structural safety apply to components manufactured for cross-provincial shipment. The Lower Mainland's port access supports import-competitive sourcing of raw zinc alloys from Asian smelters.
Atlantic Canada
Halifax and Moncton industrial zones maintain niche capacity for marine and defense-adjacent casting applications with automotive crossover potential. Federal zero-emission vehicle mandates reshape component demand across Maritime manufacturing bases. Atlantic suppliers leverage lower land and labor costs to compete on spot-market replacement hardware.
Canada Automotive Parts Zinc Die Casting Market Competitive Environment
Global majors compete with regional champions across tooling libraries and captive finishing capabilities in the Canadian zinc die casting sector. The vendor base concentrates among three tiers: multi-slide technology leaders with dedicated OEM platform contracts, mid-scale operators emphasizing proximity logistics, and specialty houses serving aftermarket distributors. Two strategic archetypes dominate competitive positioning: capital-intensive automated cell operators defending high-volume interior-component contracts, and integrated finishing-to-assembly providers capturing margin pools through downstream machining. Consolidation pressures intensify as OEM procurement teams reduce supplier bases and bundle multi-year platform agreements.
Among North American zinc die casting specialists, Dynacast and Pace Industries exemplify the capital-intensive automated tier with multi-slide technology leadership, while Brillcast Manufacturing LLC represents the integrated finishing archetype through captive tooling design capabilities. Sandhar Technologies Ltd anchors the integrated machining-and-assembly positioning with capabilities that reduce downstream steps for OEM customers. These three companies occupy distinct competitive vectors within a market where tooling engineer scarcity and 12-18 month equipment lead times constrain new entrant expansion.
| Leading Market Players |
|---|
| Sandhar Technologies Ltd |
| Brillcast Manufacturing LLC |
| Empire Casting Co |
| Dynacast |
| Pace Industries |
| Cascade Die Casting Group Inc |
| Ashok Minda Group |
| Ridco Zinc Die Casting Company |
| Northwest Die Casting Company |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up foundry specialists in Southern Ontario anchor pricing discipline through captive tooling libraries and long-term platform amortization contracts with Detroit Three OEMs. Their concentrated ownership structure limits spot-market discounting while reinforcing just-in-time delivery premiums across the Windsor-Toronto corridor.
Pricing Analysis
Input-cost pass-through from certified virgin zinc feedstock and multi-slide equipment procurement cycles governs contract pricing structures. Three-tier pricing structure across premium, standard, and economy levels separates Zamak 5 certified-grade castings from recycled-stream commodity volumes and uncertified aftermarket hardware. Cost compression in standard-tier transmission housings is intensifying because aluminum-magnesium alloys penetrate legacy zinc applications. Aftermarket distributors exhibit the highest price sensitivity due to offshore import competition, whereas OEM platform contractors prioritize dimensional stability over unit cost.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Windsor-area regional hubs serving Detroit-facing assembly plants within four-hour delivery windows. Supply draws from primary zinc smelting in Quebec and Manitoba, secondary recycling streams in Ontario, and specialized alloy additives from US Great Lakes processors. Single-source vulnerability concentrates in captive die-design engineering talent clustered among legacy Windsor-Essex operators. Distribution runs through tier-1 supplier consolidation centers bundling zinc castings into larger module assemblies for Stellantis, Ford, and General Motors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Health Canada's zero-emission vehicle mandates and molten-metal emissions standards continuously reshape component demand and compliance investment requirements.
For Market Incumbents: Cement platform-contract renewal rates by expanding electromagnetic shielding design capabilities for electric vehicle battery enclosures before aluminum suppliers develop competing solutions. Deepen backward integration into certified virgin feedstock streams to insulate margin pools from Environment and Climate Change Canada audit requirements. Prioritize captive tooling engineer retention through equity participation structures. For New Entrants and Emerging Players: Specialty vehicle assemblers in British Columbia and Alberta represent the most penetrable buyer archetype, underserved by Ontario-centric tier-1 networks. Western Canadian commercial vehicle builders seeking chassis castings with thicker wall sections offer geographic white-space. Quebec foundries expanding finishing-to-assembly capabilities demonstrate a viable go-to-market angle for reducing OEM supplier counts. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale operators with underutilized multi-slide capacity and unexploited Health Canada emissions compliance infrastructure. Long-term viability hinges on electric vehicle powertrain penetration rates and zinc's design-in success against aluminum in electromagnetic applications. Monitor Transport Canada fastener-integrity standard updates as the critical inflection signal for structural-component demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Slide Capacity Expansion | Dynacast and Pace Industries consolidate high-volume interior-component production through automated cell configurations. |
| Backward Integration into Feedstock Certification | Brillcast Manufacturing LLC and Sandhar Technologies Ltd secure audited virgin and recycled zinc streams under Canadian Environmental Protection Act requirements. |
| Integrated Finishing-to-Assembly Contracts | Eastern Townships and Quebec City suppliers reduce OEM supplier counts by bundling machining and surface-treatment capabilities. |
| Electromagnetic Shielding Design Partnerships | Vancouver-area fabricators exploit zinc's properties for battery-housing and power-electronics enclosures in zero-emission vehicle platforms. |
| Geographic Manufacturing Footprint Diversification | Calgary-Edmonton corridor expansion offers lower regulatory density and access to western Canadian commercial vehicle builders. |
Study Parameters
Multiple input streams — primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, and Environment and Climate Change Canada enforcement records; and customs/trade flow analysis — were reconciled through bottom-up and top-down triangulation. Foundry operations managers and Health Canada regulatory affairs specialists provided ground-truth on molten-metal processing compliance timelines.
Historical volume trajectories were cross-referenced against panel input from automotive procurement executives to model demand across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segment-level build-up analysis incorporating platform lifecycle timing and powertrain transition assumptions. Forecast inputs included OEM lightweighting mandate intensity and Transport Canada crashworthiness standard evolution.
Underlying measurement precision varies by segment; OEM platform contracts and Windsor-Toronto corridor production volumes carry tighter precision than aftermarket spot-market transactions and Atlantic Canada niche capacity. Forecasts reflect documented assumptions regarding zero-emission vehicle mandate implementation pace and aluminum substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Thermostat Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
North America Gear Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
United States Ceramic Ball Bearings Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake Wheel Cylinder Market