
 Electric Vehicle Fasteners Market | 2026-2036
Electric Vehicle Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Fasteners Market Insights
Software-defined battery management is repositioning how fasteners are specified, with torque-recalibration subscriptions now bundled into platform contracts. PennEngineering leverages its North American manufacturing footprint to dominate EV battery tray assemblies. KAMAX Holding GmbH & Co. KG anchors European supply through its cold-forming specialization for high-strength chassis bolts. Stanley Black & Decker extends its DeWalt industrial channel to control aftermarket fastening tool ecosystems serving EV repair networks.
Electric vehicle fasteners are mechanical joining elements, typically engineered from aluminum, steel, or titanium alloys, that secure structural and functional assemblies in electrified powertrains and body structures. These components must withstand galvanic corrosion, thermal cycling, and vibration loads while maintaining clamp load integrity across battery enclosures and chassis nodes. Bolts and screws for battery systems command premium positioning due to isolation-grade material requirements and thread-locking specifications. Aluminum fasteners are accelerating fastest as OEMs pursue mass reduction targets, though titanium variants occupy niche applications where strength-to-weight ratios justify cost premiums.
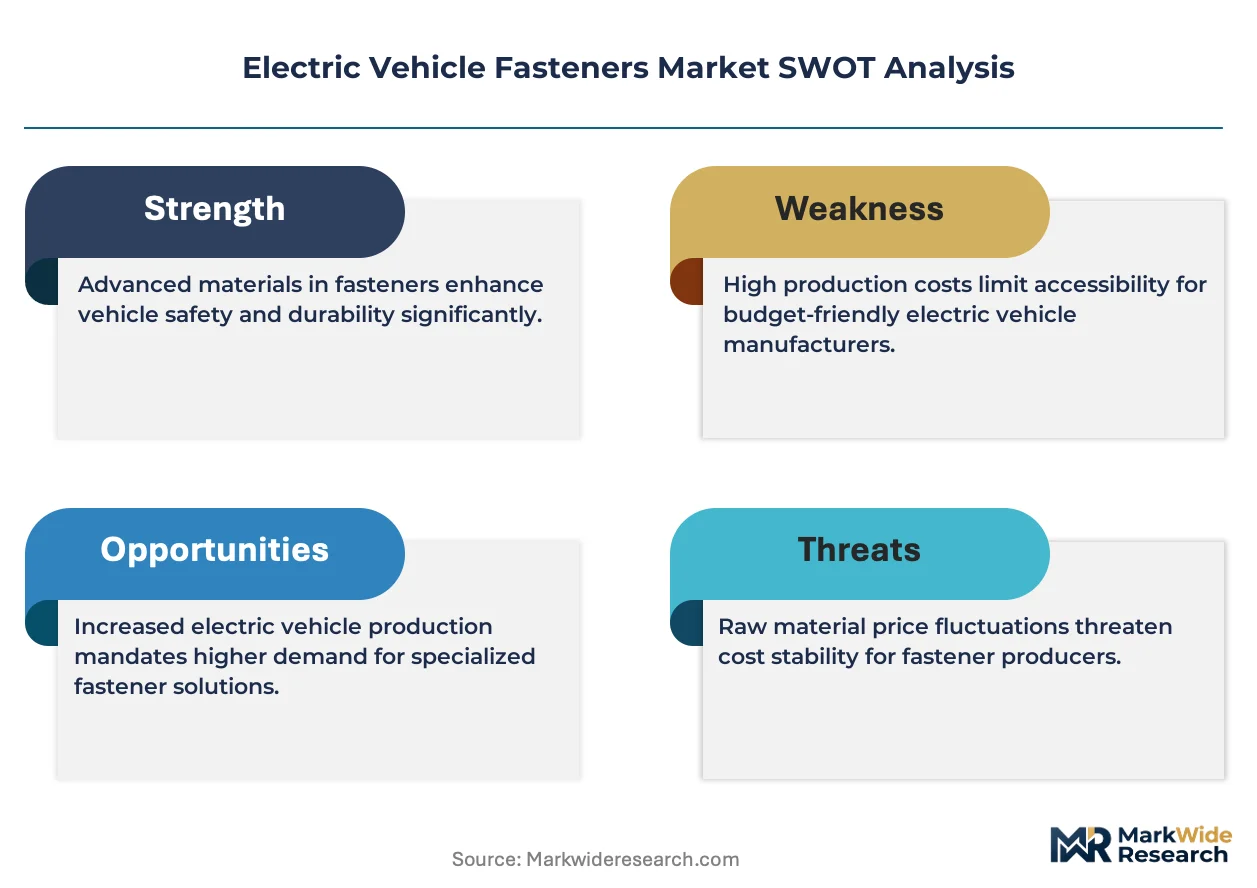
EPA tailpipe regulations and NHTSA crashworthiness standards in the United States, alongside China's GB/T standards for EV safety and ECHA REACH restrictions on hexavalent chromium plating in Europe, collectively tighten material and performance specifications for fasteners. These frameworks force suppliers to certify corrosion resistance, recyclability, and electromagnetic compatibility across jurisdictions. Stakeholders must monitor how solid-state battery architectures reshape thermal management hardware and whether new cell-to-pack designs eliminate legacy fastening points entirely.
Market Dynamics
Cell-to-pack battery architectures are eliminating traditional module-level fastening points, forcing fastener suppliers to redesign for direct cell-to-chassis attachment while maintaining thermal isolation integrity across larger structural spans.
Growth Catalysts
- China's GB/T 31467.3:Mandatory battery abuse testing protocols mandate upgraded fastener shear strength for thermal runaway containment, driving specification upgrades across export-bound supply chains.
- Aluminum cold-forming:Advanced extrusion and thread-rolling processes enable mass production of lightweight, high-torque fasteners that satisfy OEM mass reduction targets without sacrificing clamp load retention.
- German OEM hub concentration:Volkswagen, BMW, and Mercedes-Benz manufacturing clusters in Lower Saxony and Bavaria generate concentrated demand for certified structural fasteners with documented batch traceability.
Market Restraints
- Titanium alloy cost volatility:Sponge titanium pricing fluctuations and limited mill capacity constrain supply of aerospace-grade fasteners for premium EV chassis applications.
- Single-source forging dependencies:High-strength chassis bolt production concentrates in specialized European cold-forming facilities, creating geographic supply vulnerability.
- Hexavalent chromium plating bans:ECHA REACH restrictions on corrosion-resistant coatings force costly conversion to trivalent alternatives with unproven field longevity.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Domestic cell manufacturing incentives will spawn parallel fastener localization demand as Tata and Reliance scale gigafactory operations.
- Solid-state thermal management hardware:Next-generation cell architectures require novel fastening geometries for ceramic separator compression and pressure-sensitive current collectors.
- Torque-recalibration subscriptions:Software-defined battery platforms create recurring revenue streams through predictive fastener integrity monitoring bundled into OEM service contracts.
Industry Challenges
- Multi-physics simulation talent scarcity:Fastener design now requires coupled thermal-mechanical-electromagnetic modeling expertise that crosses traditional mechanical engineering boundaries.
- Cross-jurisdiction certification timelines:Simultaneous NHTSA, ECE R100, and GB/T homologation processes extend product validation cycles by months.
- Legacy thread standard incompatibility:Metric fine-pitch battery tray specifications conflict with existing imperial tool inventories at North American assembly plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Fasteners Market |
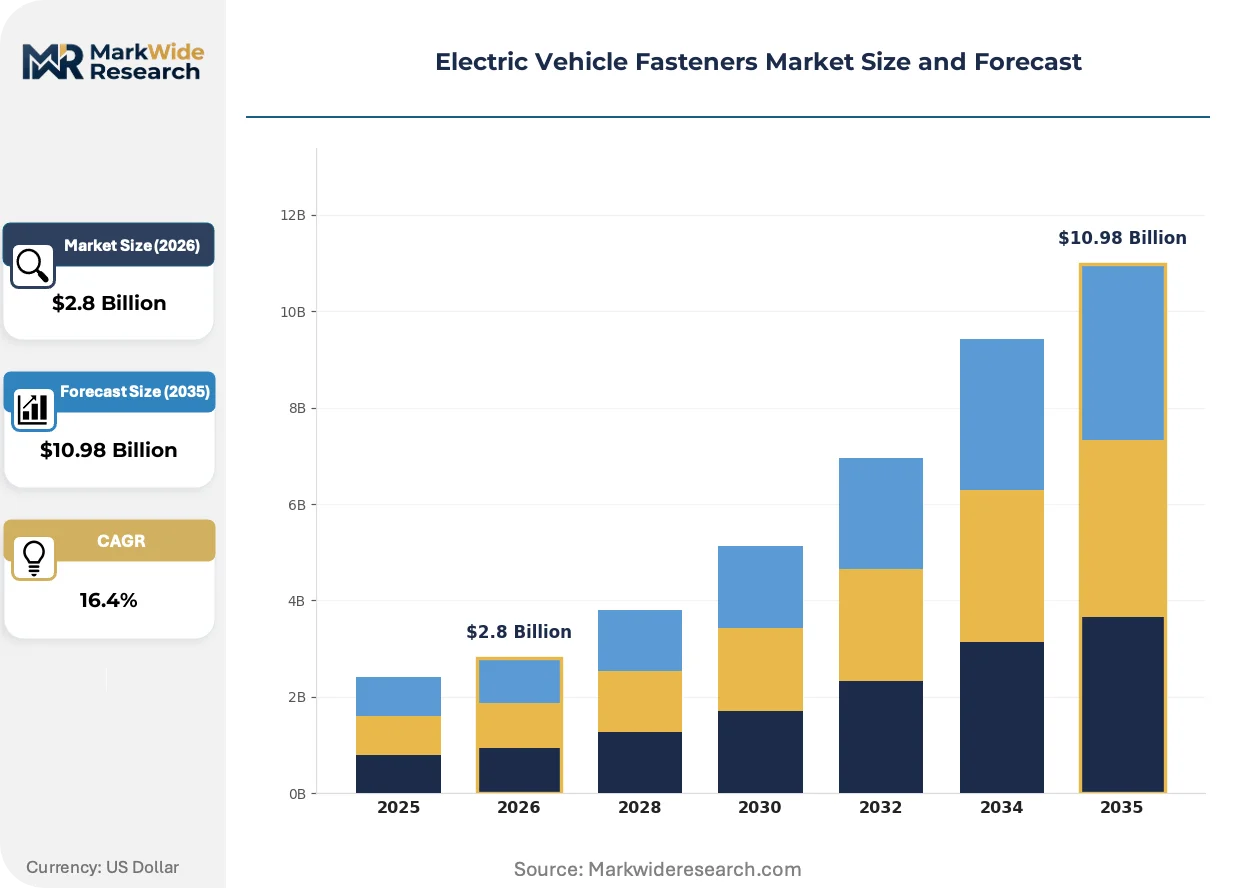
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Washers, Screws Material: Aluminum, Steel, Titanium, Plastic Application: Body Assembly, Battery Systems, Chassis, Interior Components Connection Type: Permanent, Removable, Self-Locking, Flanged |
| Companies Covered | PennEngineering, KAMAX Holding GmbH & Co. KG, Stanley Black & Decker, Nifco Inc., LISI Group, Illinois Tool Works, ARaymond Network, EJOT Holding GmbH & Co. KG, Bulten AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Fasteners Market Trends and Innovations
Digital thread technologies and predictive maintenance integration are transforming fastener specification from a commodity procurement decision into a systems engineering discipline with lifecycle accountability.
Self-piercing rivet systems with integrated fiber-optic strain sensing are rewriting how battery enclosure joints are monitored. BMW and Porsche assembly lines now specify these smart fasteners for structural nodes requiring real-time clamp load verification. The technology is compressing warranty exposure for OEMs while elevating fastener suppliers into data-service partnerships.
EPA tailpipe regulations and NHTSA crashworthiness standards are tightening material traceability requirements for structural fasteners in US-manufactured EVs. Suppliers must now document recycled content percentages and carbon intensity across smelting, forging, and finishing operations. Battery tray assemblies face the most stringent documentation burdens as they occupy critical load paths in side-impact scenarios.
Fleet operators and leasing companies are unbundling fastener replacement from traditional powertrain service contracts. Hertz and Enterprise procurement teams now negotiate directly with fastener distributors for standardized torque-tool ecosystems that reduce technician training costs. This channel disintermediation is most visible in California and Texas where commercial EV deployment concentrates.
Electric Vehicle Fasteners Market Segmentation
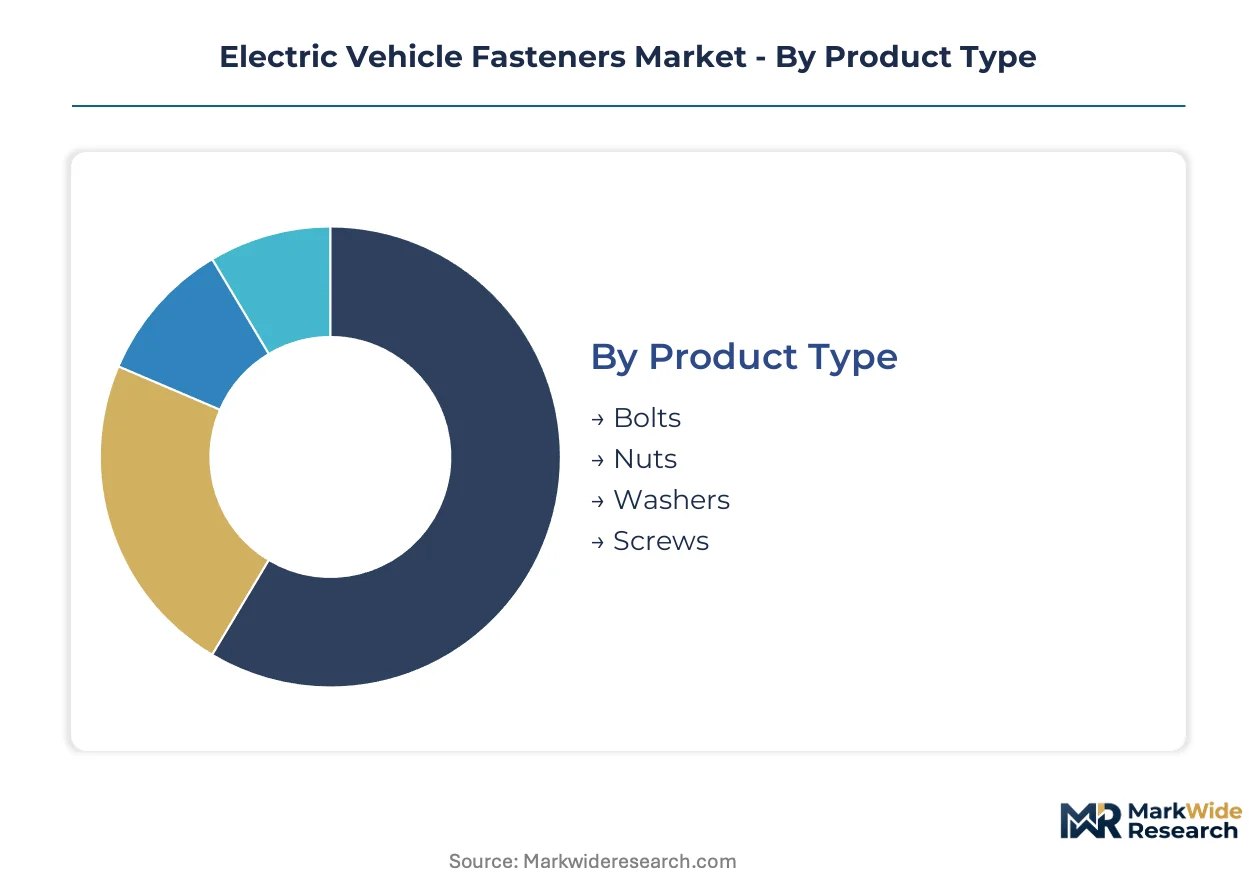
Fastener specification in electric vehicles diverges sharply across powertrain architectures, with battery system assemblies demanding isolation-grade materials while chassis applications prioritize crash-load integrity. Segmentation reveals how OEM procurement teams balance standardization economies against architecture-specific performance requirements.
Product Type:
Customization intensity varies from commodity hardware to application-engineered geometries, with battery tray assemblies driving the most specialized fastener development.
- Bolts:High-tensile steel and aluminum alloy variants dominate battery enclosure anchoring, with thread-locking compounds specified for thermal cycling resistance. Demand concentrates in German OEM battery plants where GB/T 31467.3 shear strength mandates require upgraded metallurgy. Vibration damping specifications from NHTSA crashworthiness protocols further tighten dimensional tolerances.
- Screws:Fine-pitch machine screws secure power electronics housings and junction boxes, with aluminum variants accelerating as OEMs pursue mass reduction targets. China's expanding BYD and CATL battery production lines generate concentrated procurement volume for corrosion-resistant drive geometries.
- Nuts:Prevailing torque nuts and weld nuts serve structural joints across unibody assemblies, with flange designs preferred for chassis load distribution.
- Washers:Conical and Belleville washers maintain clamp load across thermal expansion mismatches between aluminum battery trays and steel subframes.
Leading the category by volume: Bolts. Growing fastest: Aluminum screws for mass-sensitive electronics mounting.
Material:
Cost-positioning separates commodity steel from performance alloys, with titanium occupying narrow aerospace-heritage niches and engineered plastics emerging for isolation applications.
- Aluminum:Cold-formed 6xxx and 7xxx series alloys deliver strength-to-weight ratios critical for battery tray assemblies and suspension nodes. Lower Saxony Volkswagen operations specify batch-traceable aluminum fasteners with documented carbon intensity for EU Green Deal compliance. ECHA REACH restrictions on surface treatments force conversion to trivalent coating systems.
- Steel:Boron and medium-carbon steels retain cost advantage for high-volume chassis applications where mass penalties are acceptable. North American Ford and GM truck-based EV platforms specify Grade 10.9 and 12.9 bolts for frame rail connections.
- Titanium:Ti-6Al-4V fasteners serve premium chassis nodes and motor mounting brackets where strength-to-weight justifies cost premiums.
- Plastic:PEEK and nylon 66 variants isolate high-voltage busbars and sensor housings, eliminating galvanic corrosion risks in battery enclosures.
Steel commands absolute volume. Aluminum gains share fastest on mass reduction imperatives.
Application:
Engineering complexity escalates from interior trim to crash-critical structural nodes, with battery systems demanding the most multi-physics design integration.
- Battery Systems:Enclosure fasteners must simultaneously manage thermal expansion, electromagnetic shielding, and thermal runaway containment. Cell-to-pack architectures are eliminating module-level attachment points, forcing redesign for direct cell-to-chassis spans. BMW and Porsche assembly lines specify fiber-optic strain-sensing fasteners for real-time clamp load verification.
- Chassis:Subframe and suspension fasteners absorb road-load fatigue while maintaining alignment precision for battery protection. German KBA homologation requirements mandate documented batch traceability for structural bolts.
- Body Assembly:Closure panel and structural adhesive hybrid joints use self-piercing rivets and flow-drill screws to eliminate welding heat-affected zones.
- Interior Components:Standardized trim fasteners face least stringent performance requirements, with commodity procurement dominating seat and dashboard assemblies.
Battery system fasteners lead on revenue per unit. Body assembly hardware dominates absolute piece volume.
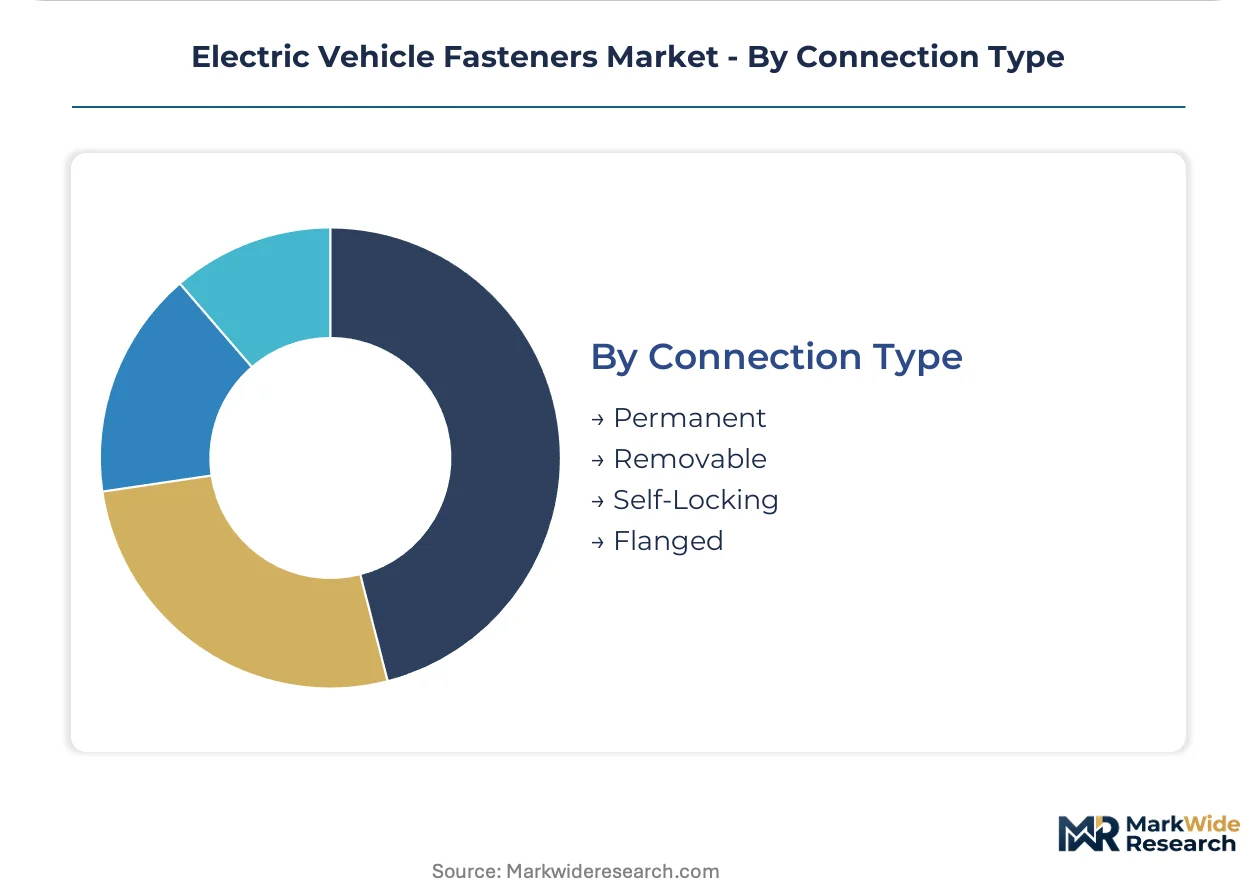
Connection Type:
Serviceability requirements differentiate removable designs for warranty-accessible components against permanent joints for sealed battery enclosures.
- Removable:Threaded fasteners with prevailing torque features enable field service of power electronics and thermal management modules. Fleet operators in California and Texas specify standardized torque-tool ecosystems to reduce technician training costs.
- Permanent:Self-piercing rivets and flow-drill screws create tamper-evident joints for battery enclosures where post-assembly access violates safety certifications.
- Self-Locking:Nylon-insert and deformed-thread designs prevent loosening under vibration without secondary locking elements.
- Flanged:Integrated washer heads distribute clamp load across thin-walled aluminum castings in battery tray and motor housing applications.
Removable designs dominate service-intensive applications. Permanent joints expand fastest with cell-to-pack sealing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in manufacturing clusters where OEM battery assembly scales fastest, while consumption patterns diverge between mature EV markets and emerging localization programs. Fastener specifications tighten fastest where regulatory pressure intersects with high-volume domestic vehicle output.
China
CATL and BYD battery production lines in Fujian and Shenzhen drive concentrated procurement of corrosion-resistant aluminum fasteners. GB/T 31467.3 abuse testing mandates force specification upgrades across export supply chains. The Yangtze River Delta hosts the densest concentration of cold-forming facilities serving both domestic OEMs and European-bound component exports.
Germany
Volkswagen, BMW, and Mercedes-Benz manufacturing hubs in Lower Saxony and Bavaria generate premium demand for batch-traceable structural fasteners. KBA homologation requirements mandate documented shear strength certification for chassis applications. Stuttgart-area suppliers specialize in high-torque titanium variants for motor mounting brackets in performance EV architectures.
United States
Ford and GM truck-based EV platforms in Michigan specify Grade 10.9 and 12.9 steel bolts for frame rail connections. NHTSA crashworthiness standards tighten dimensional tolerances for battery tray assemblies. The Detroit-Toledo corridor anchors North American fastener distribution networks serving both OEM assembly plants and aftermarket repair ecosystems.
India
Tata Motors and Reliance gigafactory construction under the PLI scheme for ACC batteries spawns parallel fastener localization demand. BIS certification requirements for automotive components force suppliers to establish domestic forging capacity. Tamil Nadu and Gujarat host the fastest-growing clusters of cold-forming investment targeting cell-to-pack assembly lines.
Japan
Toyota and Nissan solid-state battery pilot programs in Aichi and Kanagawa prefectures drive development of novel fastening geometries for ceramic separator compression. METI technology roadmaps prioritize lightweight aluminum thread-locking designs for next-generation thermal management hardware. The Nagoya industrial corridor retains specialized capacity for high-precision titanium fasteners in premium EV motor applications.
Electric Vehicle Fasteners Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where integrated forging operations face pressure from specialized component engineers. The vendor base separates into three archetypes: diversified industrial conglomerates with captive fastener divisions, pure-play cold-forming specialists with metallurgical expertise, and software-enabled service providers bundling torque monitoring into platform contracts. Dominant competitive moves include geographic co-location with OEM battery plants and backward integration into alloy smelting to secure carbon-intensity documentation for EU Green Deal compliance.
Among North American industrial conglomerates, PennEngineering and Illinois Tool Works exemplify scale-driven positions anchored in manufacturing footprint breadth. German GmbH-structured specialists including KAMAX Holding GmbH & Co. KG and EJOT Holding GmbH & Co. KG occupy the cold-forming tier with European regulatory certification depth. Stanley Black & Decker represents the tool-and-service archetype, extending industrial channel control into aftermarket fastening ecosystems. Japanese Co., Ltd. entities including Nifco Inc. and LISI Group anchor Asian supply relationships through precision manufacturing heritage.
| Leading Market Players |
|---|
| PennEngineering |
| KAMAX Holding GmbH & Co. KG |
| Stanley Black & Decker |
| Nifco Inc. |
| LISI Group |
| Illinois Tool Works |
| ARaymond Network |
| EJOT Holding GmbH & Co. KG |
| Bulten AB |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between GB/T 31467.3-compliant structural fasteners and commodity chassis hardware manifests in both pricing stratification and supply chain configuration. Premium battery tray assemblies command documented batch traceability and trivalent coating systems, while standard-grade steel bolts flow through volume-driven contract structures.
Pricing Analysis
Cost-down pressure on aluminum cold-formed fasteners accelerates as OEMs pursue mass reduction targets without sacrificing clamp load retention. Three-tier pricing structure across isolation-grade, structural, and commodity hardware separates battery enclosure specifications from chassis applications, with GB/T and ECHA REACH certification tiers driving the widest spreads. Fleet operators in California and Texas exhibit highest price sensitivity through standardized torque-tool procurement, while German OEMs absorb premiums for KBA-homologated batch traceability.
Supply Chain Analysis
Sponge titanium supply rests on limited mill capacity concentrated in Japan and Russia, constraining aerospace-grade fastener availability for premium EV motor mounting. Cold-forming equipment and boron steel feedstock draw from German and Chinese metallurgical clusters, creating geographic dependency for high-tensile chassis bolt production. Single-source forging vulnerability persists across Lower Saxony specialized facilities. Distribution runs through OEM co-located Tier 1 supplier hubs with direct-to-assembly-plant logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as ECHA REACH coating conversions and GB/T certification upgrades force sub-scale suppliers into exit or acquisition. Regulatory compliance capital requirements favor integrated players with captive metallurgical documentation.
For Market Incumbents: Hedge against cell-to-pack architecture displacement by acquiring fiber-optic strain-sensing fastener capabilities and torque-recalibration software platforms. Backward integration into 6xxx and 7xxx series aluminum smelting secures carbon-intensity documentation for EU Green Deal compliance. Defensive capacity expansion in Tamil Nadu and Gujarat captures Tata and Reliance gigafactory localization demand.
For New Entrants and Emerging Players: Launch via direct fleet operator channels in California and Texas, bypassing OEM procurement gatekeepers with standardized torque-tool ecosystem offerings. India's PLI scheme for ACC batteries presents the most penetrable white space, with BIS certification requirements creating barrier-protected niches for domestic forging investment. Solid-state battery pilot programs in Aichi and Kanagawa prefectures offer entry through novel ceramic separator compression geometries.
For Investors and Strategic Acquirers: Re-rating potential sits with cold-forming specialists possessing European regulatory certification depth given GB/T and ECHA REACH specification tightening. Long-term viability over the next decade hinges on software-defined battery platform integration and predictive maintenance data service bundling. Watch for solid-state thermal management hardware announcements as inflection indicators for next-generation fastening geometry demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Captive 6xxx series supply secures carbon documentation for Volkswagen and BMW EU Green Deal compliance. |
| Software-Defined Torque Monitoring Platform | Predictive fastener integrity subscriptions bundle into BMW and Porsche OEM service contracts. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu and Gujarat facilities capture Tata Motors and Reliance gigafactory localization requirements. |
| Cell-to-Pack Fastener Redesign | Direct cell-to-chassis attachment geometries address thermal isolation across larger structural spans. |
| Certification Investment for GB/T 31467.3 | Upgraded shear strength documentation unlocks CATL and BYD export supply chain access. |
Research Methodology
Multi-period observation of battery production capacity announcements, OEM platform engineering specifications, and fastener procurement contract structures anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, cold-forming plant managers, and aftermarket distributor operations heads. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of diversified industrial conglomerates, and customs records of aluminum alloy trade flows. Bottom-up fastener content-per-vehicle estimates triangulated against top-down market value reconstructions.
Segment-weighting across product type, material grade, application, and connection type informed the analytical framework across the projection horizon. CAGRs were derived from modeled adoption curves of cell-to-pack architectures and solid-state battery commercialization timelines. Industry-specific inputs included GB/T 31467.3 implementation schedules, ECHA REACH restriction phase-out calendars, and PLI scheme disbursement milestones for ACC battery manufacturing.
Regulatory acceleration beyond modeled timelines, raw material cost volatility in titanium sponge and boron steel, and faster-than-anticipated solid-state battery thermal management hardware redesigns are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Rammer Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Struts System Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
India Automotive Lubricants Market