
 Train Locomotive Suspension Market | 2026-2036
Train Locomotive Suspension Market Size, Share, and Industry Trends Forecast 2026-2036
Train Locomotive Suspension Market Analysis
The EU Green Deal's rail modal shift targets is shifting procurement priorities toward systems that reduce track wear and energy consumption. Wabtec Corporation leverages its electro-pneumatic expertise to capture retrofit demand across European freight corridors. Knorr-Bremse anchors its position through captive supply of integrated braking-suspension packages for high-speed platforms. Continental AG differentiates via polymer composite leaf springs that cut unsprung mass versus traditional steel architectures.
Train locomotive suspension encompasses the spring-damper assemblies, linkages, and pivot mechanisms that isolate the car body from wheel-rail contact forces, typically managing static loads from 20 to 40 tonnes per axle while controlling lateral displacement to under 10 millimeters. Its primary purpose is to preserve ride quality, protect cargo, and extend rail infrastructure life by distributing dynamic impact loads. Bogie suspension captures the dominant value pool given its complexity and replacement frequency across heavy-haul fleets. Active suspension technology leads R&D investment as freight operators pursue autonomous load-leveling for variable commodity densities. Electro-pneumatic suspension occupies a growing niche in passenger rail services where real-time damping adjustment supports higher operating speeds.
The US Federal Railroad Administration enforces Part 213 track safety standards that mandate suspension condition monitoring, while the EU F-Gas Regulation pressures air suspension manufacturers toward lower-global-warming-potential pneumatic fluids. China's GB standards for railway vehicle dynamics testing create compliance barriers for imported bogie assemblies. Stakeholders must monitor how emerging digital twin requirements from Germany's KBA and Japan's METI reshape warranty terms and aftermarket service obligations.
Market Dynamics
The collision between freight fleet electrification timelines and legacy hydraulic suspension maintenance obligations is forcing operators into premature capital allocation decisions. This structural tension concentrates bargaining power with suppliers capable of bridging both technology generations.
Growth Catalysts
- EU Green Deal modal shift mandates:The policy framework prioritizes rail freight over road haulage, expanding procurement budgets for energy-efficient suspension architectures that reduce track degradation and rolling resistance.
- Active load-leveling systems:Autonomous suspension adjustment for variable commodity densities is accelerating adoption across North American bulk freight corridors handling grain, coal, and ore shipments.
- Germany's manufacturing cluster concentration:Berlin and Munich anchor a dense supplier ecosystem for integrated bogie assemblies, shortening development cycles for next-generation platforms.
Market Restraints
- Steel and rare earth input volatility:Suspension spring alloys and permanent magnet materials for active systems face price instability from concentrated mining operations.
- EU F-Gas Regulation compliance costs:Air suspension manufacturers must reformulate pneumatic fluids to lower-global-warming-potential alternatives, raising R&D and retooling expenditures.
- Technical limitation in sensor durability:Wheel-rail impact environments degrade condition-monitoring hardware faster than replacement cycles justify, limiting predictive maintenance rollout.
Strategic Opportunities
- Underpenetrated African freight corridors:Mining and port connectivity projects in Mozambique and Tanzania lack domestic suspension suppliers, creating first-mover advantages for established manufacturers.
- Digital twin integration:Convergence of physics-based modeling with real-time operational data enables warranty term restructuring and aftermarket service unbundling.
- Japan's METI autonomous rail initiatives:Government funding for self-adjusting suspension platforms creates dedicated demand pools for electro-pneumatic system developers.
Industry Challenges
- Mechatronics skill scarcity:Active suspension development requires rare combinations of mechanical engineering and embedded software expertise, constraining product rollout velocity.
- Legacy system integration friction:Retrofitting digital control architectures onto decades-old freight bogies demands custom interface engineering that fragments project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Locomotive Suspension Market |
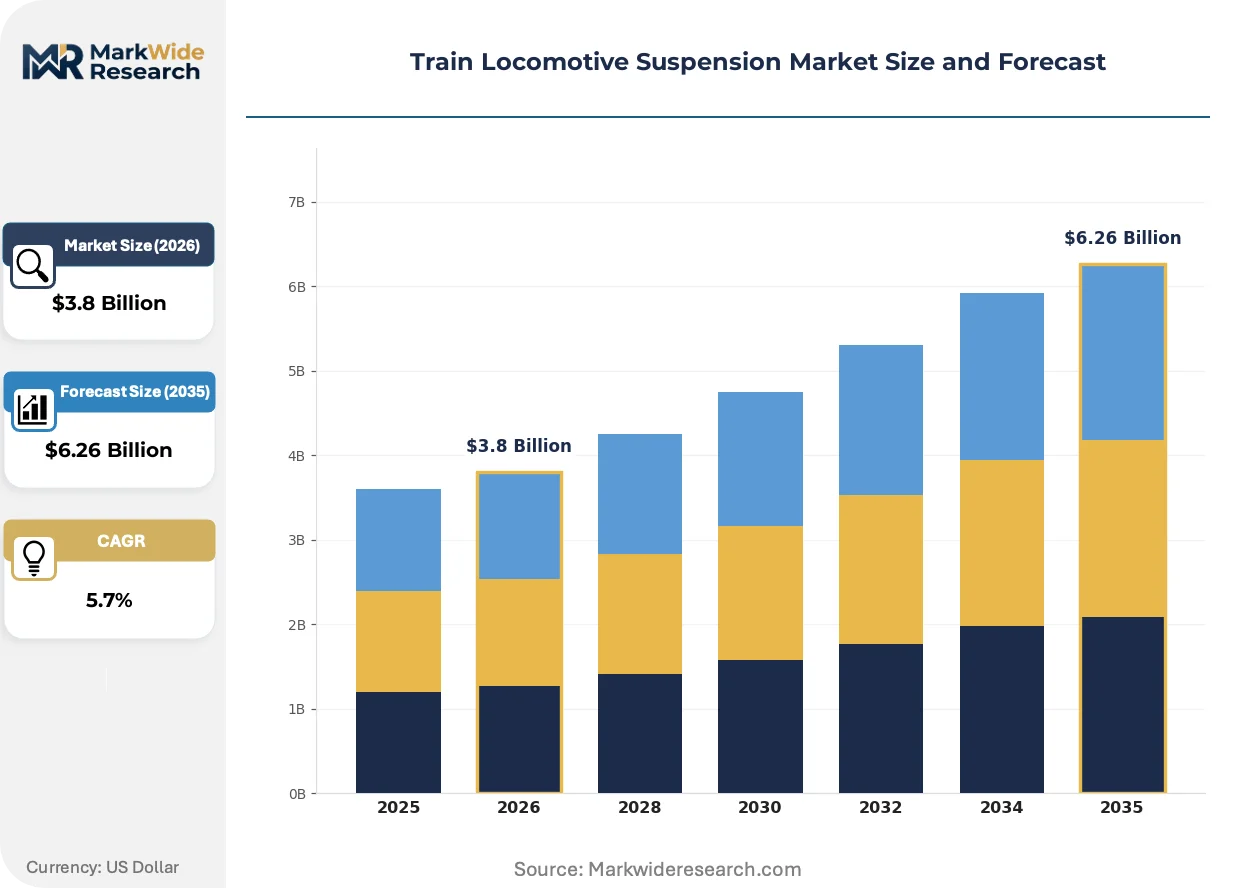
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Suspension, Leaf Spring, Hydraulic Suspension, Bogie Suspension Technology: Active Suspension, Passive Suspension, Semi-Active Suspension, Electro-Pneumatic Suspension End User: Freight Operators, Passenger Rail Services, Government Railways, Private Rail Operators Installation Type: New Installations, Retrofitting, Maintenance, Upgrades |
| Companies Covered | Stucki Company, Wabtec Corporation, Continental AG, Amsted Rail Company, Trelleborg AB, Knorr-Bremse, Nippon Steel & Sumitomo Metal Corporation, ZF Friedrichshafen AG, ALCO Spring Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Locomotive Suspension Market Emerging Trajectories
Material substitution and control system digitization are compressing traditional component hierarchies. Suppliers must now compete on embedded intelligence rather than metallurgical specifications alone.
Polymer composite leaf springs are consolidating supplier tiers by replacing multi-part steel assemblies with single-molded structures. Freight operators in Germany and the United States are specifying these for new heavy-haul builds. The technology is consolidating procurement decisions around polymer chemistry capabilities rather than conventional forging expertise.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon-based pneumatic fluids in rail applications from 2027. Air suspension manufacturers are accelerating qualification of hydrofluoroolefin and compressed air alternatives. European passenger rail fleets face the steepest transition costs given their higher air suspension penetration versus North American freight dominance of coil and leaf architectures.
Asset performance contracts are displacing component-only sales in fleet modernization programs. Operators in Australia and Brazil now specify availability guarantees rather than unit prices. Mining sector procurement teams in Western Australia are leading this shift, demanding suspension suppliers absorb downtime risk through outcome-based service agreements.
Train Locomotive Suspension Market Segmentation
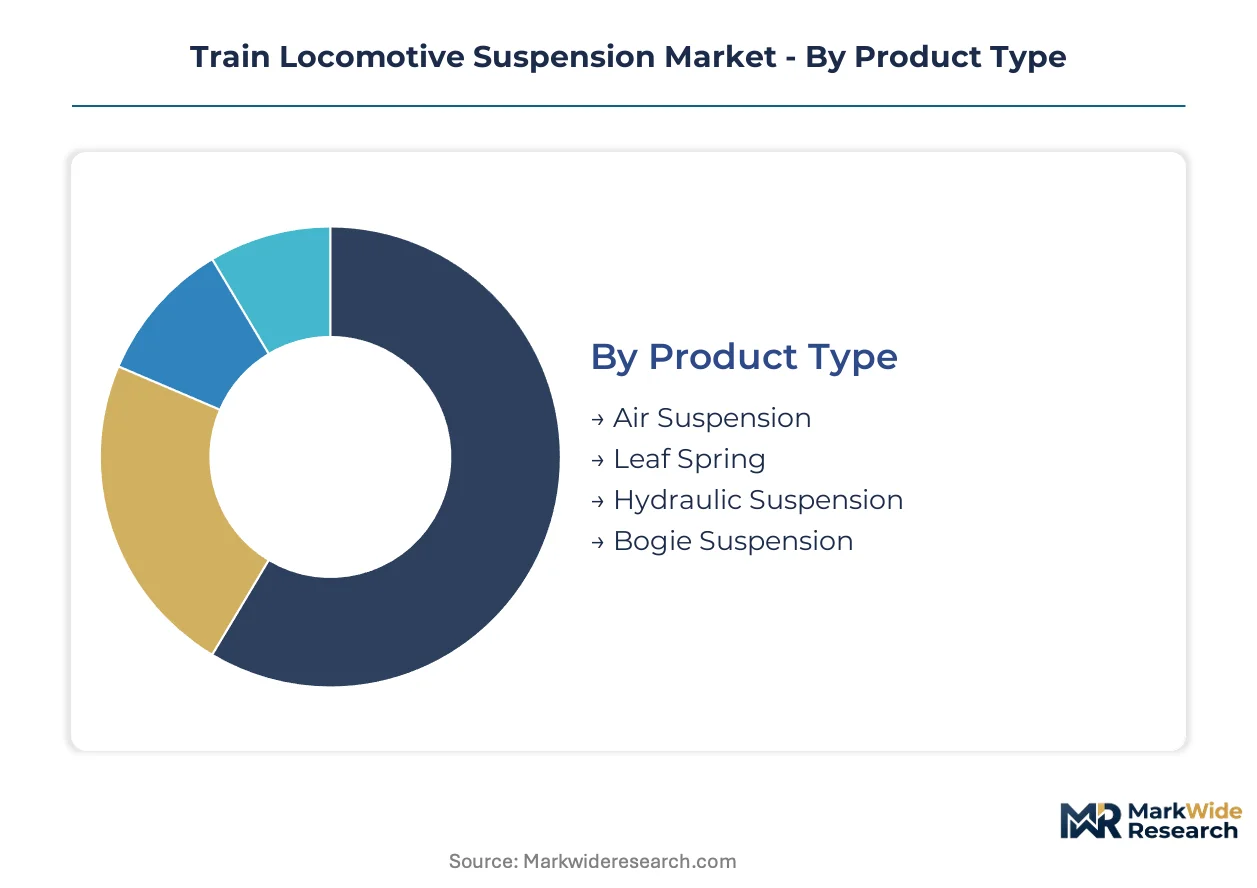
Train locomotive suspension procurement decisions fragment across four distinct dimensions. Product architecture determines raw material exposure and replacement cadence. Technology tier dictates embedded software complexity and regulatory compliance burden.
Product Type:
EU F-Gas Regulation certification requirements fall heaviest on air suspension architectures, while bogie assemblies face Germany KBA and China GB standards for complete system validation. Leaf spring and hydraulic variants navigate simpler component-level approval pathways.
- Bogie Suspension:Integrated spring-damper-linkage assemblies managing 20-40 tonne axle loads. Freight operators in North America specify these for heavy-haul corridors, with replacement cycles driving recurring revenue concentration. The US Federal Railroad Administration mandates condition monitoring integration for Part 213 compliance.
- Air Suspension:Pneumatic bellows and height-control valve systems enabling real-time stiffness adjustment. Passenger rail services in Germany and France dominate demand, pressured by EU F-Gas Regulation deadlines to reformulate pneumatic fluids.
- Leaf Spring:Multi-leaf steel or polymer composite assemblies providing progressive rate characteristics. Continental AG's composite variants cut unsprung mass for energy-conscious freight fleets.
- Hydraulic Suspension:Oil-damper systems with fixed damping curves. Legacy freight fleets in Eastern Europe and Russia maintain substantial installed bases.
Bogie Suspension sits at the top of the volume ranking, with Air Suspension climbing the fastest.
Technology:
Cost stratification separates passive architectures from electro-pneumatic and active systems requiring sensor suites and control modules. Semi-active platforms occupy a mid-tier pricing band with faster payback periods.
- Active Suspension:Real-time force actuation using powered actuators and predictive algorithms. Autonomous load-leveling for variable commodity densities drives adoption across Australian and Brazilian mining corridors.
- Electro-Pneumatic Suspension:Electronically controlled air spring systems with millisecond response times. Japan's METI funding accelerates deployment for next-generation passenger platforms.
- Passive Suspension:Fixed-rate mechanical springs and dampers without external power. Dominates North American freight due to simplicity and field-serviceability.
- Semi-Active Suspension:Magnetorheological or solenoid-controlled damping with limited energy input. Emerging as a compromise for European regional rail operators balancing cost and ride quality.
Passive Suspension retains volume leadership, though Active Suspension is gaining share fastest.
End User:
Application intensity varies sharply: freight operators prioritize durability and payload protection, while passenger services optimize for ride comfort and speed stability.
- Freight Operators:Bulk commodity and intermodal carriers specifying suspension for 30-year service lives. North American Class I railroads anchor demand with fleet modernization programs.
- Passenger Rail Services:High-speed and regional operators demanding active systems for track-friendly dynamics at 200+ km/h operation.
- Government Railways:State-owned networks in India and China with centralized procurement and domestic content requirements.
- Private Rail Operators:European open-access freight carriers and UK passenger franchises with asset-light leasing models.
Freight Operators command the volume ranking, with Passenger Rail Services expanding most quickly.
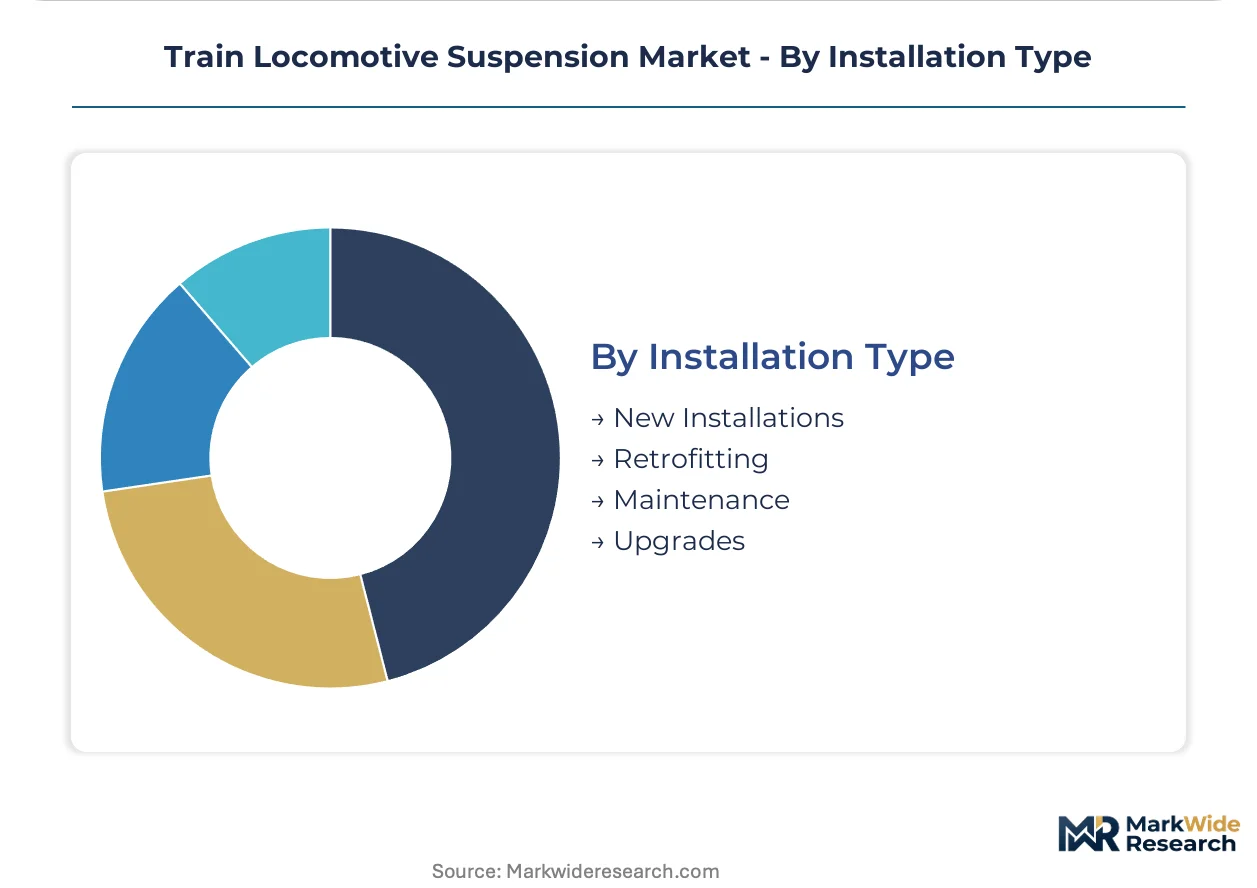
Installation Type:
Customer type determines project economics: fleet owners favor new installations with warranty bundling, while third-party maintainers capture retrofit and upgrade cycles.
- New Installations:Factory-integrated systems on rolling stock builds. OEM specification locks in supplier relationships for 15-25 year platform lives.
- Retrofitting:Technology insertion onto legacy bogies. Wabtec Corporation and Knorr-Bremse compete for European freight corridor modernization contracts.
- Maintenance:Scheduled component replacement and damper refurbishment. Mining sector procurement in Western Australia shifts toward outcome-based service agreements.
- Upgrades:Performance enhancement packages adding sensors or control modules. Digital twin integration creates warranty restructuring opportunities.
Maintenance captures the highest transaction frequency, with Retrofitting showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern rail suspension industry traces its industrial lineage to nineteenth-century foundries in Germany and Pennsylvania, where steel spring manufacturing first scaled to meet locomotive axle load requirements. That heritage persists in today's geographic concentration of advanced bogie assembly capabilities.
United States
Class I freight railroads drive suspension procurement through fleet modernization programs covering 25,000+ locomotives. The Federal Railroad Administration enforces Part 213 track safety standards mandating suspension condition monitoring integration. Chicago anchors the heaviest concentration of railcar manufacturing and remanufacturing facilities, with Wabtec Corporation and Amsted Rail maintaining significant operational presence across the Midwest corridor.
Germany
Berlin and Munich host Europe's densest supplier ecosystem for integrated bogie assemblies, shortening development cycles for next-generation platforms. The KBA (Kraftfahrt-Bundesamt) imposes digital twin documentation requirements that reshape warranty terms for suspension system suppliers. Continental AG leverages polymer composite leaf spring production from its Hanover-area manufacturing base to serve energy-conscious freight operators.
China
State-owned railway procurement under CRRC concentrates demand for high-speed and heavy-haul suspension platforms. GB standards for railway vehicle dynamics testing create compliance barriers for imported bogie assemblies, favoring domestic suppliers. The Yangtze River Delta manufacturing cluster around Shanghai and Nanjing houses the country's largest concentration of rail component foundries and spring manufacturers.
Japan
METI funding for autonomous rail initiatives creates dedicated demand pools for electro-pneumatic system developers. The Kanto region surrounding Tokyo concentrates precision manufacturing capabilities for sensor-integrated active suspension platforms. Nippon Steel & Sumitomo Metal Corporation maintains steel spring production facilities serving both domestic Shinkansen operators and export markets.
Australia
Mining sector procurement teams in Western Australia lead the shift toward outcome-based service agreements for suspension maintenance. The Pilbara iron ore corridor generates extreme duty-cycle requirements that accelerate wear on bogie components. Perth-based engineering firms coordinate fleet availability contracts that transfer downtime risk to suspension suppliers.
Train Locomotive Suspension Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier structure. Integrated bogie assemblers with captive forging and foundry capabilities hold pricing power over component-only vendors. The market stratifies into three archetypes: diversified industrial conglomerates with rail divisions, specialized suspension system houses, and regional spring manufacturers serving aftermarket channels. Competitive moves concentrate on backward integration into polymer composite materials and geographic expansion into underpenetrated mining corridors.
Among diversified industrial groups, Continental AG exemplifies the materials-science-driven archetype through its polymer composite capabilities. Wabtec Corporation and Knorr-Bremse occupy positions as integrated system suppliers with electro-pneumatic and braking-suspension bundling expertise. Regional specialists including Stucki Company and ALCO Spring Industries Inc. represent the focused component manufacturer tier serving North American aftermarket demand.
| Leading Market Players |
|---|
| Stucki Company |
| Wabtec Corporation |
| Continental AG |
| Amsted Rail Company |
| Trelleborg AB |
| Knorr-Bremse |
| Nippon Steel & Sumitomo Metal Corporation |
| ZF Friedrichshafen AG |
| ALCO Spring Industries Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU F-Gas compliant air suspension and legacy hydraulic systems manifests in both procurement premiums and supplier consolidation patterns. Premium-tier manufacturers command pricing power through captive polymer composite production, while commodity steel spring suppliers face margin compression from volatile alloy input costs and shorter replacement cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates active electro-pneumatic systems from semi-active dampers and passive mechanical springs. Price differentiation rests on embedded sensor density and KBA digital twin documentation compliance, with German passenger rail operators showing lowest sensitivity and Eastern European freight maintainers exhibiting highest cost consciousness. Cost compression in passive steel architectures is intensifying because Brazilian and Australian mining procurement teams now bundle availability guarantees into long-term service contracts rather than paying unit premiums.
Supply Chain Analysis
Single-source vulnerability sits with concentrated rare earth magnet production for active suspension actuators and specialized polymer feedstock for composite leaf springs. Manufacturing gravity centers on Germany, China, and Japan, with the Yangtze River Delta and Berlin-Munich corridor housing critical bogie assembly capabilities. Raw material dependencies draw from high-grade spring steel alloys, magnetorheological fluids, and fluoropolymer compounds. Tariff exposure on Chinese-sourced permanent magnets threatens electro-pneumatic system cost structures. Distribution runs through OEM captive supply agreements for new installations and authorized service networks for aftermarket maintenance cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as freight operators shift procurement criteria from unit cost toward track-wear reduction and energy efficiency metrics. Premium suspension specifications now dominate fleet modernization programs across North American Class I railroads and Australian mining corridors.
For Market Incumbents: Deepen backward integration into polymer composite chemistry to defend margin position against materials-science entrants. Lock in long-term offtake agreements with rare earth processors to hedge magnet cost volatility threatening active system profitability. Accelerate KBA digital twin certification to capture warranty restructuring opportunities before regulatory mandates harden.
For New Entrants and Emerging Players: Sensor-integrated predictive maintenance platforms offer the most penetrable wedge for disrupting established aftermarket channels. Target underpenetrated African mining corridors in Mozambique and Tanzania where domestic suspension capabilities are absent and port connectivity projects demand first-mover technical support. Lead with outcome-based availability contracts rather than component pricing to bypass incumbent OEM relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics skill scarcity constrains active suspension development velocity and fragments project economics. Mid-tier regional spring manufacturers with established rail certifications represent prime acquisition targets for industrial conglomerates seeking rail division expansion. Watch for inflection when METI autonomous rail funding triggers dedicated procurement pools for electro-pneumatic developers in Japan.
| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Composite Material Integration | Captive production of leaf spring substrates cuts unsprung mass for energy-conscious German freight fleets. |
| Digital Twin Platform Development | KBA documentation requirements reshape warranty terms and create aftermarket service unbundling opportunities. |
| Rare Earth Magnet Supply Agreement | Long-term offtake hedges input cost volatility threatening active suspension actuator manufacturing economics. |
| Outcome-Based Service Contracting | Western Australian mining procurement teams now demand suppliers absorb downtime risk through availability guarantees. |
| EU F-Gas Alternative Fluid Qualification | Hydrofluoroolefin and compressed air system certification captures European passenger rail replacement demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with rolling stock procurement directors, bogie assembly plant managers, rail maintenance engineers, and FRA compliance officers with secondary validation. Bottom-up triangulation drew from supplier shipment records, customs data on spring alloy imports, and CRRC procurement disclosures, while top-down cross-checks referenced EU Green Deal modal shift targets and METI autonomous rail funding allocations. Secondary sources included FRA Part 213 enforcement data, KBA technical documentation requirements, and GB standards for railway vehicle dynamics testing.
Comparable-period anchoring linked projection assumptions to historical fleet replacement cycles and modernization program cadences across the analysis window. Segmentation modeling incorporated product architecture, technology tier, end-user intensity, and installation type dimensions. CAGRs derived from rolling stock production forecasts, suspension content per bogie estimates, and regional procurement budget trajectories. Industry-specific inputs captured EU F-Gas Regulation compliance deadlines and active load-leveling adoption curves in Australian bulk freight corridors.
The model holds under stable alloy pricing and sustained modal shift policy support; deviation in rare earth export restrictions or F-Gas transition delays would shift volume trajectories. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Europe 40-Foot Platform Wagons Market
Railway
Railway Window Market
Railway
Connected Rail Market
Railway
Gangway for Railway Vehicles Market
Railway
Railway Pantograph Market
Railway
Railroad Brake Shoe Market
Railway
Train Exterior Lighting Market
Railway
Locomotive Radiator Fan Market
Railway
Railway Braking System Market
Railway
Global Train Control and Management Systems Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Locomotive Doors Market
Railway
India Rail Freight Transport Market
Railway
Global Hyperloop Train Market
Railway
Smart Railways Market
Railway
Railway Horn Market