
 Railway Pantograph Market | 2026-2036
Railway Pantograph Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Pantograph Market Analytics
Carbon-fiber-reinforced polymer integration is rewriting pantograph design by slashing static weight and permitting higher operating speeds without sacrificing contact force stability. Schunk Group leverages its materials science heritage to dominate carbon-composite strip supply for premium high-speed installations. Siemens Mobility anchors European market presence through captive production of integrated roof systems for ICE and regional trainsets. CRRC Corporation Limited sustains cost competitiveness via in-house aluminum forging and domestic rare-earth magnet sourcing for active control mechanisms.
A railway pantograph is an articulated current-collection device mounted on electric locomotive or multiple-unit roofs, typically fabricated from aluminum alloy frames with copper or sintered carbon contact strips, designed to maintain uninterrupted electrical transfer from overhead catenary wires at speeds exceeding 300 km/h. High-speed product variants command premium positioning due to aerodynamic profiling requirements and active suspension modules that compensate for wire irregularities. Composite material segments are gaining fastest traction as operators trade steel and copper for hybrid laminates that extend maintenance intervals and reduce catenary abrasion. Fixed installation types retain volume leadership in commuter and metro applications where route predictability eliminates pivot complexity.
FRA safety standards in the United States, EN 50206 in Europe, and China's GB/T 32595 collectively enforce minimum electrical clearance, mechanical fatigue resistance, and electromagnetic compatibility thresholds that filter marginal suppliers from qualified vendor lists. REACH restrictions on hexavalent chromium plating and EU Ecodesign directives are accelerating coating substitution programs across European supply chains. Stakeholders must monitor how emerging interoperability standards for cross-border corridors reshape certification burdens and whether active suspension patents consolidate around integrated system vendors or remain accessible to component specialists.
Market Dynamics
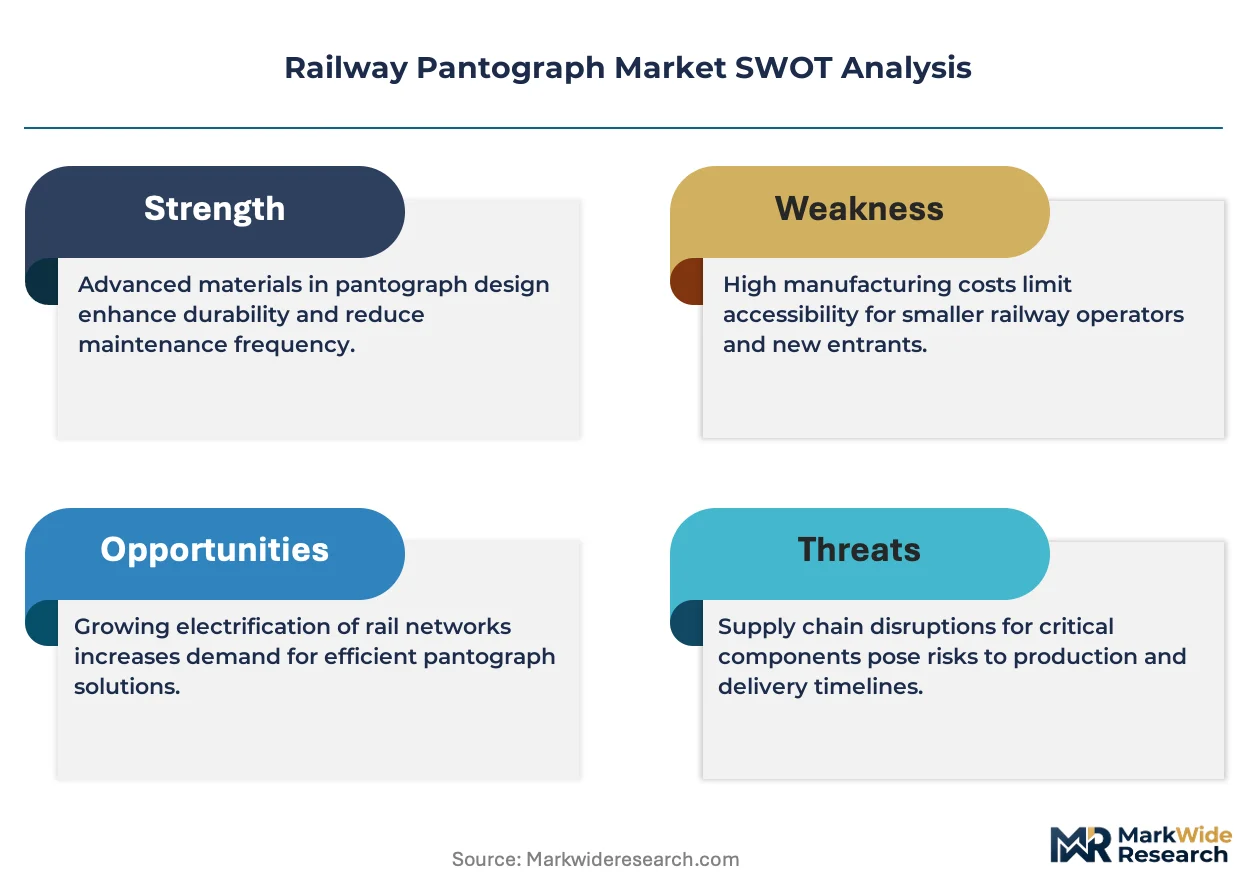
Composite material substitution is compressing traditional aluminum-copper pantograph architectures as operators prioritize catenary wear reduction and speed ceiling expansion over legacy durability metrics.
Growth Catalysts
- EU Ecodesign Directive:Mandates on energy efficiency and material recyclability are accelerating composite strip adoption across European high-speed fleets.
- China's dual carbon goals:National targets for net-zero rail operations are electrifying regional lines and expanding pantograph installation volumes.
- Active suspension modules:Sensor-integrated control systems are enabling stable current collection at speeds previously requiring mechanical redesign.
Market Restraints
- Rare-earth magnet volatility:Neodymium price swings from Chinese export controls are destabilizing cost structures for active control mechanisms.
- REACH hexavalent chromium ban:Coating substitution programs are extending qualification timelines and freezing supplier transitions.
- Carbon-fiber supply concentration:Toray, Mitsubishi Chemical, and SGL Carbon control 70% of aerospace-grade precursor output, creating bottleneck risk for rail-qualified laminates.
Strategic Opportunities
- India's Dedicated Freight Corridors:Electrification of 2,800 route kilometers under Indian Railways' expansion plan opens procurement for heavy-haul pantograph variants.
- Digital twin integration:Predictive maintenance platforms combining IoT sensors and physics modeling are creating service revenue streams beyond hardware sales.
- Cross-border corridor interoperability:TSI LOC&PAS harmonization across EU corridors is consolidating certification requirements and favoring system-integrated vendors.
Industry Challenges
- Composite fatigue characterization:Rail-specific carbon-fiber validation protocols remain underdeveloped, forcing extended field trials before homologation.
- Active control IP fragmentation:Patent thickets around sensor fusion algorithms are complicating licensing for component specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Pantograph Market |
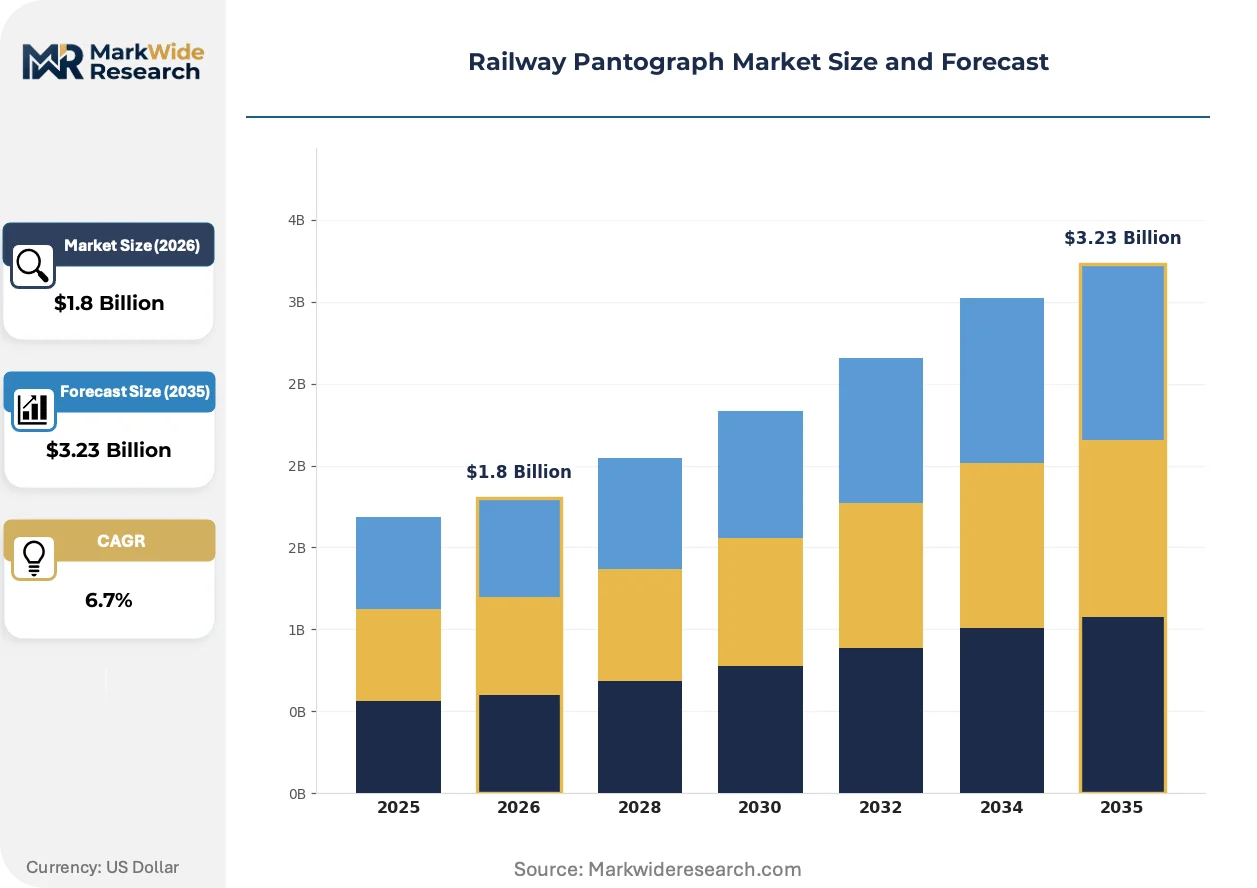
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Arm, Double Arm, High Speed, Fixed Material: Aluminum, Copper, Steel, Composite Connection Type: Welded, Bolt-on, Clamped, Detachable Installation Type: Fixed Mount, Pivoting, Modular, Integrated |
| Companies Covered | CRRC Corporation Limited, Hitachi Rail Limited, Schunk Group, Mersen Group, Knorr-Bremse AG, Wabtec Corporation, Siemens Mobility, ABB Ltd, Alstom SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Pantograph Market Evolving Landscape
Material science breakthroughs and predictive control architectures are converging to redefine pantograph lifecycle economics, shifting value capture from hardware durability to operational uptime guarantees.
Carbon-fiber-reinforced polymer contact strips are migrating from aerospace prototyping to rail-qualified production, with T800-grade laminates replacing sintered carbon in ICE and Shinkansen test fleets. Deutsche Bahn's specifications now permit full composite contact systems for 320 km/h operation. This technology is migrating from premium high-speed niches toward regional trainsets as unit costs fall and maintenance interval data accumulates.
REACH restrictions on hexavalent chromium plating entered full enforcement across EU supply chains in 2024, compelling coating suppliers to accelerate trivalent chromium and ceramic-alternative qualification programs. Surface treatment vendors are consolidating testing resources to share homologation costs. German and French operators are driving the transition fastest, with SNCF mandating chrome-free pantograph frames for all 2025 tenders.
After-sales service unbundling is disrupting traditional procurement, with operators separating hardware purchase from predictive maintenance contracts and favoring specialist diagnostics firms over integrated OEM packages. DB Systemtechnik and SNCF Réseau are piloting outcome-based availability agreements where suppliers guarantee contact quality metrics rather than component replacement schedules. This model is most advanced in Germany, where digital infrastructure maturity supports real-time pantograph monitoring across the entire electrified network.
Railway Pantograph Market Segmentation
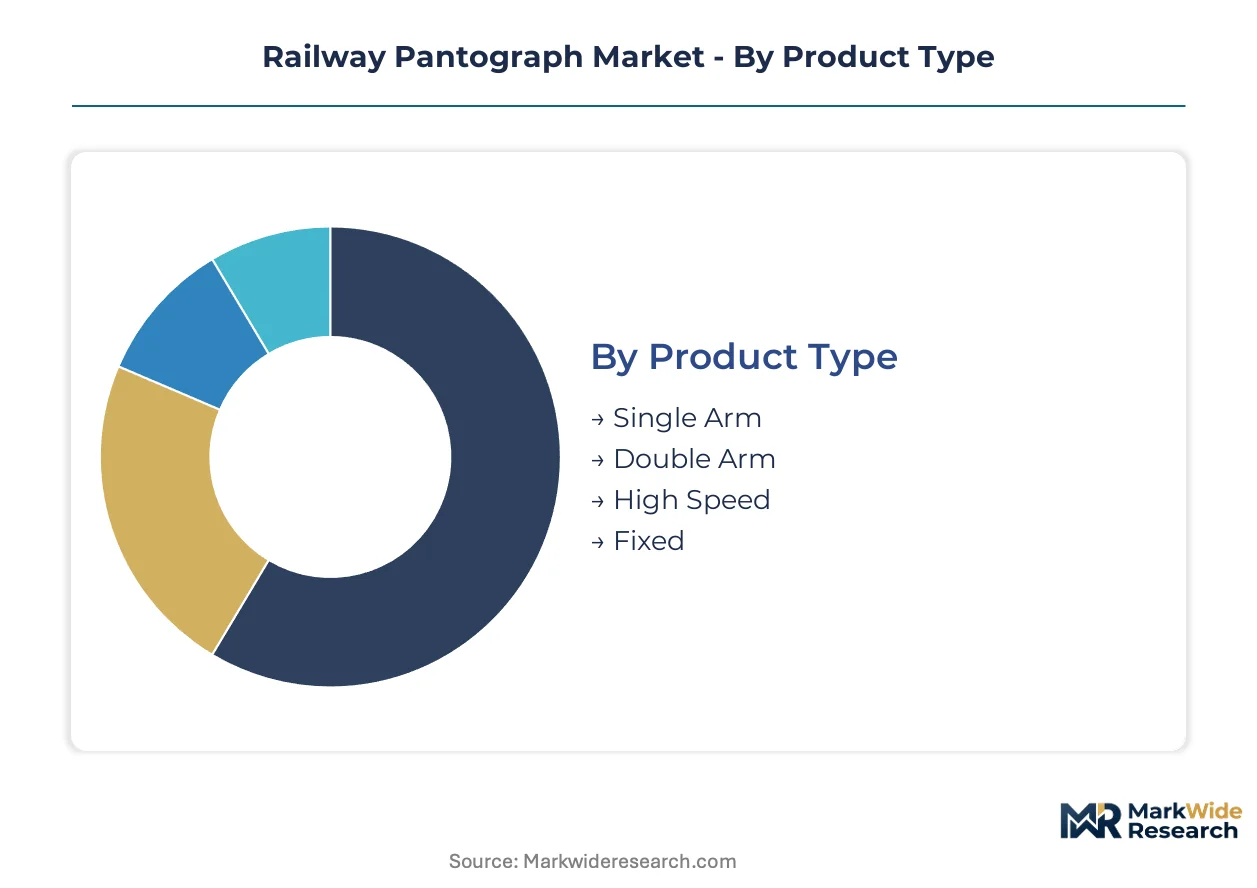
Pantograph procurement cycles vary dramatically across product architectures, with high-speed variants commanding decade-long replacement schedules while commuter installations turn over every five to seven years. Material composition and mounting configuration further stratify maintenance economics, creating distinct aftermarket revenue pools for suppliers.
Product Type:
Replacement velocity separates this category sharply, with high-speed platforms enduring fifteen-year service intervals against single-arm commuter units requiring overhaul every six to eight years.
- Single Arm:Articulated asymmetric frames dominate regional and commuter trainsets across Germany and France, where Deutsche Bahn and SNCF prioritize mechanical simplicity and lower mass for frequent stop-start operations. Operators accept reduced maximum speed in exchange for faster component swaps and standardized tooling across mixed fleets.
- High Speed:Aerodynamically profiled assemblies with active suspension modules command premium positioning for ICE, Shinkansen, and Chinese Fuxing services exceeding 300 km/h. China's expanding high-speed network under dual carbon mandates is driving procurement volume for these specialized variants.
- Double Arm:Symmetrical diamond configurations persist in heavy-haul freight applications across India and Russia, where robust current collection under variable wire tension outweighs aerodynamic penalties.
- Fixed:Rigid non-articulated designs serve metro and light rail systems with predictable route geometry, eliminating pivot maintenance in tunnel-constrained environments like London Underground and Paris Metro.
Single Arm dominates installed base. High Speed is where expansion concentrates.
Material:
Cost tiers separate legacy metallurgy from advanced composites, with aluminum-copper hybrids occupying mid-market positioning and carbon-fiber systems commanding 40-60% premiums.
- Composite:Carbon-fiber-reinforced polymer contact strips are displacing sintered carbon in ICE and Shinkansen test fleets, with T800-grade laminates permitting 320 km/h operation while slashing catenary wear. REACH restrictions on hexavalent chromium plating accelerate coating substitution programs for composite-compatible surface treatments.
- Aluminum:Extruded alloy frames remain volume leaders for regional trainsets, with CRRC Corporation leveraging in-house forging capabilities to compress cost structures for Chinese domestic procurement.
- Copper:High-conductivity contact strips retain dominance in heavy-current freight applications where thermal management trumps weight reduction.
- Steel:Structural reinforcement components persist in cost-optimized emerging market installations, though density penalties limit new adoption.
Aluminum anchors current production volumes. Composite is climbing the fastest as operators prioritize catenary preservation.
Connection Type:
Field serviceability requirements shape procurement preferences, with bolt-on and clamped configurations enabling rapid turnaround versus welded joints demanding shop-floor intervention.
- Bolt-on:Threaded mechanical fastening dominates European maintenance depots, where EN 50206 compliance documentation supports component traceability across multi-operator fleets.
- Clamped:Compression-fit joints accelerate pantograph head replacement in high-utilization corridors, with DB Systemtechnik specifying clamped interfaces for outcome-based availability contracts.
- Welded:Permanent joints persist in OEM-integrated roof systems where Siemens Mobility and CRRC optimize structural integrity over field modularity.
- Detachable:Quick-release mechanisms serve specialized inspection and tunnel-clearance requirements in Swiss alpine routes and Japanese mountain corridors.
Bolt-on dominates aftermarket procurement. Clamped is gaining share fastest through predictive maintenance integration.
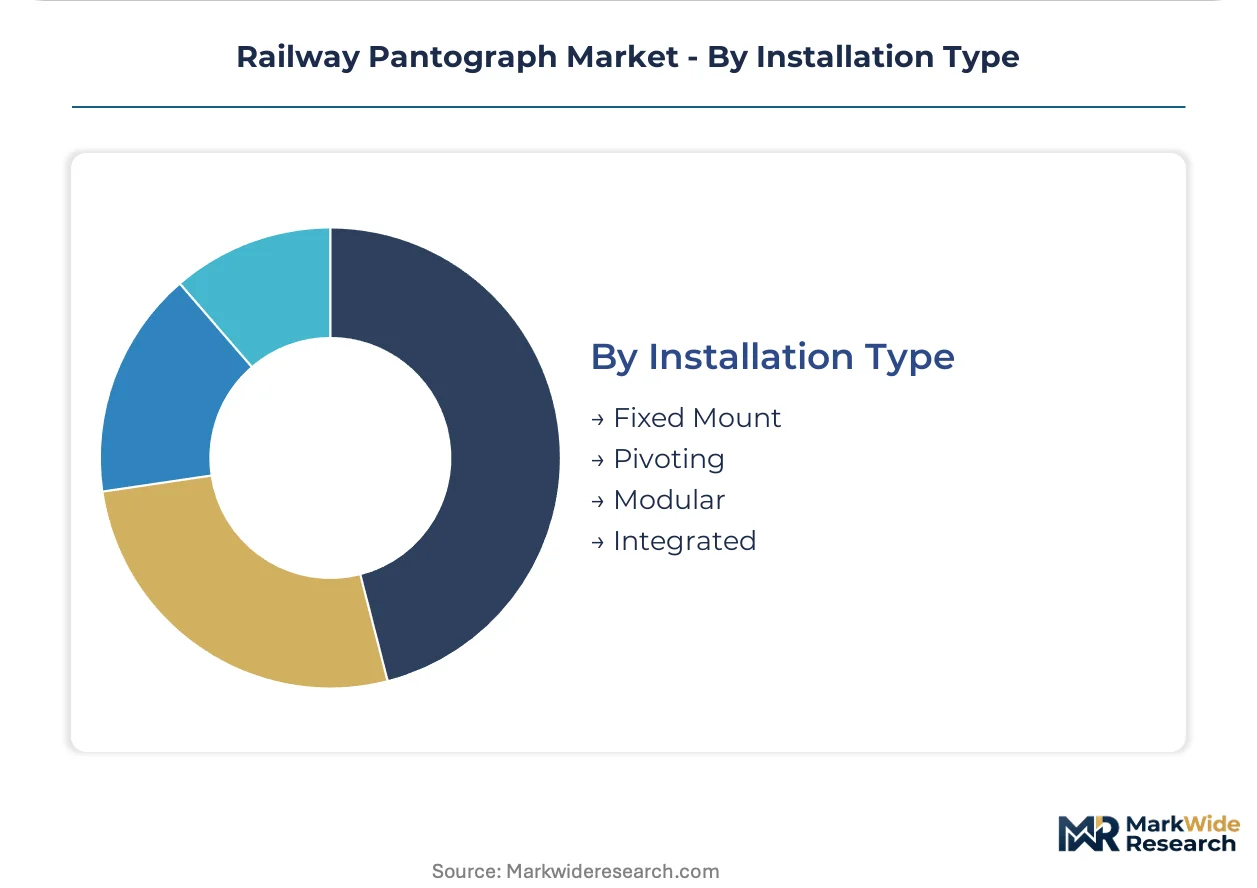
Installation Type:
Integration depth with vehicle roof architecture determines supplier relationship structures, from discrete component sales to captive system partnerships.
- Fixed Mount:Rigid attachment to roof structure serves metro applications with consistent wire height and minimal aerodynamic variation.
- Pivoting:Articulated bases compensate for vehicle roll and wire stagger in high-speed corridors, with active control mechanisms adding sensor-integrated stabilization.
- Modular:Standardized interface specifications enable operator mixing of pantograph heads, frames, and control units from competing suppliers, particularly advanced in German and Austrian procurement frameworks.
- Integrated:Complete roof system packages bundle pantograph, HVAC, and high-voltage equipment, with Siemens Mobility and CRRC leveraging captive production to lock in long-term service agreements.
Pivoting anchors high-speed fleet specifications. Modular is where procurement flexibility concentrates as operators unbundle hardware from service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pantograph exports supply high-speed rail operators across Central Europe, while Chinese manufacturers dominate domestic procurement and emerging Asian electrification projects. Trade corridors link component specialists in Japan to maintenance depots in Southeast Asian metro systems.
Germany
Deutsche Bahn's fleet modernization under the Deutschlandtakt integrated timetable program sustains demand for next-generation contact systems. EN 50206 compliance mandates shape supplier qualification timelines for cross-border ICE services. Berlin-Brandenburg and Bavaria host engineering clusters where Siemens Mobility and Schunk Group coordinate composite material testing for 320 km/h operation.
China
CRRC Corporation leverages in-house aluminum forging and domestic rare-earth sourcing to compress cost structures for Fuxing trainset deployments. MIIT's dual carbon goals accelerate regional line electrification beyond coastal corridors. The Yangtze River Delta concentration around Shanghai and Nanjing anchors high-speed pantograph production for both domestic and Belt and Road export contracts.
Japan
Shinkansen network expansion and maglev corridor development sustain precision pantograph demand from JR Central and JR East. METI's railway technology export promotion aligns component standards with Southeast Asian procurement frameworks. The Kanto cluster around Tokyo and Yokohama integrates Hitachi Rail's active suspension R&D with Toray's carbon-fiber precursor supply for next-generation contact strips.
United States
Amtrak's Acela fleet replacement and California high-speed rail construction create procurement openings for European and Asian system integrators. FRA safety standards enforce electrical clearance and fatigue resistance thresholds that filter qualified vendors. The Northeast Corridor concentration between Boston and Washington D.C. drives specialized pantograph specifications for mixed freight-passenger traffic.
India
Indian Railways' Dedicated Freight Corridor electrification of 2,800 route kilometers opens heavy-haul pantograph procurement for aluminum-steel hybrid designs. BIS certification requirements and the PLI scheme for rail component manufacturing favor domestic assembly partnerships. The Delhi-Mumbai Industrial Corridor clusters in Gujarat and Maharashtra concentrate depot infrastructure for pantograph maintenance and component refurbishment.
Railway Pantograph Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement frameworks. System-integrated vendors anchor premium high-speed segments through captive roof-system production, while component specialists capture aftermarket service revenue through predictive maintenance platforms. Three archetypes dominate: vertically integrated rail OEMs, materials-science-driven contact strip specialists, and diagnostics-focused service unbundlers. Consolidation pressure concentrates around active suspension IP and composite material qualification capabilities.
Among China-based fabricators, CRRC Corporation Limited occupies the scale-driven system-integrator position. German specialists Schunk Group and Siemens Mobility exemplify the premium-tier materials-and-systems archetype, with the former representing carbon-composite contact strip expertise and the latter anchoring integrated roof-system supply. Japanese engineering heritage surfaces through Hitachi Rail Limited's positioning within active control mechanism development.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Hitachi Rail Limited |
| Schunk Group |
| Mersen Group |
| Knorr-Bremse AG |
| Wabtec Corporation |
| Siemens Mobility |
| ABB Ltd |
| Alstom SA |
| Others |
Value Network & Pricing Analysis
Toray, Mitsubishi Chemical, and SGL Carbon's collective grip on aerospace-grade carbon-fiber precursor output anchors margin capture in downstream rail-qualified laminates. Buyers of composite pantograph systems absorb 40-60% premiums over aluminum-copper architectures because supply concentration at the precursor tier limits competitive pressure on strip fabricators.
Pricing Analysis
Next-generation carbon-fiber-reinforced polymer contact strips command substantial premiums against legacy sintered carbon and mid-tier aluminum-copper hybrids. Three-tier pricing structure across premium composite, standard aluminum, and economy steel configurations reflects certification grade and active suspension integration. Pricing pressure stems from rare-earth magnet volatility destabilizing cost structures for sensor-integrated control mechanisms. Freight operators in India and Russia exhibit highest price sensitivity, while European high-speed rail procurement favors performance over unit cost.
Supply Chain Analysis
Contract manufacturing for pantograph frames concentrates with CRRC Corporation's in-house aluminum forging operations, Siemens Mobility's captive roof-system production, and Schunk Group's composite strip fabrication. Raw material flows draw from Chinese rare-earth processing, Japanese carbon-fiber precursor supply, and German precision machining clusters. Single-source vulnerability runs through Toray's T800-grade laminate qualification for 320 km/h operation. Distribution runs through OEM-integrated roof system packages and specialist aftermarket service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service unbundling and predictive maintenance adoption fragment procurement authority, creating specialist niches alongside integrated system vendors. Composite material qualification capabilities and active suspension IP access determine competitive positioning across these emerging segments.
For Market Incumbents: Insulate premium positioning by accelerating T800-grade laminate homologation ahead of REACH coating substitution deadlines. Secure captive rare-earth magnet supply through backward integration into Chinese domestic sourcing networks. Defend against diagnostics-focused service unbundlers by embedding IoT sensor packages into hardware contracts. For New Entrants and Emerging Players: India's Dedicated Freight Corridor electrification represents the most penetrable entry point for heavy-haul aluminum-steel hybrid designs. Regional European maintenance depots seeking modular bolt-on configurations for mixed fleets offer secondary white-space. A go-to-market angle centered on outcome-based availability guarantees—contact quality metrics rather than replacement schedules—bypasses incumbent service lock-in. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rail component specialists holding EN 50206 certification but lacking composite material science depth. Long-term viability over a 5-10 year horizon hinges on positioning for TSI LOC&PAS harmonization consolidation. Watch for Deutsche Bahn or SNCF mandating chrome-free frames as the inflection signal for coating substitution winners.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Qualification | T800-grade laminate homologation secures 320 km/h ICE and Shinkansen procurement eligibility. |
| Active Suspension IP Development | Sensor fusion algorithm patents differentiate premium high-speed pantograph system vendors. |
| Digital Twin Integration | Predictive maintenance platforms with DB Systemtechnik create recurring revenue beyond hardware. |
| Rare-Earth Supply Security | Domestic neodymium sourcing under MIIT dual carbon goals insulates CRRC cost structures. |
| REACH Coating Substitution | Trivalent chromium and ceramic alternatives unlock SNCF 2025 tender participation. |
Research Methodology
Desk research of customs trade databases, railway operator procurement records, and patent filings preceded structured interviews with pantograph engineering directors, fleet procurement managers at Deutsche Bahn and SNCF, and aftermarket service heads at CRRC and Siemens Mobility. Secondary validation drew from EN 50206 compliance documentation, MIIT dual carbon policy releases, and REACH restriction enforcement timelines. Bottom-up modeling of installation volumes triangulated against top-down market sizing from OEM production forecasts.
Assumptions held fixed include China's electrification trajectory under dual carbon goals and EU Ecodesign Directive enforcement timelines, while rare-earth price volatility and composite fatigue validation protocols were stress-tested across scenarios. Segmentation dimensions spanned product architecture, material composition, connection type, and installation depth. CAGRs derived from logistic curve fitting to electrified fleet deployment schedules, with high-speed rail expansion and freight corridor electrification as primary volume drivers.
Practitioners should monitor neodymium export control announcements, T800-grade laminate field trial results, and TSI LOC&PAS revision drafts for early signals of forecast deviation. Quarterly review of operator tender specifications and REACH enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railcar Vehicle Toilet Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Railway Telematics Market
Railway
Global Train Lighting Market
Railway
Europe Intermodal Terminals Market
Railway
Automatic Train Supervision Market
Railway
Railway Automated Inspection Equipment Market
Railway
Gangway for Railway Vehicles Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Rail Maintenance Management System Market
Railway
Maglev Train Market
Railway
Train Bogie Market
Railway
Train Locomotive Suspension Market
Railway
Latin America Connected Rail Market
Railway
Train Suspension System Market
Railway
Railway Window Market