
 Locomotive Doors Market | 2026-2036
Locomotive Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Doors Market Foresight
European steel forging capacity for rail components is hardening as energy costs reshape supplier economics. Knorr-Bremse leverages its integrated brake-door control platforms to anchor premium contracts with Deutsche Bahn and SNCF. Wabtec Corporation sustains North American aftermarket dominance through captive service networks. Faiveley Transport competes on platform screen door integration, a niche where it occupies technology leadership.
Locomotive doors are engineered access systems built to withstand cyclic pneumatic loading, fire resistance ratings, and passenger safety interlocks, typically fabricated from extruded aluminum or stainless steel with rubber-composite sealing gaskets. Sliding door configurations lead volume due to their space efficiency in high-density commuter consists, while composite material adoption is accelerating as operators seek mass reduction for energy recovery systems. Rail operators represent the concentrated margin pool because lifecycle service contracts attach to initial procurement, whereas maintenance providers fragment across decentralized regional shops.
The EU MDR and EN 14752 standards enforce crashworthiness and emergency release protocols that elevate R&D thresholds for market entry. The EPA and FRA in the United States impose emissions-linked procurement rules that indirectly favor lighter door systems on new-build locomotives. China's GB standards and NMPA-equivalent rail safety certifications create parallel compliance tracks that fragment supplier testing budgets. Stakeholders must monitor how diverging national certification regimes reshape the economics of cross-border component sourcing.
Market Dynamics
Energy cost volatility across European steel-forging clusters is compressing supplier margins and forcing rail OEMs to requalify aluminum-intensive door architectures for new-build contracts. Deutsche Bahn and SNCF procurement teams now weight lifecycle energy consumption in technical scoring, redirecting engineering resources toward mass-reduction roadmaps.
Growth Catalysts
- Urban fleet expansion:Metro authorities in Germany and Japan are accelerating rolling stock procurement to address congestion. This creates pull-through demand for pneumatic door systems with platform screen door interoperability.
- EN 14752 standardization:The EU mandate for unified crashworthiness and emergency release protocols is consolidating supplier qualification pools. Door system vendors achieving certification capture disproportionate share of cross-border tenders.
- Composite material substitution:Extruded aluminum and fiber-reinforced polymer door panels are displacing stainless steel in high-frequency commuter consists. Mass reduction directly improves regenerative braking efficiency.
Market Restraints
- Aluminum alloy input volatility:European smelter curtailments have destabilized billet pricing for extruded door frames. Rail OEMs face margin compression when fixed-price contracts collide with spot market spikes.
- Supplier geographic concentration:Pneumatic actuator manufacturing clusters in southern Germany and northern Italy create single-source vulnerability. Disruption at any major forging facility cascades through multiple OEM final assembly lines.
- F-Gas Regulation compliance cost:The EU phase-down of fluorinated greenhouse gases affects door seal testing protocols. Suppliers must retool gasket validation laboratories to maintain market access.
Strategic Opportunities
- Indian domestic manufacturing:The country's PLI scheme for rail component production creates localized assembly incentives. Door system vendors establishing joint ventures with Indian forging houses access state-level metro procurement preferences.
- Platform screen door integration:Faiveley Transport's technology leadership in train-to-platform gap management creates white space for door control software convergence. Operators seek unified command systems reducing platform dwell time.
- GB standard alignment:China's rail safety certification track diverges from EN frameworks. Vendors bridging both compliance regimes capture contracts on export-oriented Chinese locomotive builds.
Industry Challenges
- Pneumatic-electronic control integration:Legacy door systems rely on mechanical interlocks that resist digital retrofit. Maintenance teams lack training in mechatronic diagnostics, extending fault isolation timelines.
- Fire resistance certification lag:New composite door panels require extended burn-test sequences under EN 45545. Development cycles stretch 18-24 months, delaying revenue recognition on next-generation contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Doors Market |
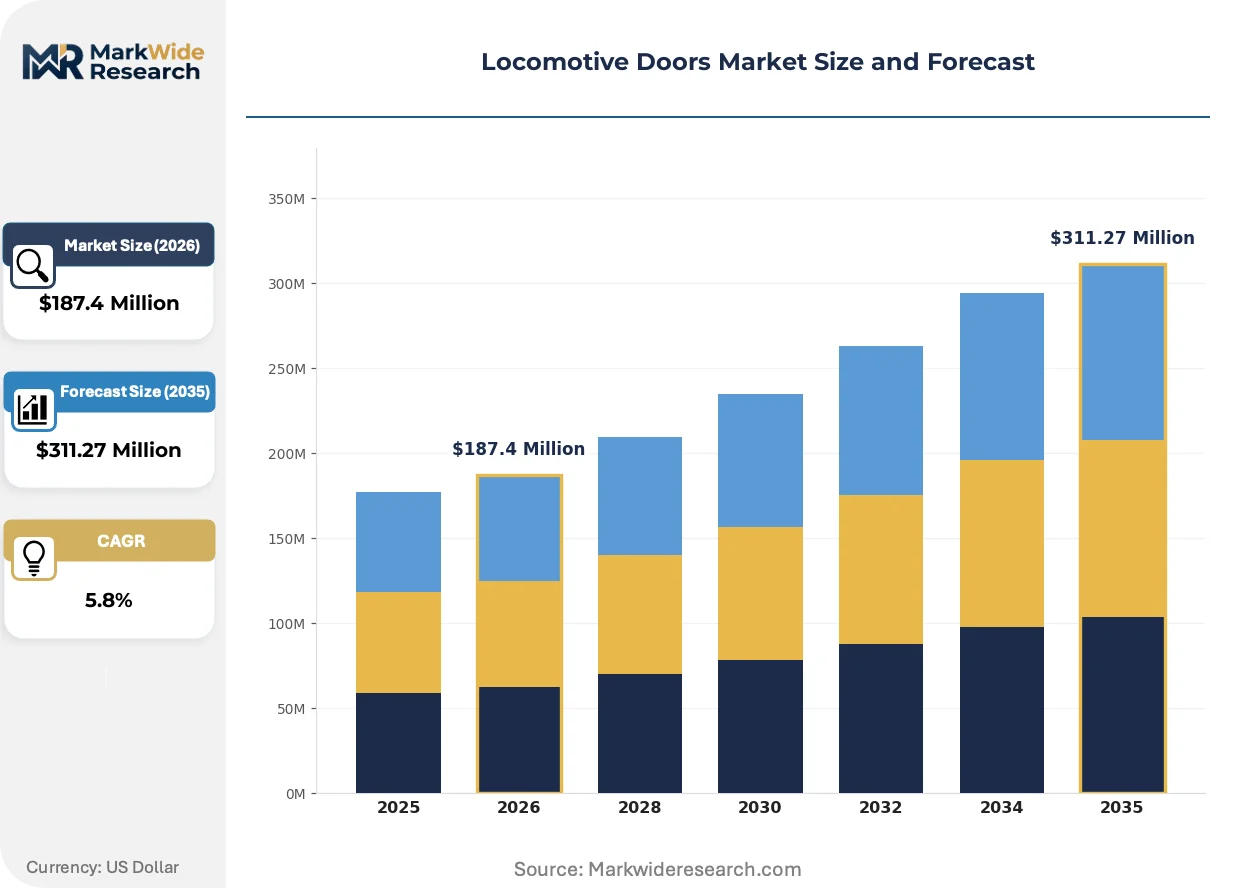
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Door Type: Sliding Doors, Hinged Doors, Bi-fold Doors, Removable Doors Material: Steel, Aluminum, Composite, Fiberglass End User: Rail Operators, Manufacturers, Maintenance Providers, Transit Authorities Technology: Manual Operation, Automatic Sensors, Remote Control, Safety Mechanisms |
| Companies Covered | Knorr-Bremse, Wabtec Corporation, Faiveley Transport, Nabtesco, Schaltbau, Fuji Electric, Yonggui, Nanjing Kangni Mechanical & Electrical, Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Doors Market Shifts & Advancements
Door system architectures are pivoting from standalone mechanical assemblies to integrated vehicle control nodes. This shift compresses supplier tiers and elevates software competency as a procurement screening criterion.
Sensor-embedded door edge technology is converging with obstacle detection algorithms to eliminate pinch-point incidents. Japanese commuter operators are mandating these systems on new metro deliveries. The technology is converging with platform screen door controllers, enabling synchronized gap management that reduces station dwell time by seconds per stop.
The EU F-Gas Regulation is tightening door seal material specifications to exclude high-global-warming-potential compounds. Industrial consequence includes accelerated R&D spending on rubber-composite gasket formulations. High-speed rail operators in France and Spain are most affected, driving qualification programs with specialty polymer suppliers.
Lifecycle service contracts are unbundling from initial equipment procurement in North American freight rail. Maintenance providers now compete separately for door system overhaul work. This pattern is most visible among Class I railroads seeking to reduce capital intensity in rolling stock ownership.
Locomotive Doors Market Segmentation
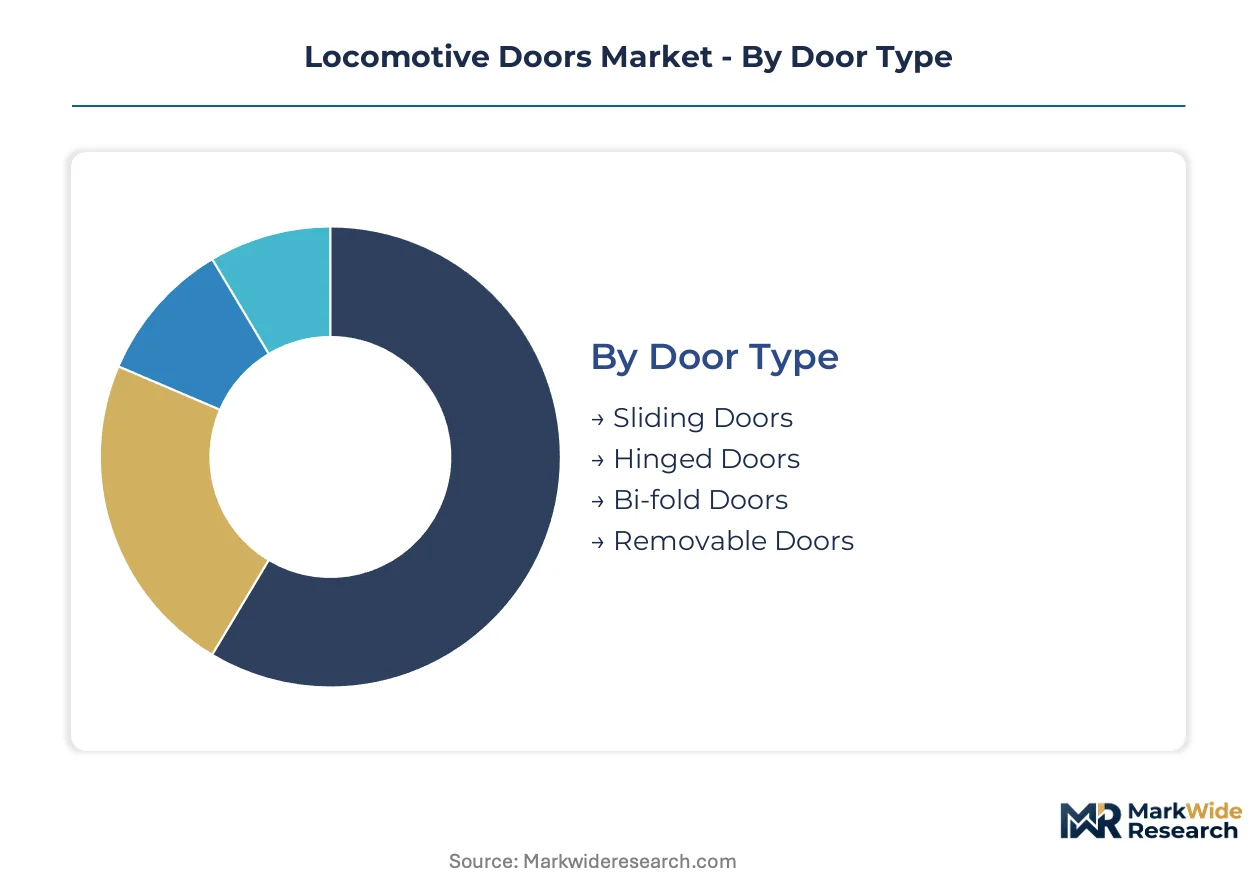
Door system procurement splits sharply between high-volume commuter deployments and premium long-distance configurations. Segmentation reveals how material choices and control architectures align with operator lifecycle cost models rather than upfront capital expenditure alone.
Door Type:
Sliding configurations dominate volume procurement while hinged systems retain premium positioning in specialized applications.
- Sliding Doors:Extruded aluminum frames with pneumatic actuation dominate high-density commuter consists in Germany and Japan. Deutsche Bahn and Tokyo Metro specifications favor these for platform screen door interoperability and minimal dwell time.
- Hinged Doors:Heavy-duty stainless steel construction serves locomotive cabs and maintenance access points where structural rigidity outweighs mass considerations. SNCF specifies these for TGV power car applications.
- Bi-fold Doors:Compact folding geometry addresses space-constrained heritage rail and narrow-gauge operations.
- Removable Doors:Tool-free detachment systems support freight locomotive maintenance protocols in North American Class I railroads.
Mature deployment sits with Sliding Doors. Newer deployment is concentrated in Bi-fold Doors for heritage fleet modernization.
Material:
Cost tiers separate forged steel foundations from aluminum and composite alternatives chasing regenerative braking efficiency.
- Steel:Forged and machined carbon steel delivers maximum impact resistance for freight locomotive applications. Energy cost volatility across European smelters has compressed supplier margins on alloy inputs.
- Aluminum:Extruded 6000-series alloys with anodized finishes achieve mass reduction targets in China's domestic high-speed programs. GB standard certification tracks diverge from EN frameworks, fragmenting supplier testing budgets.
- Composite:Fiber-reinforced polymer skins over aluminum honeycomb cores are displacing metal in French and Spanish high-speed fleets seeking energy recovery gains.
- Fiberglass:Molded thermoset panels serve auxiliary access hatches and non-structural applications where corrosion resistance matters.
Composite adoption is climbing the fastest as operators weight lifecycle energy consumption in technical scoring.
End User:
Rail operators concentrate margin capture through attached service contracts, while maintenance providers fragment regionally.
- Rail Operators:State-owned incumbents in China and India anchor procurement volume through domestic manufacturing programs. Lifecycle service contracts attach to initial equipment, creating recurring revenue streams.
- Manufacturers:CRRC, Alstom, and Siemens Mobility integrate door systems at final assembly, qualifying suppliers against platform-wide control architectures.
- Maintenance Providers:Decentralized regional shops in North American freight rail compete separately for overhaul work as Class I railroads unbundle service from procurement.
- Transit Authorities:Urban operators in Germany and Japan specify platform screen door interoperability, pulling through demand for synchronized control systems.
Procurement authority concentrates with Rail Operators. Technical specification influence is expanding fastest among Transit Authorities.
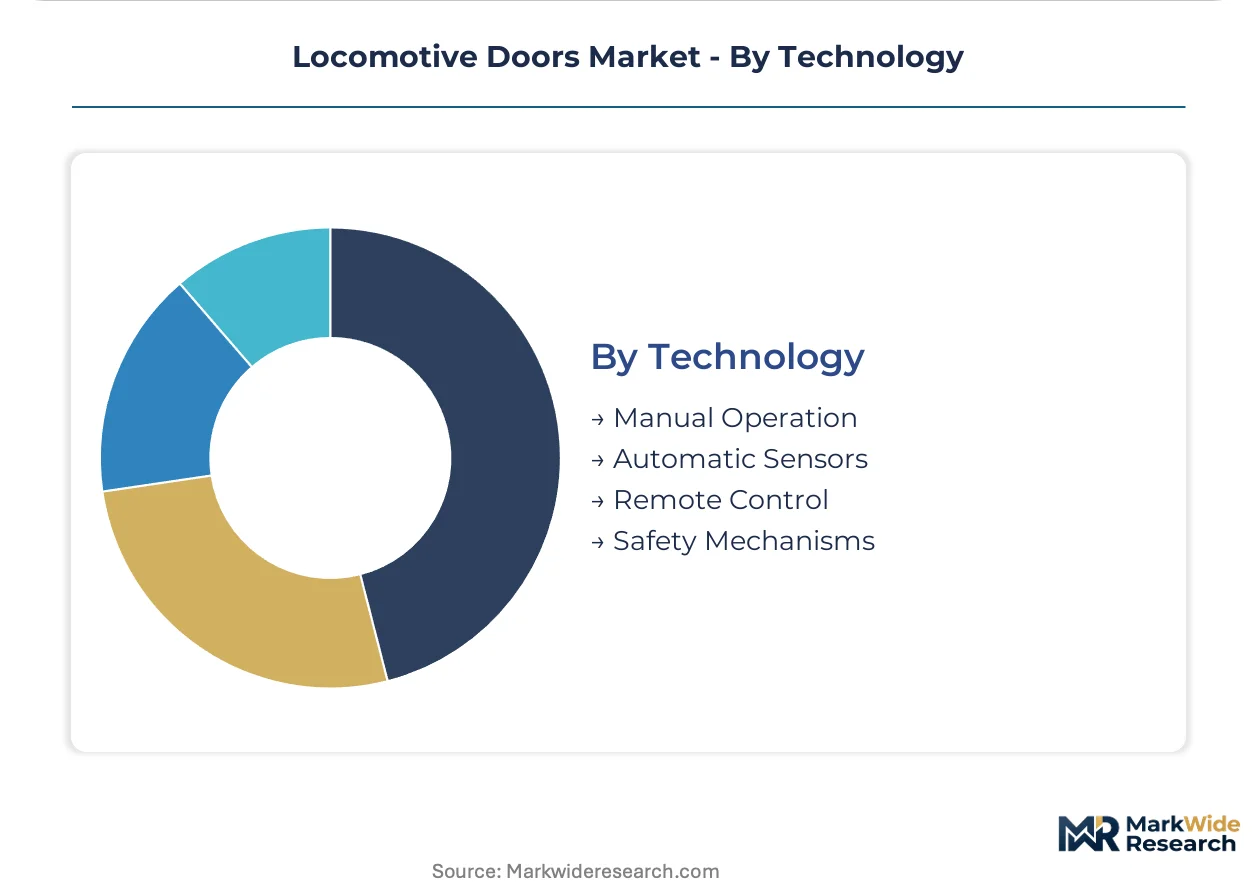
Technology:
Control architectures pivot from mechanical interlocks toward integrated vehicle nodes, elevating software competency as a screening criterion.
- Manual Operation:Mechanical linkages with pneumatic assist persist in freight and heritage applications where electronic complexity introduces failure modes.
- Automatic Sensors:Infrared and pressure-sensitive edge detection systems are mandated by Japanese commuter operators on new metro deliveries. Obstacle detection algorithms eliminate pinch-point incidents.
- Remote Control:Centralized door management from driver cabs or platform control rooms supports unmanned train operation trials in Singapore and Dubai.
- Safety Mechanisms:EN 14752-compliant emergency release protocols and fire resistance ratings under EN 45545 extend development cycles for next-generation systems.
Automatic Sensors represent the established baseline. Remote Control deployment is expanding most quickly in greenfield metro systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European steel-forging clusters in southern Germany and northern Italy anchor supplier economics for extruded aluminum door frames, while Chinese smelter capacity shapes input costs for Asia-Pacific procurement.
Germany
Deutsche Bahn's metro fleet expansion drives pneumatic door system procurement with platform screen door interoperability requirements. The EU F-Gas Regulation tightens seal material specifications, forcing retooling at gasket validation laboratories. Munich and Nuremberg forging clusters concentrate actuator manufacturing, creating single-source vulnerability for OEM final assembly lines.
China
Domestic high-speed rail programs accelerate demand for mass-reduced door architectures in regenerative braking systems. GB standards and NMPA-equivalent rail safety certifications create parallel compliance tracks that fragment supplier testing budgets. CRRC's platform-wide control architectures in Changzhou and Qingdao qualify suppliers against integrated brake-door specifications.
Japan
Tokyo Metro specifications favor sliding door configurations for minimal dwell time in high-density commuter consists. METI mandates sensor-embedded obstacle detection systems on new metro deliveries. Osaka and Nagoya industrial corridors host pneumatic actuator clusters serving export-oriented rolling stock builds.
India
State-level metro procurement in Maharashtra and Delhi-NCR pulls through demand for localized door assembly under the PLI scheme for rail components. BIS certification requirements diverge from EN frameworks, extending qualification timelines for foreign vendors. Joint ventures with Indian forging houses in Gujarat and Tamil Nadu access domestic manufacturing incentives.
United States
Class I railroads unbundle lifecycle service contracts from initial equipment procurement, creating separate competition for door system overhaul work. EPA and FRA emissions-linked procurement rules favor lighter door systems on new-build locomotives. Chicago and Pittsburgh maintenance hubs fragment aftermarket provider geography across decentralized regional shops.
Locomotive Doors Market Competitive Landscape
Global majors compete with regional champions across certification regimes and control platform integration. The supplier base concentrates around brake-door system convergence and platform screen door interoperability, with tiered qualification pools emerging from EN 14752 standardization. Three archetypes dominate: integrated vehicle control platform vendors, specialized door mechanism fabricators, and regional forging houses with captive actuator capacity. Competitive moves center on joint venture formation for local manufacturing access and technology licensing for control software convergence.
Within the integrated platform tier, Knorr-Bremse and Wabtec Corporation exemplify global positioning through brake-door control integration. Faiveley Transport occupies a specialist position in platform screen door technology leadership. Among Asia-Pacific fabricators, Nabtesco and Fuji Electric represent regional champions with established JIS certification tracks. Chinese suppliers including Yonggui and Nanjing Kangni Mechanical & Electrical sit within the domestic manufacturing expansion archetype, leveraging PLI-aligned joint ventures. Schaltbau and Ingersoll Rand exemplify diversified industrial conglomerates with rail component divisions.
| Leading Market Players |
|---|
| Knorr-Bremse |
| Wabtec Corporation |
| Faiveley Transport |
| Nabtesco |
| Schaltbau |
| Fuji Electric |
| Yonggui |
| Nanjing Kangni Mechanical & Electrical |
| Ingersoll Rand |
| Others |
Supply & Pricing Matrix
State-owned rail operators in China and India anchor procurement volume through domestic manufacturing programs, concentrating pricing power with vendors who bundle lifecycle service contracts into initial equipment sales. This buyer concentration forces tiered pricing structures that separate EN 14752-certified platform integrators from regional forging houses competing on spot aluminum billet costs.
Pricing Analysis
Warranty and service-bundling terms diverge sharply between rail operator procurement and aftermarket overhaul contracts. Three-tier pricing structure across premium, standard, and economy levels reflects EN 14752 certification grade and pneumatic-electronic control integration depth. Pricing pressure stems from aluminum alloy input volatility as European smelter curtailments destabilize billet costs for extruded door frames. Maintenance providers in North American freight rail exhibit highest price sensitivity due to unbundled procurement models, while state-backed operators in Asia-Pacific absorb premium pricing for platform screen door interoperability.
Supply Chain Analysis
Extruded aluminum billet supply rests on Chinese smelter capacity and European forging clusters in southern Germany and northern Italy. Pneumatic actuator manufacturing draws from specialty steel forgings and rubber-composite gasket formulations. Single-source vulnerability concentrates at Munich and Nuremberg forging facilities where disruption cascades through multiple OEM final assembly lines. Distribution runs through captive service networks for integrated platform vendors and decentralized regional shops for aftermarket maintenance providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The locomotive doors market sits in a technology-transition phase as sensor-embedded obstacle detection systems displace legacy mechanical interlocks, elevating software competency as a procurement screening criterion.
For Market Incumbents: Lock in platform screen door interoperability contracts with Deutsche Bahn and Tokyo Metro to defend against emerging Chinese suppliers leveraging GB standard alignment. Deepen backward integration into aluminum extrusion capacity to offset European smelter pricing volatility. Certification investment in EN 45545 fire resistance protocols creates switching costs that protect premium positioning. For New Entrants and Emerging Players: Regional forging houses in Gujarat and Tamil Nadu offer the most penetrable entry point through joint ventures accessing India's PLI scheme for rail component production. Target platform screen door control software convergence as white space where Faiveley Transport's technology leadership has not fully extended to mid-tier operators. Partner with CRRC's Changzhou and Qingdao facilities for qualification against integrated brake-door specifications. For Investors and Strategic Acquirers: The window for entry favors specialized door mechanism fabricators with JIS certification tracks and established relationships with Japanese commuter operators. Long-term viability hinges on mechatronic diagnostic capabilities as maintenance teams face training gaps in pneumatic-electronic control integration. Watch EN 14752 certification consolidation as the inflection signal for supplier qualification pool narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Screen Door Integration | Unified command systems reduce station dwell time for Deutsche Bahn and Tokyo Metro. |
| Composite Material Qualification | Fiber-reinforced polymer panels meet EN 45545 fire resistance for French TGV fleets. |
| Joint Venture Formation | Indian PLI-aligned partnerships access state-level metro procurement preferences. |
| GB Standard Alignment | Dual certification with EN frameworks captures export-oriented Chinese locomotive builds. |
| Lifecycle Service Unbundling | Separate overhaul competition targets North American Class I railroad maintenance shops. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with rail OEM procurement teams, maintenance directors at Class I railroads, pneumatic actuator plant managers, and transit authority engineering heads combined with secondary validation from UNIFE sector reports, ECHA substance registrations, and import-export databases. Bottom-up supplier capacity modeling and top-down operator fleet expansion plans underwent cross-triangulation to reconcile volume estimates.
Granularity-level modeling addressed door type, material grade, control technology architecture, and end-user procurement authority across national regulatory clusters. CAGRs derived from fitted growth curves applied to fleet replacement cycles and metro expansion timelines. Industry-specific forecast inputs included Deutsche Bahn's rolling stock procurement schedules and China's high-speed rail manufacturing targets.
Several conditions sit outside the modeled scope, including sudden regulatory shifts in F-Gas phase-down timelines and geopolitical disruptions to aluminum billet trade flows. Forecasts reflect assumptions around EN 14752 certification adoption rates and composite material burn-test completion schedules. A small set of named triggers warrants ongoing watch: European smelter curtailment extensions, BIS certification divergence from EN frameworks, and platform screen door interoperability mandate expansions beyond Japan and Germany.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Solar Powered Train Market
Railway
Railway Telematics Market
Railway
Global Train Lighting Market
Railway
Rail Maintenance Management System Market
Railway
Railway Track Market
Railway
Rail Bellows Market
Railway
Smart Railways Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Gangway for Railway Vehicles Market
Railway
Railway Management System Market
Railway
Automatic Train Operation System Market
Railway
Rail Composites Market
Railway
Global Smart Locomotive Market
Railway
Trams Market
Railway
Railway Window Market
Railway
Railway Draft Gears Market