
 Connected Rail Market | 2026-2036
Connected Rail Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Rail Market Analysis
Channel partnerships between telecom infrastructure vendors and rolling stock OEMs is rewriting how connectivity solutions reach railway operators. Nokia leverages its private wireless portfolio to anchor 5G rail corridors across European testbeds. Siemens Mobility sustains deep integration between signaling hardware and cloud analytics platforms. Huawei Technologies competes aggressively on price for digital interlocking and passenger Wi-Fi deployments in Southeast Asia and Latin America.
Connected rail encompasses sensor networks, onboard computing platforms, and real-time data pipelines that monitor train health, track conditions, and passenger flow with sub-second latency requirements. The primary purpose is to optimize asset utilization, prevent catastrophic failures, and synchronize multimodal logistics chains. Predictive Maintenance applications capture disproportionate investment as operators prioritize uptime over incremental speed gains. IoT sensor layers remain the foundational technology spend, though AI inference at the edge is displacing centralized cloud-only architectures for safety-critical decisions.
The Federal Railroad Administration mandates positive train control compliance, while the EU Agency for Railways enforces ERTMS/ETCS interoperability standards that dictate equipment procurement across member states. India's Ministry of Railways and CEA guidelines shape electrification and communication system investments for freight corridors. Stakeholders must monitor how spectrum allocation decisions by national regulators constrain or enable private 5G rail networks before committing to vendor-specific communication architectures.
Market Dynamics
The migration from centralized cloud architectures to edge AI inference is compressing decision latency for safety-critical rail operations. This structural shift reconfigures how operators allocate capital between onboard computing, trackside infrastructure, and backhaul networks.
Growth Catalysts
- EU F-Gas Regulation:Mandates for energy-efficient HVAC retrofits in rolling stock accelerate demand for sensor-integrated climate control systems across European corridors.
- Urban metro densification:Asian megacities deploy connected signaling to maximize throughput on constrained rights-of-way.
- Predictive maintenance protocols:IoT sensor layers enable condition-based asset replacement, prioritizing uptime over scheduled interventions.
Market Restraints
- Spectrum allocation bottlenecks:National regulators delay private 5G rail network authorizations, freezing vendor commitment timelines.
- Input cost volatility:Semiconductor shortages and rare earth magnet price swings disrupt rolling stock electronics procurement cycles.
- Interoperability mandates:ERTMS/ETCS compliance requirements fragment procurement specifications across EU member states.
Strategic Opportunities
- Indian freight corridors:Dedicated Freight Corridor electrification and communication system investments create greenfield deployment windows.
- Digital interlocking convergence:Integration of 5G private wireless with CBTC architectures opens retrofit markets in Southeast Asia.
- Passenger experience monetization:Wi-Fi and real-time journey analytics enable ancillary revenue streams beyond base fares.
Industry Challenges
- Legacy system integration:Analog signaling infrastructure requires phased migration paths that extend deployment timelines.
- Edge AI certification:Safety validation for autonomous decision systems lacks harmonized standards across jurisdictions.
- Specialized workforce scarcity:Rail-specific cybersecurity and radio frequency engineering skills concentrate in incumbent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Rail Market |
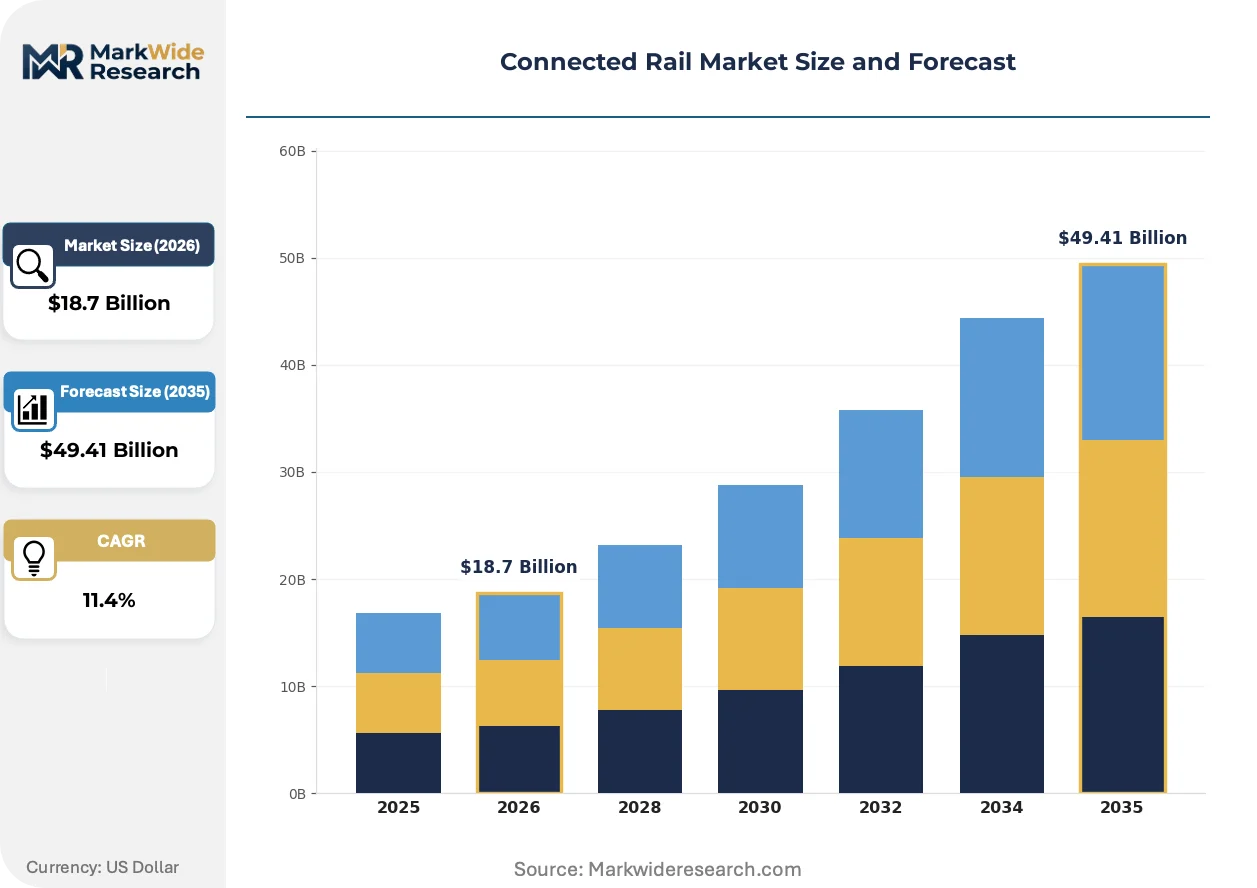
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Cloud Computing, AI, Big Data Application: Fleet Management, Passenger Information Systems, Predictive Maintenance, Security Solutions End User: Railway Operators, Infrastructure Providers, Service Providers, Logistics Companies Solution: Asset Tracking, Communication Systems, Safety Management, Energy Management |
| Companies Covered | Wabtec Corporation, Cisco Systems, Inc., Siemens Mobility, Nokia Corporation, IBM Corporation, Alstom SA, Huawei Technologies Co., Ltd., Robert Bosch GmbH, Hitachi Rail Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Rail Market Emerging Trajectories
Edge computing architectures are redistributing intelligence from centralized data centers to trackside and onboard nodes. This inversion challenges established vendor relationships and procurement patterns.
AI inference engines deployed at the network edge process sensor telemetry within sub-second windows for collision avoidance and track anomaly detection. Japanese Shinkansen operators and European high-speed networks pilot these systems for real-time braking optimization. Cloud-only analytics is rendering obsolete for safety-critical functions as latency requirements harden.
The EU Agency for Railways enforces updated ERTMS/ETCS interoperability specifications that mandate backward-compatible equipment interfaces. Rolling stock OEMs must redesign onboard control units to satisfy multi-country deployment contracts. Freight corridors spanning Germany, France, and Italy absorb disproportionate compliance engineering resources.
Performance-based maintenance contracts now tie vendor payments to availability metrics rather than spare part deliveries. Indian Railways and select Southeast Asian operators lead this transition. Mumbai Metro and Bangkok's suburban networks have unbundled service provision from hardware procurement, compressing supplier margins while extending contract durations.
Connected Rail Market Segmentation
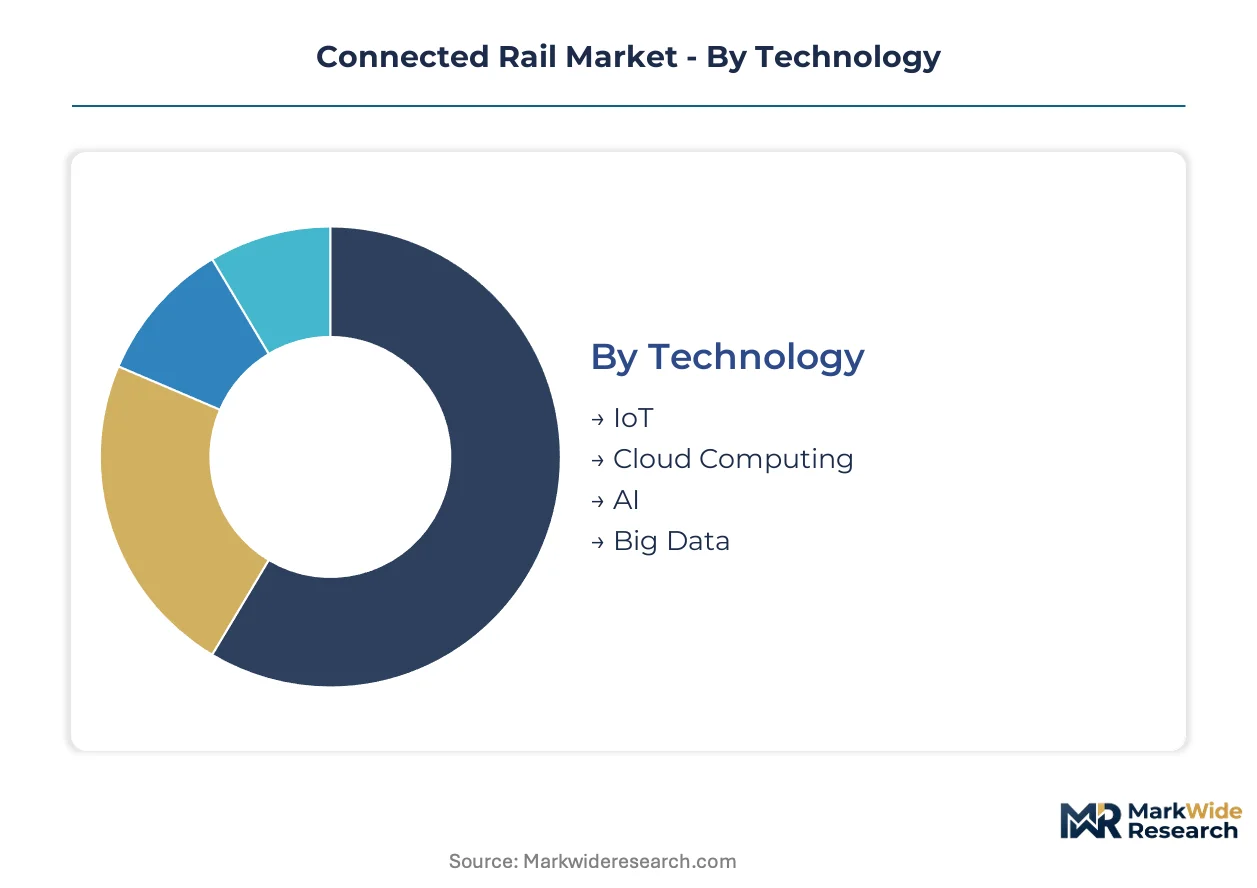
Segmentation in connected rail reveals how capital cycles differ dramatically across technology layers. Procurement timelines for safety-critical hardware stretch across decades, while software refresh cycles compress to 3-5 years. Understanding these mismatches shapes vendor strategy and operator investment sequencing.
Technology:
IoT sensors turn over fastest as edge devices require frequent calibration and replacement. Cloud platforms refresh slowest due to multi-year enterprise contracts and migration inertia. AI and Big Data occupy the middle ground, with model retraining cycles driving recurring expenditure.
- IoT:Distributed sensor networks capture vibration, temperature, and position telemetry from rolling stock and track infrastructure. Indian Dedicated Freight Corridor and Japanese Shinkansen modernization programs deploy these layers most intensively, driven by F-Gas Regulation mandates for energy-efficient monitoring systems.
- AI:Machine learning models process edge inference for collision avoidance and predictive fault detection. European high-speed networks and Asian metro operators prioritize this segment to compress decision latency below one second for safety-critical functions.
- Cloud Computing:Centralized data lakes aggregate historical performance metrics and enable long-term trend analysis. Procurement concentrates among freight corridors requiring multimodal logistics synchronization across extended geographic spans.
- Big Data:Analytics platforms correlate passenger flow patterns with asset utilization to optimize scheduling. Urban metro densification in Asia-Pacific drives adoption where constrained rights-of-way demand maximum throughput extraction.
IoT dominates installed base. AI is where expansion concentrates.
Application:
Cost tiers separate mission-critical safety systems from passenger-facing amenities. Predictive Maintenance commands premium pricing due to uptime guarantees. Fleet Management spreads across standard and economy tiers depending on fleet scale and operator sophistication.
- Predictive Maintenance:Condition-based monitoring replaces scheduled interventions using vibration analysis, thermal imaging, and acoustic sensors. Railway operators in India and Japan prioritize this application to minimize catastrophic failure costs and extend asset lifecycles.
- Fleet Management:Real-time location tracking and route optimization synchronize rolling stock deployment with demand fluctuations. Logistics companies and freight operators deploy these systems across North American and European corridors to improve asset turns.
- Passenger Information Systems:Digital displays and mobile applications deliver real-time arrival data and service disruption alerts. Urban metro networks in Asia-Pacific deploy these most aggressively to manage ridership expectations during high-frequency operations.
- Security Solutions:Video surveillance, access control, and intrusion detection protect critical infrastructure. Infrastructure providers concentrate investment here following EU Agency for Railways safety mandates and national terrorism prevention protocols.
Predictive Maintenance captures disproportionate investment. Passenger Information Systems are climbing the fastest.
End User:
Volume concentration varies by contract size and decision-making centralization. Railway Operators consolidate the largest individual procurements. Service Providers fragment across numerous smaller engagements supporting legacy system integration.
- Railway Operators:National and regional rail authorities specify integrated connected rail architectures spanning signaling, telecommunications, and onboard systems. India's Ministry of Railways and European high-speed operators drive the largest deployment scales.
- Infrastructure Providers:Track owners and station operators deploy sensor networks and communication backbone equipment. EU F-Gas Regulation compliance requirements accelerate their investment in energy-efficient HVAC and climate monitoring retrofits.
- Service Providers:Systems integrators and maintenance contractors deliver implementation and ongoing support services. Southeast Asian and Latin American markets rely heavily on these intermediaries due to localized technical expertise gaps.
- Logistics Companies:Freight rail customers demand visibility integration with their own supply chain management platforms. Dedicated Freight Corridor operators in India and intermodal shippers in Germany prioritize these data interchange capabilities.
Railway Operators dominate installed base. Logistics Companies are where expansion concentrates.
Solution:
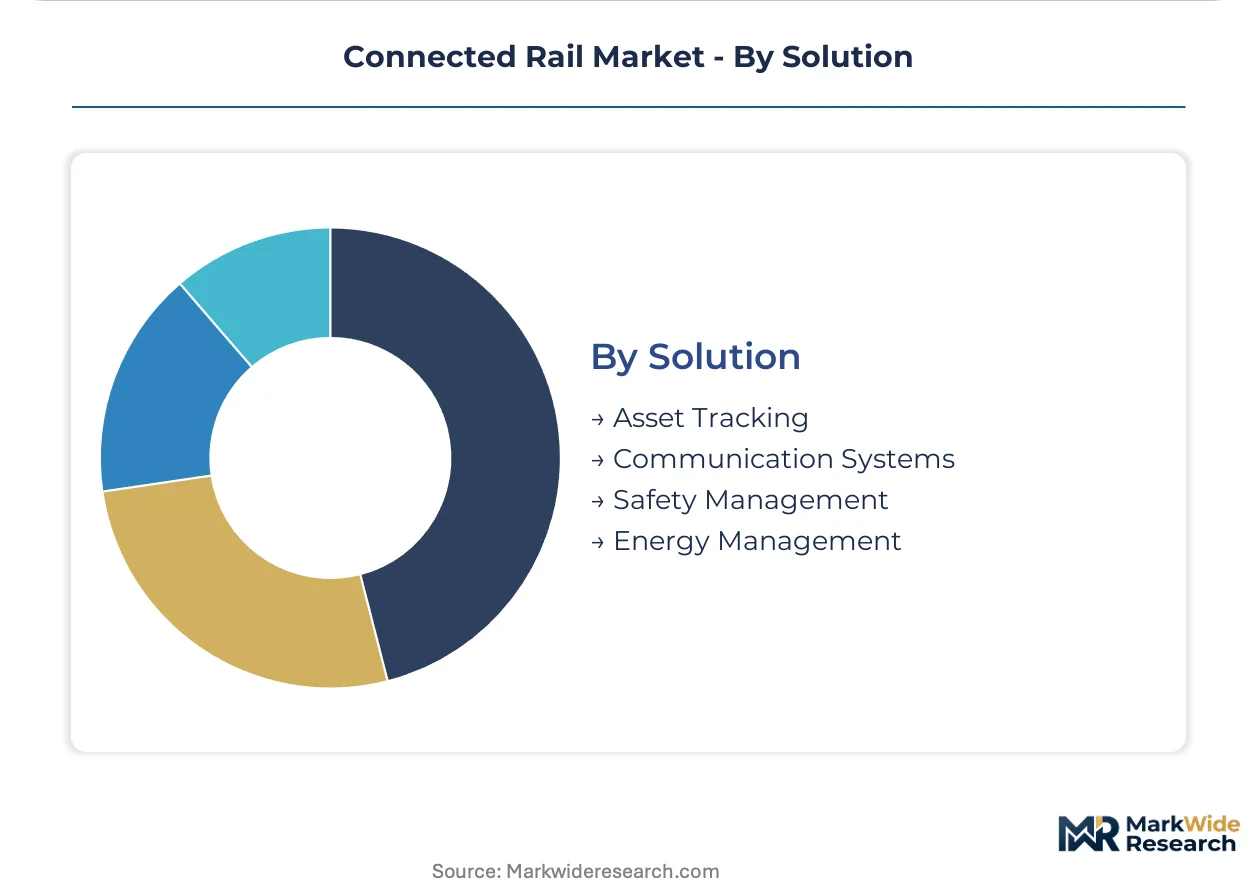
Margin structures reflect certification requirements and switching costs. Safety Management commands the highest margins due to regulatory compliance burdens. Asset Tracking competes most intensely on price with commoditized hardware options.
- Safety Management:Positive train control, automatic train protection, and emergency braking systems enforce operational limits. Federal Railroad Administration mandates in the United States and ERTMS/ETCS interoperability standards in Europe dictate procurement specifications.
- Communication Systems:Private 5G networks, TETRA, and legacy GSM-R provide voice and data connectivity across corridors. Spectrum allocation decisions by national regulators constrain deployment timelines and vendor selection flexibility.
- Asset Tracking:RFID, GPS, and beacon technologies monitor rolling stock and cargo location throughout transit networks. Freight operators deploy these solutions most widely to satisfy customer visibility requirements and insurance documentation needs.
- Energy Management:Regenerative braking optimization, substation monitoring, and consumption analytics reduce operational costs. EU F-Gas Regulation and national electrification guidelines in India shape investment priorities here.
Safety Management dominates installed base. Communication Systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Railroad Administration anchors North American deployment timelines through positive train control mandates that dictate procurement specifications across Class I freight networks. Asian megacities and European high-speed corridors concentrate investment in sensor-integrated signaling and private 5G rail networks.
United States
Class I freight operators deploy positive train control retrofits across 140,000 route miles under Federal Railroad Administration enforcement deadlines. The Infrastructure Investment and Jobs Act directs capital toward Amtrak corridor modernization and freight rail safety systems. Chicago's rail hub concentrates intermodal terminal automation investments where sensor networks synchronize container movements.
Germany
Deutsche Bahn accelerates ERTMS/ETCS Level 3 deployment across the Rhine-Alpine freight corridor to eliminate legacy signaling bottlenecks. The EU F-Gas Regulation mandates HVAC retrofit schedules that drive rolling stock sensor integration. Stuttgart's manufacturing belt hosts systems integrators delivering digital interlocking for cross-border freight routes into France and Switzerland.
India
The Dedicated Freight Corridor Corporation electrifies 2,843 kilometers of dedicated track between Delhi and Mumbai under Ministry of Railways oversight. CEA guidelines shape communication backbone specifications for freight operations separate from passenger networks. The Khurja-Bhaupur section deploys European Train Control System Level 2 signaling as the reference implementation for corridor-wide rollout.
Japan
East Japan Railway Company modernizes Shinkansen signaling architectures to accommodate autonomous train operation trials on Tohoku and Joetsu corridors. METI funding supports edge AI inference systems for real-time braking optimization at 320 km/h operating speeds. Nagoya's industrial corridor supplies onboard computing platforms for N700S series rolling stock.
United Kingdom
Network Rail's Digital Railway program replaces legacy signaling with European Train Control System infrastructure across the Great Western Main Line and Midland Main Line. The Department for Transport mandates interoperability specifications that constrain vendor selection for Thameslink and Crossrail extensions. Derby's rail supply cluster manufactures onboard control units compliant with multi-country deployment contracts.
Connected Rail Market Vendor Landscape
Telecom infrastructure specialists and rolling stock OEMs split the market through divergent channel strategies that reshape how connectivity solutions reach railway operators. The vendor base concentrates around three strategic archetypes: private wireless network providers, integrated signaling-hardware vendors, and cloud analytics platform operators. Consolidation pressures intensify as spectrum allocation decisions force long-term vendor commitments. Strategic partnerships between telecom vendors and rolling stock manufacturers displace direct procurement relationships.
Within the integrated systems tier, Siemens Mobility and Alstom SA exemplify European rolling stock OEMs with deep signaling-hardware portfolios. Nokia Corporation anchors the private wireless network provider archetype through 5G rail corridor testbeds. These three companies occupy positions that reflect the market's structural division between communication infrastructure and rolling stock integration capabilities.
| Leading Market Players |
|---|
| Wabtec Corporation |
| Cisco Systems, Inc. |
| Siemens Mobility |
| Nokia Corporation |
| IBM Corporation |
| Alstom SA |
| Huawei Technologies Co., Ltd. |
| Robert Bosch GmbH |
| Hitachi Rail Limited |
| Others |
Supply Flow & Price Mechanics
Semiconductor fabrication concentration in Taiwan and South Korea feeds directly into margin capture by rolling stock OEMs who control onboard computing platform certification. Rare earth magnet supply from Chinese processors shapes permanent motor pricing for traction systems, compressing tier-two sensor vendors who lack backward integration into magnet sourcing.
Pricing Analysis
Asian procurement contracts for private 5G rail networks undercut European pricing by 15-25% due to lower spectrum licensing costs and domestic equipment manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates safety-certified signaling hardware from passenger Wi-Fi commoditized hardware and unbranded sensor components. Cost compression in economy-tier IoT devices is intensifying because Chinese vendors flood Southeast Asian markets with uncertified alternatives. Freight operators exhibit highest price sensitivity due to thin operating margins, while high-speed passenger rail accepts premium pricing for sub-second latency guarantees.
Supply Chain Analysis
Export-control regimes limiting 5G base station and AI chip flows to named rail operators constrain vendor selection flexibility across Indian and Southeast Asian corridors. Manufacturing concentrates in China for sensor assemblies, Germany for signaling control units, and Japan for precision braking components. Supply chains rest on gallium nitride semiconductors, rare earth permanent magnets, and fiber-optic gyroscopes. Single-source vulnerability around Taiwanese foundry capacity for safety-critical processors threatens deployment timelines. Distribution runs through systems integrators who bundle hardware procurement with long-term maintenance service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based maintenance contracts are expanding faster than rolling stock hardware sales as Indian Railways and Southeast Asian metros unbundle service provision from capital procurement. Recurring revenue from uptime guarantees now exceeds upfront equipment margins for integrated vendors.
For Market Incumbents: Harden signaling-hardware certification portfolios against price-aggressive Chinese entrants by accelerating ERTMS/ETCS Level 3 compliance engineering across cross-border European corridors. Deepen vertical integration into edge AI inference chip design to escape foundry allocation bottlenecks. Channel control through exclusive telecom infrastructure partnerships with Nokia and Ericsson limits substitution risk from Huawei in spectrum-constrained markets. For New Entrants and Emerging Players: Latin American freight corridors present the most penetrable white space as legacy analog signaling requires phased digital migration with localized technical support gaps. Target digital interlocking retrofits in Southeast Asian metro networks where incumbent vendors lack price-competitive CBTC-5G convergence solutions. Partner with national telecom regulators as spectrum allocation advisors to anchor private wireless network deployment contracts before hardware procurement decisions finalize. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rail cybersecurity specialists who consolidated fragmented endpoint protection vendors across European infrastructure providers. Five-to-ten-year viability hinges on recurring software maintenance attach rates rather than one-time hardware sales. Signal to monitor: Indian Dedicated Freight Corridor electrification tender awards as volume inflection for communication backbone equipment vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Platform Integration | Compresses decision latency below one second for Shinkansen collision avoidance systems. |
| Private 5G Network Deployment | Enables CBTC convergence for Bangkok Metro and Mumbai suburban corridor retrofits. |
| Predictive Maintenance Service Unbundling | Ties vendor payments to availability metrics across Indian Railways freight operations. |
| ERTMS/ETCS Certification Investment | Unlocks cross-border procurement contracts spanning Germany-France-Italy freight corridors. |
| Rare Earth Magnet Backward Integration | Secures permanent motor supply for traction systems against Chinese processor volatility. |
Methodological Framework
A standing panel of rolling stock procurement directors, railway operator signaling engineers, telecom infrastructure vendor account managers, and national regulator spectrum allocation officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Agency for Railways ERTMS deployment databases, Federal Railroad Administration PTC compliance filings, Indian Ministry of Railways tender announcements, and semiconductor trade flow customs records. Bottom-up sensor deployment counts triangulated against top-down rolling stock OEM revenue segmentation.
Scenario-bracketing around spectrum allocation timelines and F-Gas Regulation retrofit deadlines bounded high and low growth paths across the projection horizon. Segmentation dimensions modeled include technology layer refresh cycles, application criticality tiers, end-user contract centralization, and solution certification requirements. CAGRs derived from logistic diffusion curves fitted to historical ERTMS adoption patterns and edge AI pilot program scaling rates. Forecast inputs incorporated Dedicated Freight Corridor electrification milestones and Japanese Shinkansen autonomous operation trial schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed vendors to undercut European pricing by 40% would shift outcomes toward faster technology commoditization. Material shifts in EU F-Gas Regulation enforcement stringency or Indian spectrum allocation acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Hydrogen Fuel Cell Train Market
Railway
Train Exterior Lighting Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Train HVAC Market
Railway
Locomotive Maintenance Market
Railway
India Rail Freight Transport Market
Railway
Rail Seat Market
Railway
Railroad Tie Market
Railway
Railroads Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Railway Overhead Catenary System Market
Railway
Locomotive Market
Railway
Tugger Trains Market
Railway
Solar Train Market
Railway
40-Foot Platform Wagons Market
Railway
Railway Window Market