
 Gangway for Railway Vehicles Market | 2026-2036
Gangway for Railway Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Gangway for Railway Vehicles Market Insights
Composite-to-metal bonding technology is narrowing the performance gap between traditional steel gangways and lightweight alternatives, forcing recalibration across supplier engineering roadmaps. HÜBNER GmbH & Co. KG leverages its German manufacturing base to sustain premium positioning in European high-speed contracts. Dellner Couplers anchors its competitive stance through integrated coupler-gangway systems that reduce interface complexity for rail OEMs. KTK Group dominates domestic supply chains for China's expanding metro and intercity networks.
A gangway for railway vehicles is a flexible, sealed passageway connecting adjacent railcars, typically constructed with corrugated bellows, structural frames, and wear-resistant floor panels to maintain continuous passenger or crew access during train movement. The assembly must withstand repeated compression-extension cycles, fire-resistance ratings, and acoustic isolation thresholds specified by rolling stock operators. Collapsible gangways lead volume in metro and commuter fleets where platform gap variability demands adaptive geometries. Composite materials represent the fastest-expanding material category as operators pursue weight reduction for energy efficiency targets. Rail OEMs constitute the most concentrated end-user segment, capturing direct specification authority over gangway architecture during new-build programs.
EN 15227 crashworthiness mandates from the European Committee for Standardization and China's GB/T rail vehicle safety standards govern gangway structural integrity, fire behavior, and passenger evacuation pathways, creating compliance costs that filter smaller fabricators from tender participation. The US Federal Railroad Administration (FRA) and India's Ministry of Railways enforce distinct coupling interface standards that shape regional product form factors and limit cross-certification economies. Stakeholders must monitor divergence between regional fire-smoke-toxicity protocols and emerging modular platform strategies that could unify gangway specifications across multinational fleet orders.
Market Dynamics
Composite-to-metal bonding advances are compressing engineering cycles and forcing tier-one suppliers to requalify entire product lines against crashworthiness benchmarks that previously favored steel-intensive designs.
Growth Catalysts
- EN 15227 crashworthiness mandates:European operators must replace legacy gangway assemblies by specified deadlines, creating replacement demand across Deutsche Bahn, SNCF, and Trenitalia fleets.
- China's Dedicated Freight Corridor expansion:Heavy-haul freight operators require reinforced gangway systems capable of withstanding 25-ton axle loads and extended duty cycles.
- Carbon fiber reinforced polymer (CFRP) floor panels:Weight reductions of 30-40% versus aluminum enable energy efficiency gains that operators monetize through reduced electricity consumption.
Market Restraints
- Specialized elastomer supply concentration:EPDM bellows membranes depend on petrochemical feedstocks from Gulf Coast refiners, exposing fabricators to input cost volatility.
- Crash test certification costs:Full-scale EN 15227 validation runs exceed smaller European fabricators' annual R&D budgets, consolidating tender participation.
- Legacy fleet interoperability:India's ICF coaches and older Chinese Type 22 rolling stock use non-standard coupling interfaces that resist modular gangway retrofits.
Strategic Opportunities
- India's suburban electrification:Mumbai Metro, Delhi MRTS, and Bengaluru Namma Metro expansion programs specify fire-rated gangway assemblies with 15-minute integrity ratings.
- Digital twin integration:Predictive maintenance algorithms using vibration sensor data enable condition-based gangway replacement rather than calendar-based intervals.
- EU Green Deal procurement incentives:Lifecycle carbon scoring in tender evaluation favors suppliers with recycled aluminum content and regional manufacturing footprints.
Industry Challenges
- Welding technician scarcity:TIG certification for aluminum-composite hybrid joints requires 18-month training pipelines that outpace hiring needs in Germany and Poland.
- Multi-standard certification timelines:Simaneous EN 15227, GB/T, and FRA compliance testing extends product launch cycles by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gangway for Railway Vehicles Market |
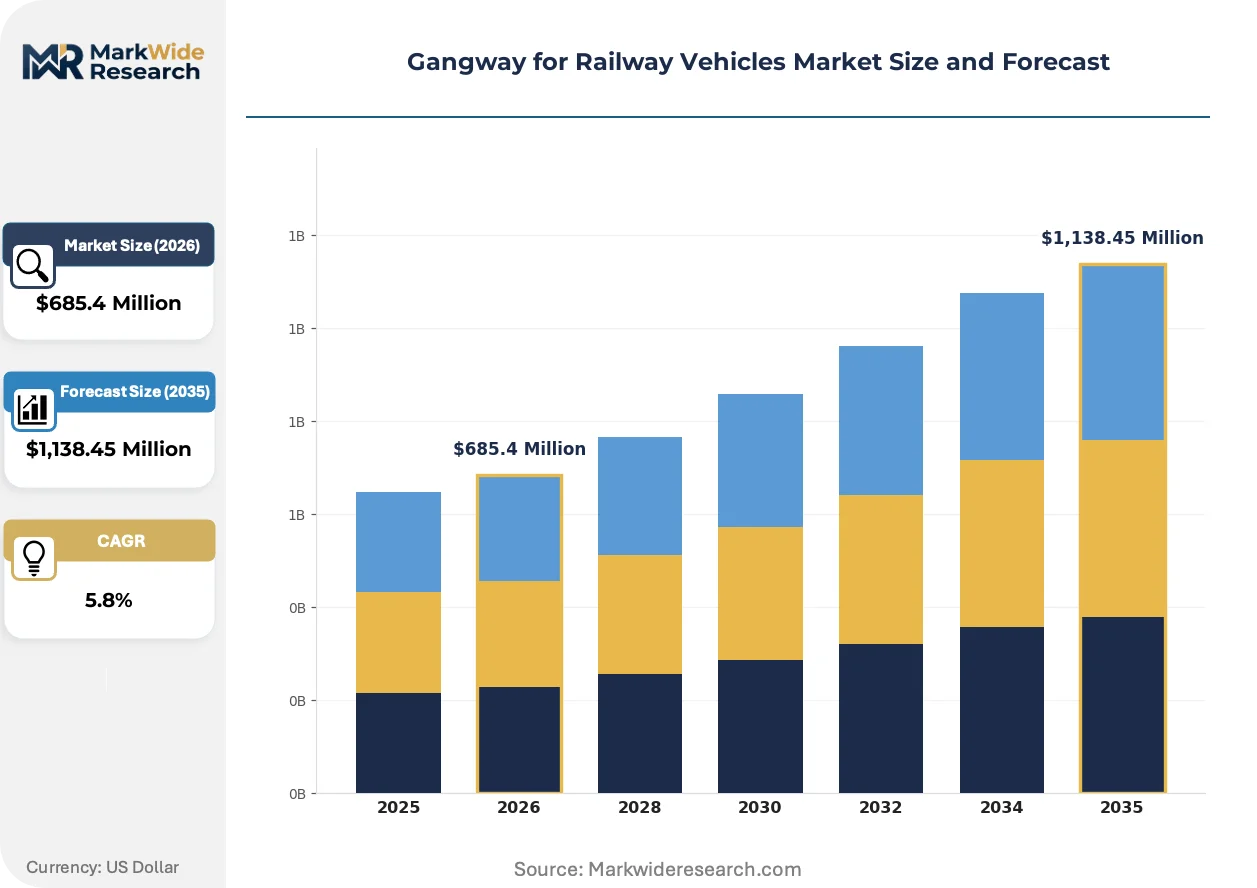
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collapsible Gangways, Fixed Gangways, Telescopic Gangways, Articulated Gangways Material: Aluminum, Steel, Fiberglass, Composite Application: Passenger Coaches, Freight Coaches, High-Speed Trains, Light Rail Vehicles End User: Rail Operators, Maintenance Agencies, OEMs, Transportation Authorities |
| Companies Covered | HÜBNER GmbH & Co. KG, Dellner Couplers, KTK Group, Zhejiang Yonggui Electric Equipment Co., Ltd., Jai Dadi Group, Chongqing Hengtairail Equipment Co., Ltd., Narita Mfg. Co., Hutchinson, ATG Autotechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gangway for Railway Vehicles Market Trends and Innovations
Active research into thermoplastic composites and embedded sensor networks is compressing the gap between structural performance and intelligence integration in next-generation gangway systems.
Modular thermoplastic composite gangways with integrated fiber-optic strain monitoring are rendering obsolete traditional bellows-and-frame assemblies that require manual inspection intervals. Japanese Shinkansen operators and French TGV maintenance depots are piloting these systems for real-time crack detection. The shift eliminates unplanned removal from service and collapses maintenance scheduling from fixed intervals to condition-triggered interventions.
REACH Annex XVII restrictions on halogenated flame retardants are forcing reformulation of gangway interior surfaces across EU rolling stock procurement. Suppliers must substitute phosphorus-nitrogen intumescent coatings for legacy brominated compounds without sacrificing 15-minute fire resistance ratings. German KBA type approval processes are absorbing 8-12 month validation extensions as laboratories clear certification backlogs.
Chinese CRRC supply chain corridors are capturing specification authority previously held by European rail OEMs, compressing design-influence windows for incumbent gangway suppliers. Domestic fabricators in Changzhou and Qingdao now receive direct technical requirements from metro operators in São Paulo, Jakarta, and Cairo. The pattern concentrates engineering feedback loops within China's industrial ecosystem and reduces European supplier access to emerging market fleet specifications.
Gangway for Railway Vehicles Market Segmentation
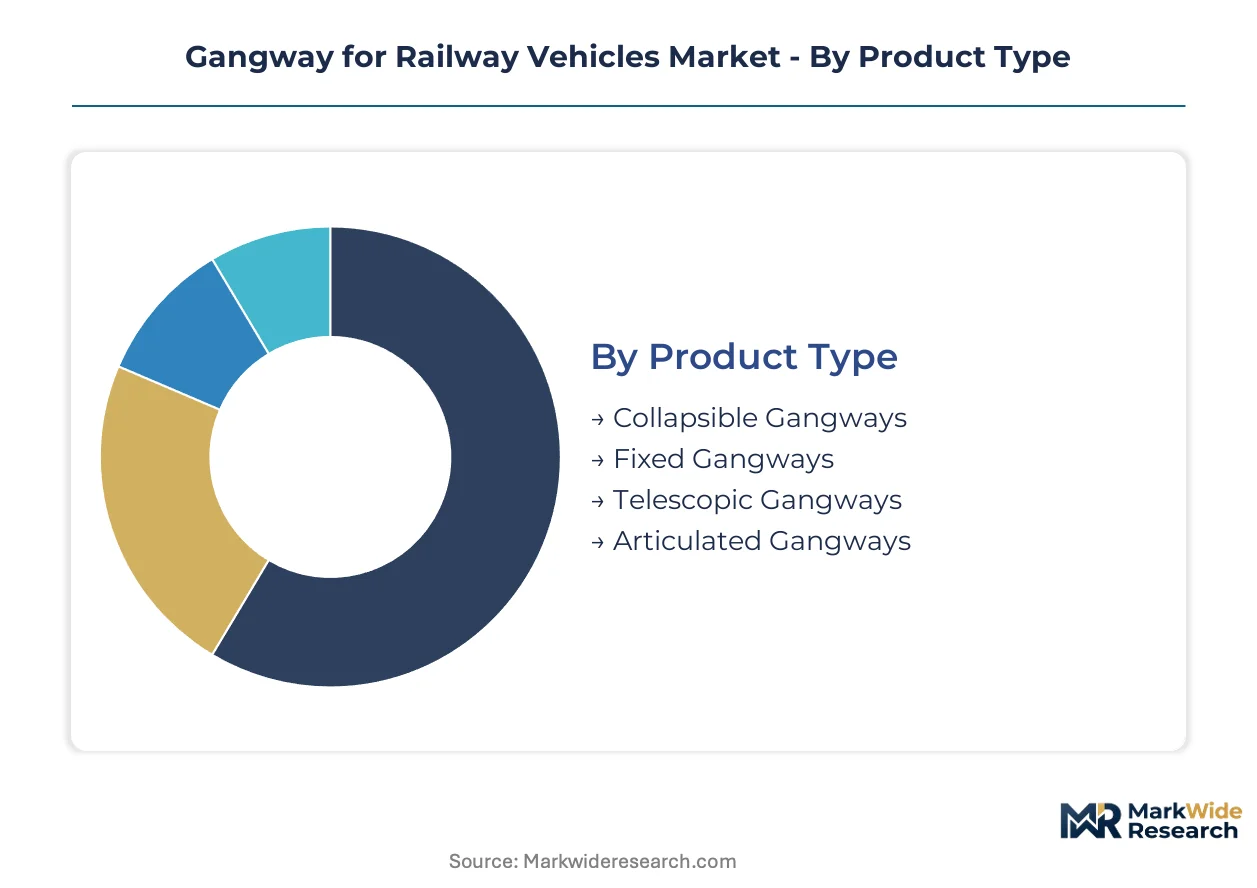
Gangway procurement patterns diverge sharply across product architectures, material specifications, and rolling stock categories. Understanding these fault lines clarifies where specification authority concentrates and which technical standards govern tender participation.
Product Type:
Application context dictates gangway geometry selection, with platform gap variability and coupling dynamics determining which structural format operators specify.
- Collapsible Gangways:Corrugated bellows assemblies with telescoping frames adapt to variable platform heights and curvature radii in metro environments. Mumbai Metro, Delhi MRTS, and Bengaluru Namma Metro specify these for 15-minute fire integrity ratings under India's expanding suburban electrification.
- Fixed Gangways:Rigid structural assemblies maintain constant geometry for high-speed trainsets with standardized platform interfaces. Deutsche Bahn ICE and SNCF TGV procurement favors these for EN 15227 crashworthiness compliance without compression-extension cycles.
- Telescopic Gangways:Nested aluminum extrusions extend coverage range for light rail vehicles with mixed platform infrastructure.
- Articulated Gangways:Multi-hinge assemblies accommodate tight curvature in urban tram networks and heritage railway retrofits.
Collapsible gangways hold installed capacity across commuter fleets. Telescopic variants are rotating up the share rankings as light rail expansion accelerates.
Material:
Weight reduction targets and crashworthiness benchmarks are redistributing procurement volumes across metallic and non-metallic alternatives.
- Composite:Carbon fiber reinforced polymer floor panels achieve 30-40% weight reduction versus aluminum, enabling energy efficiency monetization through reduced electricity consumption. Chinese CRRC supply chains and EU Green Deal procurement incentives favor these for lifecycle carbon scoring.
- Aluminum:Extruded structural frames with EPDM bellows membranes dominate mid-tier specifications where TIG welding certification constraints limit supplier participation in Germany and Poland.
- Steel:Heavy-gauge assemblies persist in India's Dedicated Freight Corridor for 25-ton axle load endurance.
- Fiberglass:Thermoplastic variants with embedded fiber-optic strain monitoring are gaining traction in Shinkansen and TGV pilot programs for real-time crack detection.
Aluminum maintains specification dominance in European high-speed tenders. Composite materials are climbing the fastest as operators prioritize energy efficiency targets.
Application:
Operational duty cycles and passenger density determine gangway durability requirements and replacement frequency.
- High-Speed Trains:Sealed gangway assemblies with acoustic isolation thresholds above 35 dB serve 300+ km/h operations where aerodynamic loading and pressure differentials stress bellows membranes.
- Passenger Coaches:High-cycle compression-extension designs withstand frequent coupling in regional and intercity services with multiple daily consists.
- Light Rail Vehicles:Compact geometries with tight turning radius accommodation suit street-running tram networks with mixed traffic interfaces.
- Freight Coaches:Reinforced structural frames support crew access in heavy-haul consists with extended duty cycles and minimal maintenance windows.
Passenger coaches retain volume leadership in unit installations. High-speed train specifications are expanding most quickly as Asian and European fleet replacement cycles converge.
End User:
Specification authority varies across the value chain, with design-influence windows narrowing as supply chain corridors consolidate.
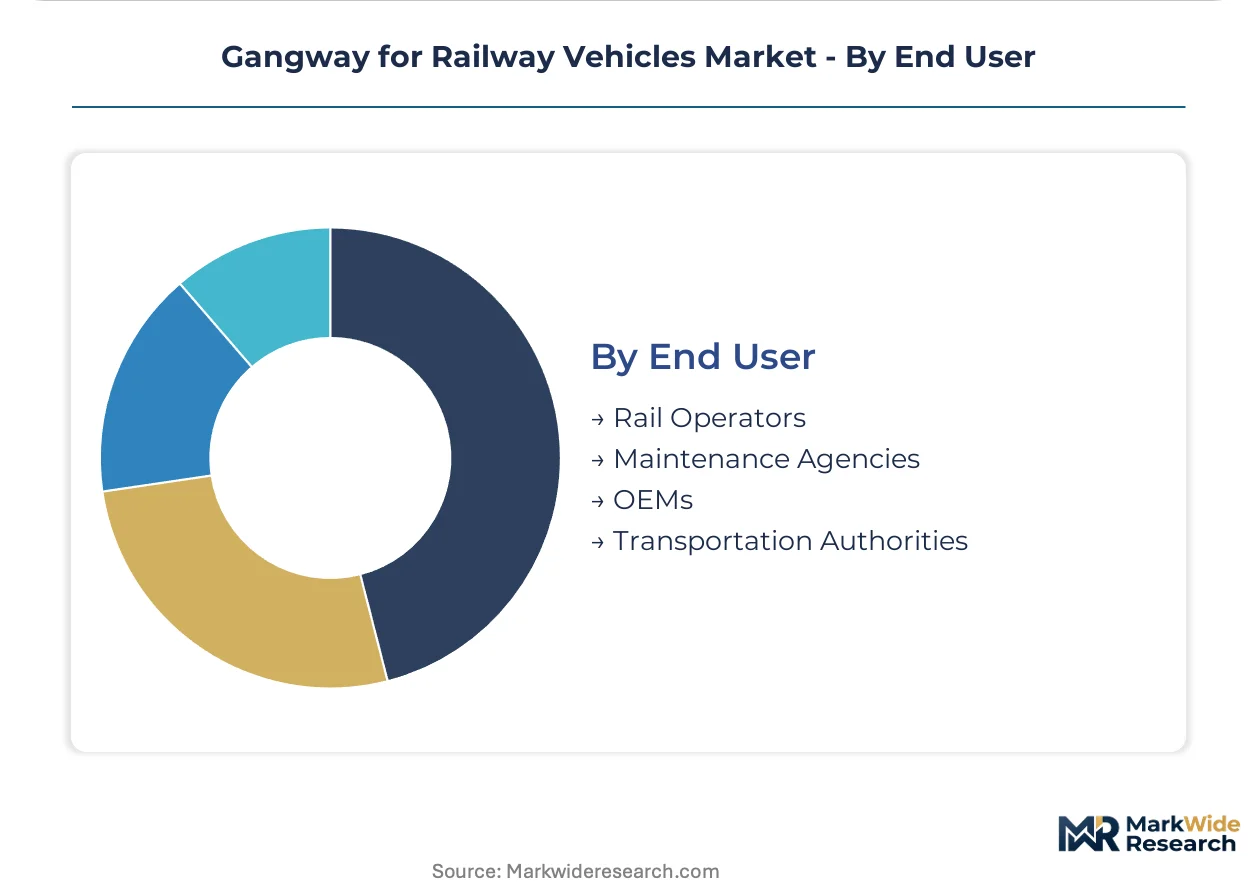
- OEMs:Rolling stock manufacturers hold direct architectural authority during new-build programs, integrating gangway specifications with coupler and carbody interfaces.
- Rail Operators:Deutsche Bahn, SNCF, and Trenitalia drive EN 15227-mandated replacement demand with fleet-wide retrofit programs.
- Transportation Authorities:Metro operators in São Paulo, Jakarta, and Cairo now issue direct technical requirements to Chinese fabricators in Changzhou and Qingdao.
- Maintenance Agencies:Condition-based replacement protocols using vibration sensor data and digital twin integration are shifting procurement from calendar-based to predictive intervals.
OEMs retain design-influence authority in European tenders. Transportation authorities are gaining specification control fastest as emerging market procurement localizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fabricators in Changzhou and Qingdao now export directly to metro operators in São Paulo, Jakarta, and Cairo, bypassing traditional European specification channels. This trade-flow reconfiguration is compressing design-influence windows for incumbent suppliers while accelerating procurement localization across emerging markets.
China
CRRC supply chain corridors dominate specification authority for domestic metro and intercity networks, with Changzhou and Qingdao clusters receiving direct technical requirements from overseas operators. GB/T rail vehicle safety standards govern structural integrity and fire behavior. Domestic fabricators now supply São Paulo Metro and Jakarta MRT with fire-rated gangway assemblies.
Germany
Deutsche Bahn ICE fleet replacement programs drive EN 15227 crashworthiness-mandated demand for sealed gangway assemblies. KBA type approval processes absorb extended validation timelines for reformulated phosphorus-nitrogen intumescent coatings. HÜBNER GmbH leverages its German manufacturing base to sustain premium positioning in European high-speed contracts.
India
Mumbai Metro, Delhi MRTS, and Bengaluru Namma Metro expansion programs specify fire-rated gangway assemblies with 15-minute integrity ratings under suburban electrification mandates. The Ministry of Railways enforces distinct coupling interface standards that shape regional product form factors. ICF coaches and older Type 22 rolling stock resist modular retrofits due to non-standard interfaces.
Japan
Shinkansen operators pilot modular thermoplastic composite gangways with embedded fiber-optic strain monitoring for real-time crack detection. METI oversees standardization of predictive maintenance protocols using vibration sensor data. Japanese maintenance depots are collapsing maintenance scheduling from fixed intervals to condition-triggered interventions.
United States
The Federal Railroad Administration enforces coupling interface standards that limit cross-certification economies with European and Asian specifications. Freight operators require reinforced gangway systems for crew access in heavy-haul consists with extended duty cycles. Input cost volatility from Gulf Coast petrochemical feedstocks exposes fabricators to EPDM bellows membrane price fluctuations.
Gangway for Railway Vehicles Market Competitive Landscape
On the supply side, the industry is consolidating around tier-one suppliers capable of absorbing multi-standard certification timelines and full-scale crash test validation costs. The vendor base stratifies into premium European specialists, scale-driven Chinese fabricators, and integrated coupler-gangway system providers. Dominant competitive moves include backward integration into elastomer membrane production and geographic expansion through direct relationships with emerging-market transportation authorities.
Among Germany-based specialists, HÜBNER GmbH & Co. KG and ATG Autotechnik GmbH occupy positions within the premium-tier vector for European high-speed and metro contracts. Dellner Couplers exemplifies the integrated-systems archetype through its combined coupler-gangway offerings. KTK Group represents scale-driven Chinese supply chain dominance for domestic and export metro networks. Zhejiang Yonggui Electric Equipment Co., Ltd. and Chongqing Hengtairail Equipment Co., Ltd. anchor the Changzhou-Qingdao manufacturing corridor serving CRRC-directed specifications.
| Leading Market Players |
|---|
| HÜBNER GmbH & Co. KG |
| Dellner Couplers |
| KTK Group |
| Zhejiang Yonggui Electric Equipment Co., Ltd. |
| Jai Dadi Group |
| Chongqing Hengtairail Equipment Co., Ltd. |
| Narita Mfg. Co. |
| Hutchinson |
| ATG Autotechnik GmbH |
| Others |
Pricing and Supply Chain Analysis
Changzhou and Qingdao manufacturing clusters command downstream pricing power through captive access to CRRC supply chain corridors, compressing margins for European fabricators lacking equivalent domestic rail OEM relationships. Composite material cost trajectories and EN 15227 certification burdens are redistributing procurement leverage toward scale-driven suppliers with in-house TIG welding pipelines and crash test facilities.
Pricing Analysis
Current-generation aluminum-EPDM gangway assemblies, prior-generation steel-intensive designs, and next-generation thermoplastic composite systems with embedded sensor networks stratify across three performance tiers. Premium-mid-economy pricing differentiation rests on EN 15227 certification grade and GB/T compliance breadth, with European high-speed tenders absorbing 30-40% premiums for KBA-validated fire-rated assemblies. Cost compression in mid-tier specifications is intensifying because Chinese fabricators are exporting directly to São Paulo and Jakarta metro authorities, bypassing traditional OEM markups. Volume-scaled rail operators in India's Dedicated Freight Corridor exhibit highest price sensitivity, while Deutsche Bahn and SNCF procurement teams prioritize lifecycle carbon scoring over unit cost.
Supply Chain Analysis
Export-control restrictions on carbon fiber precursor technologies limit composite material flows from US and Japanese suppliers to Chinese fabricators, forcing Changzhou producers toward domestic PAN-based alternatives. Geographic supply concentration centers on China, Germany, and India, with EPDM bellows membranes drawing from Gulf Coast petrochemical feedstocks and aluminum extrusions sourcing from European smelters. Single-source vulnerability pervades specialized elastomer supply, where three refiners control global EPDM polymerization capacity. Distribution runs through rail OEM specification channels in Europe and direct transportation authority contracting in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite-to-metal bonding breakthroughs and EN 15227 mandate deadlines are accelerating fleet replacement cycles, creating a high-growth disruption window for suppliers with certified lightweight architectures.
For Market Incumbents: Insulate premium positioning in European high-speed tenders by deepening backward integration into phosphorus-nitrogen intumescent coating production, eliminating KBA validation bottlenecks. Accelerate capacity addition in Poland to circumvent German welding technician scarcity while defending against Chinese fabricator encroachment through bundled predictive maintenance software offerings. For New Entrants and Emerging Players: India's suburban electrification programs represent the most penetrable entry point, with Mumbai Metro and Bengaluru Namma Metro specifying fire-rated gangway assemblies that domestic ICF coach retrofits cannot satisfy. Light rail vehicle telescopic gangway specifications in Southeast Asian cities lack established supplier relationships, enabling direct transportation authority contracting as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because multi-standard certification timelines and crash test facility capital requirements are filtering smaller fabricators from tender participation. Acquisition targets should display captive elastomer membrane production and existing EN 15227 validation records. The signal to watch is CRRC specification authority expansion into Middle Eastern and African metro procurements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Membrane Production | Captive supply of bellows materials insulates margins from Gulf Coast petrochemical volatility. |
| Digital Twin Platform Development | Predictive maintenance algorithms enable condition-based replacement contracts with Deutsche Bahn and SNCF. |
| Multi-Standard Certification Investment | Simultaneous EN 15227, GB/T, and FRA compliance accelerates product launch cycles for multinational fleet orders. |
| Direct Transportation Authority Contracting | Bypassing OEM specification channels captures procurement localization in São Paulo, Jakarta, and Cairo metro expansions. |
| Thermoplastic Composite Manufacturing Scale-Up | Embedded fiber-optic strain monitoring aligns with Shinkansen and TGV pilot programs for real-time crack detection. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with rolling stock procurement directors, rail OEM platform engineers, maintenance agency technical leads, and elastomer compound specialists; and secondary validation through customs trade databases, SEC filings of listed rail component suppliers, EN 15227 certification registries, and CRRC annual production disclosures. Bottom-up triangulation across gangway unit installation records and top-down reconciliation against rolling stock delivery schedules anchored volume estimates.
Forecast inputs incorporated product type evolution, material substitution trajectories, and end-user specification authority shifts across the projection horizon. Segmentation dimensions modeled include gangway architecture, composite versus metallic material categories, rolling stock application classes, and geographic regulatory clusters. CAGRs were derived from fitted growth curves calibrated to fleet replacement cycle timing and electrification program announcements.
Stress conditions across EPDM feedstock pricing, EN 15227 certification backlog durations, and Chinese export financing availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding CRRC supply chain corridor expansion and EU Green Deal procurement incentive continuity. Material shifts in REACH Annex XVII flame retardant restrictions or FRA coupling interface standard harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Rolling Stock Management Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Automatic Train Operation System Market
Railway
Locomotive Doors Market
Railway
France Connected Rail Market
Railway
Global Train Brake Market
Railway
Rail Brace Market
Railway
Freight Cars Market
Railway
Rail Brake Frame Market
Railway
Rail Seat Market
Railway
Railway Axle Market
Railway
Railway Pantograph Market
Railway
Solar Train Market
Railway
Train Bogie Market
Railway
Railway Window Market
Railway
Check Rails Market