
 Global Hyperloop Train Market | 2026-2036
Global Hyperloop Train Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hyperloop Train Market Outlook
ISO 9001 quality management certification is reorganizing vendor qualification across the Global Hyperloop Train Market, filtering which engineering firms secure infrastructure contracts. Virgin Hyperloop leverages extensive magnetic levitation R&D to sustain technology leadership in vacuum tube propulsion. Hardt B.V. anchors European project development through specialized control systems integration. TransPod competes on proprietary linear motor designs that differentiate its corridor proposals in North American feasibility studies.
Hyperloop trains are sealed-pod transit systems operating within reduced-pressure tubes at speeds exceeding conventional rail, utilizing magnetic levitation and linear induction motors to minimize aerodynamic drag. Passenger applications dominate current project pipelines, while freight transport segments attract logistics operators seeking same-day intercity delivery capacity. Vacuum tube technology commands the deepest engineering investment, though safety mechanisms represent the fastest-growing procurement category as regulators mandate redundant braking and emergency egress systems.
The Federal Railroad Administration in the United States, the European Union Agency for Railways, and the UAE's Roads and Transport Authority each impose distinct safety and interoperability standards that shape certification timelines and cross-border project viability. Compliance with these overlapping frameworks determines which consortia qualify for public-private partnership financing. Stakeholders must monitor which regulatory body first establishes internationally recognized hyperloop-specific standards, as that jurisdiction will likely set the template for global procurement requirements.
Market Dynamics
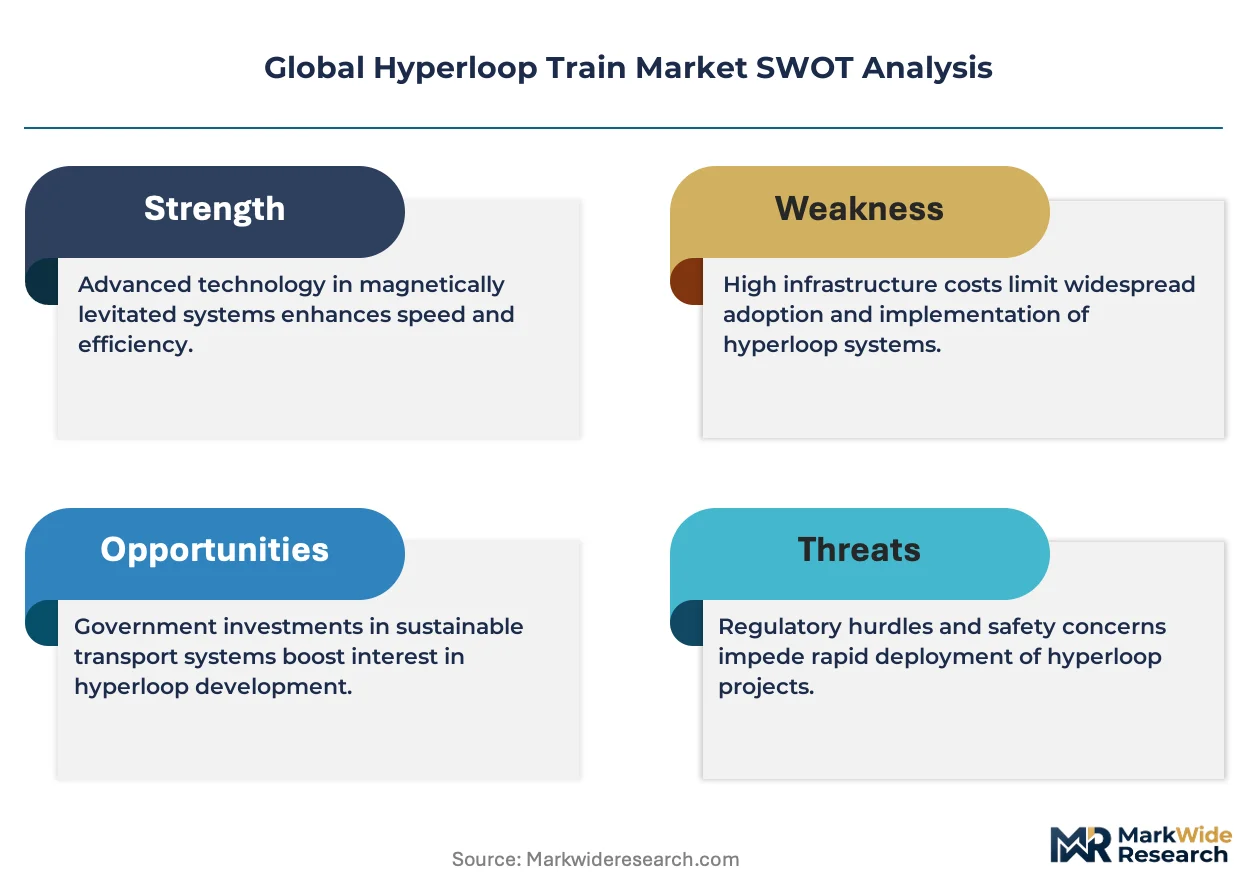
Vacuum-sealed propulsion systems are forcing a fundamental reconfiguration of infrastructure procurement timelines across intercity corridor development, as magnetic levitation R&D investments compress certification cycles and reshape vendor qualification frameworks.
Growth Catalysts
- UAE Corridor Development:The Dubai-Abu Dhabi route anchors regional project pipelines, with the Roads and Transport Authority accelerating feasibility studies and land acquisition protocols for vacuum tube infrastructure.
- F-Gas Regulation Compliance:The EU's fluorinated gas restrictions are redirecting engineering investment toward sealed-environment propulsion systems that eliminate atmospheric emissions from transport operations.
- Linear Induction Motor Maturation:Advances in electromagnetic propulsion efficiency are reducing per-kilometer energy requirements below conventional high-speed rail thresholds.
Market Restraints
- Steel Alloy Supply Concentration:Specialized vacuum-grade tubing production concentrates in German and Japanese metallurgical facilities, creating input bottlenecks for corridor-scale deployment.
- Right-of-Way Acquisition Costs:Urban periphery land values in the United States and United Kingdom inflate capital requirements for tube routing between metropolitan centers.
- Interoperability Friction:Divergent safety protocols between the Federal Railroad Administration and EU Agency for Railways fragment certification pathways for cross-border equipment suppliers.
Strategic Opportunities
- Saudi Arabia NEOM Integration:The Kingdom's linear city development presents purpose-built corridor conditions without legacy infrastructure conflicts or expropriation complexity.
- Freight Pod Specialization:Logistics operators in the Netherlands and Singapore are piloting cargo-optimized capsule designs for same-day intercontinental delivery networks.
- ISO 13001 Convergence:Emerging magnetic levitation quality standards are creating first-mover certification advantages for engineering firms that achieve early compliance.
Industry Challenges
- Vacuum Engineering Talent Scarcity:The specialized workforce for maintaining near-atmospheric pressure environments across hundred-kilometer tubes remains concentrated in aerospace and particle physics programs.
- Redundant Safety System Certification:Regulators in the United States and United Arab Emirates mandate dual independent braking architectures that extend validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hyperloop Train Market |
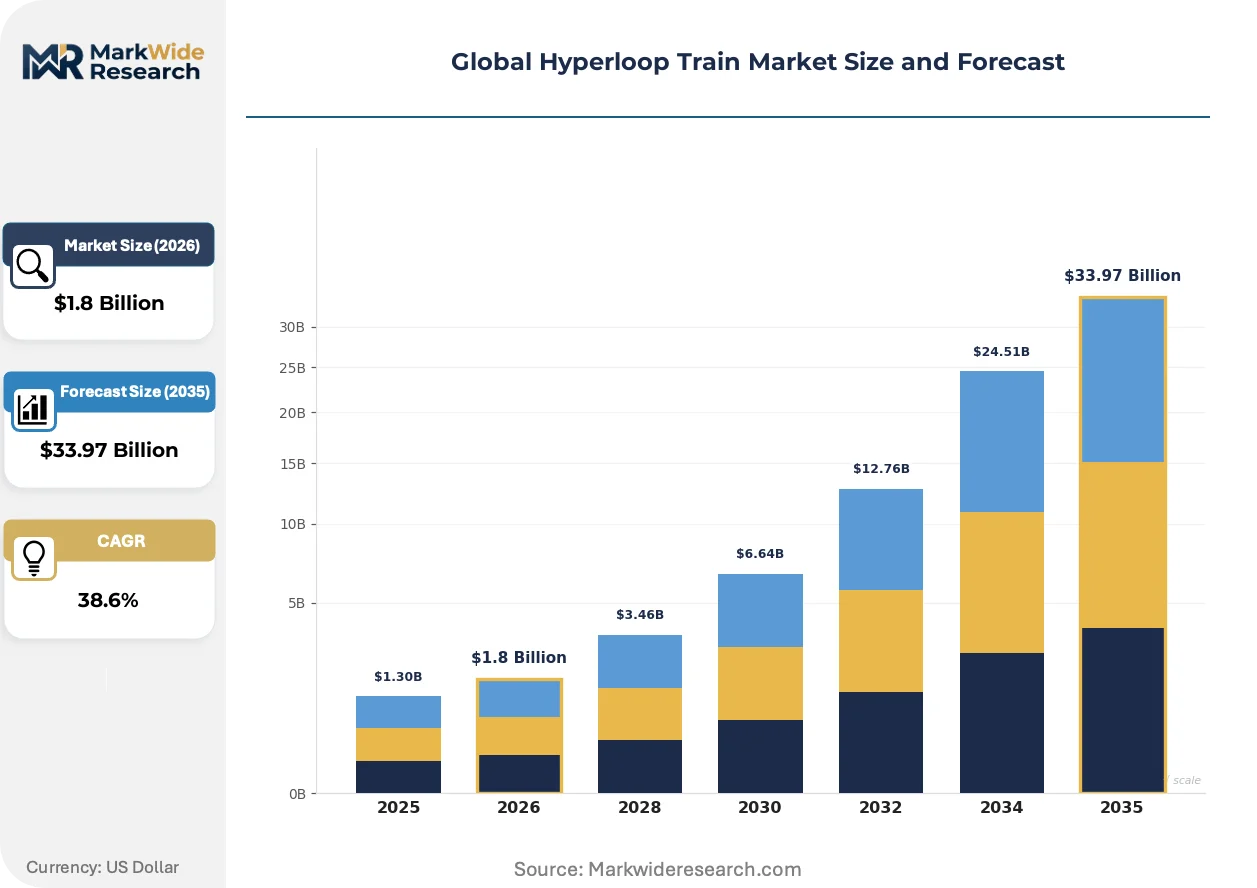
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.97 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Passenger, Cargo, Hybrid, Magnetic Levitation Technology: Vacuum Tube, Propulsion System, Safety Mechanisms, Control Systems End User: Government, Private Sector, Infrastructure Developers, Transportation Authorities Application: Urban Transit, Intercity Travel, Freight Transport, Tourism |
| Companies Covered | Hyperloop Transportation Technologies, Virgin Hyperloop, Hardt B.V., TransPod, Zeleros, Space Exploration Technologies Corporation, The Boring Company, Arrivo, Dinclix GroundWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hyperloop Train Market Strategic Shifts
Active magnetic levitation systems are supplanting passive alternatives across prototype testing programs, while regulatory bodies in multiple jurisdictions race to establish precedent-setting safety frameworks before commercial deployment.
Permanent magnet synchronous motors are supplanting earlier induction designs in vacuum tube propulsion architectures. Transportation authorities in the Netherlands and Canada are specifying these systems for pilot corridors due to superior power density. The technology is supplanting conventional wheel-rail contact entirely, eliminating friction maintenance from operational budgets.
The EU's F-Gas Regulation is mandating sealed-environment transport systems for new intercity infrastructure above certain speed thresholds. Engineering consortia are redesigning thermal management systems to comply with fluorinated gas phase-out schedules. European corridor proposals now prioritize vacuum tube configurations over open-air magnetic levitation to secure permitting approval.
Public-private partnership structures are replacing traditional government procurement for hyperloop infrastructure financing. Municipal authorities in the United Arab Emirates and Saudi Arabia are transferring construction risk to private operators through availability-payment mechanisms. This model is concentrating project development expertise within specialized infrastructure funds rather than diversified engineering conglomerates.
Global Hyperloop Train Market Segmentation
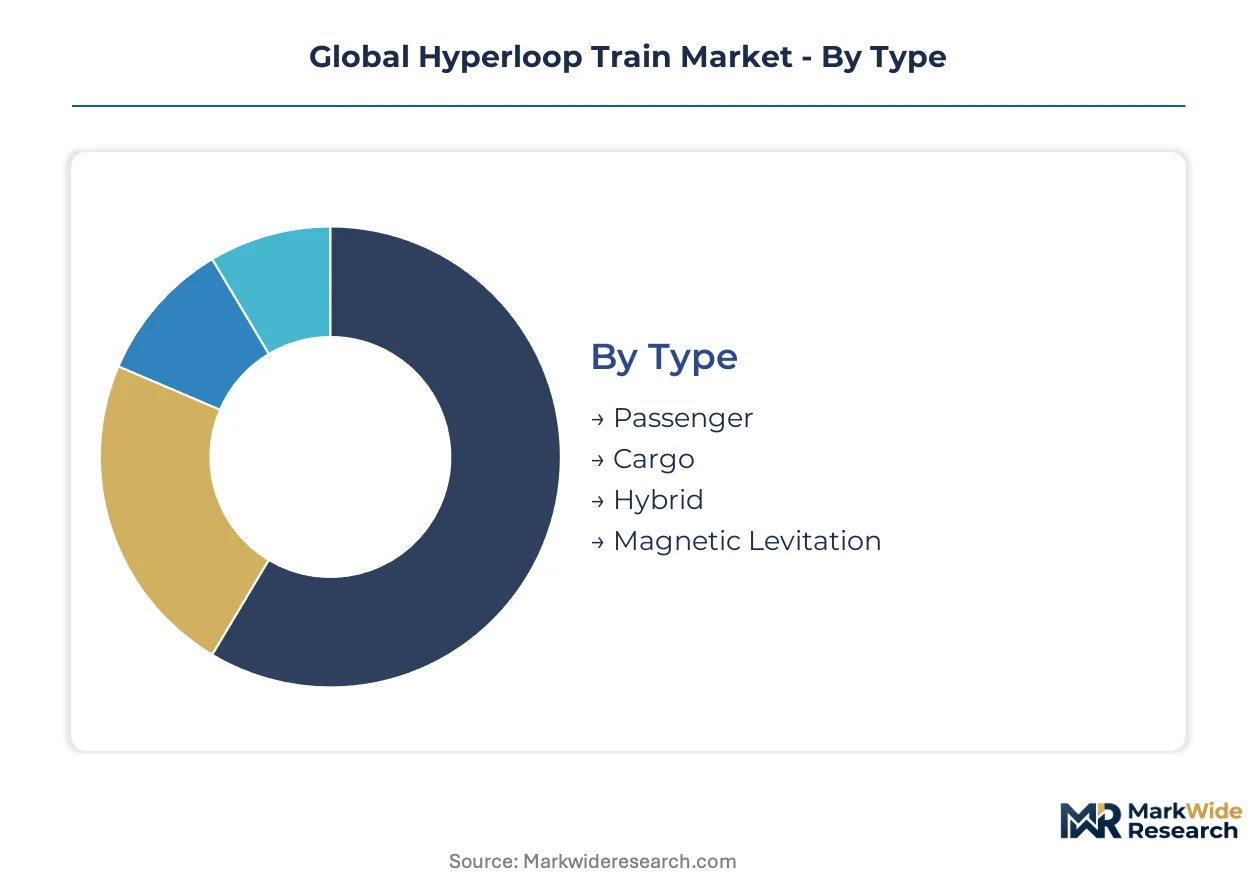
Hyperloop train segmentation reveals distinct margin architectures across propulsion technologies and operator models. Procurement patterns diverge sharply between government-led corridor development and private logistics networks, creating tiered investment timelines and certification requirements.
Type:
Margin pools concentrate in pod configurations that minimize per-kilometer infrastructure costs while maximizing passenger throughput.
- Passenger:Sealed human-transport capsules dominate current procurement pipelines, with the Dubai-Abu Dhabi corridor anchoring feasibility investment. The Roads and Transport Authority mandates redundant life-support systems that extend certification cycles.
- Cargo:Freight-optimized designs attract logistics operators seeking same-day intercontinental delivery capacity. Netherlands-based pilots are testing automated loading mechanisms for e-commerce distribution networks.
- Hybrid:Dual-purpose pods accommodate mixed payloads during off-peak passenger hours, appealing to infrastructure funds optimizing utilization rates.
- Magnetic Levitation:Pure levitation architectures eliminate wheel-rail contact entirely, concentrating R&D investment in electromagnetic efficiency gains.
Passenger systems command the dominant share, while Cargo configurations are climbing the fastest as logistics operators pilot dedicated freight corridors.
Technology:
Engineering investment intensity varies dramatically by subsystem, with vacuum integrity representing the highest technical barrier to commercial deployment.
- Vacuum Tube:Reduced-pressure infrastructure commands the deepest capital allocation, requiring specialized steel alloys from German and Japanese metallurgical suppliers. The EU's F-Gas Regulation is accelerating sealed-environment specifications for new intercity corridors.
- Propulsion System:Linear induction and permanent magnet synchronous motors are supplanting conventional traction across prototype testing. Canadian transportation authorities specify these systems for pilot programs due to superior power density.
- Safety Mechanisms:Dual independent braking architectures and emergency egress systems represent the fastest-expanding procurement category as regulators mandate redundant protection layers.
- Control Systems:Automated pod coordination platforms integrate with legacy rail signaling infrastructure, creating interoperability requirements that fragment vendor qualification.
Vacuum Tube infrastructure absorbs the largest capital share, though Safety Mechanisms procurement is expanding most quickly under tightening regulatory mandates.
End User:
Financing risk allocation determines contract structures, with availability-payment mechanisms transferring construction exposure from public to private balance sheets.
- Government:National transportation ministries anchor corridor-scale development through sovereign-backed procurement, with Saudi Arabia's NEOM project offering purpose-built conditions without legacy conflicts.
- Private Sector:Infrastructure funds and specialized operators are assuming construction risk under public-private partnership frameworks, concentrating expertise outside traditional engineering conglomerates.
- Infrastructure Developers:Turnkey consortiums integrate tube manufacturing, propulsion installation, and operational commissioning into unified delivery contracts.
- Transportation Authorities:Municipal and regional regulators define safety protocols and interoperability standards that shape vendor qualification timelines.
Government entities retain the dominant procurement volume, while Private Sector participation is gaining share fastest through risk-transfer financing structures.
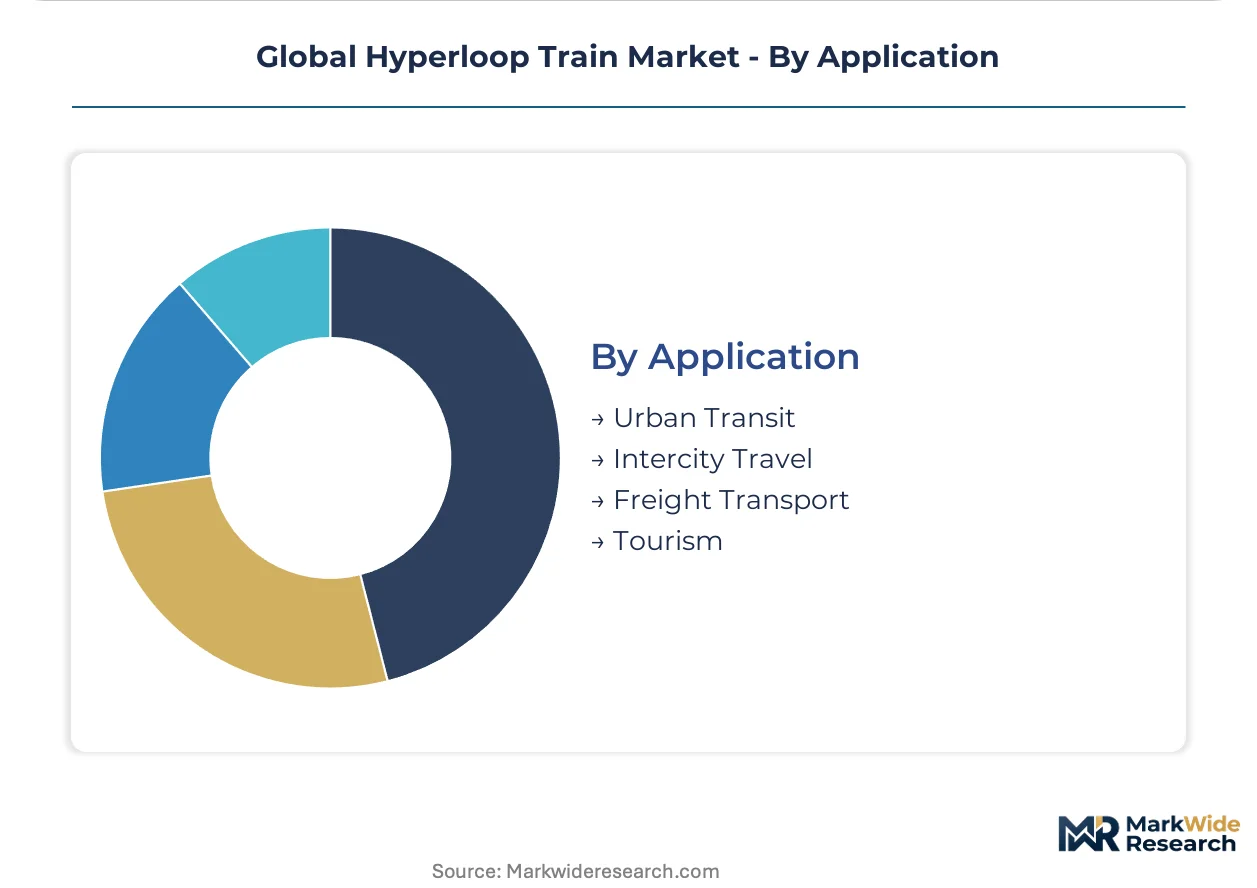
Application:
Route economics vary by distance and payload, with intercity corridors offering superior speed-value propositions against conventional rail and aviation.
- Urban Transit:Metropolitan periphery connections face right-of-way acquisition costs that inflate capital requirements in high-land-value markets like the United Kingdom.
- Intercity Travel:Regional corridor development concentrates in the United Arab Emirates and Saudi Arabia, where greenfield conditions avoid expropriation complexity.
- Freight Transport:Same-day delivery networks attract logistics investment in Singapore and the Netherlands, where port-to-inland distribution demands rapid turnaround.
- Tourism:Experience-oriented capsules with panoramic viewing configurations target premium passenger segments in destination markets.
Intercity Travel holds the dominant project pipeline, while Freight Transport is advancing fastest as logistics operators validate cargo-optimized designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public-private partnership frameworks and sovereign infrastructure funds are accelerating corridor-scale feasibility studies across multiple jurisdictions. The Federal Railroad Administration, the EU Agency for Railways, and the UAE's Roads and Transport Authority each impose distinct certification requirements that shape vendor qualification timelines and cross-border project viability.
United States
The Federal Railroad Administration mandates redundant braking architectures and emergency egress systems that extend validation timelines for commercial deployment. State-level transportation authorities in California and Texas anchor feasibility studies for intercity corridors, though right-of-way acquisition costs in urban periphery markets inflate capital requirements. The Midwest corridor proposals concentrate engineering investment around Chicago-Detroit routing studies.
United Arab Emirates
The Roads and Transport Authority accelerates land acquisition protocols and feasibility investment for the Dubai-Abu Dhabi vacuum tube corridor. Sovereign-backed procurement frameworks transfer construction risk to specialized infrastructure funds through availability-payment mechanisms. The emirates' greenfield development conditions avoid legacy infrastructure conflicts that complicate routing in established metropolitan regions.
Saudi Arabia
The Kingdom's NEOM linear city development presents purpose-built corridor conditions without expropriation complexity or existing transport conflicts. The national transportation ministry anchors corridor-scale development through direct sovereign procurement rather than risk-transfer financing. The northwestern region concentrates project development expertise within specialized infrastructure funds and turnkey consortiums.
Netherlands
Port-to-inland distribution demands from Rotterdam's logistics hub attract pilot investment for cargo-optimized capsule designs and automated loading mechanisms. The national transport authority specifies permanent magnet synchronous motor systems for pilot programs due to superior power density. The Randstad metropolitan cluster concentrates control systems integration expertise for automated pod coordination platforms.
Canada
Transportation authorities in Ontario and Quebec specify linear induction and permanent magnet synchronous motor architectures for intercity pilot corridors. Provincial regulators coordinate with the Federal Railroad Administration on interoperability standards that fragment certification pathways for equipment suppliers. The Toronto-Montreal corridor anchors feasibility studies for vacuum-sealed propulsion deployment.
Global Hyperloop Train Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and infrastructure financing structures, creating a tiered competitive architecture where scale advantages concentrate in established transport conglomerates while innovation velocity sits with venture-backed entrants. The vendor base organizes around three strategic archetypes: integrated infrastructure developers controlling tube manufacturing through operational commissioning, specialized propulsion engineering firms licensing linear motor intellectual property, and diversified aerospace contractors repurposing vacuum engineering capabilities. Dominant competitive moves include public-private partnership formation to transfer construction risk and strategic technology licensing to accelerate certification timelines.
Within the integrated infrastructure developer tier, Virgin Hyperloop and Hardt B.V. exemplify archetypes competing on proprietary magnetic levitation R&D and control systems integration respectively. TransPod occupies a position among specialized propulsion engineering firms, differentiating corridor proposals through linear motor design intellectual property. These three anchors represent distinct competitive vectors: Virgin Hyperloop leverages extensive magnetic levitation research heritage, Hardt B.V. anchors European project development through systems integration specialization, and TransPod competes on proprietary electromagnetic architectures in North American feasibility studies.
| Leading Market Players |
|---|
| Hyperloop Transportation Technologies |
| Virgin Hyperloop |
| Hardt B.V. |
| TransPod |
| Zeleros |
| Space Exploration Technologies Corporation |
| The Boring Company |
| Arrivo |
| Dinclix GroundWorks |
| Others |
Value Chain & Pricing Dynamics
ISO 13001 magnetic levitation certification gates both vendor qualification and price differentiation across procurement contracts, forcing engineering consortia to absorb compliance costs that stratify bidding tiers while buyers prioritize certified suppliers for risk mitigation.
Pricing Analysis
Certification level creates the primary spread between premium and standard procurement tiers. Project-based contract structures dominate corridor-scale deployment, with price differentiation resting on ISO 9001 quality grades and F-Gas Regulation compliance status. Cost compression in mid-tier propulsion systems is intensifying because European transportation authorities are consolidating approved vendor lists. Government transportation ministries exhibit lowest price sensitivity due to sovereign-backed financing, while private infrastructure funds face tighter return thresholds that amplify bargaining leverage.
Supply Chain Analysis
Extended lead times for vacuum-grade steel alloys from German and Japanese metallurgical suppliers stretch procurement cycles beyond eighteen months for tube manufacturing. Specialized steel production draws from concentrated metallurgical facilities in Germany, Japan, and South Korea, with permanent magnet synchronous motors and linear induction components feeding from Taiwanese and Chinese electromagnetic suppliers. Single-source vulnerability in vacuum-grade tubing creates exposure to geopolitical trade restrictions. Distribution runs through turnkey infrastructure consortiums that integrate manufacturing, installation, and operational commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around vacuum-sealed propulsion standards creates defensive moats for early-certified engineering firms, as switching costs for transportation authorities escalate once safety protocols are embedded in procurement frameworks.
For Market Incumbents: Secure dual certification pathways with both the Federal Railroad Administration and EU Agency for Railways to preempt competitor access to cross-border corridor financing. Deepen backward integration into vacuum-grade steel sourcing to mitigate German and Japanese supply concentration. Lock in long-term availability-payment contracts with UAE and Saudi Arabian sovereign funds before emerging entrants achieve technical validation. For New Entrants and Emerging Players: Anchor in cargo-optimized pod development for Netherlands and Singapore port-to-inland distribution networks, where logistics operators pilot dedicated freight corridors with lower certification barriers than passenger systems. Target freight transport applications as the most penetrable segment given lighter regulatory scrutiny and faster validation timelines. Pursue joint development agreements with specialized infrastructure funds seeking operational expertise without legacy engineering conglomerate overhead. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across vacuum tube infrastructure manufacturing as steel alloy procurement and redundant safety system development consume larger capital pools. Five-to-ten year viability hinges on which consortia secure first-mover corridor completion and operational data. Acquisition candidates center on specialized propulsion engineering firms with proprietary linear motor intellectual property. The signal to watch is which regulatory body first establishes internationally recognized hyperloop-specific standards, as that jurisdiction will template global procurement requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Levitation R&D Partnership | Virgin Hyperloop leverages extensive research heritage to sustain technology leadership in vacuum tube propulsion systems. |
| Control Systems Integration Specialization | Hardt B.V. anchors European project development through proprietary automated pod coordination platforms. |
| Linear Motor IP Licensing | TransPod differentiates North American corridor proposals through proprietary electromagnetic architecture designs. |
| Public-Private Partnership Formation | UAE Roads and Transport Authority transfers construction risk to infrastructure funds through availability-payment mechanisms. |
| Freight Pod Specialization | Netherlands-based logistics operators pilot cargo-optimized capsules for same-day intercontinental delivery networks. |
Study Parameters
Initial hypotheses were tested against primary input from infrastructure fund managers, transportation authority procurement officers, magnetic levitation R&D directors, and vacuum engineering specialists and refined through secondary validation against F-Gas Regulation filings, Federal Railroad Administration safety protocols, EU Agency for Railways technical specifications, and UAE Roads and Transport Authority feasibility studies. Bottom-up corridor project pipelines were triangulated with top-down sovereign infrastructure spending forecasts.
Variance decomposition across the projection horizon isolates volume sensitivity to certification timeline acceleration and capital commitment phasing by government transportation ministries. Segmentation dimensions modeled include propulsion technology type, pod configuration, end-user financing structure, and regional regulatory cluster. CAGRs were derived from corridor deployment schedules weighted by land acquisition progress and metallurgical supply availability. Industry-specific inputs incorporate vacuum-grade steel production capacity and electromagnetic propulsion efficiency curves.
Material uncertainties — regulatory standard fragmentation, right-of-way expropriation delays, vacuum engineering workforce scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions about sovereign procurement continuity and alloy supply chain stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Heritage Railways Trains Market
Railway
Tugger Trains Market
Railway
Train Locomotive Suspension Market
Railway
Connected Rail Market
Railway
Light Rail Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Railway System Market
Railway
Hydrogen Trains Market
Railway
Smart Railways Market
Railway
Railway Window Market
Railway
Railway Rolling Stock Market
Railway
Europe Intermodal Terminals Market
Railway
Global Train Brake Market
Railway
Automatic Train Operation System Market
Railway
Railway Draft Gears Market
Railway
Automatic Train Control Market