
 Railway Horn Market | 2026-2036
Railway Horn Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Horn Market Analytics
Aluminum diaphragm assemblies is restructuring cost structures across pneumatic horn manufacturing, trimming weight and extending service intervals versus traditional brass components. Wabtec Corporation leverages its North American installed base to sustain aftermarket parts revenue. Nathan Airchime, LLC anchors its position through specialized casting expertise for high-decibel locomotive applications. Alstom SA competes on integrated train-level signaling systems that incorporate horn modules into broader communication architectures.
A railway horn is an acoustic warning device engineered to emit standardized audible signals, typically operating between 96 and 110 decibels at 100 feet to alert pedestrians, workers, and vehicles near track crossings. Pneumatic variants dominate freight and heavy-haul segments due to superior sound projection and reliability in extreme temperatures, while electric horns gain share in metro systems where compressor maintenance is constrained by tunnel access limitations. Roof-mounted installation captures the majority of retrofit demand, though integrated designs bundled with new-build trainsets are expanding as OEMs specify factory-installed horn modules to streamline homologation.
The Federal Railroad Administration (FRA) mandates horn sounding patterns at public crossings, directly shaping product decibel thresholds and automatic activation system demand. The European Union Agency for Railways (ERA) enforces interoperability standards through TSIs that dictate horn frequency ranges and electromagnetic compatibility for cross-border rolling stock. India's Ministry of Railways and Research Designs and Standards Organisation (RDSO) specify horn types for domestic manufacture, creating localized procurement pools. Stakeholders must monitor divergence between national noise ordinances and railway-specific safety exemptions as urban densification intensifies.
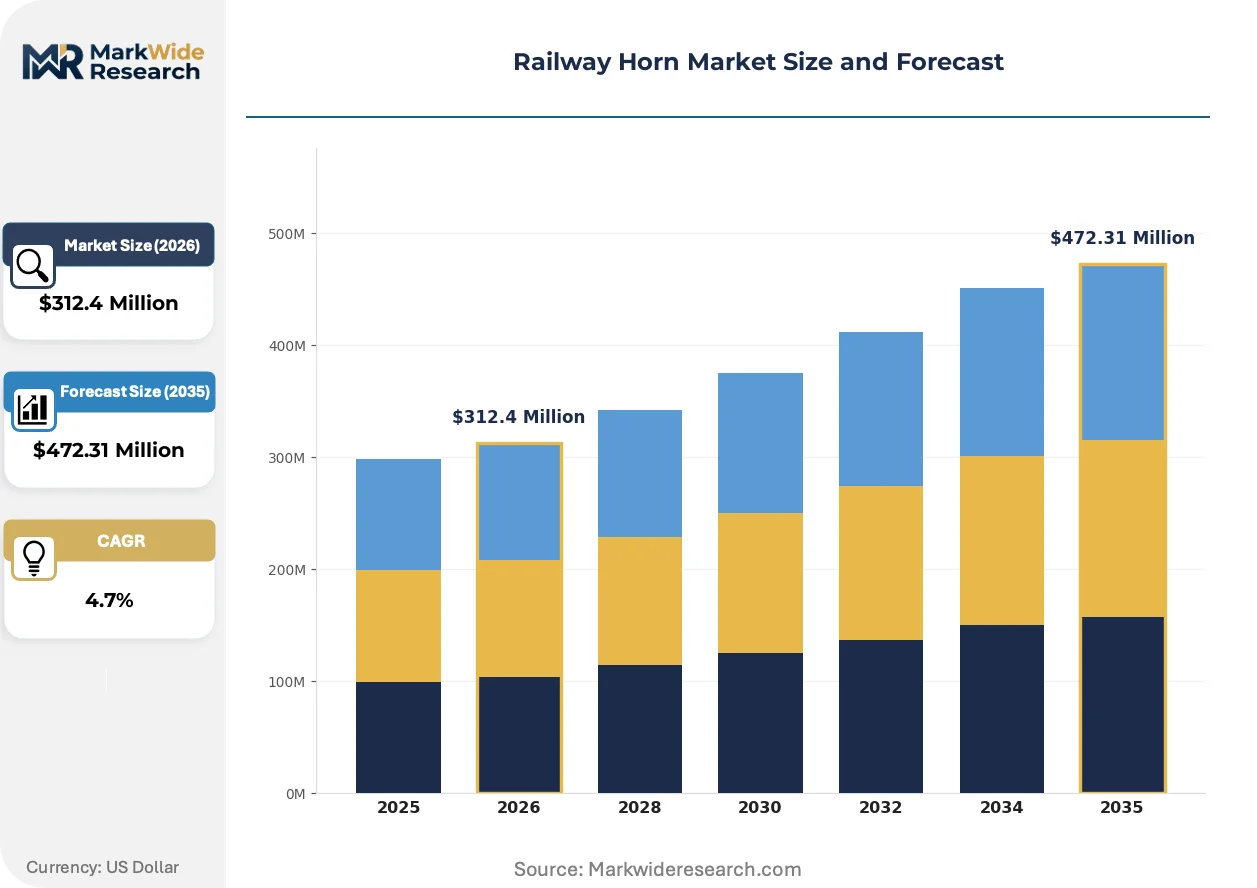
Market Dynamics
Compressed air system miniaturization is displacing legacy mechanical designs across freight and metro fleets, forcing manufacturers to retool casting and diaphragm fabrication lines while railway electrification mandates accelerate procurement cycles in emerging economies.
Growth Catalysts
- Electrification Mandates:India's Ministry of Railways and RDSO specifications for standardized horn signaling equipment under Dedicated Freight Corridor and metro buildouts are generating sustained procurement volume for pneumatic and electric variants.
- Aluminum Diaphragm Assemblies:Weight reduction and extended service intervals versus brass components are lowering total cost of ownership for fleet operators managing high-utilization rolling stock.
- Urban Metro Expansion:Southeast Asian cities including Bangkok, Jakarta, and Ho Chi Minh City are expanding fleet procurement under national railway modernization programs, creating concentrated demand for roof-mounted and integrated horn modules.
Market Restraints
- Copper and Aluminum Price Volatility:Diaphragm and electromagnetic coil materials face commodity price swings that compress manufacturing margins and complicate long-term contract pricing.
- Supply Concentration in Casting:Specialized foundry capacity for high-decibel locomotive horn housings concentrates in select industrial clusters, creating vulnerability to localized disruptions.
- Acoustic Substitution Limits:Electronic warning systems and wayside horns cannot fully replace onboard pneumatic devices under FRA and ERA interoperability mandates, locking in legacy infrastructure requirements.
Strategic Opportunities
- Integrated Train-Level Signaling:Horn modules bundled with communication architectures enable OEMs to streamline homologation and capture factory-installed specification share.
- Automatic Activation Systems:GPS-triggered horn sounding patterns reduce operator burden and ensure FRA compliance at public crossings, opening retrofit markets for legacy fleets.
- Aftermarket Parts Revenue:North American installed base maintenance creates recurring demand for diaphragm kits, valve assemblies, and compressor components as service intervals extend.
Industry Challenges
- Homologation Timeline Compression:Divergence between national noise ordinances and railway-specific safety exemptions in urban densification zones complicates certification cycles for cross-border rolling stock.
- Tunnel Access Constraints:Metro maintenance windows limit compressor serviceability, forcing electric horn adoption despite pneumatic superiority in sound projection and temperature resilience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Horn Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Pneumatic, Electric, Mechanical, Digital Application: Freight Trains, Passenger Trains, Metro Systems, Light Rail Power Source: Battery-Powered, AC-DC Powered, Solar-Powered, Manual Installation: Roof-Mounted, Under-Chassis, Portable, Integrated |
| Companies Covered | Leslie Controls, Inc., Alstom SA, Nathan Airchime, LLC, Webber Manufacturing, Nathan Manufacturing, Buell Air Horns, Gustin Bacon Mfg. Co., Kirby-Leslie Horns, Wabtec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Horn Market Evolving Landscape
Acoustic engineering and materials science are converging to redefine horn performance benchmarks, while regulatory fragmentation and procurement centralization reshape how manufacturers compete for specification.
Electromagnetic compatibility integration is unifying horn modules with broader train communication networks. Metro operators in India and Southeast Asia are specifying factory-installed systems to reduce tunnel maintenance exposure. This convergence is compressing the addressable market for standalone pneumatic suppliers and favoring signaling system integrators.
TSI noise and interoperability standards from the EU Agency for Railways are mandating frequency range harmonization across cross-border rolling stock. Manufacturers must redesign acoustic profiles to satisfy multiple national exemptions simultaneously. Freight corridors linking Germany, Poland, and Czech Republic are experiencing the steepest compliance cost escalation.
Buyer consolidation through national tendering authorities is fragmenting channel structures. Indian Railways' centralized procurement through RDSO specifications and Southeast Asian metro development corporations are disintermediating traditional distributor networks. Fleet operators in these markets now negotiate directly with manufacturers for multi-year framework agreements covering horn modules, compressors, and service packages.
Railway Horn Market Segmentation
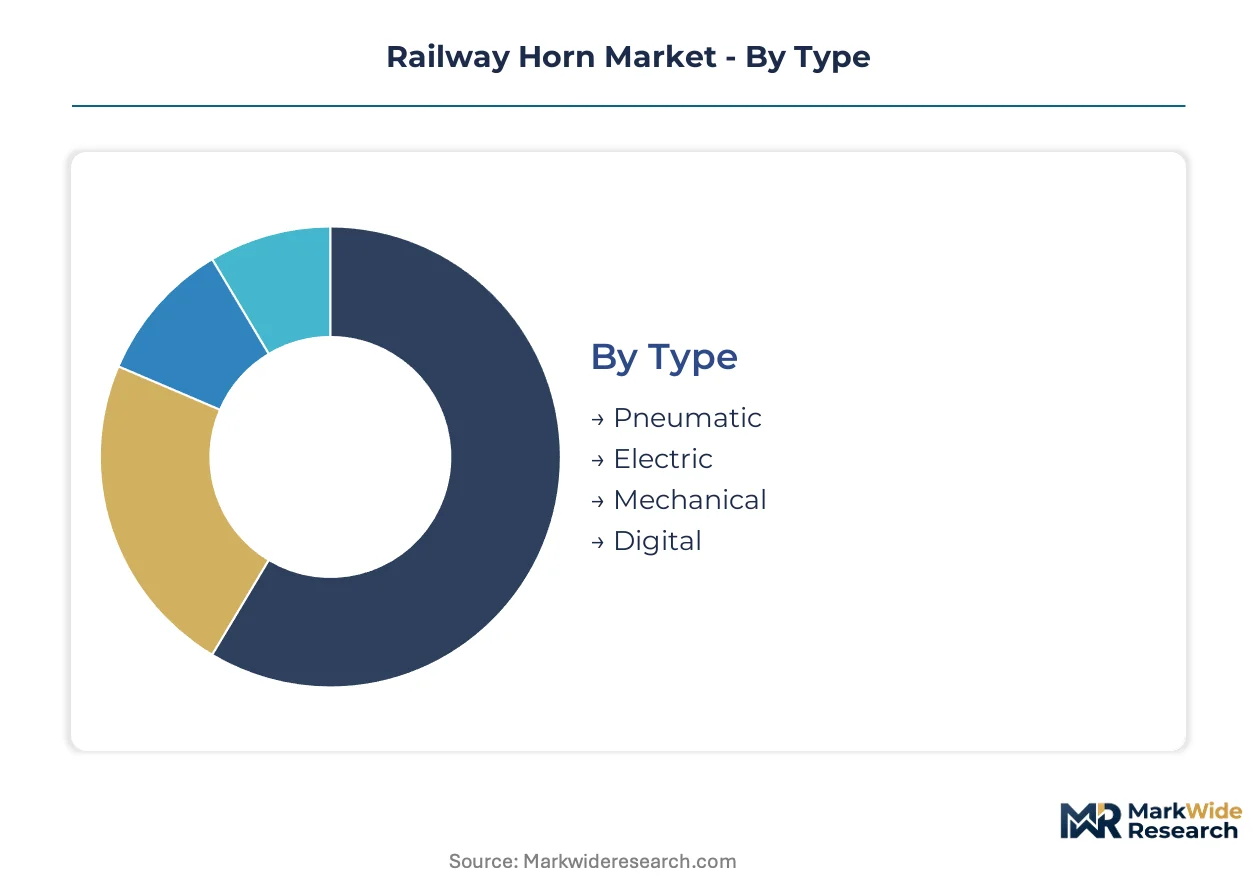
Railway horn procurement patterns diverge sharply across operational contexts, with regulatory mandates and infrastructure constraints dictating specification choices. Fleet operators select horn types based on compressor availability, tunnel access limitations, and interoperability requirements for cross-border corridors.
Type:
Pneumatic variants require FRA pattern compliance and ERA TSI frequency certification, while electric and digital formats face electromagnetic compatibility testing under EU Agency for Railways and India's RDSO protocols.
- Pneumatic:Compressed air systems operating between 96 and 110 decibels at 100 feet dominate freight corridors and heavy-haul segments. India's Dedicated Freight Corridor specifications mandate standardized pneumatic signaling equipment for interoperability across electrified networks.
- Electric:Electromagnetic coil assemblies eliminate compressor dependency, enabling deployment in metro tunnels where maintenance access is restricted. Bangkok and Jakarta metro systems specify electric variants to reduce tunnel service intervals.
- Mechanical:Legacy lever-actuated designs persist in heritage rail operations and developing markets with limited compressed air infrastructure.
- Digital:Programmable waveform horns with GPS-triggered activation patterns support automatic sounding compliance at public crossings under FRA mandates.
Leading the category by volume: Pneumatic. Growing fastest: Electric.
Application:
Freight corridors prioritize sound projection and temperature resilience, while passenger systems balance acoustic performance with noise ordinance exemptions in urban zones.
- Freight Trains:High-decibel pneumatic horns withstand extreme temperature ranges across North American and Indian freight networks. Aluminum diaphragm assemblies reduce weight while maintaining projection requirements for long-haul consist safety.
- Metro Systems:Electric horn adoption concentrates in Southeast Asian urban buildouts where tunnel maintenance windows constrain compressor serviceability. Ho Chi Minh City and Jakarta procurement specifications favor integrated roof-mounted modules.
- Passenger Trains:Intercity rolling stock requires harmonized frequency ranges for cross-border operation under ERA TSI standards linking Germany, Poland, and Czech Republic corridors.
- Light Rail:Lower-decibel specifications apply to street-level tram systems subject to municipal noise ordinances in dense European and Asian urban centers.
Freight trains command the largest procurement volumes. Metro systems are expanding most quickly.
Power Source:
Battery and AC-DC configurations dominate electrified railway networks, while solar and manual options serve isolated infrastructure segments.
- Battery-Powered:Lithium-ion and lead-acid configurations enable horn operation on non-electrified branch lines and maintenance vehicles. Indian Railways' remote section specifications drive procurement for battery-backed pneumatic systems.
- AC-DC Powered:Direct integration with locomotive electrical systems supports continuous operation without separate charging infrastructure. Factory-installed specifications from Alstom and Siemens integrate AC-DC horn modules into train-level communication architectures.
- Solar-Powered:Photovoltaic charging supports wayside and portable horn deployments in off-grid track maintenance zones.
- Manual:Hand-operated mechanical horns persist in yard switching operations and emergency backup configurations.
AC-DC powered systems hold the largest installed base. Battery-powered variants are gaining share fastest.
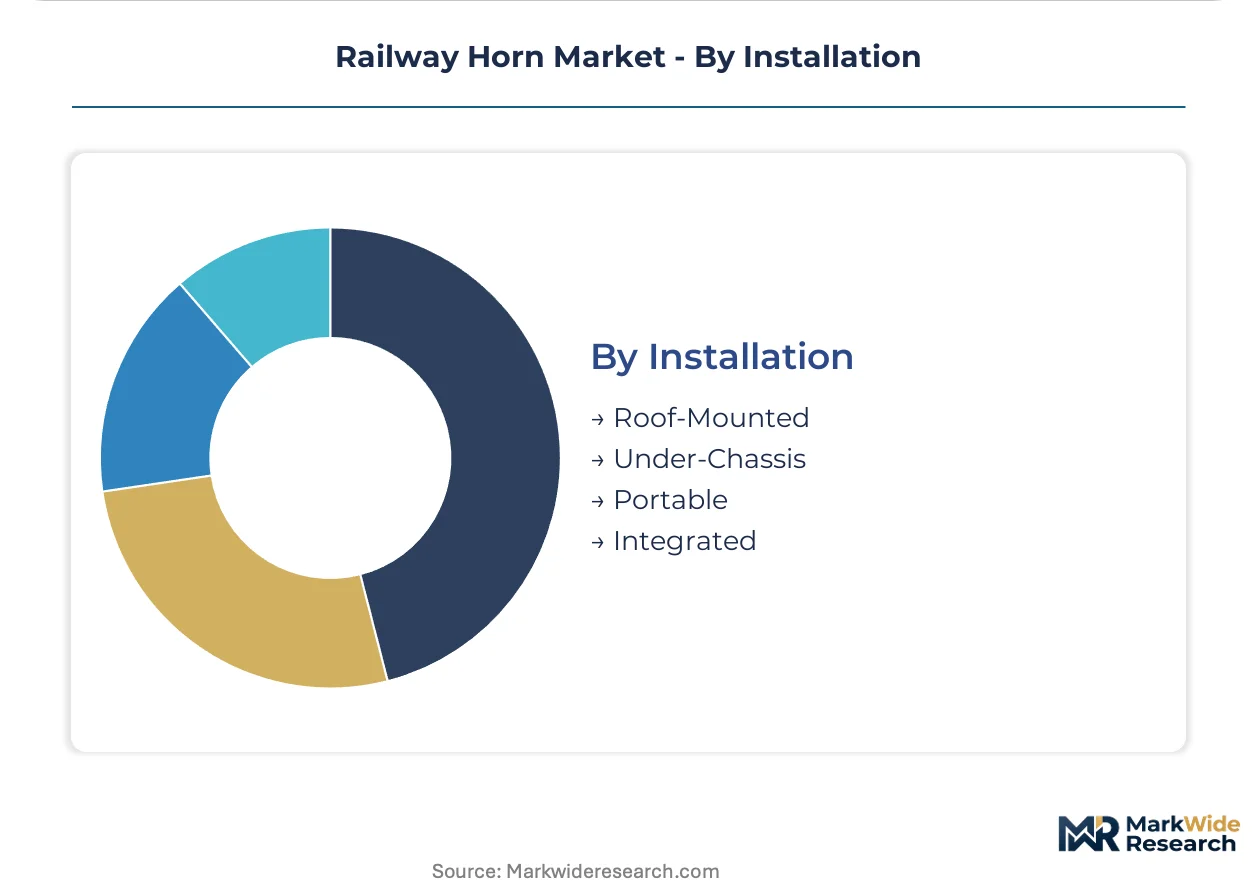
Installation:
Roof mounting captures retrofit demand, while integrated designs streamline OEM homologation for new-build trainsets.
- Roof-Mounted:External installation above the operator cab maximizes sound projection while enabling field replacement of diaphragm assemblies. India's metro buildouts specify standardized roof mounting patterns for fleet commonality.
- Integrated:Factory-installed horn modules bundled with new-build trainsets reduce homologation timeline compression risks. Southeast Asian metro development corporations negotiate directly with manufacturers for integrated communication system packages.
- Under-Chassis:Concealed mounting protects horn assemblies from weather exposure on high-speed passenger rolling stock.
- Portable:Temporary deployment for track maintenance zones and construction site safety requires battery or manual power configurations.
Roof-mounted installations lead by unit volume. Integrated designs show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dedicated Freight Corridor tax incentives and metro development authority procurement zones concentrate railway horn demand across electrified rail corridors in India, Southeast Asian urban buildouts, and North American freight networks.
India
The Dedicated Freight Corridor Corporation and Research Designs and Standards Organisation specifications drive standardized pneumatic horn procurement for electrified freight networks. Indian Railways' centralized tendering through RDSO creates localized manufacturing pools near Jhansi and Varanasi industrial clusters. Metro buildouts in Delhi, Mumbai, and Bengaluru specify roof-mounted electric variants to reduce tunnel maintenance exposure.
United States
Federal Railroad Administration pattern compliance mandates sustain aftermarket demand for diaphragm kits and valve assemblies across Class I railroad installed bases. The FRA's automatic activation system requirements at public crossings generate retrofit procurement for GPS-triggered horn modules. Manufacturing concentrates in Pennsylvania and Ohio foundry clusters serving Wabtec Corporation's North American supply network.
Germany
EU Agency for Railways TSI interoperability standards dictate frequency range harmonization for cross-border rolling stock linking German freight corridors to Poland and Czech Republic networks. ECHA REACH compliance shapes aluminum diaphragm material specifications for reduced-weight horn assemblies. Industrial fabrication clusters in North Rhine-Westphalia and Bavaria supply integrated train-level signaling systems to European OEMs.
Thailand
Bangkok Mass Transit Authority fleet expansion under national railway modernization programs concentrates demand for electric horn modules in tunnel-constrained metro infrastructure. The State Railway of Thailand's procurement specifications favor factory-installed integrated designs to streamline homologation timelines. Manufacturing partnerships cluster in Eastern Economic Corridor zones near Chonburi and Rayong.
Indonesia
Jakarta MRT and LRT buildouts under Ministry of Transportation electrification mandates specify standardized horn signaling equipment for urban fleet procurement. National railway procurement centralization through PT KAI and metro development corporations disintermediates traditional distributor networks. Component assembly concentrates in Bekasi and Tangerang industrial zones serving Southeast Asian rolling stock programs.
Railway Horn Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pneumatic heritage players defending aftermarket positions while signaling integrators capture factory-installed specification share. The vendor base organizes around three archetypes: casting-intensive heritage manufacturers, integrated train-system suppliers, and regional fabrication specialists serving tender-driven procurement markets. Consolidation pressure concentrates in North American aftermarket channels, while Asian buildout markets fragment across national tendering authorities. Dominant competitive moves include backward integration into aluminum diaphragm foundry capacity and technology licensing for automatic activation system deployment.
Among heritage casting specialists, Nathan Airchime, LLC and Leslie Controls, Inc. exemplify the pneumatic-focused archetype with decades of locomotive application expertise. Wabtec Corporation occupies a position bridging aftermarket parts distribution and integrated system supply for North American freight networks. These three entities represent contrasting strategic postures: specialized component heritage versus diversified platform integration versus installed-base service monetization.
| Leading Market Players |
|---|
| Leslie Controls, Inc. |
| Alstom SA |
| Nathan Airchime, LLC |
| Webber Manufacturing |
| Nathan Manufacturing |
| Buell Air Horns |
| Gustin Bacon Mfg. Co. |
| Kirby-Leslie Horns |
| Wabtec Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FRA-compliant pneumatic assemblies and standard electric modules manifests in divergent procurement economics and sourcing footprints. Premium-tier pneumatic horns draw from specialized North American foundry capacity, while commodity electric variants source from dispersed Asian fabrication clusters serving metro buildouts.
Pricing Analysis
High-volume freight fleet procurement compresses per-unit margins on standardized pneumatic equipment, while low-volume integrated signaling packages retain pricing power through factory-installed specification capture. Price differentiation separates FRA-certified brass-diaphragm heritage designs from aluminum-diaphragm economy tiers and digital GPS-triggered premium modules. Pricing pressure stems from copper and aluminum commodity volatility feeding raw material cost escalation. Class I railroad procurement teams exhibit highest price sensitivity due to fleet-scale volume leverage, whereas Southeast Asian metro development corporations prioritize homologation speed over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle integrated train-level signaling demand from Alstom and Siemens, while distributor networks serve aftermarket diaphragm and valve replacement for North American freight operators. Geographic supply concentration centers on Pennsylvania and Ohio foundry clusters for heritage casting, Eastern Economic Corridor zones in Thailand for Southeast Asian assembly, and Jhansi-Varanasi industrial corridors for Indian Railways procurement. Raw material dependencies include copper electromagnetic coils, aluminum diaphragm sheet, and specialized brass casting alloys. Single-source vulnerability concentrates in high-decibel locomotive horn housing foundries. Distribution runs through national tendering authorities in India and Indonesia that disintermediate traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
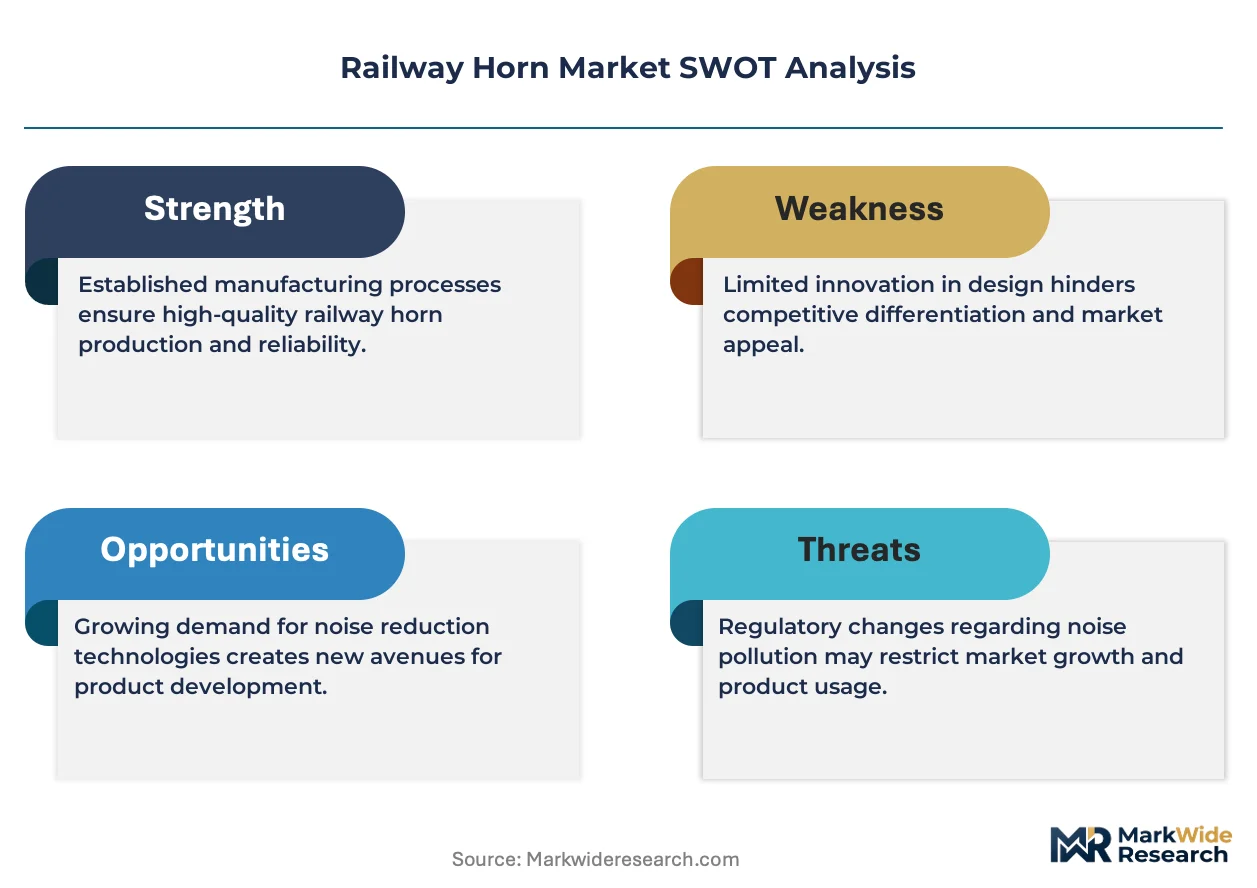
Specialized foundry capacity constraints for FRA-compliant brass casting prop pricing power for incumbent heritage manufacturers. Supply bottlenecks in acoustic housing fabrication limit rapid scale-up by challengers.
For Market Incumbents: To counter electric horn displacement in tunnel-constrained metro segments, backward integration into aluminum diaphragm foundry capacity secures cost structure control against commodity volatility. Incumbents should deepen captive supply of compressor valve assemblies to defend aftermarket parts revenue streams from Asian contract manufacturers. For New Entrants and Emerging Players: National tendering authorities in Indonesia and Thailand present accessible procurement channels for integrated electric horn modules. Battery-powered configurations for Indian Railways' non-electrified branch lines offer the most penetrable white-space segment. New entrants should pursue direct framework agreements with metro development corporations, bypassing legacy distributor networks. For Investors and Strategic Acquirers: Re-rating potential sits with signaling system integrators given convergence of horn modules into train-level communication architectures. Long-term viability favors manufacturers with captive casting capacity and RDSO certification credentials. Investors should monitor Indian Railways' centralized procurement volume as the inflection indicator for sector pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diaphragm Foundry Capacity | Captive aluminum casting supply insulates margin structures from LME price volatility. |
| RDSO Certification Investment | Indian Railways' centralized tendering requires domestic manufacture compliance for specification access. |
| Automatic Activation System Development | GPS-triggered FRA pattern compliance opens retrofit markets across Class I railroad installed bases. |
| Integrated Signaling Architecture Partnership | Factory-installed horn modules bundled with Alstom and Siemens train systems streamline homologation. |
| Eastern Economic Corridor Manufacturing Footprint | Thailand's zone incentives position suppliers for Bangkok MRT and Jakarta metro procurement cycles. |
Research Methodology
Document review covered FRA safety advisories, ERA TSI interoperability standards, and Indian Railways RDSO specifications, complemented by interviews with fleet procurement directors at Class I railroads, metro development authority engineers in Southeast Asia, and foundry operations managers in North American industrial clusters. Secondary validation drew from customs trade data for aluminum and copper imports, rolling stock production databases, and tender documentation from India's Dedicated Freight Corridor Corporation. Bottom-up unit demand estimates and top-down market sizing were triangulated for convergence.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include horn type, application context, power source configuration, and installation method. CAGRs were derived from rolling stock fleet expansion schedules and electrification mandate timelines. Forecast inputs incorporated tunnel access constraints driving electric horn substitution and commodity price assumptions for diaphragm materials.
Caveats apply where Indian Railways procurement centralization shifts or ERA TSI frequency standard revisions could materially shift the outlook. Forecasts reflect assumptions about Dedicated Freight Corridor completion schedules and Southeast Asian metro buildout pacing. Periodic stress-testing of base assumptions against tender award volumes and foundry capacity utilization is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Train Bogie Market
Railway
Global Smart Locomotive Market
Railway
South Africa Rail Freight Transport Market
Railway
Rail Maintenance Management System Market
Railway
Global Train Lighting Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Heritage Railways Trains Market
Railway
Locomotive Parking Brake Market
Railway
Automatic Train Operation System Market
Railway
Railway Bearing Market
Railway
France Connected Rail Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
Latin America Connected Rail Market
Railway
Rail Glazing Market
Railway
Check Rails Market
Railway
Railcar Vehicle Toilet Market