
 Smart Railways Market | 2026-2036
Smart Railways Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Railways Market Intelligence
India's extensive railway network expansion is fragmenting the traditional supply base for signaling and control systems. Siemens Mobility leverages its deep expertise in automated train control to secure major urban transit projects. Alstom competes through its comprehensive portfolio of digital mobility solutions and advanced rolling stock. Meanwhile, Hitachi Rail differentiates with its integrated approach, combining rolling stock, signaling, and maintenance services.
Smart railways integrate advanced digital technologies into rail infrastructure to enhance operational intelligence and automation. This involves deploying IoT sensors on tracks and trains to transmit real-time data on asset health and location. The primary purpose is to improve safety, optimize fleet management, and increase network capacity. The adoption of AI & Machine Learning enables high-value applications like predictive maintenance, while cloud-based platforms are becoming central for data aggregation and analysis across an entire network.
Regulatory frameworks like the EU's Technical Specifications for Interoperability (TSIs) and China's GB standards define core requirements for new systems. These standards mandate specific safety integrity levels and data communication protocols, influencing technology choices for rail operators. Rail operators must now decide between adopting proprietary, integrated solutions or pursuing more flexible, open-standard architectures for future deployments.
Market Dynamics
The smart railways market is shaped by the tension between proprietary, vertically integrated technology stacks and the push for open-standard architectures. This conflict influences technology adoption for rail operators, forcing a choice between single-vendor ecosystems and flexible, interoperable solutions.
Growth Catalysts
- EU Interoperability Mandates:The EU's Technical Specifications for Interoperability (TSIs) mandate standardized digital systems, driving demand for compliant technologies for cross-border traffic.
- Predictive Maintenance Demand:Freight operators demand IoT and AI predictive maintenance to cut asset downtime and improve fleet efficiency.
- 5G for Mission-Critical Communication:5G deployment offers low-latency connectivity essential for real-time automated train control and high-volume data transmission.
Market Restraints
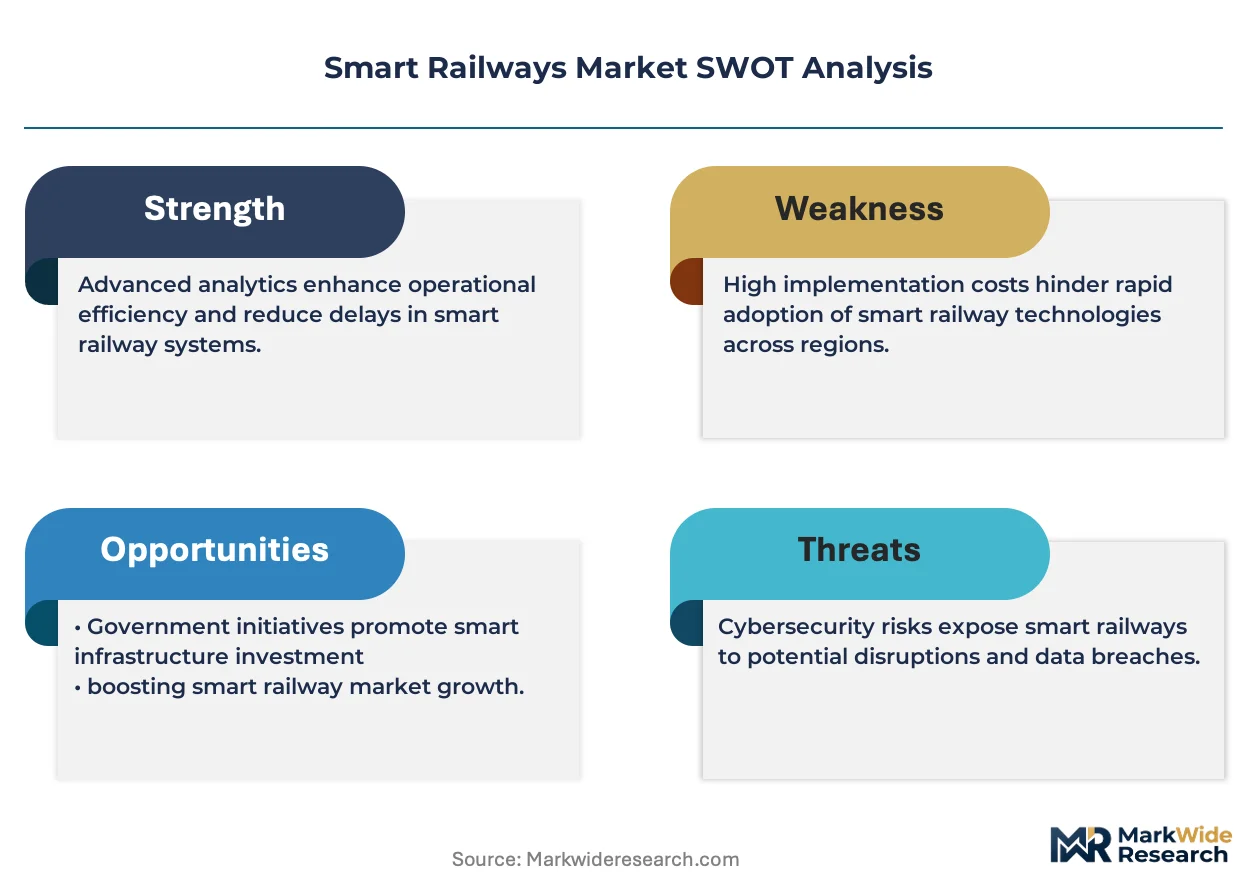
- High Capital Expenditure:High upfront investment to retrofit legacy infrastructure with new sensors and control centers is a primary barrier for operators.
- Legacy System Integration:Integrating new digital technologies with existing proprietary signaling systems presents significant technical complexity and cost, slowing modernization.
- Vendor Lock-In:A concentrated supply base for safety-critical control systems creates a high risk of vendor lock-in, limiting operator flexibility and increasing long-term costs.
Strategic Opportunities
- Southeast Asian Network Expansion:Infrastructure projects in nations like Indonesia and Vietnam offer greenfield opportunities for deploying smart railway systems without legacy constraints.
- Cybersecurity as a Service:The connectivity of rail networks creates demand for specialized cybersecurity services to protect operational technology systems from digital threats.
- Digital Twin Integration:Combining AI with digital twin models allows for advanced network simulation, optimizing timetabling, energy consumption, and maintenance schedules.
Industry Challenges
- Specialized Skills Gap:Rail operators face a shortage of personnel with expertise in data science, AI, and cybersecurity, which is critical for managing new smart systems.
- Interoperability and Integration:A lack of universal data standards complicates integration between multi-vendor systems, creating operational hurdles and delaying the realization of network-wide benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Railways Market |
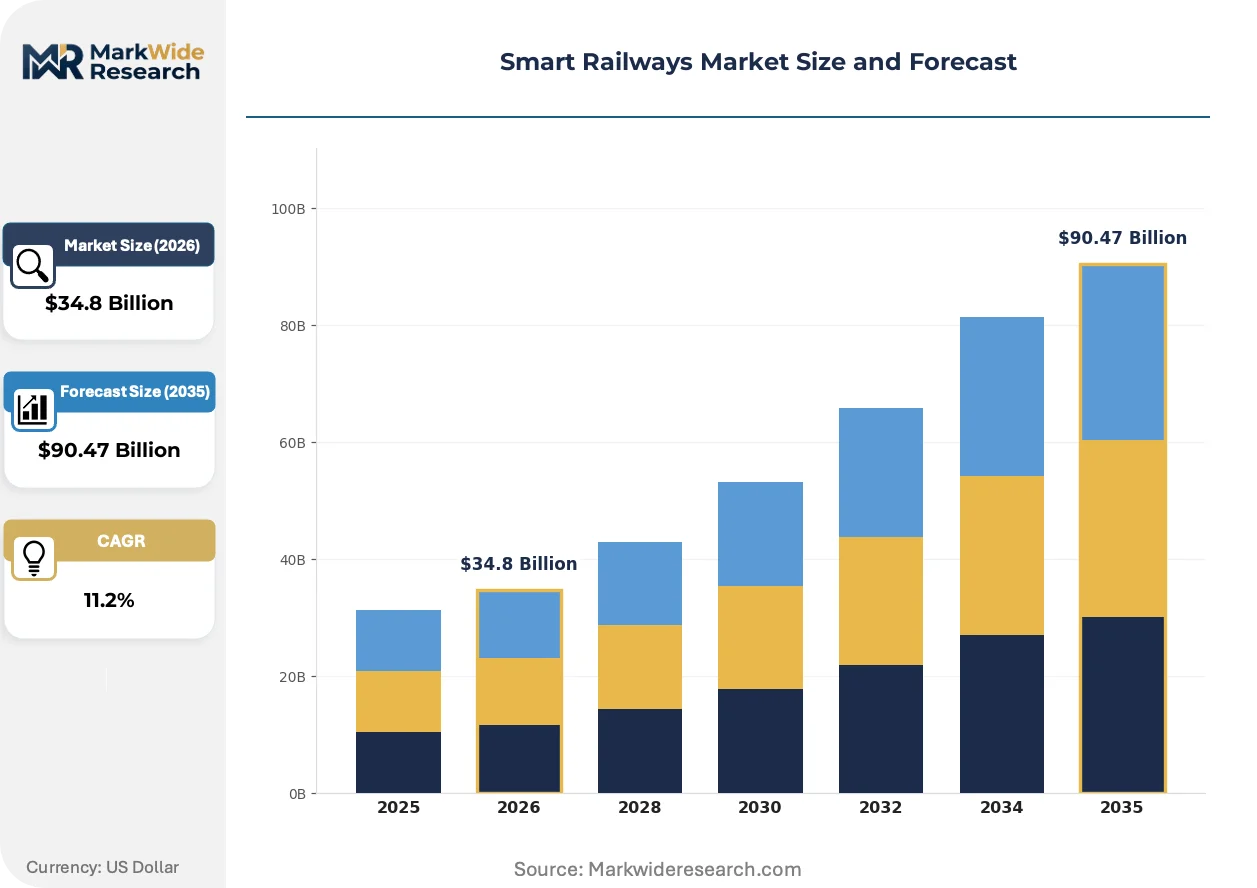
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $90.47 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, Cloud Computing, AI & Machine Learning, Big Data Analytics, Automated Signaling, Edge Computing Application: Passenger Safety, Predictive Maintenance, Fleet Management, Real-Time Tracking, Energy Management, Ticketing Automation End User: Rail Operators, Infrastructure Managers, Freight Controllers, Public Transit Authorities, Maintenance Contractors, Technology Providers Deployment: Onboard Systems, Trackside Systems, Control Centers, Cloud-Based Platforms, Hybrid Solutions, Mobile Applications |
| Companies Covered | Siemens Mobility, Alstom, Hitachi Rail, Cisco Systems, Huawei Technologies, Thales Group, Wabtec Corporation, ABB, Indra Sistemas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Railways Market Strategic Shifts & Innovations
A fundamental shift from hardware-centric infrastructure to software-defined, data-driven operations is reshaping the market. This transition prioritizes operational intelligence and automated decision-making over traditional mechanical engineering, creating new value streams.
Cloud-based Traffic Management Systems (TMS) centralize network-wide operational data, enabling real-time monitoring and control from a single platform. Major urban transit authorities and national freight lines are adopting these platforms to improve capacity and service reliability. This software-centric approach is rendering obsolete the need for disparate, locally-managed control systems, consolidating operational command.
The EU AI Act introduces risk-based requirements for artificial intelligence systems, including those used in critical railway infrastructure. This regulation mandates rigorous testing, transparency, and human oversight for AI applications like predictive maintenance and automated train operation. Developers must now embed 'safety-by-design' principles and create auditable AI models to ensure compliance for systems deployed in the EU.
Rail operators are shifting from large capital expenditures for technology acquisition to subscription-based and 'as-a-Service' models. This approach for software and analytics displaces traditional procurement cycles, tying costs more directly to operational outcomes and performance. The shift is most visible in North America and Europe, where operators convert capital costs into predictable operating expenses.
Smart Railways Market Segmentation
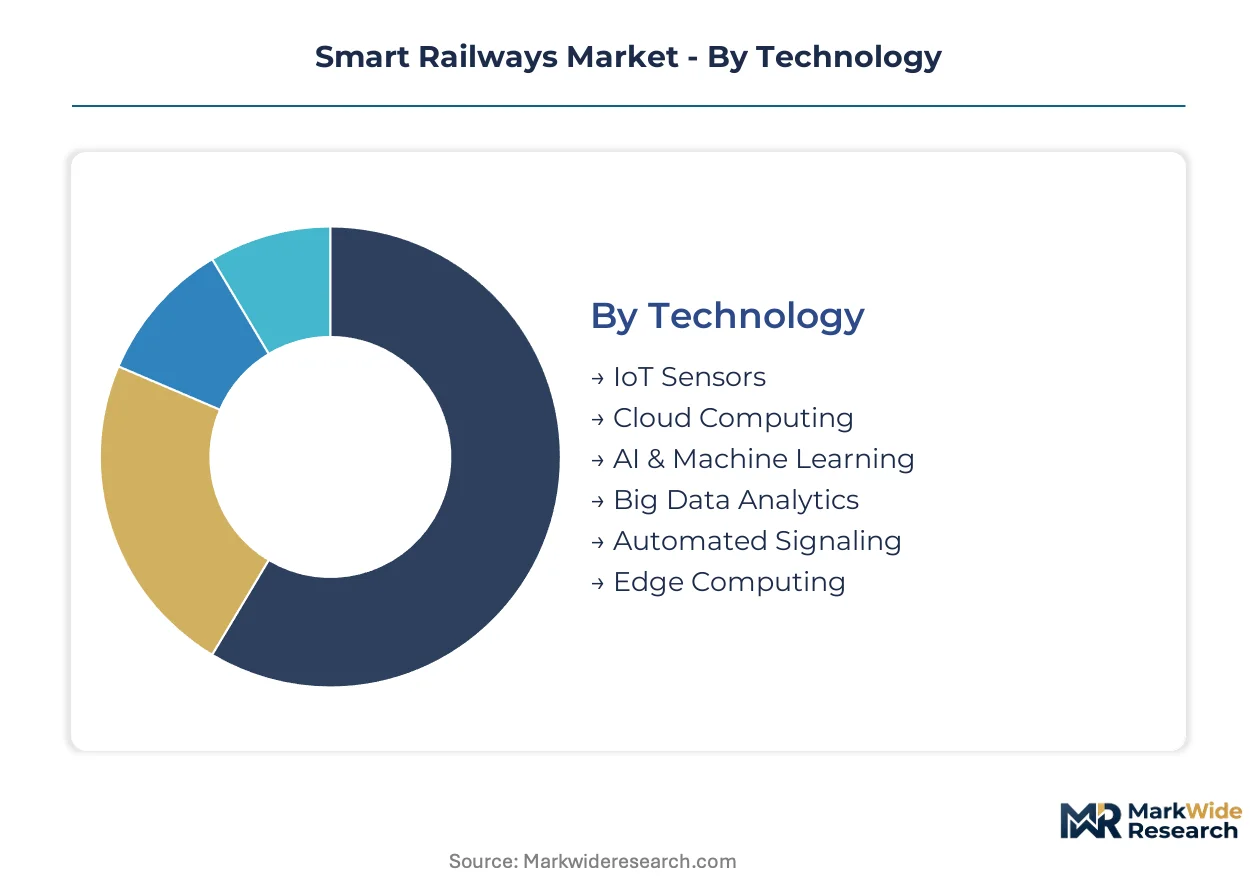
Market segmentation provides a granular view of the smart railways ecosystem, highlighting distinct technology components, operational applications, and end-user groups. Understanding these divisions helps stakeholders identify areas of concentrated demand and emerging growth vectors within the industry.
Technology:
The technology dimension delineates the foundational digital components enabling smart railway operations.
- IoT Sensors:These devices collect real-time data on asset health, environmental conditions, and train location from tracks and rolling stock. Demand for IoT sensors is concentrating in India due to extensive infrastructure investments, driving predictive maintenance solutions.
- AI & Machine Learning:These advanced algorithms process vast datasets to enable predictive analytics, automated decision-making, and optimized operational efficiencies. AI and machine learning adoption is being driven by freight controllers seeking to improve fleet efficiency and reduce downtime.
- Cloud Computing:Centralized platforms aggregate and analyze network-wide operational data, supporting real-time monitoring and control.
- Big Data Analytics:Tools and processes extract insights from large, complex datasets generated by railway operations, informing strategic decisions.
- Automated Signaling:Systems use digital controls to manage train movements, ensuring safety and optimizing network capacity.
- Edge Computing:Data processing occurs closer to the source, reducing latency for mission-critical applications like automated train control.
Automated Signaling holds installed capacity. IoT Sensors are rotating up the share rankings.
Application:
Operational utility defines the application segment, reflecting how smart railway technologies deliver tangible benefits.
- Predictive Maintenance:This application uses data analytics and AI to forecast equipment failures, minimizing unplanned downtime and optimizing maintenance schedules. Freight operators in North America are increasingly demanding predictive maintenance solutions to cut asset downtime.
- Passenger Safety:Technologies like advanced surveillance, real-time monitoring, and automatic incident detection enhance security and emergency response for travelers. Public transit authorities across Europe prioritize passenger safety applications to meet stringent regulatory requirements.
- Fleet Management:Solutions optimize the utilization and scheduling of rolling stock, improving operational efficiency and reducing costs.
- Real-Time Tracking:Systems provide precise location data for trains and assets, enhancing operational visibility and logistical planning.
- Energy Management:Applications monitor and optimize energy consumption of trains and infrastructure, reducing operational expenses.
- Ticketing Automation:Digital systems streamline fare collection and passenger access, improving convenience and operational flow.
Predictive Maintenance solutions are expanding most quickly. Passenger Safety applications maintain a significant market presence.
End User:
The customer type segment identifies the primary beneficiaries and decision-makers for smart railway system deployment.
- Rail Operators:These entities manage train services, requiring smart systems for fleet optimization, safety, and passenger services. European rail operators are shifting towards subscription-based models for software and analytics, influencing procurement.
- Freight Controllers:Organizations responsible for freight movement demand smart solutions for predictive maintenance and real-time tracking to ensure efficient logistics. Demand from freight controllers for predictive maintenance solutions is a key growth area for the market.
- Infrastructure Managers:Entities responsible for tracks, signals, and stations utilize smart technologies for asset health monitoring and network capacity management.
- Public Transit Authorities:Urban and regional transit bodies adopt smart systems for passenger safety, ticketing, and operational control.
- Maintenance Contractors:Third-party service providers use smart tools for efficient repair and upkeep of railway assets.
- Technology Providers:Companies developing and supplying smart railway hardware and software solutions serve as key market participants.
Rail Operators represent the largest direct customer base. Freight Controllers are gaining share fastest among specialized users.
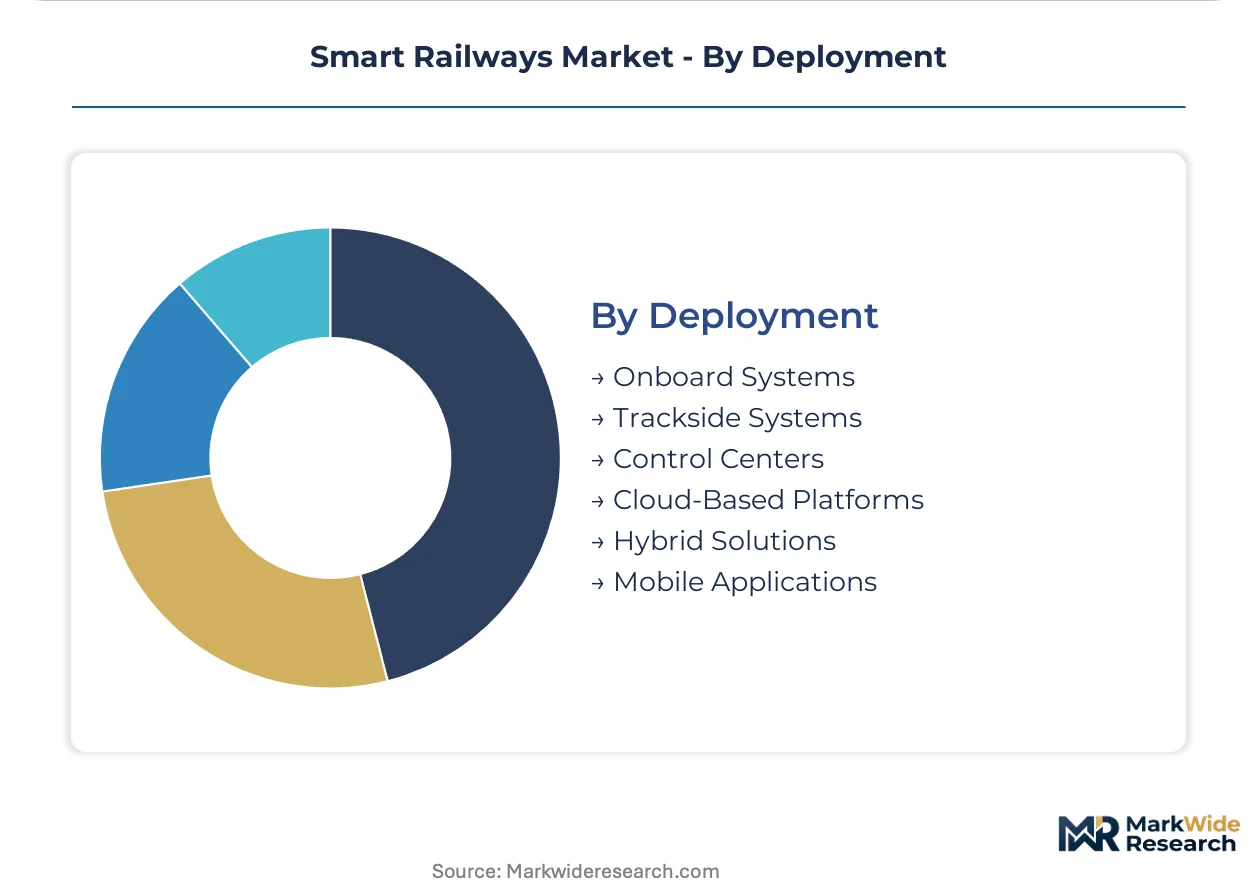
Deployment:
The deployment dimension categorizes where smart railway technologies are physically implemented and managed.
- Cloud-Based Platforms:These centralize network-wide operational data and control, enabling real-time monitoring from a single interface. Major urban transit authorities are adopting these platforms to improve capacity.
- Onboard Systems:Technologies integrated directly into trains, including sensors, communication devices, and control units, provide real-time operational data. These systems are critical for automated train control and passenger safety applications.
- Trackside Systems:Equipment installed along railway lines, such as sensors, signaling apparatus, and communication infrastructure, monitors track conditions and train movements.
- Control Centers:Centralized facilities equipped with advanced software and human interfaces manage and coordinate entire railway networks.
- Hybrid Solutions:Combinations of onboard, trackside, and cloud-based systems offer flexible and scalable deployment options.
- Mobile Applications:Software running on portable devices provides operational data, maintenance alerts, or passenger information to personnel and travelers.
Cloud-Based Platforms are seeing the steepest expansion trajectory. Onboard Systems remain a critical point of data generation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart railways market sees technology development concentrating in regions with significant infrastructure investment and regulatory push. Innovation hubs are emerging where new digital systems are deployed. This geographic focus influences global supply dynamics for advanced rail solutions.
India
India's extensive railway network expansion drives demand for IoT sensors and AI-driven predictive maintenance solutions. The Indian Railways' modernization programs, supported by government policies, accelerate technology adoption. New system deployments concentrate in regions like the Delhi-NCR, creating a hub for advanced signaling and control.
Germany
Germany pioneers smart railway deployments, driven by EU interoperability mandates for cross-border traffic and demand for automated train control. The EU AI Act influences the development of compliant AI systems for critical railway infrastructure. Major urban transit projects in cities like Berlin leverage advanced digital technologies for operational efficiencies.
United States
Freight operators in the United States demand predictive maintenance and real-time tracking solutions to optimize fleet efficiency. The Federal Railroad Administration (FRA) mandates safety standards that influence technology choices for rail operators. Key freight corridors in regions like the Midwest, particularly around Chicago, are adopting IoT and AI for operational intelligence.
Indonesia
Indonesia's ongoing infrastructure projects offer greenfield opportunities for deploying smart railway systems without legacy constraints. National railway development plans prioritize digital technologies to enhance network capacity and safety. Significant investments in urban transit in Jakarta are driving the adoption of cloud-based traffic management systems.
China
China's vast high-speed rail network and urban metro systems drive demand for advanced signaling and real-time data analytics. The country's GB standards define core requirements for new systems, influencing technology choices. Major rail hubs in the Yangtze River Delta region are implementing integrated smart solutions for optimized operational intelligence.
Smart Railways Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing foundational hardware and software. The smart railways market exhibits a tiered structure, with large multinational corporations offering comprehensive solutions and niche players focusing on specific technologies. Strategic archetypes include full-service digital mobility providers and specialized signaling system manufacturers. Companies pursue strategic partnerships and portfolio diversification to enhance their market presence.
Within the comprehensive digital mobility solutions archetype, Siemens Mobility, a German multinational, leverages its deep expertise in automated train control. French-based Alstom competes effectively through its extensive portfolio of digital solutions and advanced rolling stock. Japanese conglomerate Hitachi Rail differentiates with its integrated approach, combining rolling stock, signaling, and maintenance services, exemplifying a full-service provider strategy in the smart railways market. These leading players command significant market share through their broad offerings and global reach.
| Leading Market Players |
|---|
| Siemens Mobility |
| Alstom |
| Hitachi Rail |
| Cisco Systems |
| Huawei Technologies |
| Thales Group |
| Wabtec Corporation |
| ABB |
| Indra Sistemas |
| Others |
Cost & Logistics Intelligence
India's concentrated hub for new system deployments drives capacity dynamics, influencing pricing power for smart railway solutions across Asia. This regional focus shapes competitive offerings for both hardware and software.
Pricing Analysis
The EU's Technical Specifications for Interoperability (TSIs) dictates the pricing tier structure for compliant systems, especially for cross-border traffic. Pricing stratifies across project-based contracts for large infrastructure deployments and subscription-based models for software and analytics. Differentiation stems from certified safety integrity levels and the complexity of integrating with legacy systems. Pricing softness stems from high upfront investment requirements for rail operators. Public transit authorities prioritize safety, exhibiting lower price sensitivity for critical solutions, while freight operators remain highly sensitive to overall operational cost reductions.
Supply Chain Analysis
Specialized electronic components and advanced digital modules form the upstream feedstock for smart railway systems. Geographic supply concentration includes India for IoT sensors, Germany for advanced signaling systems, and China for various digital hardware components. Raw material dependencies center on semiconductor chips, 5G communication modules, and AI/ML software libraries. Vendor lock-in presents a structural risk due to the concentrated supply base for safety-critical control systems. Distribution runs through platform integrators like Siemens Mobility and Alstom, which integrate components from specialist suppliers to deliver comprehensive solutions to rail operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart railways market presents a significant service-attach opportunity, with cybersecurity-as-a-service offerings expanding faster than core hardware deployments.
For Market Incumbents: Entrench existing market share by deepening vertical integration into specialized software development, particularly for AI and cybersecurity. Invest in talent development for data science and operational technology security to counter the specialized skills gap. Counter emerging entrants offering open-standard architectures by providing flexible, modular solutions. Leverage established customer relationships to introduce outcome-based service contracts for predictive maintenance.
For New Entrants and Emerging Players: Southeast Asian network expansion offers a geographic underpenetration opportunity for greenfield smart railway deployments. Target cloud-based traffic management systems and cybersecurity-as-a-service offerings as white-space opportunities. The most penetrable segment lies in providing open-standard, interoperable solutions for new urban transit projects. A go-to-market angle focusing on lower total cost of ownership through flexible subscription models can attract cost-conscious operators.
For Investors and Strategic Acquirers: Carve-out targets emerge from large industrial conglomerates seeking to divest non-core digital or software divisions. The market demonstrates long-term viability, driven by persistent demand for enhanced safety and operational efficiency across rail networks. Acquisition targets should include specialized firms in AI/ML analytics, digital twin technology, or cybersecurity for operational technology (OT). Monitor the EU AI Act's evolving compliance requirements as a key inflection indicator for investment in auditable AI systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered predictive maintenance solutions | Enhances asset uptime for freight operators, improving fleet efficiency. |
| Integrate cloud-based Traffic Management Systems | Centralizes operational data for urban transit authorities, boosting network capacity. |
| Form strategic partnerships with 5G providers | Ensures low-latency connectivity for automated train control and real-time data. |
| Acquire specialized cybersecurity firms | Protects critical operational technology systems from increasing digital threats. |
| Target greenfield infrastructure projects in Southeast Asia | Captures new system deployment opportunities without legacy integration constraints. |
Research Approach
Cross-validation between primary interviews and regulatory filings anchors the qualitative findings of this market study. The process involved extensive discussions with rail operators, freight controllers, infrastructure managers, and technology providers. Secondary validation utilized government railway reports, company annual reports, and industry association publications, ensuring robust data triangulation from both bottom-up and top-down perspectives.
Market size calibration across the analysis window involves a multi-stage approach, integrating historical growth trends with projected technology adoption rates. The analytical framework modeled key segmentation dimensions including Technology, Application, End User, Deployment, and regional regulatory frameworks. Compound annual growth rates were derived from a combination of market demand drivers and industry-specific forecast inputs, such as infrastructure investment plans and smart system deployment roadmaps.
Practitioners should monitor major infrastructure policy shifts and rapid technological advancements for early signals of market revision. Forecasts reflect assumptions regarding economic stability and regulatory continuity over the projection horizon. Cross-checking against national railway development plans and industry investment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Sanitary Systems for Rail Transit Market
Railway
France Connected Rail Market
Railway
Check Rails Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Heritage Railways Trains Market
Railway
Automatic Train Control Market
Railway
Railway Horn Market
Railway
Railway Braking System Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
40-Foot Platform Wagons Market
Railway
Rail Transit Traction Converter Market
Railway
Freight Cars Market
Railway
Locomotive Maintenance Market
Railway
Railway Management System Market
Railway
South Africa Rail Freight Transport Market
Railway
Tugger Trains Market