
 Railway Braking System Market | 2026-2036
Railway Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Braking System Market Outlook
Multi-source procurement for brake control electronics is shifting toward captive in-house production among tier-one suppliers. Knorr-Bremse AG leverages its vertically integrated valve manufacturing to secure long-term OEM contracts. Wabtec Corporation anchors North American freight retrofit demand through distributed power braking platforms. Faiveley Transport competes in European high-speed rail with integrated electropneumatic architectures.
A railway braking system controls deceleration and stopping of rolling stock through friction, electromagnetic, or regenerative energy conversion, typically operating at brake cylinder pressures of 3.5 to 5.0 bar in pneumatic configurations. Electromagnetic technology leads in high-speed train installations where non-contact braking reduces thermal wear, while regenerative systems capture the fastest growth as operators prioritize energy recovery over friction-dependent disc brakes. Urban transit applications sustain the largest installed base of disc and drum brake hardware due to frequent stop-start cycles and lower maximum speeds.
EU F-Gas Regulation and REACH compliance constrain hydraulic brake fluid formulations across European networks, while China's NMPA and GB standards enforce electromagnetic compatibility testing for domestically produced control units. India's CEA rail electrification mandates indirectly expand regenerative braking deployment on newly electrified corridors. Stakeholders must monitor evolving interoperability standards between national rail networks and assess whether regional certification requirements will fragment supplier qualification pathways.
Market Dynamics
The railway braking system market is being fundamentally restructured by the EU F-Gas Regulation and EU Green Deal mandates, which are forcing a technology transition from hydraulic and pneumatic friction systems toward electromagnetic and regenerative architectures across European networks.
Growth Catalysts
- EU Green Deal decarbonization targets:Mandates for energy-efficient rail transport are accelerating regenerative braking deployment on newly electrified corridors, particularly in freight applications where energy recovery delivers measurable operating cost reductions.
- China's high-speed rail expansion:CRRC-led fleet procurement programs are generating concentrated demand for electromagnetic brake systems capable of handling sustained speeds above 300 km/h without thermal degradation.
- India's Dedicated Freight Corridor electrification:CEA rail electrification mandates are indirectly expanding regenerative braking infrastructure across 1,500 km of new freight routes, creating hardware demand for both locomotive and wagon-mounted systems.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electromagnetic brake manufacturing depends on neodymium and dysprosium supply chains concentrated in Chinese processing facilities, exposing OEMs to input price swings and export restriction risks.
- REACH compliance friction for hydraulic fluids:ECHA substance restrictions are forcing reformulation of brake fluids used in legacy pneumatic systems, creating certification bottlenecks for suppliers serving mixed-fleet operators.
- Technical limitation in extreme cold climates:Regenerative braking efficiency degrades below minus 25 degrees Celsius, forcing operators in Nordic networks and Russian corridors to retain friction-based backup systems and dual infrastructure.
Strategic Opportunities
- Underpenetrated African rail modernization:Kenya's Standard Gauge Railway and planned Tanzania-Uganda extensions represent greenfield opportunities for integrated braking system suppliers able to finance turnkey electrification packages.
- Technology convergence of braking and traction control:Integration of electropneumatic brake controllers with predictive energy management software is creating premium system architectures for high-speed operators seeking unified train control platforms.
- EU F-Gas Regulation phase-down incentives:Accelerated depreciation allowances for electromagnetic brake retrofits are creating aftermarket demand among European freight operators seeking to avoid hydraulic fluid compliance costs.
Industry Challenges
- Electromagnetic compatibility certification complexity:China's NMPA and GB standards require extensive EMC testing for control units, extending product qualification timelines by 8-14 months for foreign suppliers without domestic testing partnerships.
- Integration complexity with legacy pneumatic networks:Mixed-fleet operators running pre-2000 rolling stock face interoperability failures when installing modern brake controllers, requiring costly gateway valve retrofits or partial fleet standardization.
- Skill gap in mechatronic maintenance:Electromagnetic brake systems demand technicians trained in both mechanical friction component replacement and power electronics diagnostics, a combination scarce in traditional rail maintenance workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Braking System Market |
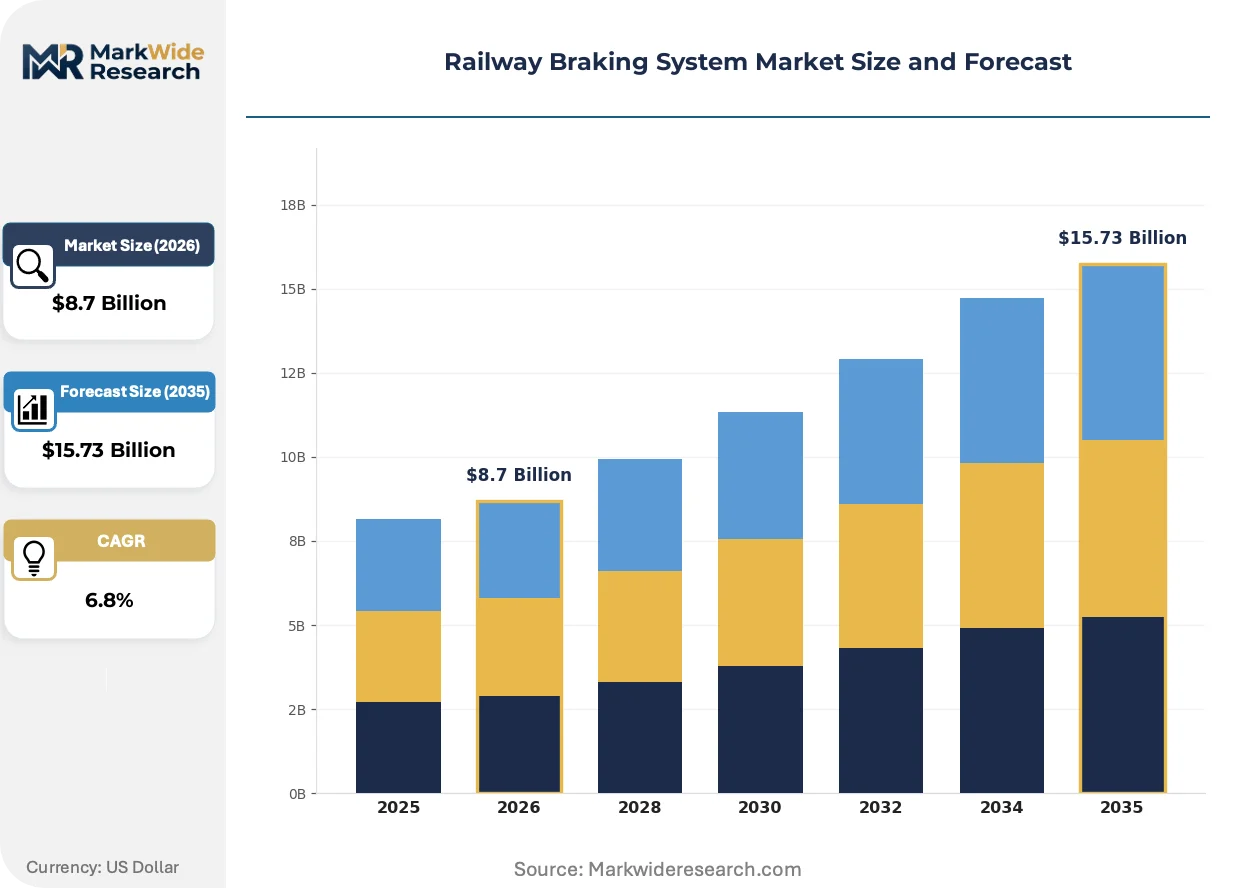
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electromagnetic, Pneumatic, Hydraulic, Mechanical Application: High-Speed Trains, Freight Trains, Urban Transit, Light Rail End User: Government, Private Operators, Manufacturers, Maintenance Providers Product Type: Disc Brakes, Drum Brakes, Regenerative Brakes, Anti-lock Braking Systems |
| Companies Covered | Knorr-Bremse AG, Wabtec Corporation, Faiveley Transport, CRRC Corporation Limited, Alstom SA, Nabtesco Corporation, Hitachi Rail, Akebono Brake Industry Co Ltd, Amsted Rail Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Braking System Market Strategic Shifts
Active technology integration is compressing the traditional separation between braking hardware and train control software, with suppliers embedding predictive algorithms directly into brake control units to optimize energy recovery and wear management in real time.
Electropneumatic brake architectures are integrating machine-learning-based friction coefficient estimation to replace fixed braking curves with adaptive deceleration profiles. European high-speed operators including SNCF and Deutsche Bahn are piloting these systems on ICE and TGV fleets, enabling 12-18 percent reduction in disc wear while maintaining safety margins. This integration is compressing the aftermarket for generic brake pad suppliers by tying consumables to proprietary control algorithms.
EU F-Gas Regulation phase-down schedules are forcing hydraulic brake fluid manufacturers toward PFAS-free formulations by 2030. ECHA restriction proposals are triggering premature obsolescence of mineral-oil-based systems in Scandinavian networks, where environmental liability risks outweigh retrofit costs. Freight operators in Germany and Austria are responding by accelerating electromagnetic brake conversion programs ahead of regulatory deadlines.
After-sales service unbundling is disrupting traditional brake system procurement, with operators separating hardware purchase from maintenance contracts to capture efficiency gains through third-party predictive analytics providers. Japanese Shinkansen operators and Singapore's MRT are leading this shift, contracting brake wear monitoring to independent sensor networks rather than OEM service arms. This pattern is most visible in urban transit systems with dedicated infrastructure budgets and centralized fleet management.
Railway Braking System Market Segmentation
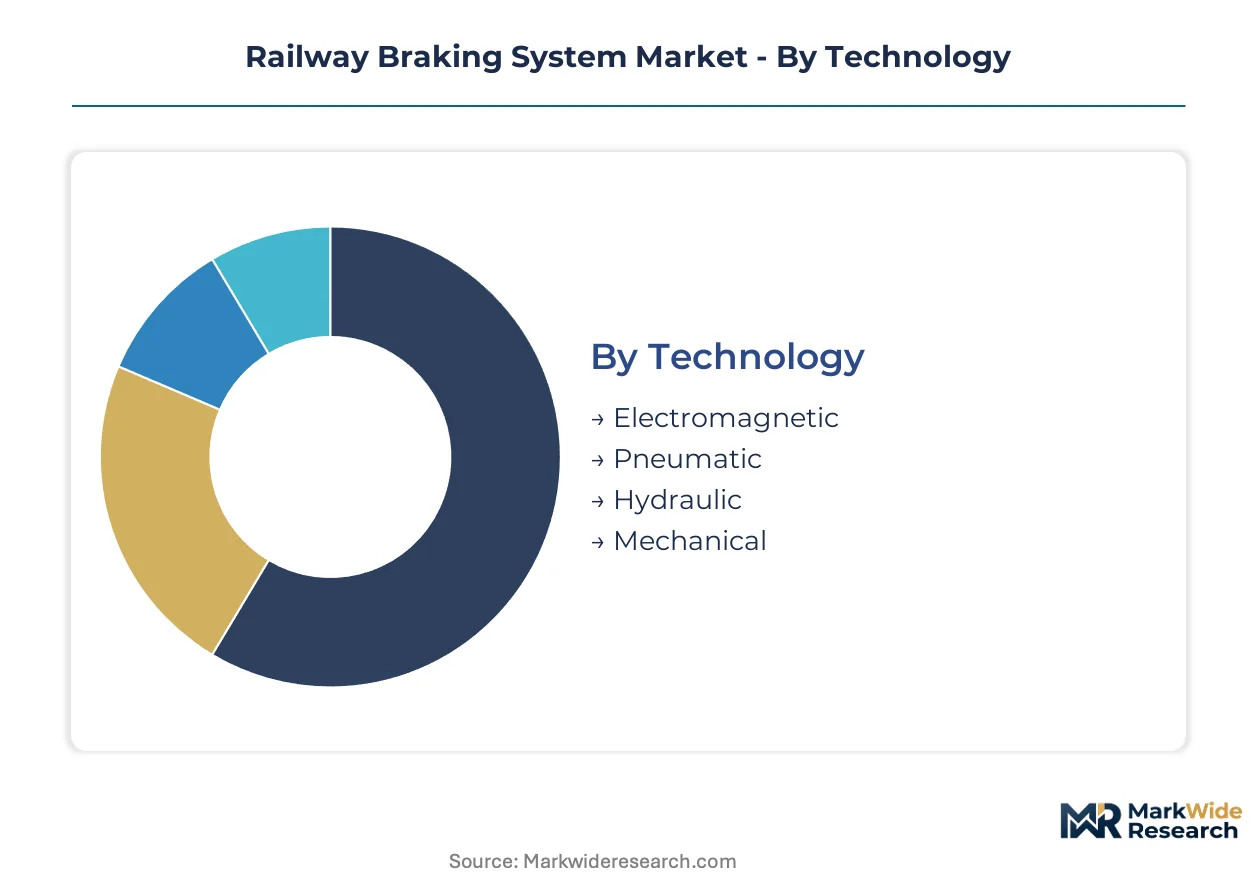
Brake system procurement diverges sharply across operational contexts. High-speed corridors demand thermal-resistant electromagnetic architectures, while freight networks prioritize energy recovery economics and urban transit optimizes for stop-cycle durability.
Technology:
Specification requirements vary by thermal load, response latency, and infrastructure compatibility.
- Electromagnetic:Non-contact braking via eddy current or linear motor induction eliminates friction wear at sustained speeds above 300 km/h. CRRC procurement for China's expanding high-speed network concentrates demand here, though neodymium supply exposure constrains OEM pricing flexibility.
- Pneumatic:Compressed air systems operating at 3.5–5.0 bar cylinder pressure remain dominant in legacy freight and mixed-fleet operations. India's Dedicated Freight Corridor electrification sustains demand for electropneumatic hybrid controllers compatible with existing wagon infrastructure.
- Hydraulic:Fluid-pressure systems serve niche applications requiring compact actuation force.
- Mechanical:Direct friction linkages persist in heritage rail and extreme cold-climate backup systems.
Mature deployment sits with Pneumatic systems. Newer deployment is concentrated in Electromagnetic architectures.
Application:
Operational velocity and duty cycle dictate brake system selection and replacement frequency.
- High-Speed Trains:Sustained velocities above 250 km/h mandate electromagnetic primary braking with pneumatic emergency backup. SNCF and Deutsche Bahn piloting adaptive friction coefficient algorithms on ICE and TGV fleets are reshaping supplier qualification requirements.
- Freight Trains:Heavy-haul electrification prioritizes regenerative energy recovery to reduce operating costs across kilometer-long consists. Germany and Austria accelerate electromagnetic retrofits to preempt EU F-Gas Regulation compliance deadlines for hydraulic fluid systems.
- Urban Transit:Frequent stop-start cycles below 80 km/h maximize disc and drum brake wear rates.
- Light Rail:Lower axle loads and shared street running demand compact, low-noise friction systems.
Volume concentration rests with Urban Transit. Steepest expansion trajectory belongs to Freight Train electrification corridors.
End User:
Procurement authority determines specification stringency and maintenance contract structure.
- Government:National rail authorities in China, India, and EU member states set interoperability mandates and safety certification thresholds. China's NMPA electromagnetic compatibility testing extends foreign supplier qualification timelines.
- Private Operators:Freight concessionaires and open-access passenger services prioritize total cost of ownership metrics over first-cost minimization.
- Manufacturers:Rolling stock OEMs specify brake systems during initial fleet design.
- Maintenance Providers:Third-party service unbundling in Japan's Shinkansen and Singapore's MRT separates hardware procurement from predictive analytics contracts.
Specification authority concentrates with Government entities. Service contract innovation is accelerating among Maintenance Providers.
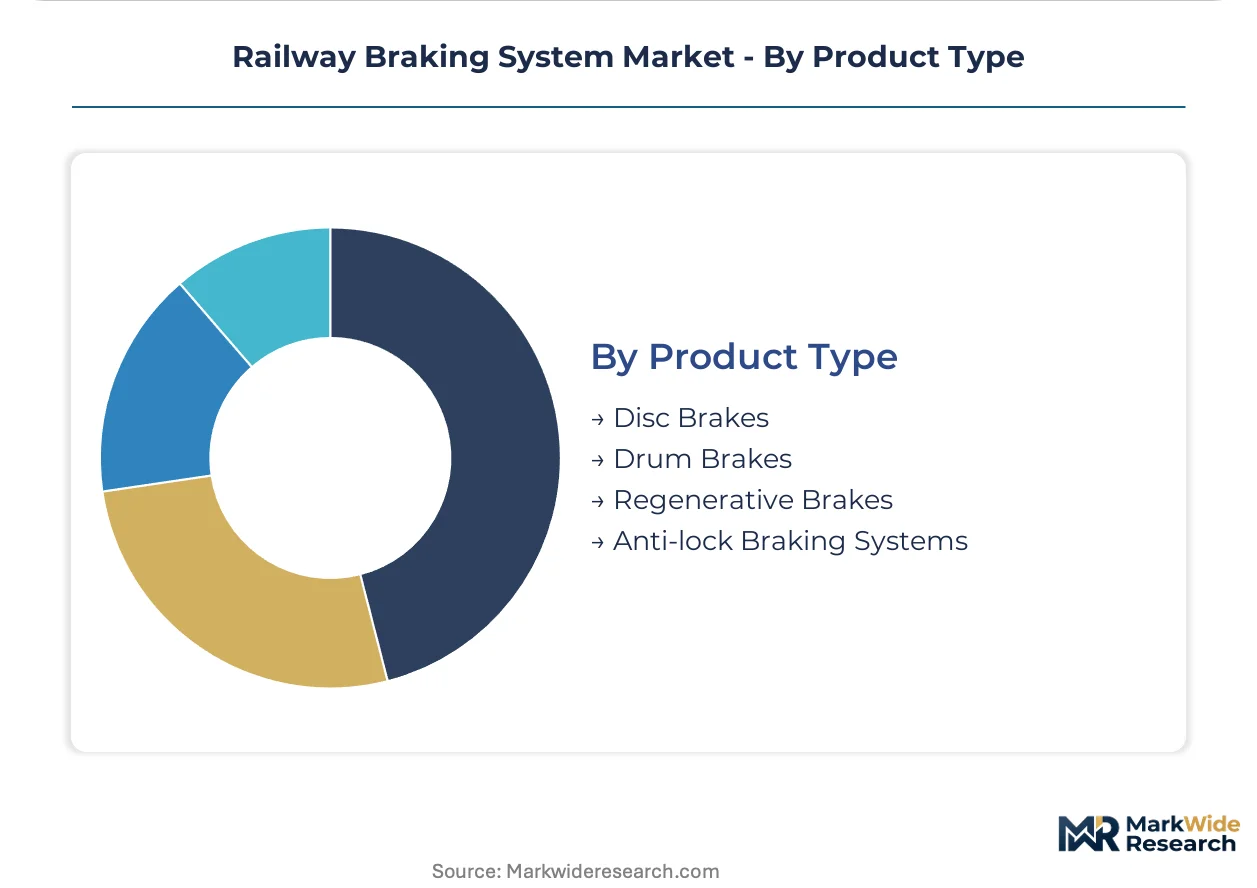
Product Type:
Hardware form factor determines thermal dissipation capacity and integration complexity with train control networks.
- Disc Brakes:Ventilated cast-iron or composite rotors handle primary friction duty in high-speed and urban applications. Machine-learning-based wear estimation is compressing the aftermarket for generic pad suppliers by tying consumables to proprietary control algorithms.
- Regenerative Brakes:Traction motor inversion captures kinetic energy for grid return or onboard storage. Efficiency degradation below minus 25 degrees Celsius forces Nordic and Russian operators to retain friction backup systems.
- Drum Brakes:Enclosed friction surfaces suit contaminated environments and legacy wagon fleets.
- Anti-lock Braking Systems:Wheel-slip control modules integrate with train-wide adhesion management.
Installed base dominance sits with Disc Brakes. Technology convergence is advancing fastest around Regenerative Brakes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement authority through CRRC-led manufacturing clusters, while Germany and India anchor technology transition corridors through divergent regulatory pathways. Regulatory fragmentation across electromagnetic compatibility certification and electrification mandates is reshaping supplier qualification requirements by geography.
China
CRRC fleet procurement programs drive concentrated demand for electromagnetic brake systems rated above 300 km/h sustained operation. NMPA electromagnetic compatibility testing extends foreign supplier qualification timelines by 8-14 months without domestic testing partnerships. Qingdao and Changchun rail manufacturing clusters house captive brake control electronics production for high-speed export programs.
Germany
Deutsche Bahn pilot programs on ICE fleets integrate machine-learning friction coefficient estimation into electropneumatic architectures. EU F-Gas Regulation phase-down schedules accelerate electromagnetic brake retrofit programs ahead of 2030 PFAS-free fluid mandates. KBA certification requirements for high-speed interoperability concentrate supplier development in Bavaria and Baden-Württemberg engineering corridors.
India
CEA rail electrification mandates expand regenerative braking deployment across 1,500 km of Dedicated Freight Corridor routes. BIS standards enforcement for domestically produced control units creates qualification barriers for foreign OEMs without local assembly partnerships. Gujarat and Maharashtra industrial corridors concentrate freight locomotive manufacturing with integrated brake system sourcing.
Japan
Shinkansen operators unbundle after-sales brake wear monitoring from OEM service contracts to independent predictive analytics providers. METI technology roadmaps prioritize convergence between braking hardware and energy management software platforms. Nagoya and Osaka metropolitan manufacturing bases supply urban transit disc brake systems for Southeast Asian export markets.
United States
Freight railroads anchor North American demand through distributed power braking platform retrofits on legacy consists. FRA safety mandates for positive train control integration reshape brake controller specification requirements for mixed-fleet operators. Chicago and Pittsburgh industrial corridors concentrate valve manufacturing and remanufacturing capacity for Class I railroad procurement programs.
Railway Braking System Market Competitive Environment
Backward integration into captive valve manufacturing dominates the current landscape as tier-one suppliers secure long-term OEM contracts through upstream control over critical pneumatic components. The vendor base stratifies across three tiers: vertically integrated European specialists with in-house electropneumatic production, North American freight-focused platform providers, and Asian rolling stock OEMs with captive brake system divisions. Two competitive moves define current positioning: technology convergence through brake-traction control integration, and geographic expansion via turnkey electrification packages in underpenetrated corridors.
Among Germany-based integrated specialists, Knorr-Bremse AG exemplifies the vertically integrated archetype through its valve manufacturing footprint. Wabtec Corporation occupies a position representing North American freight retrofit demand concentration. Faiveley Transport anchors the European high-speed rail technology tier. These three entities collectively illustrate how supplier positioning diverges by operational context rather than converging on uniform global standards.
| Leading Market Players |
|---|
| Knorr-Bremse AG |
| Wabtec Corporation |
| Faiveley Transport |
| CRRC Corporation Limited |
| Alstom SA |
| Nabtesco Corporation |
| Hitachi Rail |
| Akebono Brake Industry Co Ltd |
| Amsted Rail Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
Electromagnetic brake manufacturing migration from pneumatic-dominant architectures to hybrid electropneumatic and fully electromagnetic systems simultaneously inflates upfront component costs and concentrates supplier leverage among rare-earth processors in China. This technology transition rewards tier-one suppliers with captive neodymium sourcing arrangements while squeezing margins for second-tier assemblers exposed to spot magnet markets.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium-tier brake system suppliers from economy competitors in contract negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by electromagnetic compatibility certification grade and after-sales service integration. Cost compression in standard-tier pneumatic retrofits is intensifying because European freight operators accelerate F-Gas Regulation compliance conversions ahead of fluid phase-down deadlines. Government rail authorities exhibit lowest price sensitivity due to interoperability mandates, while private freight concessionaires prioritize total cost of ownership metrics.
Supply Chain Analysis
Certification gating through China's NMPA electromagnetic compatibility testing and India's BIS standards enforcement fragments supplier qualification pathways across Asian manufacturing corridors. Component sourcing concentrates in China for rare-earth magnet processing, Germany for precision valve manufacturing, and Japan for power electronics modules. Brake control unit production draws from neodymium, dysprosium, and silicon carbide inputs. Single-source vulnerability in Chinese rare-earth refining exposes OEMs to export restriction risks. Distribution runs through rolling stock OEM captive procurement channels and third-party maintenance provider networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over valve manufacturing and rare-earth magnet supply chains determines long-term contract viability. Players securing upstream component production or downstream predictive analytics integration capture pricing power unavailable to pure hardware assemblers.
For Market Incumbents: Anticipate margin compression from emerging Asian rolling stock OEMs with captive brake divisions by deepening backward integration into rare-earth magnet sourcing and electromagnetic compatibility testing partnerships. Prioritize certification pre-qualification in China's NMPA and India's BIS frameworks to extend qualification timelines for foreign competitors. For New Entrants and Emerging Players: The price-point gap between premium electromagnetic systems and legacy pneumatic retrofits creates entry space for mid-tier hybrid electropneumatic suppliers. Target India's Dedicated Freight Corridor electrification projects and African greenfield rail corridors where specification authority remains unsettled. Pursue turnkey electrification financing packages to bypass incumbent OEM procurement lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by rolling stock OEMs seeking captive brake system capabilities. Long-term viability favors suppliers with dual certification in European F-Gas Regulation compliance and Asian electromagnetic compatibility standards. Monitor neodymium export licensing patterns from Chinese processing facilities as inflection indicator for input cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Sourcing | Secures neodymium supply chains against Chinese export restrictions for electromagnetic brake production. |
| Electromagnetic Compatibility Certification Pre-Qualification | Accelerates NMPA and BIS approval timelines for brake control units in Asian procurement programs. |
| Predictive Maintenance Analytics Platform Development | Captures aftermarket revenue from Shinkansen and MRT operators unbundling service contracts. |
| Turnkey Electrification Package Financing | Enables market entry in African greenfield corridors with limited infrastructure capital availability. |
| PFAS-Free Hydraulic Fluid Formulation Investment | Preempts EU F-Gas Regulation obsolescence risk for legacy pneumatic system suppliers. |
Study Parameters
Document review covered regulatory filings from ECHA, NMPA, and BIS, complemented by interviews with rolling stock OEM procurement directors, brake system engineering leads, freight operator maintenance heads, and rare-earth supply chain specialists. Secondary sources included customs trade data, railway electrification project databases, and rolling stock production records. Bottom-up segment sizing triangulated against top-down macroeconomic rail infrastructure investment flows.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation modeling incorporated technology type, application velocity tier, end-user procurement authority, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to electrification corridor completion schedules and fleet replacement cycles. Forecast inputs included neodymium price trajectory assumptions and F-Gas Regulation phase-down enforcement intensity.
Inputs from NMPA certification timelines and CEA electrification mandates were available through the study window; gaps in proprietary OEM procurement contract terms introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and rare-earth supply chain stability. A model refresh is warranted upon material change in Chinese rare-earth export licensing policy or EU F-Gas Regulation amendment timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Gearbox for Rail Vehicles Market
Railway
Railway Buffer Stops Market
Railway
Rail Composites Market
Railway
India Rail Freight Transport Market
Railway
Railway Management System Market
Railway
Railroad Tie Market
Railway
Locomotive Doors Market
Railway
Hydrogen Trains Market
Railway
Road-Rail Vehicles Market
Railway
40-Foot Platform Wagons Market
Railway
Global Hyperloop Train Market
Railway
Rail Seat Market
Railway
Railway System Market
Railway
Train HVAC Market
Railway
Rail Transit Traction Converter Market
Railway
Railway Pantograph Market