
 Automotive Suspension System Market | 2026-2036
Automotive Suspension System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Suspension System Market Analysis
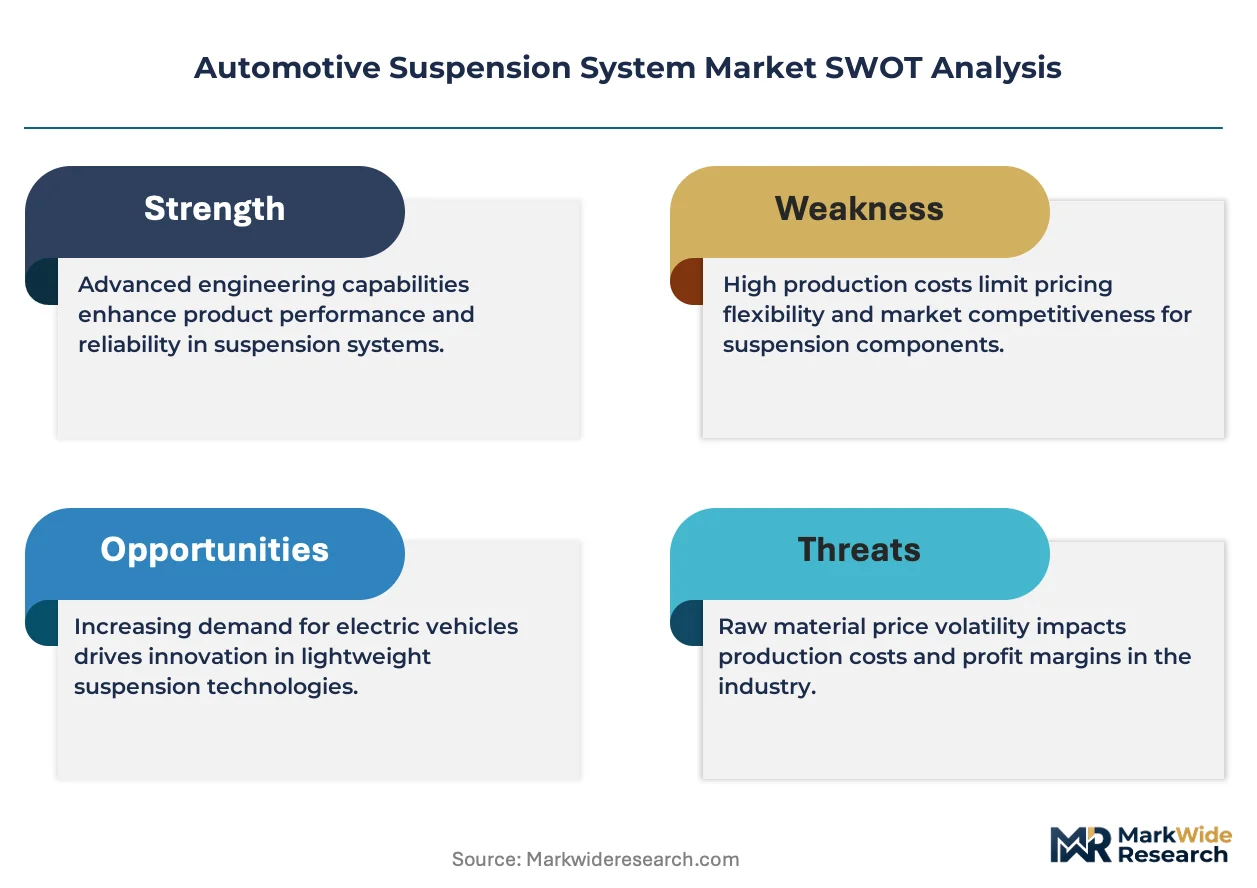
ISO 26262 functional safety certification is collapsing the supplier base for electronic suspension controls, favoring incumbents with proven ASIL-D track records. ZF Friedrichshafen AG leverages its integrated chassis electronics portfolio to dominate electromechanical active suspension development. Continental AG anchors its position through captive semiconductor sourcing for damper control modules. KYB Corporation specializes in monotube hydraulic architectures for motorsport and aftermarket channels.
An automotive suspension system integrates springs, dampers, linkages, and control electronics to manage tire-road contact forces, with typical passenger car spring rates ranging from 15 to 45 N/mm and damping coefficients tuned to 0.2–0.4 critical damping ratios for ride comfort optimization. Electromechanical active suspension commands the highest value per unit among product types, while passive suspension sustains volume leadership in emerging-market passenger vehicle platforms. Hydraulic technology retains cost advantages in commercial vehicle leaf-spring and air-spring combinations, though electromechanical architectures are displacing pneumatic systems in premium passenger applications where real-time road preview integration justifies cost premiums.
NHTSA Federal Motor Vehicle Safety Standard 126 mandates electronic stability control interoperability, which shapes suspension sensor architecture and control module validation requirements for US-bound vehicles. EPA corporate average fuel economy rules and the EU F-Gas Regulation jointly pressure mass reduction strategies, driving aluminum-forged control arm and composite spring adoption. EMA and FDA do not regulate this sector directly. Stakeholders must monitor pending Euro 7 brake and tire particulate limits, as these will cascade into suspension-integrated particulate capture and weight trade-offs that redefine supplier qualification criteria.
Market Dynamics
Electromechanical active suspension architectures are compressing the addressable market for traditional hydraulic and pneumatic systems, forcing tier-one suppliers to requalify damper control electronics under ISO 26262 ASIL-D functional safety mandates.
Growth Catalysts
- Euro 7 particulate limits:Brake and tire emissions caps under this framework are compelling aluminum-forged control arms and composite spring adoption to offset capture-system weight penalties.
- Commercial fleet retention economics:Long-haul operators in Germany and the United States are retrofitting active suspension to reduce cargo damage claims and driver turnover costs.
- Road-preview sensor fusion:Integration of camera and lidar data into damper control loops enables real-time damping coefficient adjustment for premium passenger platforms.
Market Restraints
- Rare-earth magnet cost volatility:Electromechanical actuator motors depend on neodymium supply concentrated in Chinese processing facilities, exposing BOM costs to export quota fluctuations.
- Semiconductor fab concentration:ASIL-D-qualified microcontrollers for damper modules source from a narrowing base of TSMC and GlobalFoundries capacity, creating allocation risk.
- Passive system residual demand:Emerging-market passenger platforms in India and Brazil sustain hydraulic damper volumes that compress electromechanical pricing power.
Strategic Opportunities
- Aftermarket active retrofit kits:Independent garages in the United States and Germany are developing plug-and-play electromechanical upgrade modules for legacy luxury platforms.
- EU F-Gas Regulation phase-down:Pneumatic suspension refrigerant restrictions are accelerating electromechanical replacement demand in premium European passenger segments.
- Autonomous ride-hail specifications:Robotaxi fleet operators are specifying predictive suspension tuning to minimize motion sickness and improve passenger retention metrics.
Industry Challenges
- ASIL-D validation timeline compression:Functional safety certification for new damper control algorithms now spans 18-24 months, delaying platform launch windows.
- Legacy bus architecture integration:Electromechanical modules must bridge CAN-FD and Ethernet backbones in mixed-electronics vehicle platforms, multiplying software validation scope.
- Mechatronics talent scarcity:Combined mechanical-hydraulic-electronics expertise required for active suspension development concentrates at ZF Friedrichshafen AG, Continental AG, and a handful of tier-two specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Suspension System Market |
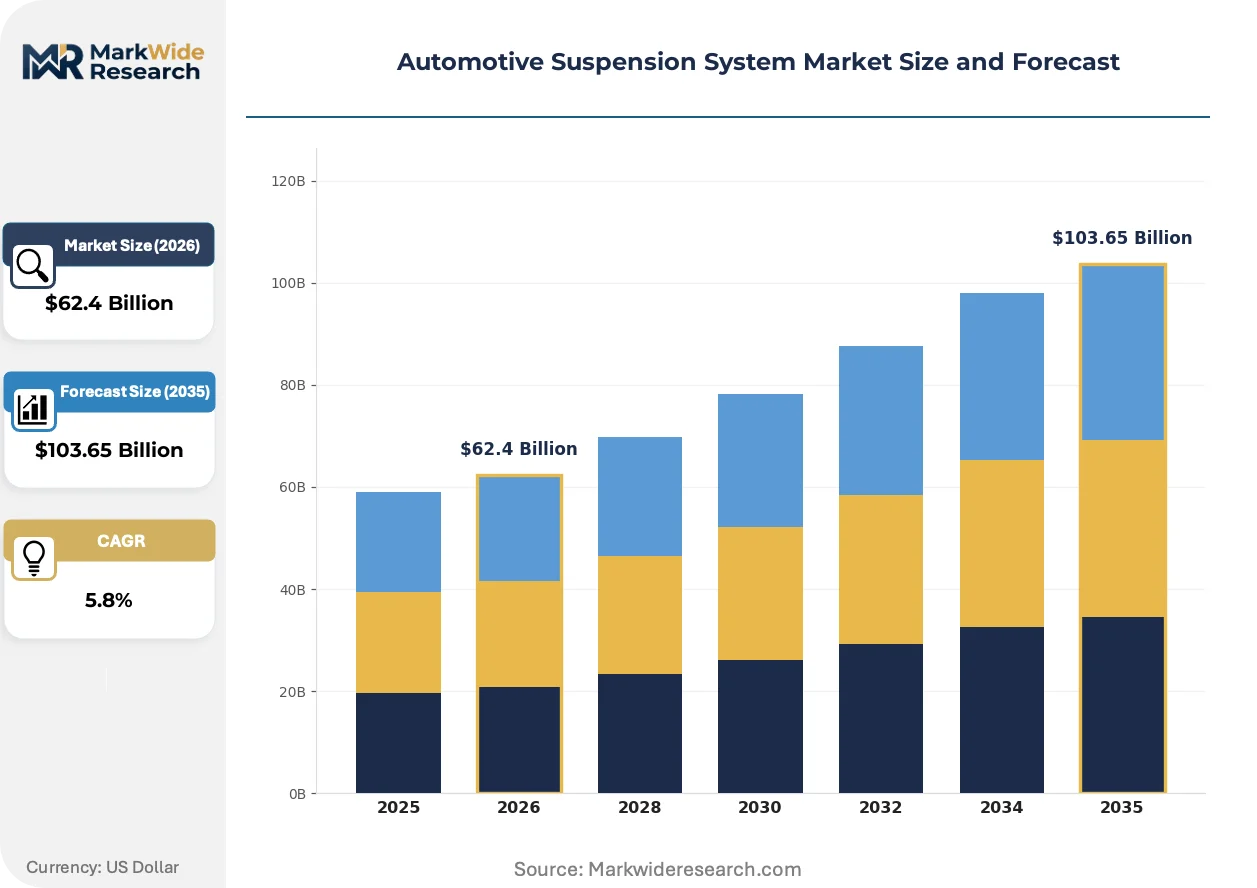
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $103.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Suspension, Active Suspension, Semi-Active Suspension, Magnetic Ride Technology: Hydraulic, Pneumatic, Electromechanical, Mechanical Application: Passenger Vehicles, Commercial Vehicles, Motorsport Vehicles, Heavy-Duty Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | ThyssenKrupp AG, Mando Corporation, Continental AG, Hyundai Mobis Co. Ltd., Magneti Marelli SpA, ZF Friedrichshafen AG, KYB Corporation, Sogefi SpA, Tenneco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Suspension System Market Emerging Trajectories
Sensor fusion architectures and predictive damping algorithms are rewriting the competitive boundary between chassis electronics and suspension hardware, collapsing traditional tier boundaries.
Electromechanical actuator technology is fragmenting the supplier landscape for premium passenger damping systems. These motors replace hydraulic valves with direct force control, enabling millisecond-level response to road surface changes. German and Chinese OEMs are qualifying this architecture for flagship sedan platforms. The shift is fragmenting established hydraulic damper supply relationships and forcing semiconductor-qualified entrants into chassis electronics.
EPA Tier 3 and Euro 7 tailpipe and particulate standards are cascading into suspension weight budgets. Regulators in the United States and European Union now treat brake and tire wear particles as regulated emissions categories. This is compressing allowable unsprung mass and accelerating carbon-fiber-reinforced polymer spring adoption in performance segments. Suppliers are requalifying material fatigue models under combined thermal and particulate exposure cycles.
Fleet procurement specifications are unbundling suspension hardware from chassis electronics service contracts. Large commercial operators in the United States now source dampers and control modules through separate RFP processes, then negotiate integrated maintenance pricing. This bifurcation is compressing historical bundled-margin structures for incumbent tier-one suppliers. The pattern is most visible in long-haul trucking procurement through dedicated fleet management companies.
Automotive Suspension System Market Segmentation
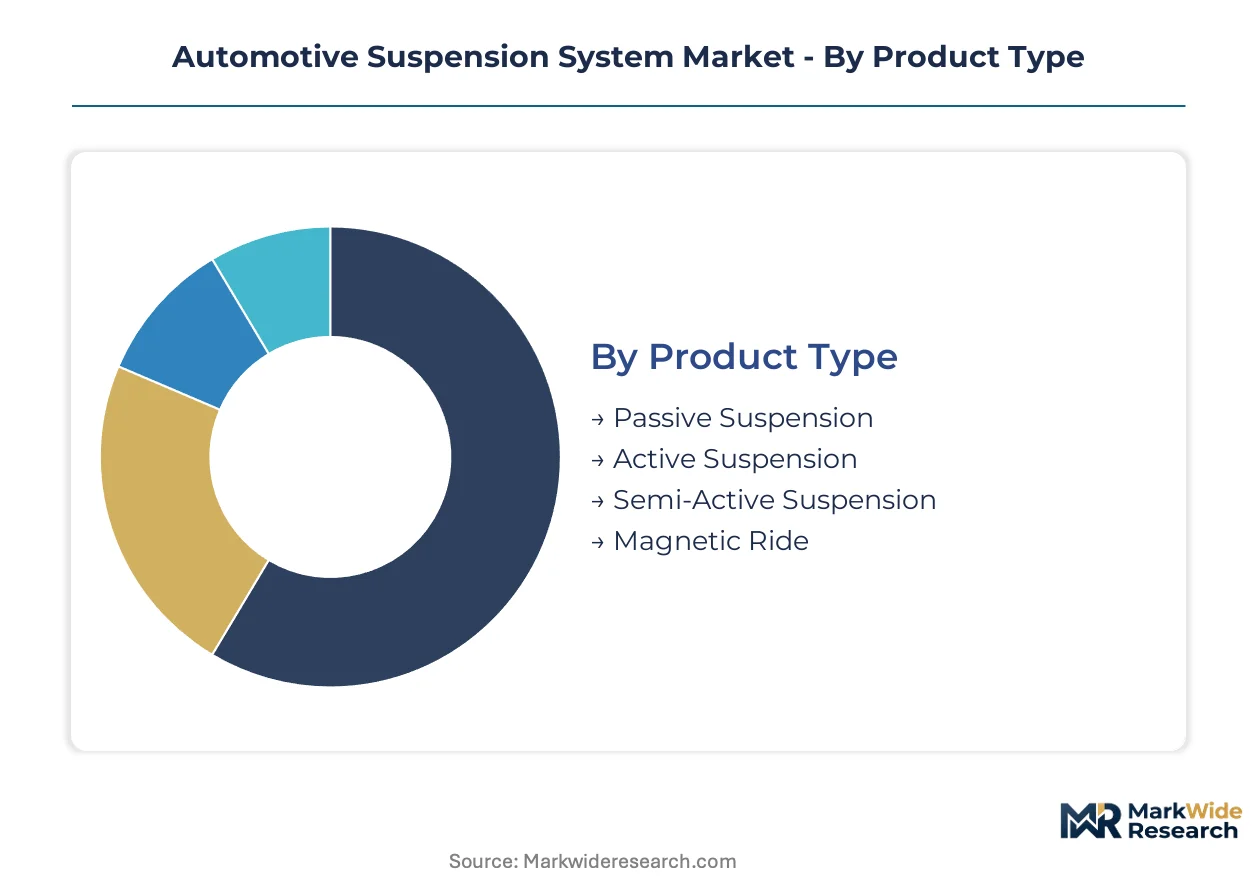
Segmentation in the Automotive Suspension System Market reveals distinct procurement channels and technical requirements that reshape supplier relationships. Product type and technology choices determine whether components flow through captive OEM supply agreements or fragmented aftermarket distribution networks.
Product Type:
Channel-mix patterns diverge sharply across suspension architectures, with passive systems dominating aftermarket volume while active configurations concentrate in OEM flagship programs.
- Passive Suspension:Conventional coil-spring and fixed-damper assemblies deliver baseline ride comfort through mechanical energy dissipation. Demand concentrates in Brazil and India where budget passenger vehicle platforms sustain hydraulic damper volumes and compress electromechanical pricing power.
- Active Suspension:Real-time force actuation through electromechanical motors enables continuous spring rate and damping adjustment. German and Chinese OEMs are qualifying this architecture for flagship sedan platforms where road-preview sensor fusion justifies cost premiums.
- Semi-Active Suspension:Switchable damper valving provides discrete stiffness modes without full force control. Fleet operators in the United States specify these for mid-tier commercial vehicles balancing acquisition cost against cargo damage reduction.
- Magnetic Ride:Magnetorheological fluid systems deliver millisecond response through variable viscosity control. Motorsport applications in Italy and Japan anchor niche procurement volumes.
Passive Suspension dominates installed base. Active Suspension is where expansion concentrates.
Technology:
Cost tier stratification separates mature hydraulic architectures from emerging electromechanical platforms competing on performance metrics rather than price.
- Hydraulic:Pressurized fluid circuits transmit damping forces through piston-cylinder assemblies with established fatigue models. Commercial vehicle leaf-spring combinations in Germany retain cost advantages despite weight penalties under Euro 7.
- Pneumatic:Compressed air springs enable self-leveling and ride height adjustment through rubber bellows and compressor modules. EU F-Gas Regulation refrigerant phase-down is accelerating electromechanical replacement demand in premium European passenger segments.
- Electromechanical:Direct-drive motors replace fluid circuits with precise force control and energy recuperation capability. ASIL-D functional safety mandates are collapsing the supplier base for electronic controls and favoring incumbents with proven certification track records.
- Mechanical:Solid linkages and friction dampers serve cost-minimized platforms with no electronic content. Emerging-market vehicle assemblers in Thailand and Mexico specify these for entry-level export programs.
Hydraulic technology anchors current revenue. Electromechanical configurations are climbing the fastest.
Application:
Volume concentration varies by vehicle duty cycle, with passenger platforms driving technology adoption that later cascades into commercial segments.
- Passenger Vehicles:Multi-link independent architectures optimize tire contact patch geometry for ride and handling trade-offs. United States premium sedan production anchors OEM procurement volumes for adaptive damping modules.
- Commercial Vehicles:Rigid axle and air-spring combinations manage high sprung mass with durability-focused designs. Long-haul operators in Germany and the United States are retrofitting active suspension to reduce cargo damage claims and driver turnover costs.
- Motorsport Vehicles:Inboard suspension layouts with pushrod actuation minimize unsprung mass for transient response. KYB Corporation specializes in monotube hydraulic architectures for this channel and parallel aftermarket distribution.
- Heavy-Duty Vehicles:Multi-axle bogie systems distribute extreme loads across parabolic leaf springs or air-ride modules. Mining and construction fleets in Australia specify predictive maintenance integration for remote operation support.
Passenger Vehicles dominate installed base. Commercial Vehicles are gaining share fastest.
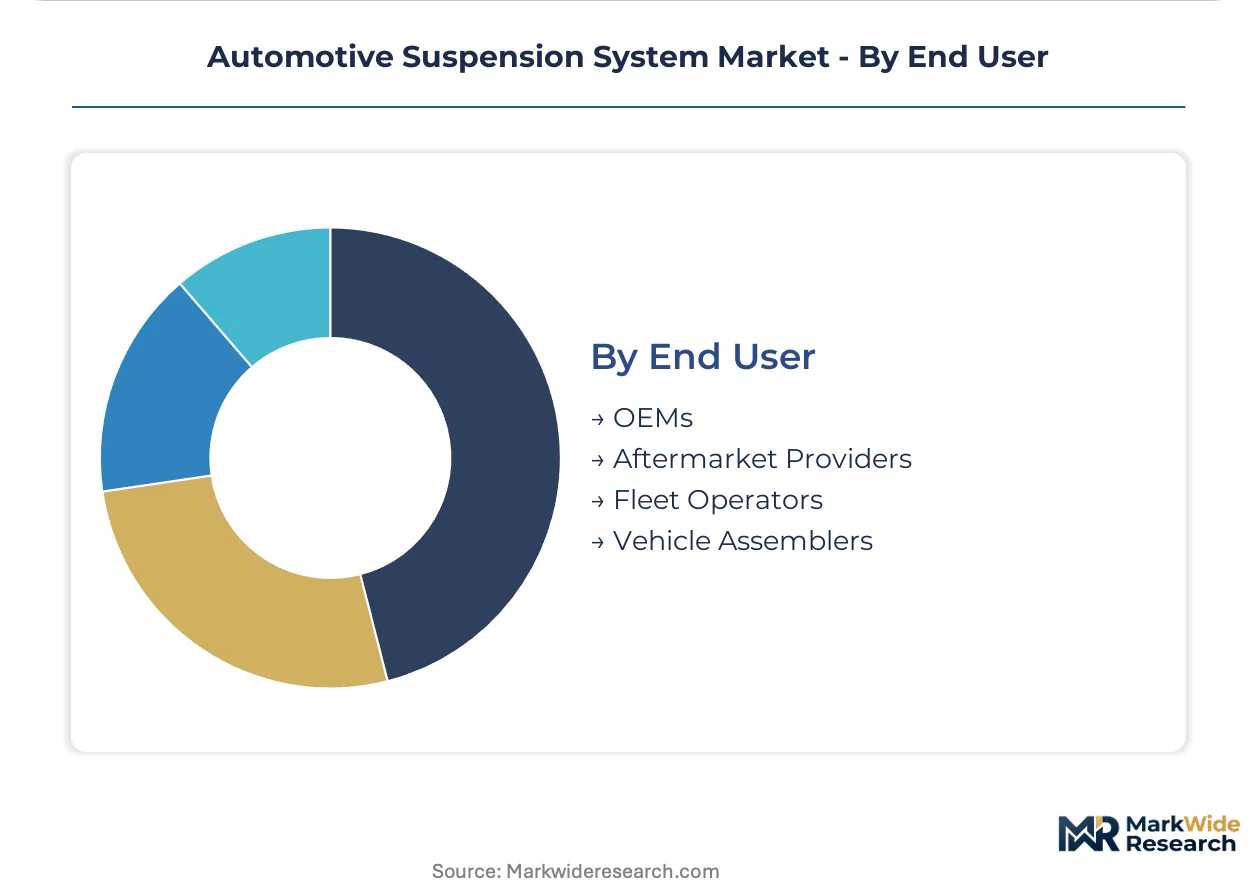
End User:
Customer type determines contract structure, with OEMs demanding systems integration accountability while fleet operators unbundle hardware from service agreements.
- OEMs:Vehicle manufacturers specify suspension modules as chassis subsystems with tier-one supplier integration responsibility. ZF Friedrichshafen AG leverages its integrated chassis electronics portfolio to dominate electromechanical active suspension development.
- Aftermarket Providers:Independent distributors and garage networks service replacement demand and performance upgrades. Plug-and-play electromechanical retrofit kits for legacy luxury platforms are emerging in the United States and Germany.
- Fleet Operators:Large commercial buyers now source dampers and control modules through separate RFP processes, then negotiate integrated maintenance pricing. This bifurcation compresses historical bundled-margin structures for incumbent suppliers.
- Vehicle Assemblers:Contract manufacturers and kit-builders procure suspension systems as pre-validated modules for localized final assembly. Operations in South Africa and Vietnam rely on imported subassemblies with regional content compliance.
OEMs dominate installed base. Fleet Operators are where procurement innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Euro 7 brake and tire particulate limits are reshaping procurement priorities across major automotive manufacturing clusters. OEMs in Germany, China, and the United States are accelerating aluminum-forged control arm adoption to offset capture-system weight penalties.
United States
NHTSA Federal Motor Vehicle Safety Standard 126 mandates electronic stability control interoperability for all US-bound vehicles. EPA Tier 3 tailpipe standards cascade into suspension weight budgets, pressuring mass reduction strategies. Detroit's automotive corridor anchors OEM procurement volumes for adaptive damping modules in premium sedan production.
Germany
Long-haul fleet operators are retrofitting active suspension systems to reduce cargo damage claims and driver turnover costs. KBA vehicle type approval requirements enforce rigorous validation protocols for electromechanical damper controls. Stuttgart's integrated chassis electronics cluster concentrates ZF Friedrichshafen AG and Continental AG development activity.
China
Dual carbon goals under MEE directives are compelling lighter suspension architectures in domestic EV platforms. GB standards for vehicle safety systems shape control module validation requirements. Shanghai's Yangtze River Delta automotive cluster hosts tier-one supplier joint ventures for electromechanical active suspension qualification.
Japan
METI industrial policy supports motorsport-derived technology transfer into production vehicle platforms. JIS fatigue testing standards govern carbon-fiber-reinforced polymer spring qualification for performance segments. KYB Corporation anchors monotube hydraulic architecture development in Osaka's precision manufacturing belt.
South Korea
MFDS automotive safety regulations align with ISO 26262 functional safety mandates for electronic suspension controls. Government EV subsidies accelerate electromechanical actuator adoption in domestic flagship platforms. Hyundai Mobis Co. Ltd. anchors active suspension module production in Ulsan's integrated vehicle manufacturing complex.
Automotive Suspension System Market Vendor Landscape
Player mix skews toward diversified chassis systems integrators with captive electronics capabilities. Market structure concentrates around tier-one suppliers possessing ASIL-D certification track records and semiconductor sourcing relationships. Two strategic archetypes dominate: integrated chassis electronics portfolios and specialized hydraulic damper fabricators. Competitive moves center on functional safety qualification acceleration and aftermarket retrofit kit development.
Among diversified German chassis integrators, ZF Friedrichshafen AG and Continental AG exemplify the integrated electronics archetype, each leveraging captive semiconductor relationships and ASIL-D validation capabilities to anchor electromechanical active suspension development. KYB Corporation represents the specialized hydraulic fabricator position, concentrating motorsport and aftermarket channel expertise. These three entities occupy distinct competitive vectors within a supplier base compressed by ISO 26262 certification barriers.
| Leading Market Players |
|---|
| ThyssenKrupp AG |
| Mando Corporation |
| Continental AG |
| Hyundai Mobis Co. Ltd. |
| Magneti Marelli SpA |
| ZF Friedrichshafen AG |
| KYB Corporation |
| Sogefi SpA |
| Tenneco Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with TSMC and GlobalFoundries lock in semiconductor access for damper control modules while capping price volatility exposure for tier-one suppliers. These contracts tether electromechanical active suspension BOM stability to wafer allocation priority, compressing margin flexibility for entrants lacking similar foundry relationships.
Pricing Analysis
Certification level creates the primary spread, with ASIL-D-qualified electronic controls commanding substantial premiums over lower-grade alternatives. Three-tier pricing structure separates flagship OEM programs from mid-tier fleet specifications and emerging-market passive systems. Cost compression in passive hydraulic segments intensifies because Indian and Brazilian assemblers prioritize acquisition cost over performance metrics. Fleet operators exhibit highest price sensitivity, while German premium OEMs absorb certification premiums for road-preview integration capabilities.
Supply Chain Analysis
China and Germany anchor rare-earth magnet processing and precision forging respectively, creating dual-hemisphere dependency for electromechanical actuator motors. Neodymium supply draws from Chinese separation facilities, while aluminum-forged control arms source from German automotive clusters. Single-source vulnerability concentrates in ASIL-D microcontroller fabrication at TSMC. Distribution runs through captive OEM supply agreements for active systems, with fragmented aftermarket channels serving replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combined mechatronics expertise—spanning mechanical-hydraulic-electronics integration—concentrates at a handful of tier-one suppliers, creating acute capability scarcity that shapes competitive dynamics and entry barriers across the value chain.
For Market Incumbents: Fortify ASIL-D certification pipelines through accelerated validation timelines to offset 18-24 month algorithm approval delays. Deepen captive semiconductor sourcing relationships with foundry capacity reservation agreements to defend against allocation risk from emerging electromechanical entrants. Prioritize backward integration into rare-earth magnet supply chains to mitigate Chinese export quota exposure. For New Entrants and Emerging Players: ISO 26262 fast-track partnerships with established validation consultancies enable compressed certification timelines for damper control modules. Target aftermarket retrofit kits for legacy luxury platforms in the United States and Germany, where plug-and-play electromechanical upgrade demand outstrips qualified supply. Pursue fleet operator direct procurement relationships that bypass incumbent tier-one bundled service contracts. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors semiconductor-qualified chassis electronics specialists over legacy hydraulic fabricators. Long-term viability hinges on functional safety certification track records and foundry access rather than manufacturing scale alone. Monitor rare-earth magnet price volatility and foundry allocation announcements as inflection indicators for BOM cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | Compresses validation timelines for damper control algorithms to capture flagship OEM programs. |
| Captive Semiconductor Sourcing | Locks in TSMC capacity allocation for electromechanical actuator control modules. |
| Aftermarket Retrofit Kit Development | Opens plug-and-play revenue streams in United States and Germany luxury vehicle segments. |
| Rare-Earth Supply Diversification | Reduces neodymium dependency on Chinese processing facilities for actuator motor magnets. |
| Fleet Service Contract Unbundling | Enables direct damper and control module procurement separate from historical tier-one bundles. |
Methodological Framework
Desk research of regulatory filings, vehicle production databases, and tier-one supplier annual disclosures preceded structured interviews with OEM platform engineers, tier-one procurement directors, aftermarket distributors, and fleet maintenance managers. Primary fieldwork across Germany, China, and the United States validated electromechanical adoption trajectories and certification timeline assumptions. Secondary sources included NHTSA safety standard documentation, KBA type approval records, and IHS Markit vehicle registration data. Bottom-up segment sizing triangulated against top-down OEM procurement value chain estimates.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster shaped the analytical framework. Modeled CAGRs derived from production volume trajectories, technology penetration curves, and value-per-vehicle escalation for active suspension content. Forecast inputs incorporated Euro 7 weight compliance deadlines and fleet operator retrofit specification trends throughout the projection horizon.
Decision-makers should treat outputs as directional under assumptions of stable rare-earth supply and foundry capacity allocation; material deviation would warrant model refresh. Specific risks include Chinese export quota disruptions, ASIL-D validation timeline extensions, and passive system residual demand persistence in emerging markets. Recalibration cycles align with material shifts in regulatory enforcement schedules and semiconductor supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Exhaust Hanger Material Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
North America Gear Market
Automotive Parts
United States Ceramic Ball Bearings Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Air Brake Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Timing Belt Market