
 Suspension Spring Market | 2026-2036
Suspension Spring Market Size, Share, and Industry Trends Forecast 2026-2036
Suspension Spring Market Insights
Electric vehicle chassis architecture is decoupling from legacy internal combustion suspension loads, creating divergent spring specification requirements. NHK Spring Co. Ltd. leverages its materials science heritage to anchor premium EV platform contracts. Mubea specializes in lightweight composite coil solutions for battery-heavy vehicle architectures. Thyssenkrupp AG competes through integrated forging capabilities that sustain cost discipline across high-volume OEM programs.
A suspension spring is a mechanical energy storage device manufactured from alloy steel wire or composite filament, formed through hot coiling, shot peening, and presetting processes to achieve specified fatigue life and load-deflection characteristics; its primary purpose is to isolate vehicle occupants from road disturbances while maintaining tire contact patch consistency. Coil springs dominate passenger vehicle applications due to packaging efficiency and tunable rate characteristics, while leaf springs retain structural importance in commercial vehicle rear axles where load-bearing capacity governs specification. Air springs command premium positioning in heavy equipment and luxury bus segments where adjustable ride height creates measurable operational value.
NHTSA crashworthiness standards and EPA fuel economy mandates in the United States, alongside Europe's REACH substance restrictions and CE marking requirements, collectively elevate material traceability and lightweighting imperatives across supplier tiers. China's GB standards and MIIT new energy vehicle directives impose additional compliance layers for market access. Stakeholders must monitor evolving chassis electrification roadmaps and regulatory harmonization pressures to align capital allocation with emerging specification thresholds.
Market Dynamics
Chassis electrification is bifurcating suspension spring specifications as battery-electric platforms impose fundamentally different mass distribution and packaging constraints than legacy internal combustion architectures, forcing suppliers to retool material science and manufacturing footprints simultaneously.
Growth Catalysts
- MIIT new energy vehicle directives:China's production mandates for zero-emission platforms are expanding procurement volumes for lightweight coil architectures in battery-heavy vehicle designs.
- Composite filament winding:Glass and carbon fiber reinforced polymer springs are penetrating premium EV segments where unsprung mass reduction extends range.
- Commercial vehicle load optimization:Air spring adoption in heavy-duty trucking corridors across Germany and the United States is accelerating as fleet operators prioritize adjustable ride height for fuel efficiency.
Market Restraints
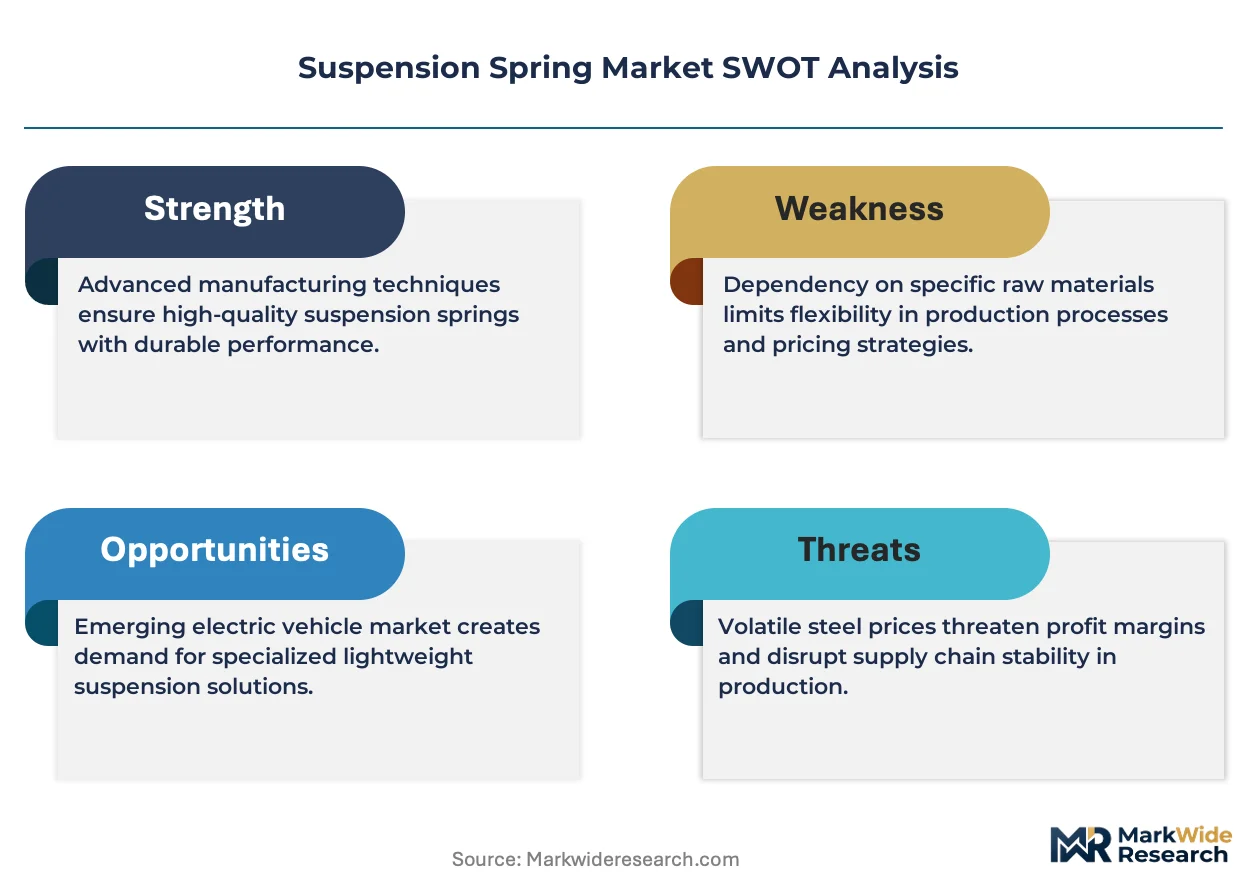
- Alloy steel wire price volatility:Crude oil and scrap metal input costs fluctuate with energy market cycles, compressing margin predictability for forged component suppliers.
- Shot peening equipment concentration:Precision surface treatment capacity clusters in Japanese and German industrial corridors, creating geographic supply vulnerability.
- REACH substance restrictions:ECHA compliance for surface coatings and anti-corrosion treatments adds formulation complexity and testing overhead.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives are opening localization pathways for global Tier 1 suppliers serving emerging EV assembly hubs.
- Autonomous ride-hail fleets:Durability-focused spring specifications for high-utilization robotaxi platforms represent a specification white space distinct from consumer vehicle cycles.
- CE marking harmonization:Unified conformity assessment across EU member states is reducing market entry friction for standardized coil spring portfolios.
Industry Challenges
- Multiphysics simulation talent scarcity:Fatigue modeling expertise combining nonlinear FEA with material science is concentrating at a handful of specialized engineering consultancies.
- Hot coiling furnace capex cycles:Precision temperature control equipment for high-strength steel processing requires seven-figure capital commitments with decade-long depreciation horizons.
- ISO 9001 and IATF 16949 certification timelines:Dual quality management system audits for automotive OEM qualification extend supplier onboarding by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suspension Spring Market |
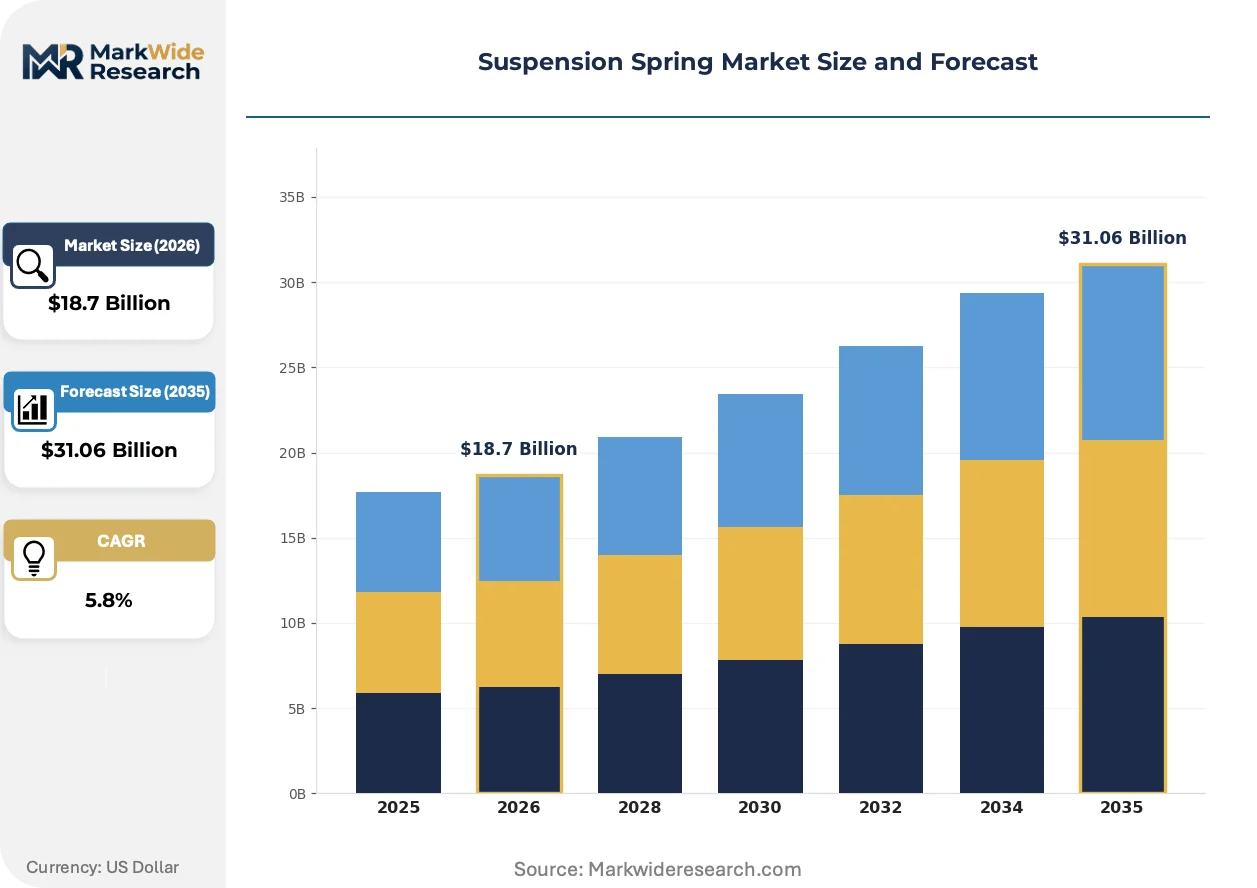
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coil Springs, Leaf Springs, Air Springs, Torsion Springs End User: Automotive Manufacturers, Aftermarket Suppliers, Heavy Equipment, Aerospace Material: Steel, Composite, Aluminum, Zinc-Coated Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Industrial Machinery |
| Companies Covered | NHK Spring Co. Ltd., Mubea, Rassini, Sogefi SpA, Thyssenkrupp AG, Mitsubishi Steel Mfg. Co. Ltd., ZF Friedrichshafen AG, Tenneco Inc., Lesjofors Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suspension Spring Market Trends and Innovations
Material science convergence with digital manufacturing is compressing spring development cycles while regulatory chemistry constraints are forcing coating and surface treatment reinvention across supplier tiers.
Glass-reinforced polymer coil springs are absorbing torsional loads in select EV platforms where mass reduction priorities override cost premiums. European luxury manufacturers are piloting these architectures in rear axle applications with lower duty cycles than front suspensions. The technology is absorbing engineering validation resources that would otherwise flow toward incremental steel alloy improvements.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon propellants used in air spring manufacturing, forcing suppliers to reformulate elastomer bladder compounds and retest fatigue performance under alternative blowing agents. Air spring producers serving bus and heavy truck OEMs face compressed compliance timelines as 2027 phase-out deadlines approach. German and French fleet operators are accelerating procurement of compliant systems to avoid aftermarket retrofit liability.
Fleet procurement departments are consolidating suspension component sourcing through long-term platform contracts rather than transactional spot purchasing. Large commercial vehicle operators in the United States are negotiating direct supply agreements with spring manufacturers, bypassing traditional distributor networks. This concentration is most visible in long-haul trucking corridors where total cost of ownership analytics now dominate specification decisions over upfront component pricing.
Suspension Spring Market Segmentation
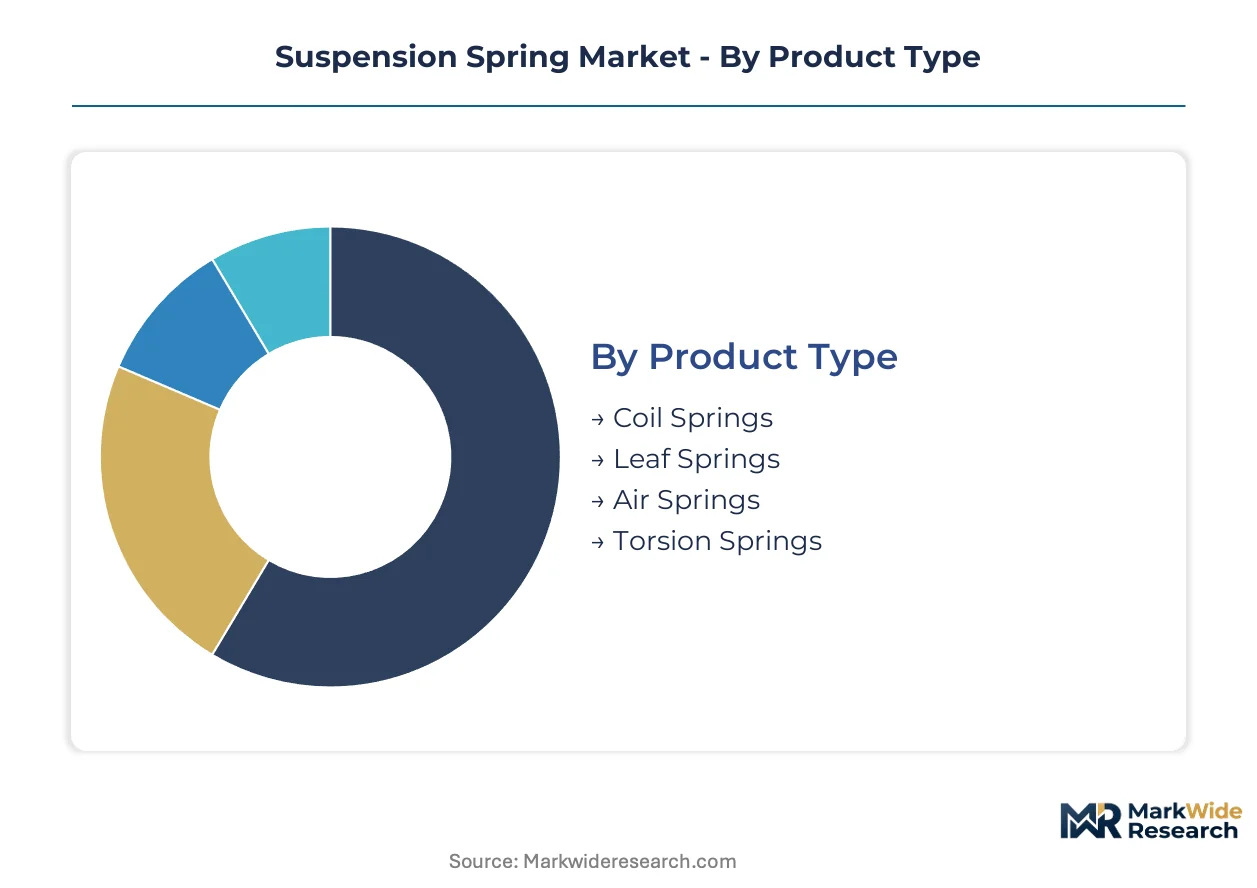
Spring specification divergence across electrified chassis architectures demands granular segment intelligence. Procurement teams now source coil, leaf, air, and torsion variants through fundamentally different qualification pathways.
Product Type:
Material composition and forming processes distinguish competitive positioning across spring architectures.
- Coil Springs:Helical compression elements wound from high-tensile alloy steel wire dominate passenger vehicle independent suspension modules. China's MIIT new energy vehicle directives are accelerating lightweight coil procurement for battery-heavy platform designs.
- Leaf Springs:Layered steel parabolic assemblies sustain rear axle loads in commercial vehicle architectures where cost-per-kilogram metrics govern specification. Fleet operators across Germany and the United States prioritize these assemblies for durability in high-cycle freight corridors.
- Air Springs:Elastomeric bellows with pressurized air cores enable adjustable ride height in luxury buses and heavy equipment.
- Torsion Springs:Twisted bar configurations absorb rotational loads in compact suspension geometries and stabilizer linkages.
Coil springs lead on scale; air springs lead on momentum.
End User:
Customer procurement sophistication varies sharply across OEM, aftermarket, and industrial channels.
- Automotive Manufacturers:Tier 1 suppliers engage directly with vehicle OEMs through multi-year platform contracts specifying fatigue life, corrosion resistance, and traceability under IATF 16949 protocols. NHTSA crashworthiness standards and EPA mandates in the United States impose additional validation layers.
- Aftermarket Suppliers:Distributor networks and service chains source replacement springs with shorter lead times and reduced documentation burdens.
- Heavy Equipment:Construction and mining machinery producers specify springs for extreme duty cycles under ISO standards.
- Aerospace:Aircraft landing gear and control surface applications demand titanium and superalloy formulations with FAA certification.
Automotive manufacturers concentrate procurement volume; heavy equipment commands premium pricing tiers.
Material:
Substrate selection determines mass, fatigue performance, and regulatory compliance trajectories.
- Steel:Chrome-silicon and chrome-vanadium alloys remain the baseline for cost-sensitive high-volume production.
- Composite:Glass and carbon fiber reinforced polymer springs are penetrating premium EV segments where unsprung mass reduction extends range.
- Aluminum:Lightweight coil formulations serve niche motorsport and aerospace applications.
- Zinc-Coated:Hot-dip and electro-galvanized surface treatments satisfy REACH-compliant corrosion protection for European market access.
Steel dominates installed base; composite formulations are climbing the fastest.
Application:
Vehicle duty cycles and operating environments dictate spring specification hierarchies.
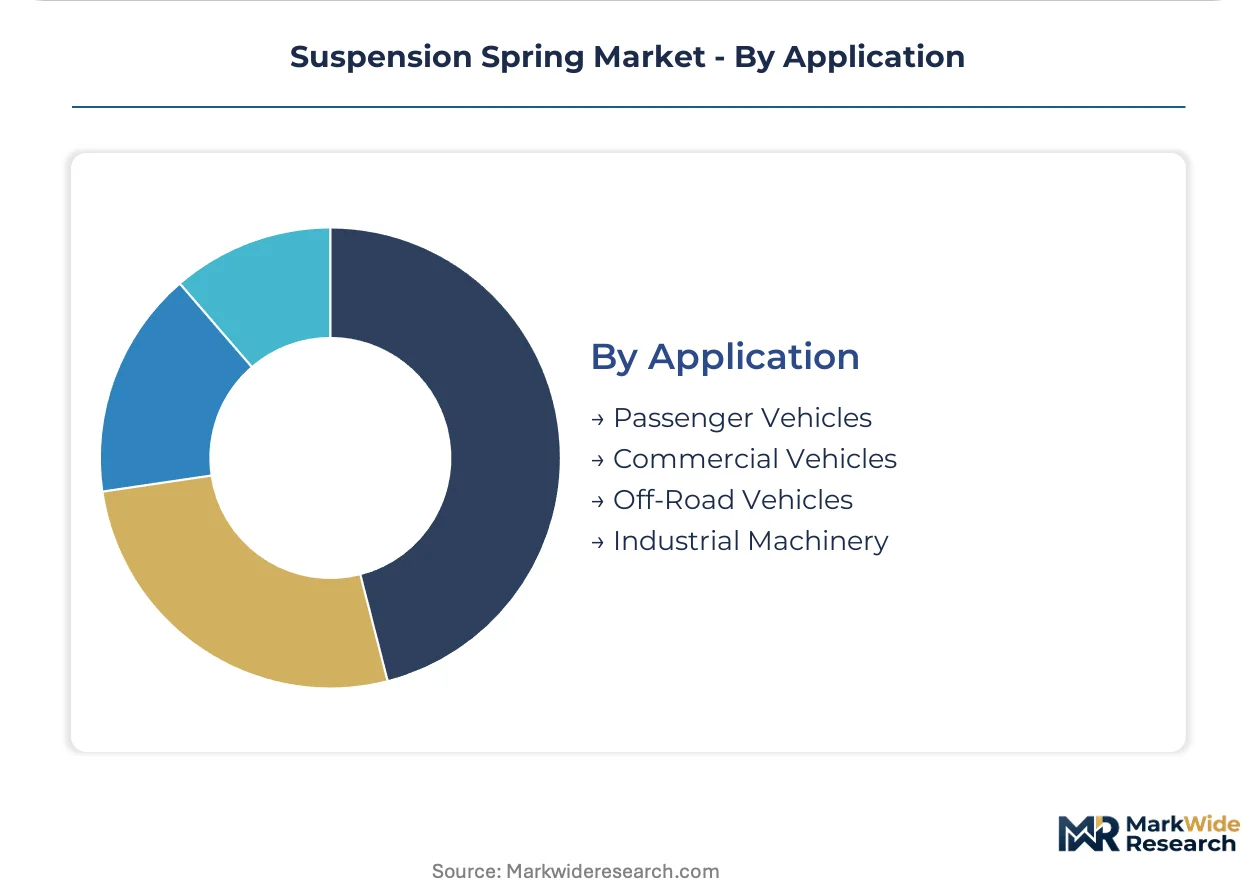
- Passenger Vehicles:Coil-spring MacPherson strut and multi-link architectures govern C-segment and above platforms. Europe's F-Gas Regulation and REACH compliance are tightening material standards for coatings and surface treatments.
- Commercial Vehicles:Leaf spring rear suspensions and air spring cab mounts balance payload capacity with driver comfort.
- Off-Road Vehicles:Progressive-rate coil and torsion configurations absorb terrain impacts in agricultural and recreational machinery.
- Industrial Machinery:Compression and extension springs isolate vibration in manufacturing equipment and material handling systems.
Passenger vehicles anchor volume demand; off-road applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive manufacturing corridors concentrate the heaviest procurement volumes for suspension spring suppliers serving battery-electric platform expansions. Chassis electrification roadmaps in Germany, Japan, and the United States are diverging specification requirements across three distinct regulatory environments.
China
MIIT new energy vehicle directives are accelerating lightweight coil procurement for battery-heavy platform designs. GB standards impose additional compliance layers for surface treatments and fatigue testing protocols. Shanghai and Guangzhou manufacturing clusters host concentrated shot peening capacity serving domestic EV OEMs.
Germany
KBA vehicle certification requirements and ECHA REACH substance restrictions are elevating material traceability standards for coil spring coatings. F-Gas Regulation phase-out deadlines are forcing air spring suppliers to reformulate elastomer compounds. Stuttgart and Munich industrial corridors anchor premium EV platform engineering.
United States
NHTSA crashworthiness standards and EPA fuel economy mandates are tightening validation protocols for chassis components. Long-haul trucking fleets in the Midwest are consolidating procurement through direct manufacturer agreements. Detroit and Tennessee manufacturing belts concentrate forging capacity for high-volume OEM programs.
Japan
METI industrial policy is channeling R&D subsidies toward composite filament winding technologies for unsprung mass reduction. JIS standards govern fatigue life specifications for passenger vehicle applications. Nagoya and Osaka industrial districts maintain precision surface treatment expertise for premium tier supply.
India
PLI scheme incentives for auto components are opening localization pathways for global Tier 1 suppliers. BIS certification requirements are extending quality management system audits for market entry. Tamil Nadu and Maharashtra assembly corridors are absorbing capital deployment for EV platform component manufacturing.
Suspension Spring Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers retool hot coiling furnaces and shot peening lines for divergent EV and ICE specifications. The vendor base stratifies across three tiers: integrated steel-forging conglomerates with captive wire supply, specialized coil spring manufacturers with IATF 16949 pedigree, and composite filament specialists serving premium mass reduction segments. Strategic archetypes include material science heritage players leveraging metallurgical IP, lightweighting-focused composite innovators, and scale-driven forgists competing on cost discipline. M&A activity and geographic expansion into India's PLI corridors represent the dominant competitive vectors.
Among Japanese heritage manufacturers, NHK Spring Co. Ltd. and Mitsubishi Steel Mfg. Co. Ltd. occupy positions anchored by materials science lineage and precision manufacturing pedigree. Thyssenkrupp AG represents the integrated European forging archetype with captive steel processing capabilities. These three entities exemplify distinct competitive positions: metallurgical IP depth, upstream integration, and platform-scale cost architecture respectively.
| Leading Market Players |
|---|
| NHK Spring Co. Ltd. |
| Mubea |
| Rassini |
| Sogefi SpA |
| Thyssenkrupp AG |
| Mitsubishi Steel Mfg. Co. Ltd. |
| ZF Friedrichshafen AG |
| Tenneco Inc. |
| Lesjofors Group |
| Others |
Pricing and Supply Chain Analysis
Captive steel-forging capabilities at Thyssenkrupp AG and Mitsubishi Steel Mfg. Co. Ltd. anchor supply positions while insulating premium coil spring tiers from alloy wire volatility that compresses margins for merchant-market competitors. This upstream control translates directly into pricing power for IATF 16949-certified suppliers serving multi-year OEM platform contracts.
Pricing Analysis
Alloy steel wire cost pass-through clauses dominate coil spring contracts, with chrome-silicon and chrome-vanadium price indices resetting quarterly. Three-tier pricing structure across premium, standard, and economy levels separates IATF-certified forged components from distributor-grade aftermarket springs. Cost compression in standard-grade merchant supply is intensifying because scrap metal volatility erodes forging margins. Fleet procurement departments show lowest price sensitivity due to total cost of ownership analytics, while aftermarket distributors face highest sensitivity to spot steel movements.
Supply Chain Analysis
IATF 16949 and ISO 9001 certification gating extends supplier onboarding timelines, concentrating qualified capacity in Germany, China, and Japan. Raw material supply draws from high-tensile alloy steel wire, glass and carbon fiber filaments, and REACH-compliant anti-corrosion coatings. Single-source vulnerability concentrates in precision shot peening equipment clustered around Nagoya and Stuttgart industrial districts. Distribution runs through Tier 1 direct OEM contracts for automotive manufacturers, bypassing traditional aftermarket channels for high-volume platform supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme production incentives widen margin spreads against REACH compliance costs in European manufacturing corridors.
For Market Incumbents: To counter composite filament displacement in premium EV segments, deepen metallurgical IP moats through chrome-silicon alloy optimization and expand hot coiling furnace capacity in Tamil Nadu PLI corridors to capture localization arbitrage. For New Entrants and Emerging Players: Begin with autonomous ride-hail fleet specifications as the most penetrable white space, targeting durability-focused spring architectures distinct from consumer vehicle replacement cycles, and pursue direct fleet procurement relationships bypassing established distributor networks. For Investors and Strategic Acquirers: Roll-up economics work for specialized coil spring manufacturers with IATF 16949 pedigree because certification timelines create artificial scarcity that consolidates bargaining power with OEM platform engineers. Watch for MIIT production mandate acceleration as the inflection signal for China EV procurement volume.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Filament Capacity Buildout | Glass-reinforced polymer spring production addresses unsprung mass reduction priorities in battery-electric platforms. |
| REACH-Compliant Coating Reformulation | ECHA substance restrictions force surface treatment reinvention for European market access continuity. |
| India PLI Localization Footprint | Tamil Nadu and Maharashtra manufacturing corridors capture domestic content requirements for emerging EV assembly. |
| Direct Fleet Procurement Agreements | Long-haul trucking operators in US Midwest corridors consolidate sourcing through manufacturer bypass of distributor networks. |
| Shot Peening Precision Expansion | Surface treatment capacity additions in Shanghai and Guangzhou clusters serve domestic Chinese EV OEM qualification. |
Research Methodology
Coverage spans China, Germany, United States, Japan, and India, with primary inputs from each market cluster combining interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, and shot peening equipment specialists. Secondary validation draws from vehicle production databases, IHS Markit registration data, MIIT new energy vehicle directive filings, and ECHA REACH substance restriction updates. Bottom-up coil spring volume estimates triangulate against top-down automotive production forecasts.
Rate-of-change decomposition separates volume growth from value growth across the analysis window, with segmentation modeled by product type, material substrate, end-user channel, and regional production cluster. CAGRs derive from fitted growth curves applied to historical procurement patterns and projected EV platform penetration trajectories. Industry-specific inputs include chassis electrification roadmaps, alloy steel wire price indices, and IATF 16949 certification pipeline data.
Caveats apply where MIIT mandate acceleration, F-Gas Regulation phase-out deadlines, or alloy steel commodity volatility could materially shift the outlook. A model refresh is warranted upon material change in battery-electric platform production schedules or REACH substance restriction enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
VVT Actuators Market