
 Bus Bellows Market | 2026-2036
Bus Bellows Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Bellows Market Outlook
Modular bellows assemblies is pivoting buyer preference away from standalone component sourcing. HÜBNER GmbH & Co. KG leverages its German manufacturing base to dominate European OEM supply chains. Continental anchors global material science capabilities across rubber-to-metal bonding processes. Masats, S.A. specializes in thermoplastic configurations for lightweight transit platforms.
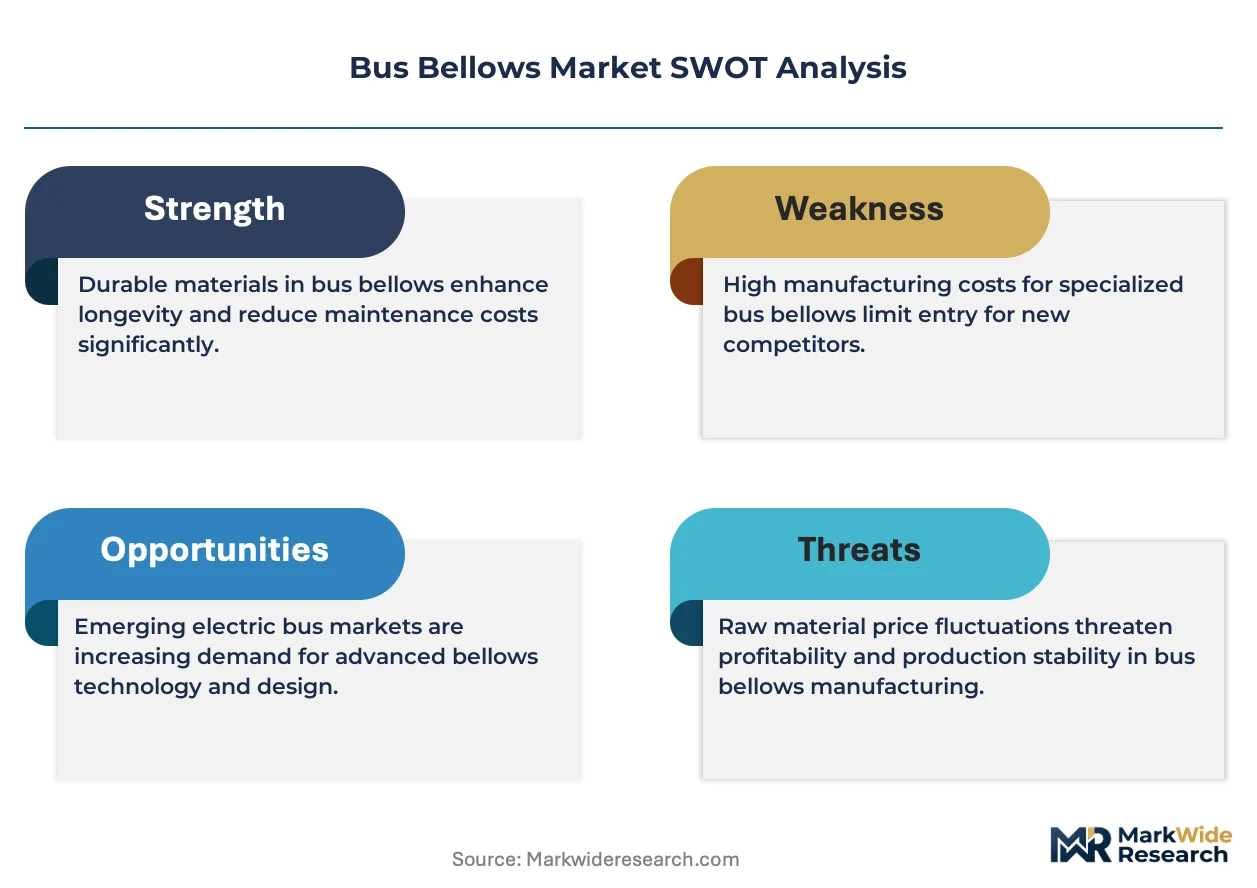
Bus bellows are flexible, accordion-shaped sealing connectors installed between articulated bus sections to protect wiring, pneumatic lines, and passenger gangways from debris, moisture, and thermal stress, typically manufactured from EPDM rubber, reinforced fabric plies, or thermoplastic elastomers with specified fatigue-cycle ratings exceeding 500,000 operations. Their primary purpose is maintaining environmental integrity and operational safety in high-articulation transit vehicles. Composite bellows command premium positioning due to hybrid material stacks balancing weight reduction with abrasion resistance. Electric bus applications represent the fastest-growing segment as zero-emission fleet mandates reshape procurement specifications. Retrofit installation channels face margin compression from shorter replacement cycles in high-utilization urban corridors.
FDA material-contact guidelines, ECHA REACH substance restrictions, and China's GB/T rubber standards collectively govern base compound approvals and cross-border component eligibility. NHTSA bus safety protocols in the United States and EU MDR-adjacent durability benchmarks for transit infrastructure further tighten product qualification thresholds. Stakeholders must monitor evolving electric bus platform architectures where integrated sensor bellows and predictive wear systems redefine supplier capability requirements.
Market Dynamics
Articulated bus electrification mandates are compressing replacement cycles and rewriting durability specifications across municipal procurement corridors. Transit agencies now specify integrated sensor bellows and predictive wear systems as baseline requirements, forcing material suppliers to requalify compounds under accelerated fatigue protocols.
Growth Catalysts
- China's MIIT durability standards:Stricter GB/T rubber specifications for bus connecting systems are disqualifying legacy compounds and opening certified supplier slots for EPDM specialists with validated fatigue-cycle documentation.
- São Paulo fleet electrification:Brazil's largest municipal transit operator is expanding articulated electric bus corridors, generating concentrated demand for thermoplastic bellows configurations rated for tropical thermal cycling.
- EPDM-to-thermoplastic material migration:Lightweight transit platforms in Stuttgart and Shenzhen are specifying hybrid material stacks that reduce per-unit mass while maintaining abrasion resistance thresholds.
Market Restraints
- Natural rubber price volatility:EPDM compound costs fluctuate with Malaysian and Thai feedstock availability, compressing margins for standardized bellows manufacturers without captive polymer supply.
- German supplier concentration:European OEM supply chains anchor heavily on Baden-Württemberg manufacturing clusters, creating geographic single-source exposure for just-in-time assembly lines.
- Polyurethane substitution threat:Injection-molded thermoplastic elastomers from automotive sealing applications are crossing over into retrofit channels at 15-20% cost deltas against fabric-reinforced rubber assemblies.
Strategic Opportunities
- India's urban bus rapid transit expansion:Cities including Ahmedabad and Indore are tendering articulated fleet additions without legacy supplier relationships, creating first-mover windows for certified entrants.
- Integrated sensor bellows convergence:Predictive wear monitoring systems combining fiber optic strain sensing with thermoplastic housings are enabling outcome-based maintenance contracts with transit agencies.
- EU Green Deal procurement incentives:Lifecycle carbon accounting requirements for public transport infrastructure are favoring suppliers with verified recycled-content EPDM and closed-loop manufacturing footprints.
Industry Challenges
- Multi-standard certification timelines:Simultaneous NHTSA, ECHA REACH, and GB/T qualification processes extend product launch cycles by 18-24 months for global platform suppliers.
- Rubber-to-metal bonding process expertise:Qualified technicians for vulcanization bonding of fabric plies to aluminum frames are concentrated in aging workforces across German and Japanese manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Bellows Market |
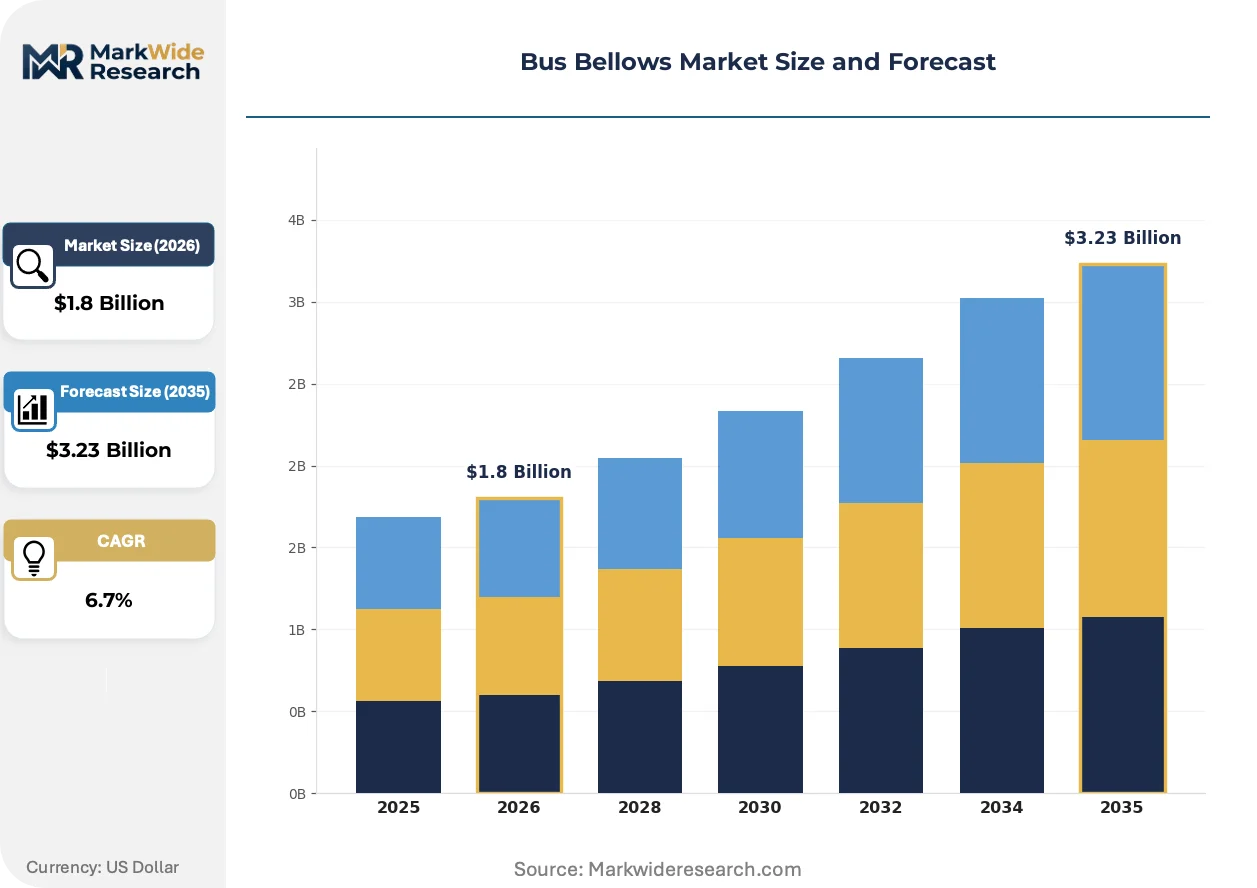
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Bellows, Fabric Bellows, Composite Bellows, Metal Bellows Application: Passenger Vehicles, Coaches, Electric Buses, School Buses Installation Type: In-Factory Installation, Retrofit Installation, Field Service Installation, Maintenance Replacement End User: Bus Manufacturers, Public Transport Operators, Fleet Owners, Aftermarket Suppliers |
| Companies Covered | Continental, FENIKSbus d.o.o., HÜBNER GmbH & Co. KG, Dynatect Manufacturing, Interstate-McBee, LLC, ATG Autotechnik GmbH, Masats, S.A., PEI Mobility, Bellow and Bus (Pty) Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Bellows Market Strategic Shifts
Smart material integration and predictive maintenance architectures are redefining bus bellows from passive sealing components to active data collection nodes. The competitive frontier now sits at the intersection of polymer science, embedded sensing, and fleet management software.
Thermoplastic elastomer bellows with embedded fiber optic strain sensors are expanding into electric bus platforms requiring real-time articulation angle monitoring. Shenzhen-based fleet operators are specifying these configurations for 18-meter battery-electric articulated vehicles. The technology is expanding into predictive maintenance contracts that unbundle hardware supply from performance-guaranteed service agreements.
EU MDR-adjacent durability benchmarks for transit infrastructure are tightening fatigue-cycle documentation requirements across European procurement corridors. Suppliers must now submit third-validated test data exceeding 500,000 operations for GB/T and REACH compound approvals. Articulated bus OEMs in Stuttgart and Mannheim are consolidating supplier panels to vendors with pre-qualified regulatory dossiers.
Fleet operators are unbundling after-sales service from initial equipment procurement, compressing traditional component margins while opening recurring revenue streams. Municipal transit agencies in São Paulo and Curitiba now specify performance-based maintenance clauses with penalty structures for unplanned downtime. This reconfiguration is most visible in high-utilization corridors where replacement cycle frequency dominates total cost of ownership calculations.
Bus Bellows Market Segmentation
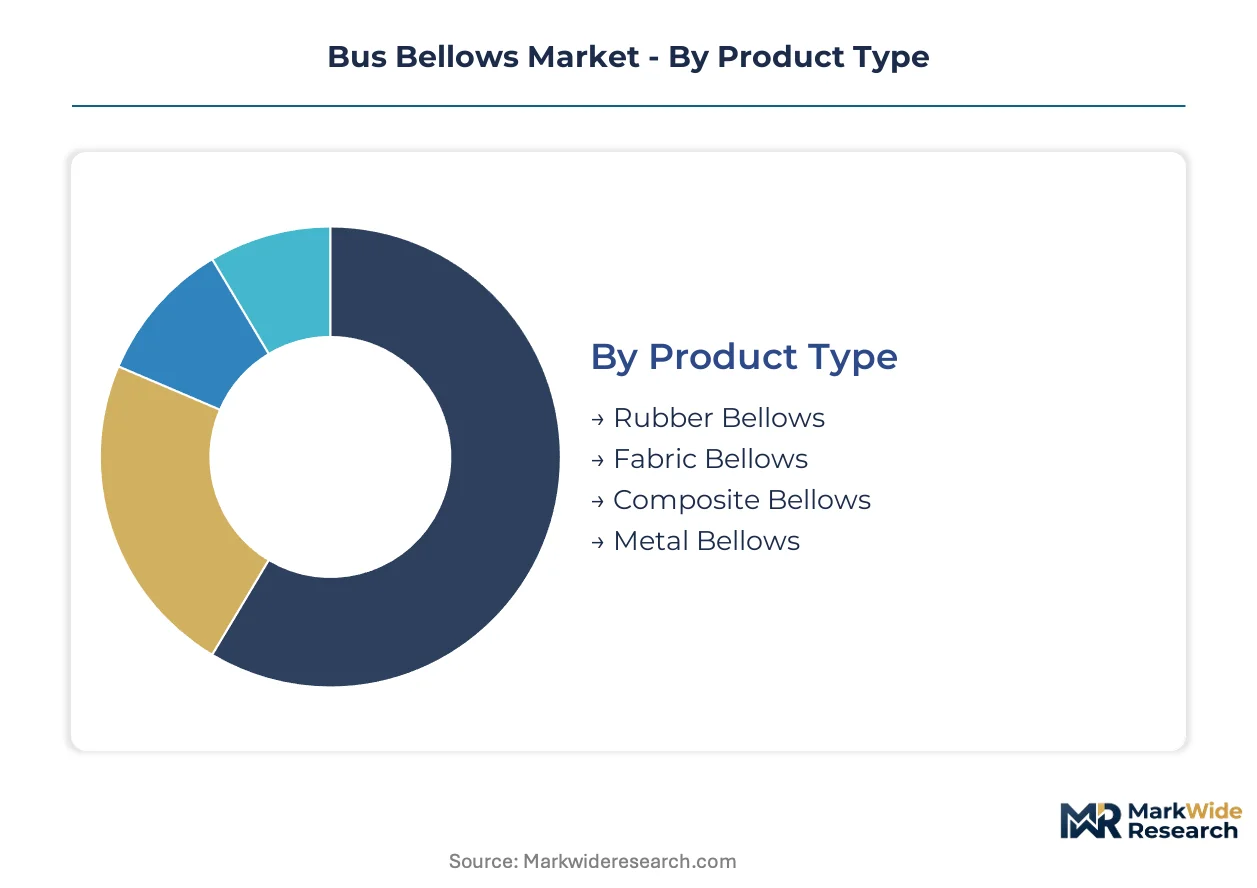
Bus bellows procurement diverges sharply across material specifications, vehicle architectures, and channel economics. Understanding these fault lines reveals where pricing power concentrates and which supplier capabilities command premium positioning.
Product Type:
Material composition dictates fatigue-cycle performance, weight targets, and regulatory qualification burdens across procurement specifications.
- Rubber Bellows:EPDM and natural rubber compounds reinforced with fabric plies dominate legacy articulated fleets. São Paulo's tropical thermal cycling corridors and Stuttgart's high-frequency municipal lines specify these configurations for validated durability exceeding 500,000 operations under GB/T and REACH protocols.
- Composite Bellows:Hybrid material stacks combining thermoplastic elastomers with fiber-reinforced polymers balance weight reduction against abrasion resistance. Shenzhen's 18-meter battery-electric articulated platforms specify composite configurations to maximize battery range while maintaining sealing integrity.
- Fabric Bellows:Coated textile assemblies serve cost-sensitive retrofit channels in India's emerging bus rapid transit corridors.
- Metal Bellows:Stainless steel convoluted designs handle extreme thermal environments in specialized coach applications.
Rubber bellows lead on scale; composite bellows lead on momentum.
Application:
Vehicle electrification mandates are fragmenting durability specifications and rewiring supplier qualification requirements.
- Electric Buses:Battery-electric articulated platforms demand integrated sensor bellows with predictive wear monitoring. Curitiba and Shenzhen fleet operators specify real-time articulation angle tracking for 18-meter vehicles, unbundling hardware procurement from performance-based maintenance contracts.
- Coaches:Intercity configurations prioritize acoustic dampening and extended service intervals over rapid-cycle durability.
- Passenger Vehicles:Standard transit buses specify conventional EPDM bellows for moderate articulation frequencies.
- School Buses:Safety-regulated segments in the United States require NHTSA-certified compounds with enhanced fire resistance.
Electric buses are expanding most quickly; coaches retain the highest per-unit margins.
Installation Type:
Channel economics separate captive OEM supply from fragmented aftermarket replacement cycles.
- In-Factory Installation:OEM assembly lines in Baden-Württemberg manufacturing clusters specify pre-qualified modular bellows assemblies. Just-in-time delivery contracts lock in multi-year supply relationships with validated fatigue-cycle documentation.
- Retrofit Installation:Third-party upgrade channels face margin compression from polyurethane thermoplastic elastomers crossing over from automotive sealing applications at cost deltas of 15-20 percent.
- Field Service Installation:Emergency replacement protocols concentrate in high-utilization urban corridors with compressed downtime windows.
- Maintenance Replacement:Scheduled lifecycle programs are unbundling from initial equipment procurement into recurring revenue streams.
In-factory installation commands pricing power; retrofit channels face steepest margin pressure.
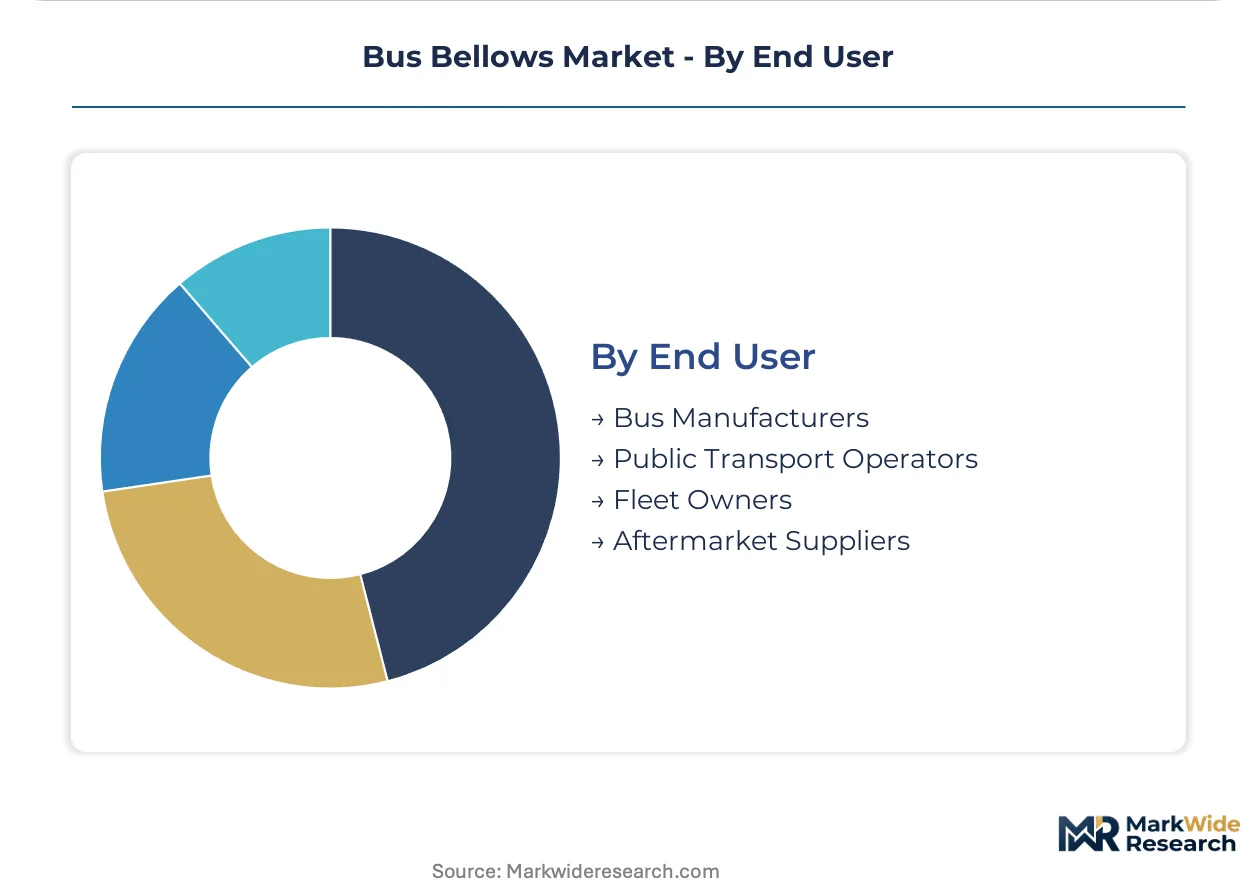
End User:
Buyer sophistication and procurement leverage vary dramatically across the value chain.
- Public Transport Operators:Municipal agencies in São Paulo, Curitiba, and Stuttgart specify outcome-based maintenance clauses with penalty structures for unplanned downtime. These stakeholders now mandate integrated sensor bellows and predictive wear systems as baseline requirements.
- Bus Manufacturers:OEM consolidation in Mannheim and Stuttgart is narrowing supplier panels to vendors with pre-qualified regulatory dossiers spanning NHTSA, ECHA REACH, and GB/T standards.
- Fleet Owners:Private operators prioritize total cost of ownership calculations over upfront equipment costs.
- Aftermarket Suppliers:Independent distributors serve fragmented replacement demand without captive manufacturing relationships.
Public transport operators drive specification upgrades; bus manufacturers control supplier access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered articulated bus manufacturing in Europe, establishing the technical foundation for modern bellows specifications that now govern procurement across three continents. The industry's geographic footprint now spans mature OEM clusters, electrification corridors, and emerging rapid transit markets.
Germany
Baden-Württemberg manufacturing clusters anchor European OEM supply chains for modular bellows assemblies. KBA vehicle safety protocols enforce durability documentation exceeding 500,000 fatigue cycles for transit infrastructure components. Stuttgart and Mannheim assembly lines specify pre-qualified EPDM compounds under EU MDR-adjacent benchmarks.
China
Shenzhen's 18-meter battery-electric articulated fleet generates concentrated demand for integrated sensor bellows with real-time articulation monitoring. MIIT enforces stricter GB/T rubber specifications for bus connecting systems that disqualify legacy compounds. The Pearl River Delta manufacturing base supplies thermoplastic configurations for lightweight transit platforms.
Brazil
São Paulo's municipal transit operator is expanding articulated electric bus corridors through tropical thermal cycling environments. ANVISA material-contact guidelines intersect with municipal procurement mandates for outcome-based maintenance clauses. Curitiba fleet operators specify predictive wear systems for high-utilization urban corridors.
United States
NHTSA bus safety protocols govern EPDM compound approvals for school bus and transit applications with enhanced fire resistance requirements. The Southeast manufacturing corridor serves retrofit installation channels facing margin compression from polyurethane substitution. California's zero-emission fleet mandates reshape durability specifications for electric bus procurement.
India
Ahmedabad and Indore are tendering articulated fleet additions for bus rapid transit expansion without legacy supplier relationships. BIS rubber standards create certification pathways for first-mover entrants into emerging procurement corridors. The Delhi-NCR urban agglomeration concentrates demand for cost-sensitive fabric bellows configurations.
Bus Bellows Market Competitive Environment
Premium-margin players sit above commodity-margin players across material qualification and regulatory dossier depth. The vendor base stratifies between EPDM specialists with validated fatigue-cycle documentation and thermoplastic converters crossing over from automotive sealing applications. Three archetypes dominate: German OEM-anchored fabricators with captive rubber-to-metal bonding expertise, Spanish and Slovenian mid-cap specialists in thermoplastic configurations, and diversified industrial conglomerates with global material science capabilities. Competitive moves concentrate on regulatory pre-qualification sprinting and predictive maintenance service unbundling.
Among German fabricators, HÜBNER GmbH & Co. KG and ATG Autotechnik GmbH occupy positions within the premium-tier OEM supply chain, exemplifying Baden-Württemberg's concentration of vulcanization bonding expertise. Masats, S.A. represents the thermoplastic specialization vector for lightweight transit platforms. Continental anchors the diversified conglomerate archetype with cross-industry material science capabilities.
| Leading Market Players |
|---|
| Continental |
| FENIKSbus d.o.o. |
| HÜBNER GmbH & Co. KG |
| Dynatect Manufacturing |
| Interstate-McBee, LLC |
| ATG Autotechnik GmbH |
| Masats, S.A. |
| PEI Mobility |
| Bellow and Bus (Pty) Ltd |
| Others |
Value Chain & Pricing Dynamics
Malaysian natural rubber futures volatility cascades through EPDM compound costs into three distinct pricing tiers across procurement corridors. Transit agencies in Stuttgart and São Paulo face divergent landed cost structures depending on captive polymer supply versus spot-market exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates modular sensor-integrated assemblies from conventional fabric-reinforced configurations and basic retrofit components. Price differentiation hinges on GB/T fatigue-cycle certification tier and volume scale commitments. Cost compression in the retrofit tier is intensifying as polyurethane thermoplastic elastomers cross over from automotive sealing applications. Fleet operators in high-utilization corridors exhibit lowest price sensitivity due to unplanned downtime penalty clauses, while independent aftermarket distributors face acute margin pressure.
Supply Chain Analysis
China's MIIT domestic-content mandates for bus connecting systems are reshaping sourcing patterns across Pearl River Delta manufacturing bases. Supply concentrates in Germany, China, and Brazil, with Baden-Württemberg clusters anchoring European OEM relationships. Raw material dependencies center on Malaysian and Thai EPDM feedstock, German aluminum extrusion frames, and Japanese fiber-reinforced polymer fabrics. Single-source vulnerability runs through aging vulcanization technician workforces concentrated in German manufacturing bases. Distribution runs through just-in-time OEM assembly contracts and fragmented third-party retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA REACH substance restrictions and China's GB/T durability standards continuously elevate qualification barriers for new compounds.
For Market Incumbents: Anchor rubber-to-metal bonding expertise through apprenticeship pipelines in Baden-Württemberg manufacturing clusters to counter workforce aging. Deepen captive polymer supply arrangements with Malaysian feedstock processors to insulate margin structures from spot-market volatility. Consolidate supplier panel positions by pre-qualifying regulatory dossiers across NHTSA, ECHA REACH, and GB/T standards before procurement cycles commence. For New Entrants and Emerging Players: Launch via certified compound partnerships targeting India's bus rapid transit expansion in Ahmedabad and Indore corridors lacking legacy supplier relationships. Concentrate initial positioning on thermoplastic configurations for tropical thermal cycling environments where EPDM specialists carry cost disadvantages. Pursue outcome-based maintenance contract structures that unbundle hardware from performance-guaranteed service agreements. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap thermoplastic specialists possessing validated fatigue-cycle documentation and pre-qualified regulatory dossiers. Long-term viability over a multi-year window favors suppliers with integrated sensor bellows capabilities as predictive maintenance architectures reshape procurement specifications. Monitor GB/T standard revision announcements as the primary inflection signal for compound requalification windows and supplier displacement opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Pre-Qualification | Accelerates OEM supplier panel access across Stuttgart and Mannheim assembly corridors. |
| Sensor Integration Partnership | Enables predictive maintenance contracts with São Paulo and Curitiba fleet operators. |
| Captive Polymer Supply Arrangement | Insulates margin structures from Malaysian natural rubber futures volatility. |
| Apprenticeship Pipeline Investment | Addresses vulcanization technician scarcity in aging German manufacturing workforces. |
| Thermoplastic Configuration Scale-Up | Captures lightweight transit platform demand from Shenzhen battery-electric fleets. |
Study Parameters
Direct dialogue with transit agency procurement officers, OEM platform engineers, EPDM compound technical directors, and aftermarket distribution heads grounded the qualitative foundation. Secondary validation drew from MIIT GB/T standard filings, KBA vehicle safety protocol documentation, ANVISA material-contact guidelines, and customs trade data for rubber-to-metal bonded components. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level outputs spanning material composition, vehicle architecture, installation channel, and end-user buyer type fed into the analytical framework. CAGRs were derived from regression analysis against electric bus fleet procurement trajectories and articulated vehicle production volumes. Model inputs incorporated MIIT durability standard enforcement timelines, EU Green Deal procurement incentive adoption curves, and tropical thermal cycling degradation rates for EPDM compounds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt natural rubber supply disruptions or accelerated polyurethane substitution in retrofit channels. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM supplier panel consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Airport Bus Market
Buses
Global Luxury Shuttle Bus Market
Buses
North America Bus Market
Buses
Buses & Coaches Market
Buses
Bus Seat Market
Buses
Bus Rental Market
Buses
Canada Transit Buses Market
Buses
Fuel Cell Electric Bus Market
Buses
Europe Trolley Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Bus Charter Services Market
Buses
Bus Chassis Market
Buses
Electric Intercity Bus Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Bus Flooring Market
Buses
Hydrogen Buses Market