
 Global Train Control and Management Systems Market | 2026-2036
Global Train Control and Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Train Control and Management Systems Market Intelligence
Copper interconnect infrastructure is shifting toward fiber-optic backbones in modern train control architectures, reducing electromagnetic interference susceptibility while boosting data throughput for real-time signaling. Siemens AG leverages captive semiconductor sourcing to secure component availability for its European signaling deployments. Alstom anchors its market position through concentrated R&D spending on hybrid CBTC-ERTMS platforms. Hitachi Ltd. dominates Japan's Shinkansen upgrade cycles with proprietary train-to-ground communication protocols.
Train Control and Management Systems integrate onboard microprocessor units, wayside control equipment, and centralized traffic management software to supervise train movement, enforce speed restrictions, and optimize headway distances across rail networks. These systems process location data through balise transponders and axle counters, transmitting commands via IEEE 1474-compliant wireless or wired links to ensure safe separation between rolling stock. Communication-Based Train Control leads technology adoption in dense urban corridors where headways below 90 seconds justify infrastructure-intensive upgrades. Positive Train Control represents a mature regulatory-mandated segment in North American freight corridors, with margin pools shifting toward lifecycle maintenance and software refresh cycles. Satellite Communication and GSM-R technologies compete for rural and intercity deployments where terrestrial radio coverage remains economically challenging.
The EU's ERTMS deployment mandates under the European Railway Agency framework compel cross-border infrastructure harmonization, while the Federal Railroad Administration enforces PTC compliance across Class I freight routes in the United States. Japan's Ministry of Land, Infrastructure, Transport and Tourism certifies proprietary signaling protocols that create de facto import barriers for foreign TCMS vendors. Stakeholders must monitor divergence between sovereign certification regimes and the IEEE 1474 standardization push to anticipate platform architecture bets.
Market Dynamics
EU ERTMS deployment mandates under the European Railway Agency framework are compressing supplier certification timelines while forcing cross-border interoperability investments that reshape vendor competitive economics.
Growth Catalysts
- ERTMS Level 3 mandates:The European Railway Agency framework compels corridor upgrades across Germany, France, and Italy, eliminating national legacy systems.
- Urban metro densification:Indian cities including Mumbai and Delhi are expanding fleet procurement to achieve sub-90-second headways.
- Fiber-optic backbone migration:Electromagnetic interference reduction requirements in Japanese Shinkansen corridors are accelerating copper-to-fiber infrastructure replacement.
Market Restraints
- Semiconductor supply concentration:Captive foundry capacity at TSMC and Samsung constrains availability of automotive-grade microprocessors for onboard control units.
- Proprietary protocol lock-in:Japan's Ministry of Land, Infrastructure, Transport and Tourism certification requirements create de facto import barriers for foreign TCMS vendors.
- Copper price volatility:Legacy signaling infrastructure still relies on copper interconnects, exposing maintenance budgets to London Metal Exchange price swings.
Strategic Opportunities
- India's Dedicated Freight Corridors:The Dedicated Freight Corridor Corporation is tendering for new-build TCMS installations without legacy system integration burdens.
- Hybrid CBTC-ERTMS platforms:Convergence of urban metro and mainline signaling standards enables single-supplier consolidation across previously separate procurement silos.
- Satellite-based rural signaling:ESA's RailSAT initiative offers an alternative to GSM-R for intercity deployments across Spain and Scandinavia where terrestrial coverage is uneconomical.
Industry Challenges
- Embedded systems engineering talent scarcity:Railway-specific firmware development requires SIL 4 safety certification expertise that outpaces European university pipeline output.
- Legacy system integration complexity:German and Swiss operators must maintain interoperability between new ERTMS deployments and existing LZB and PZB installations during multi-year transition windows.
- IEEE 1474 compliance timeline compression:Standardization divergence between regional certification regimes forces vendors to maintain parallel development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Train Control and Management Systems Market |
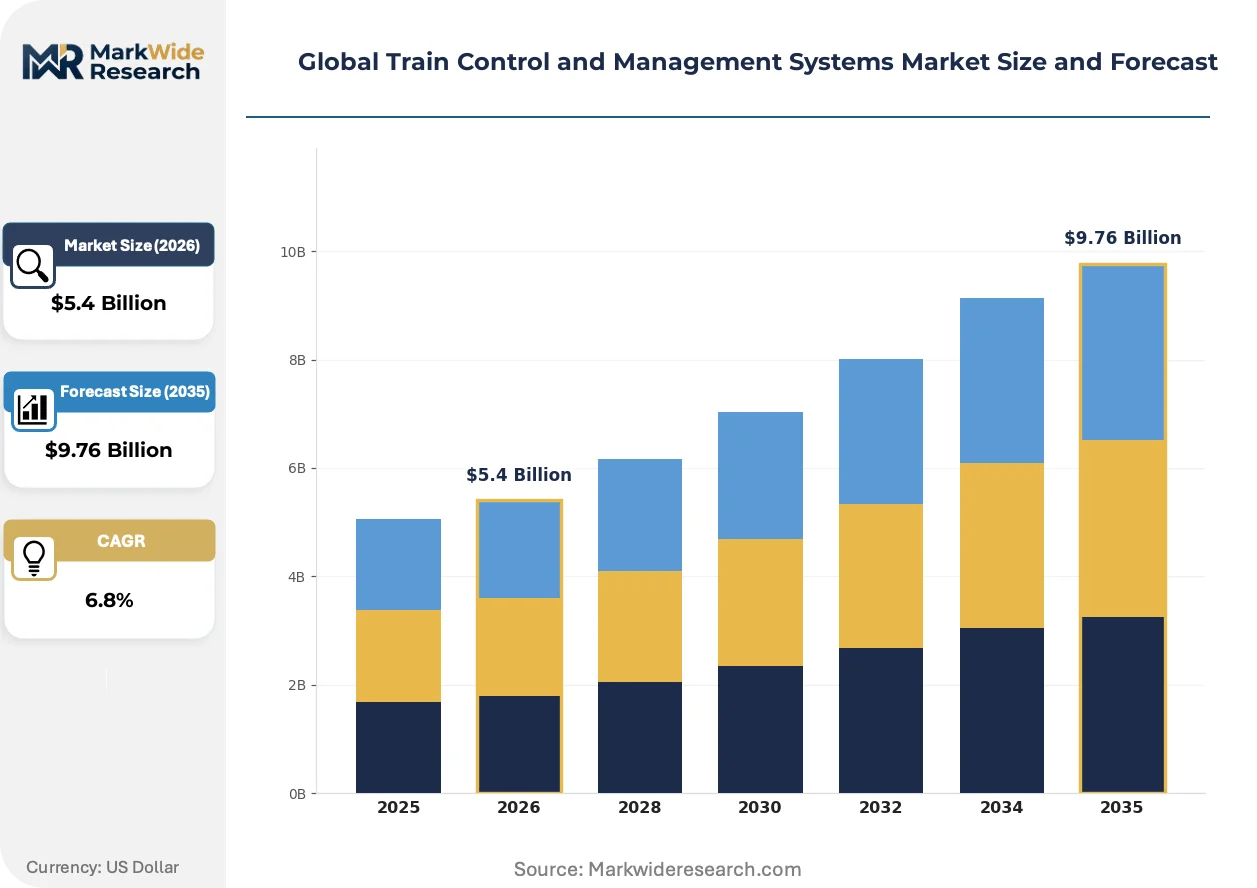
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Automatic Train Control, Positive Train Control, Communication-Based Train Control, Electronic Interlocking Technology: Radio Frequency, Satellite Communication, Optical Fiber, Wi-Fi, GSM-R Application: High-Speed Rail, Freight Transport, Urban Transit, Long-Distance Passenger, Subway End User: Railway Operators, Infrastructure Providers, Signaling Companies, Maintenance Providers, Transport Authorities |
| Companies Covered | Siemens AG, Alstom, Hitachi Ltd., Mitsubishi Electric Corporation, Toshiba Corporation, Thales Group, Bombardier Inc., Knorr-Bremse AG, CAF, Construcciones y Auxiliar de Ferrocarriles, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Train Control and Management Systems Market Strategic Shifts & Innovations
Digitalization of train-to-ground communication architectures is compressing the gap between urban metro and mainline signaling capabilities, while sovereign certification regimes fragment standardization momentum.
Moving-block signaling algorithms are automating headway optimization in dense corridors. Paris Metro and London Underground operators are retrofitting legacy fixed-block infrastructure with continuous position-reporting capabilities. This convergence is automating the vendor selection criteria that previously separated urban and intercity procurement categories.
REACH restrictions on halogenated flame retardants are forcing PCB substrate material transitions in onboard control equipment. European TCMS vendors face reformulation deadlines for their rolling stock electronics supply chains. Wayside equipment manufacturers serving Germany and France are accelerating ceramic-based alternative qualification programs.
Lifecycle service contracting is displacing upfront capital procurement in mature European markets. Deutsche Bahn and SNCF are unbundling hardware acquisition from 15-year availability guarantees. French and British operators now specify outcome-based performance metrics that transfer operational risk to system integrators.
Global Train Control and Management Systems Market Segmentation
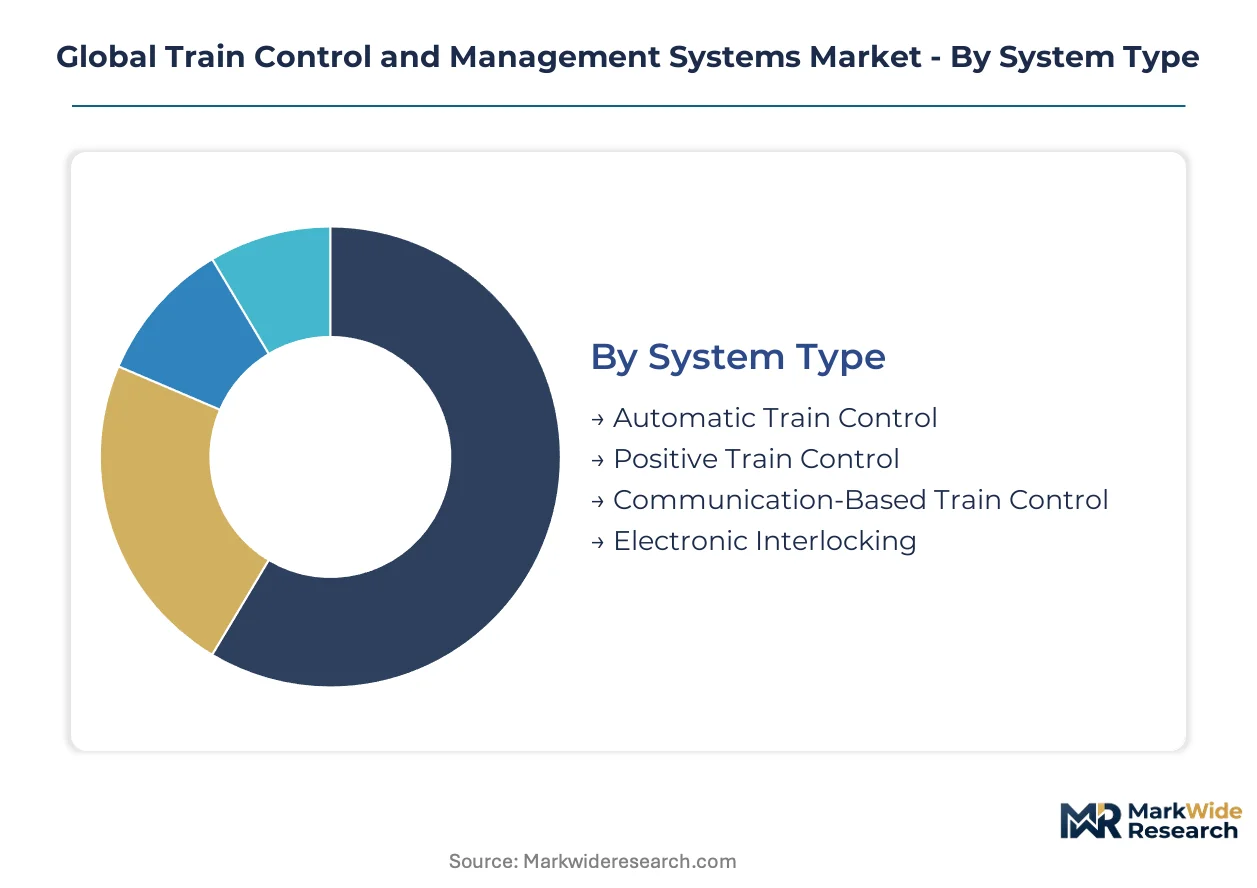
Train control procurement splits across four distinct decision hierarchies. System type determines capital intensity and safety certification requirements. Technology selection governs electromagnetic compatibility and rural coverage economics. Application context dictates headway specifications and interoperability mandates. End-user category shapes contract structure and lifecycle service expectations.
System Type:
Capital allocation thresholds separate procurement committees by corridor density and regulatory mandate stringency.
- Communication-Based Train Control:Continuous bidirectional train-to-wayside data exchange enables moving-block headways below 90 seconds. Mumbai Metro and Delhi Metro are expanding CBTC deployments to achieve sub-90-second frequencies on congested lines.
- Positive Train Control:GPS-augmented enforcement of speed restrictions and authority limits dominates North American freight corridors. The Federal Railroad Administration mandates PTC across Class I routes, shifting vendor revenue toward 15-year maintenance and software refresh cycles.
- Automatic Train Control:Wayside-to-train speed supervision with cab signaling remains prevalent in legacy Japanese and European installations.
- Electronic Interlocking:Microprocessor-based route setting and signal control replaces relay-based logic in German and Swiss renewal programs.
CBTC leads on scale; PTC leads on momentum through regulatory compulsion.
Technology:
Electromagnetic environment and terrain economics drive transmission medium selection across deployment contexts.
- Optical Fiber:Immunity to interference and terabit-scale bandwidth support real-time video and diagnostic data in Japanese Shinkansen corridors. JR East is replacing copper backbones with fiber to eliminate lightning-induced signaling failures.
- GSM-R:Railway-specific voice and data radio serves as the ERTMS bearer standard across Germany, France, and Italy. European Railway Agency mandates compel interoperability testing against national legacy installations.
- Radio Frequency:IEEE 1474-compliant 2.4 GHz and 5.8 GHz links serve urban metro CBTC deployments with limited spectrum licensing friction.
- Satellite Communication:ESA's RailSAT initiative offers coverage for Spanish and Scandinavian intercity routes where terrestrial infrastructure is uneconomical.
- Wi-Fi:Unlicensed spectrum supports non-safety-critical passenger information and maintenance diagnostics.
Optical fiber commands premium deployment economics; satellite links are gaining share fastest in rural gaps.
Application:
Speed regime and passenger volume density determine signaling complexity and supplier qualification tiers.
- Urban Transit:High-frequency metro and light rail operations demand sub-90-second headways with continuous position reporting. Indian cities including Mumbai and Delhi are procuring integrated train control and platform screen door systems.
- High-Speed Rail:Train control must enforce braking curves above 250 km/h with ETCS Level 2 or national equivalents. Japan's Ministry of Land, Infrastructure, Transport and Tourism certifies proprietary protocols that limit foreign vendor participation.
- Subway:Underground electromagnetic environments favor leaky feeder or radiating cable solutions over free-space radio.
- Freight Transport:North American heavy-haul corridors prioritize collision avoidance and authority enforcement over headway optimization.
- Long-Distance Passenger:Mixed-traffic mainlines require interoperability between passenger and freight signaling standards.
Urban transit dominates procurement volume; high-speed rail shows the steepest expansion trajectory through corridor electrification programs.
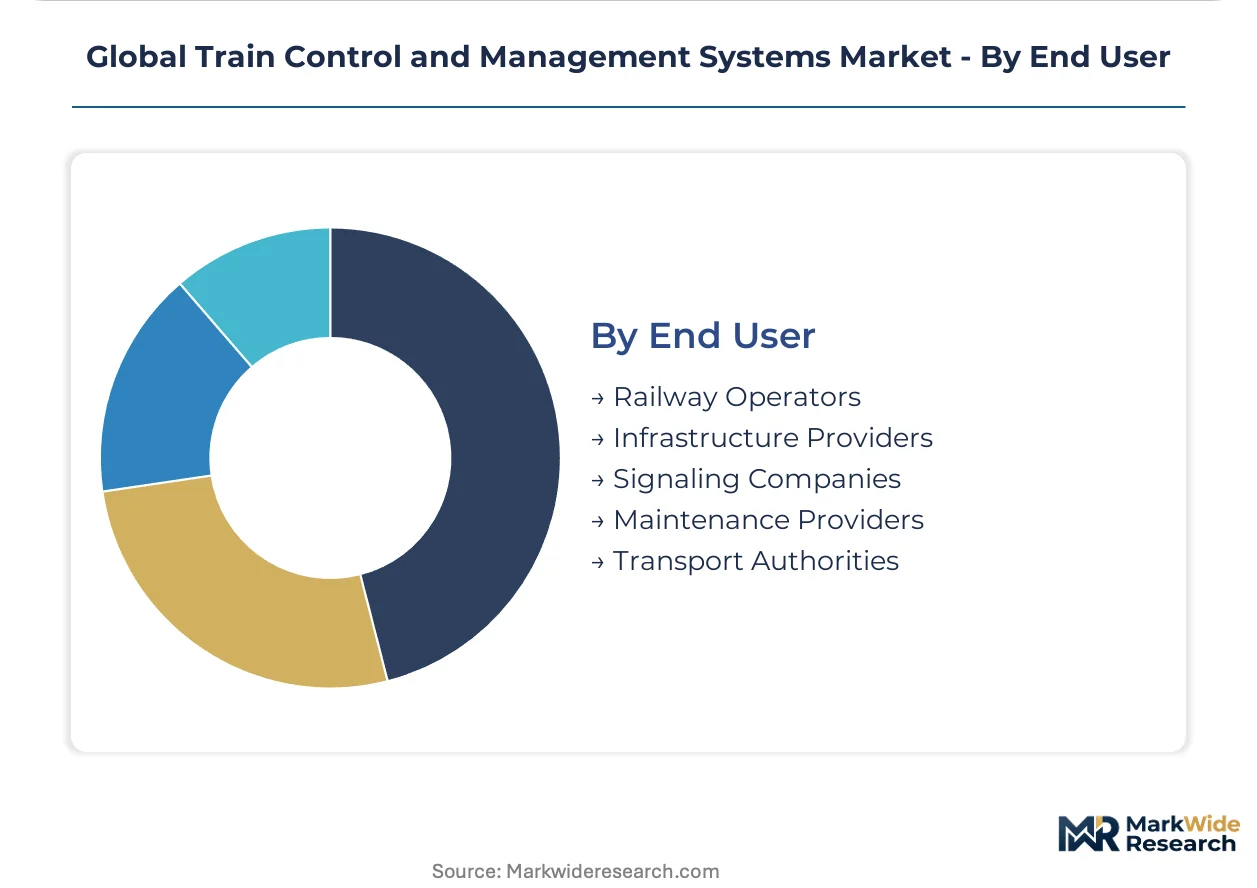
End User:
Contracting authority determines risk allocation between capital expenditure and operational outcome guarantees.
- Railway Operators:Deutsche Bahn and SNCF are unbundling hardware acquisition from availability-based performance contracts spanning 15 years.
- Infrastructure Providers:Germany's DB Netz and Italy's RFI specify ERTMS migration timelines under European Railway Agency framework mandates.
- Signaling Companies:System integrators bear SIL 4 certification liability and embedded firmware development costs.
- Maintenance Providers:Lifecycle service specialists capture recurring revenue from obsolescence management and predictive analytics.
- Transport Authorities:Indian Dedicated Freight Corridor Corporation tenders specify greenfield TCMS without legacy integration burdens.
Railway operators anchor contract value; infrastructure providers are concentrating procurement authority through network rationalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors European TCMS procurement through Deutsche Bahn's ERTMS Level 3 migration timeline. The Federal Network Agency's infrastructure investment mandates compress supplier certification windows while DB Netz unbundles hardware acquisition from 15-year availability contracts.
Germany
Deutsche Bahn's corridor electrification program drives demand for hybrid CBTC-ERTMS platforms. The Federal Network Agency mandates interoperability testing against legacy LZB installations during transition windows. Siemens AG leverages captive semiconductor sourcing from its Munich headquarters to secure component availability for signaling deployments across Bavaria and North Rhine-Westphalia.
Japan
JR East's Shinkansen upgrade cycles require proprietary train-to-ground communication protocols. The Ministry of Land, Infrastructure, Transport and Tourism certifies domestic signaling standards that create import barriers for foreign vendors. Hitachi Ltd. dominates procurement in the Kanto corridor around Tokyo through concentrated R&D on fiber-optic backbone migration.
India
The Dedicated Freight Corridor Corporation is tendering for greenfield TCMS installations without legacy integration burdens. The Ministry of Railways specifies sub-90-second headway requirements for Mumbai and Delhi metro expansions under the National Rail Plan. Alstom's manufacturing presence in Andhra Pradesh positions it for corridor electrification tenders across the Delhi-Mumbai Industrial Corridor.
United States
Class I freight operators complete Positive Train Control compliance mandates across Union Pacific and BNSF networks. The Federal Railroad Administration enforces GPS-augmented speed restriction enforcement through regulatory deadlines. Wabtec Corporation captures lifecycle maintenance contracts in the Chicago rail hub as margin pools shift from capital procurement to software refresh cycles.
France
SNCF's ERTMS deployment under the European Railway Agency framework eliminates national legacy systems on cross-border routes. The French rail safety authority mandates SIL 4 certification for onboard control units in the Paris-Lyon high-speed corridor. Thales Group concentrates R&D spending at its Paris headquarters to secure mainline signaling contracts through the Grand Est and Auvergne-Rhône-Alpes regions.
Global Train Control and Management Systems Market Key Industry Players
Global majors compete with regional champions across certification regime fragmentation, technology platform divergence, and sovereign procurement preference enforcement. The vendor base organizes around three strategic archetypes: integrated European conglomerates with captive semiconductor supply, Japanese specialists with proprietary protocol lock-in, and emerging Indian system integrators leveraging greenfield corridor tenders. Dominant competitive moves include hybrid platform convergence bets and lifecycle service contracting unbundling.
Within the integrated European tier, Siemens AG and Alstom exemplify full-stack system integrators spanning onboard units, wayside equipment, and centralized traffic management software. Thales Group occupies a position among defense-electronics crossover specialists applying aerospace-grade safety certification to rail signaling. Among Japanese manufacturers, Hitachi Ltd. and Mitsubishi Electric Corporation represent domestic market anchors with proprietary protocol development capabilities. Toshiba Corporation sits within the industrial electronics conglomerate archetype with rolling stock control heritage. Knorr-Bremse AG exemplifies the braking-systems specialist expanding into integrated train control through component-level integration.
| Leading Market Players |
|---|
| Siemens AG |
| Alstom |
| Hitachi Ltd. |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Thales Group |
| Bombardier Inc. |
| Knorr-Bremse AG |
| CAF, Construcciones y Auxiliar de Ferrocarriles, S.A. |
| Others |
Cost & Logistics Intelligence
Captive semiconductor sourcing by Siemens and Alstom anchors both supply security and pricing power for European signaling deployments, insulating these vendors from foundry allocation shocks that compress margins for competitors dependent on merchant silicon.
Pricing Analysis
Input-cost pass-through from automotive-grade microprocessors and fiber-optic cable runs through project-based contract structures, with Siemens and Alstom commanding premium positioning through SIL 4 certification depth and captive component supply. Price differentiation separates ERTMS Level 3 full-stack integrators from maintenance-only service providers, with Deutsche Bahn and SNCF least sensitive to upfront capital outlays when bundled with 15-year availability guarantees. Pricing pressure stems from Indian greenfield tenders attracting low-cost Asian system integrators unburdened by legacy certification overhead. Municipal transport authorities in Mumbai and Delhi exhibit highest price sensitivity, prioritizing per-kilometer procurement metrics over lifecycle service bundling.
Supply Chain Analysis
Reverse-logistics flows for wayside equipment refurbishment concentrate in Germany and France, where Deutsche Bahn and SNCF operate dedicated remanufacturing facilities for axle counters and balise transponders nearing end-of-design-life. Component sourcing draws from Taiwan and South Korea for safety-critical microprocessors, Japan for proprietary optical transceivers in Shinkansen corridors, and China for non-safety-critical PCB assemblies. Single-source vulnerability in automotive-grade silicon foundry capacity constrains delivery schedules for onboard control units. Distribution runs through system integrator direct sales for ERTMS deployments, with maintenance service contracts disintermediating traditional distribution channels in mature European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with European Railway Agency ERTMS Level 3 mandates generating sustained demand visibility through mandated corridor upgrade timelines that eliminate national legacy systems.
For Market Incumbents: Acquire embedded firmware engineering teams with SIL 4 safety certification expertise to offset European university pipeline shortfalls. Consolidate hybrid CBTC-ERTMS platform development to capture procurement unification across urban metro and mainline segments previously siloed. Threat substitution from satellite-based RailSAT alternatives in rural Scandinavia and Spain compresses GSM-R equipment refresh cycles, forcing accelerated R&D redeployment. For New Entrants and Emerging Players: Begin with India's Dedicated Freight Corridor Corporation greenfield tenders, where absence of legacy system integration burdens lowers certification barriers for non-incumbent system integrators. Target Mumbai and Delhi metro expansions specifying sub-90-second headways with integrated platform screen door requirements. Go-to-market through joint venture structures with established rolling stock manufacturers to bypass proprietary protocol lock-in in Japan. For Investors and Strategic Acquirers: Roll-up economics work for lifecycle service specialists because Deutsche Bahn and SNCF unbundling of hardware acquisition from availability contracts creates recurring revenue platforms with embedded customer switching costs. Five-to-ten year viability hinges on ERTMS migration completion rates across German and French corridors. Signal to monitor: Indian Ministry of Railways tender specifications shifting from pure capital procurement to outcome-based performance metrics, indicating contract structure convergence with European precedents.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid CBTC-ERTMS Platform Convergence | Alstom and Siemens capture procurement consolidation across previously separate urban and mainline signaling categories. |
| Captive Semiconductor Sourcing | European vendors secure automotive-grade microprocessor allocation ahead of merchant-dependent competitors facing TSMC capacity constraints. |
| Lifecycle Service Contract Unbundling | Deutsche Bahn and SNCF transfer operational risk to system integrators through 15-year availability guarantees displacing upfront capital sales. |
| Fiber-Optic Backbone Migration | JR East eliminates lightning-induced signaling failures in Shinkansen corridors through copper-to-fiber infrastructure replacement. |
| Satellite-Based Rural Signaling Deployment | ESA RailSAT initiative offers coverage alternative for Spanish and Scandinavian intercity routes where terrestrial GSM-R remains uneconomical. |
Research Approach
Direct dialogue with signaling system integrators, railway operator procurement directors, embedded firmware engineering leads, and European Railway Agency certification officers grounded qualitative findings, validated against customs trade data for fiber-optic cable and semiconductor imports, company SEC filings for R&D segmentation, ERTMS deployment databases maintained by the European Union Agency for Railways, and IEEE 1474 standardization committee records. Bottom-up and top-down triangulation cross-checked vendor shipment estimates against infrastructure provider capital expenditure disclosures.
Bottom-up modeling aggregated system-level deployments across CBTC, PTC, ATC, and electronic interlocking categories, while top-down analysis calibrated total addressable market against national rail electrification program budgets in Germany, Japan, India, and the United States. Segmentation dimensions spanned system type, transmission technology, application context from urban transit through high-speed rail, and end-user contracting authority structure. CAGRs derived from logistic diffusion curves fitted to ERTMS mandate compliance timelines and metro densification headway targets. Industry-specific inputs included European Railway Agency certification pipeline data and Indian Dedicated Freight Corridor Corporation tender award patterns.
Several conditions sit outside the modeled scope, including sovereign certification regime divergence beyond IEEE 1474 standardization progress, semiconductor foundry capacity allocation shocks, and copper price volatility effects on legacy signaling maintenance budgets. Forecasts assume continued ERTMS mandate enforcement without regulatory delay, sustained railway operator capital expenditure commitments, and stable electromagnetic compatibility standards. Practitioners should monitor European Railway Agency Level 3 deployment acceleration rates and Indian Ministry of Railways outcome-based contracting adoption for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Engine Market
Railway
Check Rails Market
Railway
Railroad Tie Market
Railway
Rail Seat Market
Railway
Railway Bearing Market
Railway
South Africa Rail Freight Transport Market
Railway
Latin America Connected Rail Market
Railway
Rail Brake Frame Market
Railway
Solar Powered Train Market
Railway
Railway Window Market
Railway
Maglev Train Market
Railway
Hydrogen Trains Market
Railway
Road-Rail Vehicles Market
Railway
Automatic Train Operation System Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Sanitary Systems for Rail Transit Market