
 India Rail Freight Transport Market | 2026-2036
India Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
India Rail Freight Transport Market Foresight
Manufacturers of cement and construction materials are redrawing India's rail freight demand map as they shift bulk cargo from highways to dedicated corridors. Container Corporation of India anchors containerized logistics through its terminal network across hinterland manufacturing clusters. Dedicated Freight Corridor Corporation of India sustains capital deployment along the Western and Eastern corridors, while Adani Logistics competes through integrated port-rail linkages at Mundra and Hazira.
India rail freight transport encompasses the movement of bulk and containerized commodities over the national railway network using wagons with axle loads up to 25 tonnes and train lengths exceeding 1.5 kilometres, serving industrial supply chains where unit cost per tonne-kilometre undercuts road alternatives by substantial margins. Coal dominates product type volumes as power utilities maintain long-term rake contracts, while food grains represent the fastest-growing product category driven by Food Corporation of India procurement decentralization. Among service types, Dedicated Freight Corridor operations concentrate the highest margin pools due to guaranteed transit slots and premium pricing for time-definite bulk delivery.
The Ministry of Railways and the Dedicated Freight Corridor Corporation operate under Railway Board directives and PM Gati Shakti National Master Plan coordination, with freight tariff policies shaped by the Railway Rates Tribunal and safety standards enforced by the Commission of Railway Safety under the Ministry of Civil Aviation. The Bureau of Indian Standards specifies wagon construction and braking system norms that determine fleet eligibility for high-speed corridor operations. Stakeholders must monitor how the proposed Indian Railways tariff rationalization and private train operator licensing framework alter competitive access to terminal infrastructure and rolling stock deployment priorities.
Market Dynamics
The Dedicated Freight Corridor network is redrawing India's logistics geography by concentrating bulk commodity flows along electrified, high-capacity routes that compress transit times between industrial belts.
Growth Catalysts
- PM Gati Shakti National Master Plan:The multimodal integration framework is accelerating corridor-based demand concentration by synchronizing rail freight with port and highway networks.
- Food Corporation of India procurement decentralization:State-level grain procurement mandates are expanding rail off-take for food grains across secondary hinterland terminals.
- Cement sector modal shift:Escalating diesel costs and axle-load restrictions on national highways are pushing construction material manufacturers toward 25-tonne axle-load wagon contracts.
Market Restraints
- Terminal access concentration:Container handling infrastructure remains concentrated at legacy junctions, creating bottlenecks for first-mile and last-mile connectivity.
- Wagon fleet heterogeneity:Mixed-age rolling stock with varying brake system specifications limits train composition flexibility and corridor speed eligibility.
- Road freight substitution elasticity:Informal trucking networks in the 300-500 kilometer range retain price advantages for non-bulk, time-flexible cargo.
Strategic Opportunities
- Private train operator licensing:The proposed framework under Railway Board directives creates white space for specialized bulk and containerized service contracts outside Indian Railways operations.
- Eastern Dedicated Freight Corridor extension:Ludhiana-Dankuni route completion opens captive mineral and steel flows from Punjab and Haryana to eastern port evacuation.
- Refrigerated container penetration:Temperature-controlled pharma and horticulture logistics remain underdeveloped relative to ambient container volumes.
Industry Challenges
- Locomotive crew specialization:High-speed freight operations above 100 kmph require certified drivers with corridor-specific signaling competency, creating recruitment friction.
- Legacy terminal digitization:Yard management systems at older goods sheds lack real-time integration with CONCOR and private logistics operator platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Rail Freight Transport Market |
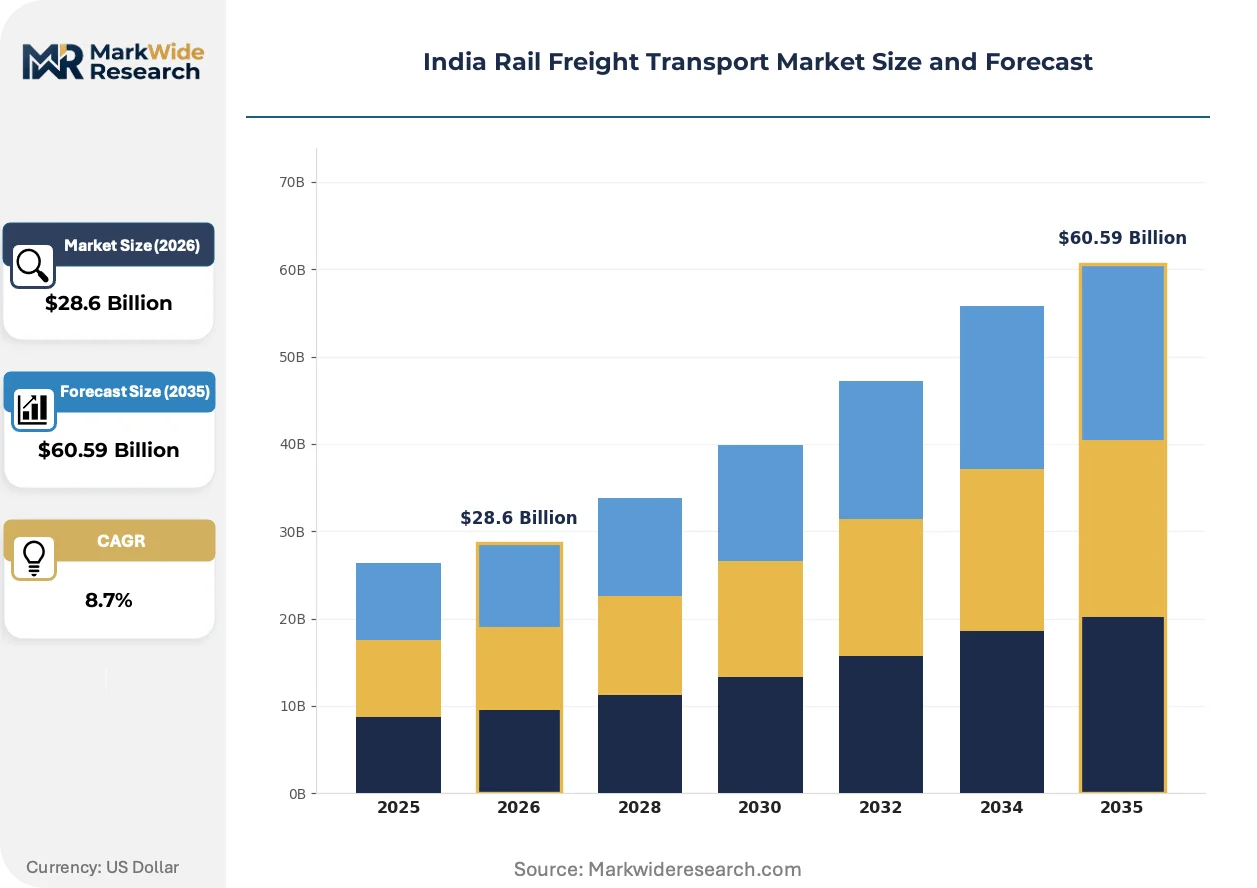
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coal, Food Grains, Iron & Steel, Cement End User: Manufacturers, Retailers, Exporters, Construction Service Type: Full Truck Load, Less than Truck Load, Intermodal, Dedicated Freight Corridor Delivery Mode: Direct Delivery, Scheduled Delivery, On-Demand Delivery, Bulk Delivery |
| Companies Covered | Indian Railway Finance Corporation Ltd. (IRFC), IRCTC, Indian Railways, TCI Express Ltd, Dedicated Freight Corridor Corporation of India (DFCCIL), Container Corporation of India (CONCOR), Rail Vikas Nigam Ltd. (RVNL), Mahindra Logistics Ltd, Adani Logistics Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Rail Freight Transport Market Shifts & Advancements
Digital freight matching and electrified traction are compressing the cost and reliability gap between rail and road logistics for time-sensitive bulk cargo.
Longer freight trains exceeding 1.5 kilometers with distributed power systems are displacing conventional single-locomotive consists on Western Dedicated Freight Corridor routes. Power utilities and steel mills are contracting these configurations for coal and iron ore evacuation. The shift is compressing per-tonne-kilometer operating costs below road parity for 500-plus kilometer hauls.
The Commission of Railway Safety under the Ministry of Civil Aviation is tightening braking system certification timelines for high-speed corridor eligibility. Wagon retrofits must comply with revised BIS specifications for pneumatic brake compatibility. Fleet operators are accelerating brake unit replacement cycles to maintain slot access on premium corridor segments.
Long-term rake contracts with annual volume commitments are displacing spot-market wagon leasing for coal and cement flows. Large thermal power generators and integrated cement manufacturers are consolidating procurement under three-to-five-year agreements. This pattern is most visible along the Delhi-Mumbai industrial corridor where fuel cost volatility has made price certainty the dominant selection criterion.
India Rail Freight Transport Market Segmentation
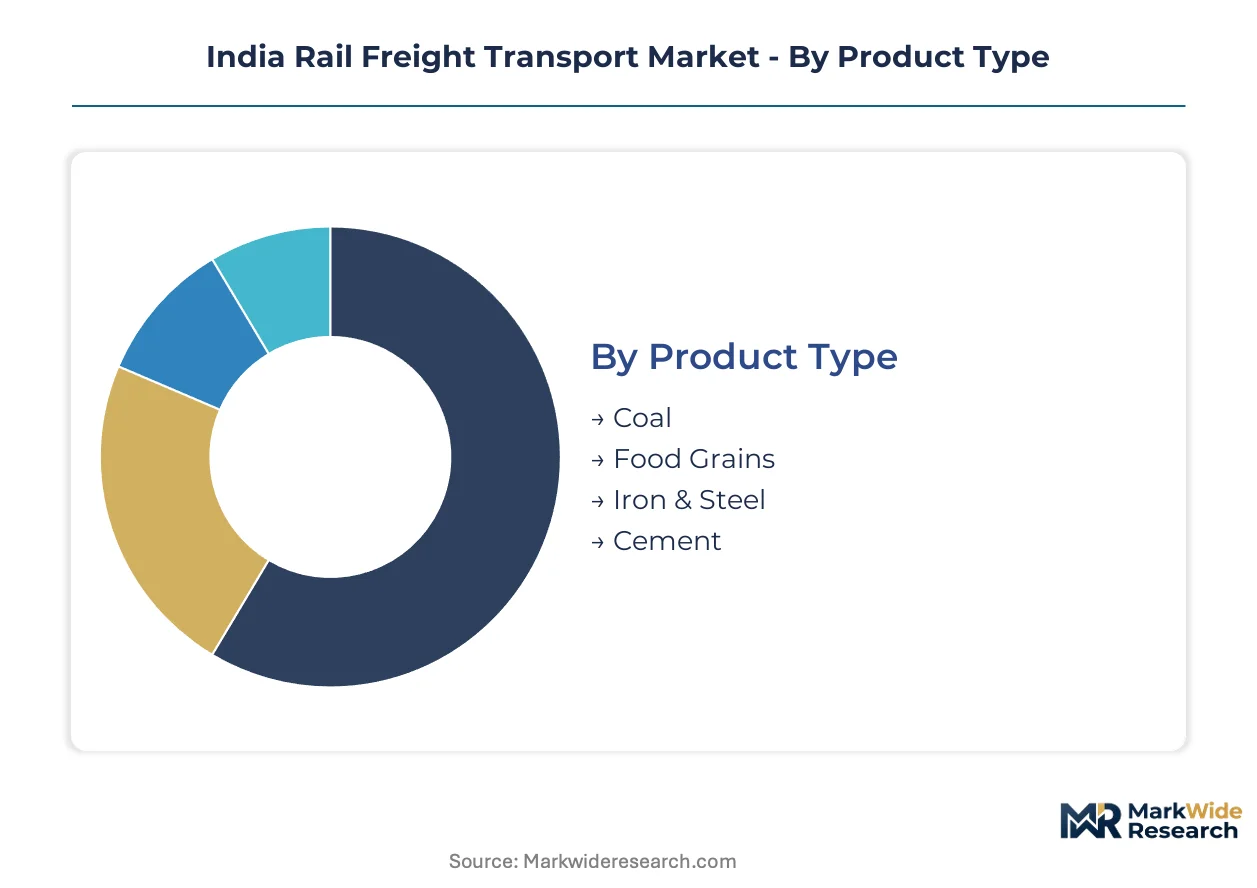
India's rail freight segmentation reflects how commodity characteristics, customer scale, and corridor infrastructure shape contract structures. Regulatory specifications from the Bureau of Indian Standards and Dedicated Freight Corridor Corporation determine which segments qualify for premium electrified routes versus legacy network access.
Product Type:
Bureau of Indian Standards axle-load classifications and wagon brake specifications segment commodity eligibility for high-speed corridor operations versus standard network constraints.
- Coal:Thermal power utilities contract dedicated rakes under long-term fuel supply agreements with 25-tonne axle-load specifications. NTPC and state gencos dominate off-take along the Eastern Dedicated Freight Corridor connecting coal fields to Punjab and Haryana power plants.
- Food Grains:Food Corporation of India procurement decentralization drives state-mandated grain movements from surplus regions to deficit states. Temperature-controlled wagon specifications under FSSAI storage norms are expanding for wheat and rice consignments.
- Iron & Steel:Integrated steel mills move finished flat products and raw material inputs through slab and coil-specific wagon configurations.
- Cement:Clinker and finished cement movements concentrate on Western Dedicated Freight Corridor routes serving Maharashtra and Gujarat construction corridors.
Established volume favors Coal; emerging adoption favors Food Grains.
End User:
Customer scale and procurement sophistication determine access to long-term rake contracts versus spot-market wagon leasing rates.
- Manufacturers:Cement and steel producers with captive siding infrastructure negotiate multi-year dedicated rake agreements. Their procurement teams coordinate directly with Railway Board freight marketing cells for corridor slot allocation.
- Construction:Project developers and ready-mix concrete suppliers aggregate bulk cement demand through terminal-based procurement, creating concentrated off-take at DFC junctions serving Delhi-Mumbai infrastructure corridors.
- Retailers:FMCG and consumer goods distributors utilize containerized services through CONCOR terminal networks for palletized cargo consolidation.
- Exporters:Containerized cargo owners access port-rail linkages at Mundra, Hazira, and JNPT for maritime connectivity.
Contract tenure distinguishes Manufacturers; shipment frequency distinguishes Construction.
Service Type:
Infrastructure access rights and locomotive priority determine service tier hierarchy and tariff structures.
- Dedicated Freight Corridor:Electrified double-stack routes with guaranteed transit slots and 100 kmph operating speeds command premium pricing. Western and Eastern corridor segments offer time-definite delivery commitments for coal, cement, and containerized flows.
- Intermodal:CONCOR-operated container trains integrate with road feeder services at inland container depots, serving manufacturing clusters without direct rail siding access.
- Full Truck Load:Block rake bookings for single-commodity movements match train capacity to shipper volume without intermediate marshalling.
- Less than Truck Load:Wagon space consolidation at goods sheds serves smaller shippers through Indian Railways parcel and smalls services.
Margin concentration sits with Dedicated Freight Corridor; volume accessibility sits with Intermodal.
Delivery Mode:
Scheduling flexibility and batch size requirements segment customer willingness to pay for certainty versus cost minimization.
- Bulk Delivery:Power utilities and steel mills accept scheduled dispatch windows in exchange for per-tonne-kilometre rates below road parity. Train-length configurations exceeding 1.5 kilometres maximize wagon utilization on dedicated corridor segments.
- Scheduled Delivery:Cement manufacturers and automotive component suppliers contract fixed-departure services with defined transit windows for inventory planning.
- Direct Delivery:Single-origin to single-destination movements bypass intermediate terminal handling for time-sensitive consignments.
- On-Demand Delivery:Spot-market wagon release accommodates demand surges and supply disruptions without long-term contract commitment.
Cost efficiency drives Bulk Delivery; reliability premiums drive Scheduled Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power utilities and cement manufacturers cluster their procurement decisions around corridor proximity, with the Western and Eastern Dedicated Freight Corridors capturing the densest buyer concentration.
Maharashtra
Thermal power plants and steel mills along the Mumbai-Pune industrial belt contract dedicated coal rakes through the Western Dedicated Freight Corridor. The state's industrial policy under the Maharashtra Industrial Development Corporation prioritizes multimodal logistics parks at DFC junctions. Manufacturing clusters in Nagpur and Aurangabad are expanding siding infrastructure for cement clinker evacuation.
Gujarat
Port-centric manufacturing at Mundra and Hazira drives containerized cargo demand for maritime connectivity. The Gujarat Maritime Board coordinates with CONCOR for hinterland container movement under PM Gati Shakti guidelines. Chemical and pharmaceutical manufacturers in Vadodara and Bharuch are shifting bulk raw material procurement from road to 25-tonne axle-load wagon contracts.
Haryana
Grain procurement decentralization by the Food Corporation of India concentrates wheat movements through Panipat and Ambala terminals. The Haryana State Industrial and Infrastructure Development Corporation is developing captive rail sidings for auto component manufacturers in Manesar. Steel rerolling mills in Bahadurgarh source iron ore via Eastern Dedicated Freight Corridor linkages.
West Bengal
Steel and mineral flows from Jharkhand terminate at Dankuni and Kolkata port facilities along the Eastern Dedicated Freight Corridor extension. The West Bengal Industrial Development Corporation is upgrading freight terminals at Kharagpur for cement distribution. Jute and tea exporters in the Kolkata metropolitan region utilize containerized services for port evacuation.
Tamil Nadu
Automotive manufacturers in Chennai and Sriperumbudur contract scheduled delivery services for component supply chains. The Tamil Nadu Industrial Development Corporation is integrating freight terminals with Ennore and Chennai port operations. Wind turbine and heavy engineering producers in Coimbatore are negotiating long-term rake agreements for steel and machinery movements.
India Rail Freight Transport Market Competitive Landscape
Player mix skews toward state-backed infrastructure operators with corridor access rights and private port-rail integrators competing on hinterland connectivity. The market structure concentrates around entities controlling terminal infrastructure and locomotive deployment priority. Two strategic archetypes dominate: corridor operators with guaranteed slot access, and containerized logistics platforms with inland depot networks. Competitive moves center on terminal capacity expansion and strategic partnerships for first-mile connectivity.
Within the state-backed infrastructure tier, Indian Railways and Dedicated Freight Corridor Corporation of India anchor corridor operations and capital deployment. Container Corporation of India occupies a position in containerized logistics through its terminal network. Adani Logistics Ltd exemplifies private port-rail integration with captive linkages at Mundra and Hazira.
| Leading Market Players |
|---|
| Indian Railway Finance Corporation Ltd. (IRFC) |
| IRCTC |
| Indian Railways |
| TCI Express Ltd |
| Dedicated Freight Corridor Corporation of India (DFCCIL) |
| Container Corporation of India (CONCOR) |
| Rail Vikas Nigam Ltd. (RVNL) |
| Mahindra Logistics Ltd |
| Adani Logistics Ltd |
| Others |
Supply & Pricing Matrix
Bureau of Indian Standards brake system certification gates both corridor slot eligibility and tariff tier access simultaneously, compressing price differentiation between legacy wagon operators and high-speed fleet holders while concentrating procurement leverage with buyers who meet axle-load specifications.
Pricing Analysis
Prior-generation pneumatic brake wagon contracts trade at substantial discounts to current-generation distributed power configurations, while next-generation autonomous train management systems command premium positioning. Three-tier pricing structure across premium corridor slots, standard network access, and economy goods shed services segments the market by transit certainty. Price differentiation hinges on BIS certification tier and volume commitment scale, with annual rake contracts securing lowest per-tonne-kilometre rates. Pricing pressure stems from diesel-road freight competition in the 300-500 kilometer band, where informal trucking networks undercut rail for non-bulk cargo. Cement manufacturers exhibit highest price sensitivity due to thin clinker margins, while power utilities with fuel pass-through mechanisms accept premium corridor tariffs for delivery certainty.
Supply Chain Analysis
Inbound logistics costs through Jawaharlal Nehru Port and Mundra Port congestion cycles feed directly into containerized rail tariff volatility, with Chennai and Visakhapatnam trade lanes offering alternative evacuation routes during peak seasons. Domestic wagon manufacturing concentrates in Maharashtra, Tamil Nadu, and West Bengal, while specialized brake system components draw from Germany, China, and Japan. Raw material dependencies span high-tensile steel for wagon bodies, copper for traction systems, and composite brake blocks for high-speed eligibility. Single-source vulnerability sits with imported pneumatic valve assemblies certified for 100 kmph operations. Distribution runs through DFCCIL corridor junctions, CONCOR inland container depots, and legacy Indian Railways goods sheds serving first-mile aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as PM Gati Shakti decentralizes procurement authority to state industrial development corporations, creating niche entry points for specialized operators outside national rail contracts.
For Market Incumbents: Compound corridor access advantages through captive siding infrastructure at DFC junctions serving Maharashtra and Gujarat cement clusters. Accelerate brake system retrofit cycles to maintain slot priority as BIS tightens certification timelines. Defensive consolidation should target terminal digitization partnerships with CONCOR to preempt private train operator licensing disruption. For New Entrants and Emerging Players: Anchor in refrigerated container logistics for pharmaceutical and horticulture verticals, where temperature-controlled wagon specifications remain underdeveloped relative to ambient volumes. Ludhiana-Dankuni Eastern Dedicated Freight Corridor extension offers penetrable white space for Punjab steel and mineral flows. Go-to-market leverage rests on direct contracts with state industrial development corporations bypassing Indian Railways freight marketing cells. For Investors and Strategic Acquirers: Private train operator licensing under Railway Board directives reshapes the acquisition landscape toward terminal-capable fleet operators with BIS-certified rolling stock. Five-to-ten year viability favors entities controlling DFC-adjacent land parcels for logistics park development. Signal to watch: DFCCIL slot allocation transparency rules determining competitive access parity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Rake Contracting | Power utilities like NTPC secure price certainty through three-to-five-year fuel supply agreements. |
| Backward Integration into Siding Infrastructure | Cement manufacturers in Gujarat and Maharashtra bypass terminal congestion through captive rail connections. |
| Refrigerated Container Fleet Expansion | Temperature-controlled pharma logistics addresses FSSAI compliance gaps in food grain movements. |
| Private Train Operator Licensing | Railway Board framework creates white space for specialized bulk services outside Indian Railways operations. |
| Terminal Digitization Partnership | Real-time yard management integration with CONCOR platforms compresses goods shed dwell times. |
Research Methodology
Cross-validation between Railway Board freight traffic circulars and DFCCIL corridor utilization reports anchors the qualitative findings across primary interviews and secondary validation. Stakeholder consultations encompassed Railway Board freight marketing directors, CONCOR terminal operations managers, cement manufacturer procurement heads, power utility fuel supply coordinators, and state industrial development corporation infrastructure planners. Secondary sources integrated Indian Railways annual statistical statements, DFCCIL project progress disclosures, BIS wagon construction standards, and PM Gati Shakti master plan documents. Bottom-up rake contracting volume analysis triangulated with top-down corridor capacity modeling.
Sensitivity analysis around diesel price volatility and road freight substitution elasticity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, end user scale, service tier infrastructure access, and delivery mode scheduling flexibility. CAGRs derived from corridor completion timelines and modal shift elasticity curves, with cement sector diesel cost pass-through and FCI procurement decentralization mandates as rail-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of Dedicated Freight Corridor electrification completion and PM Gati Shakti multimodal integration; material deviation in road fuel taxation or private operator licensing pace would warrant model refresh. Specific risk factors span locomotive crew certification bottlenecks for high-speed operations and legacy terminal digitization lag. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Horn Market
Railway
Heritage Railways Trains Market
Railway
Rail Brace Market
Railway
Train Bogie Market
Railway
Railway Bearing Market
Railway
Automatic Train Operation System Market
Railway
Global Hyperloop Train Market
Railway
Maglev Train Market
Railway
Check Rails Market
Railway
Latin America Connected Rail Market
Railway
Bullet Train Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Global Smart Locomotive Market
Railway
Railway Pantograph Market
Railway
Smart Railways Market
Railway
Railway Management System Market