
 APAC Machine Vision Systems Market | 2026-2036
APAC Machine Vision Systems Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Machine Vision Systems Market Outlook
The performance gap between high-resolution multispectral systems and basic 2D inspection setups is realigning procurement priorities across APAC factory floors. Keyence Corporation leverages its direct sales force to dominate Japan's precision electronics sector. Cognex Corporation sustains technology leadership through deep learning-enabled vision tools for complex assembly verification. Basler AG anchors European-origin quality standards while competing aggressively on camera modularity for Chinese system integrators.
APAC machine vision systems integrate cameras, optics, processors, and software algorithms to capture, analyze, and interpret visual information for automated industrial decision-making, typically operating at frame rates exceeding 100 fps with pixel resolutions ranging from 1 to 25 megapixels depending on inspection granularity. These systems perform quality control, dimensional measurement, and robotic guidance tasks that exceed human visual consistency in high-throughput manufacturing environments. Smart cameras capture the largest installed base due to their standalone processing capability, though deep learning technology expands fastest as semiconductor fabs and battery plants demand adaptive defect classification. Vision software commands premium margins where manufacturers require customizable analytics pipelines across multi-site deployments.
China's MIIT mandates smart manufacturing certification for state-supported industrial zones, while Japan's METI promotes JIS-compliant vision integration through productivity subsidies. South Korea's MFDS and KOSHA frameworks impose equipment safety standards that filter non-compliant imports from Southeast Asian channels. Stakeholders must monitor diverging national certification requirements as regional supply chains localize camera sourcing and software development.
Market Dynamics
Deep learning inference at the edge is compressing inspection cycle times across APAC semiconductor fabs, forcing incumbent hardware architectures toward GPU-accelerated smart camera designs.
Growth Catalysts
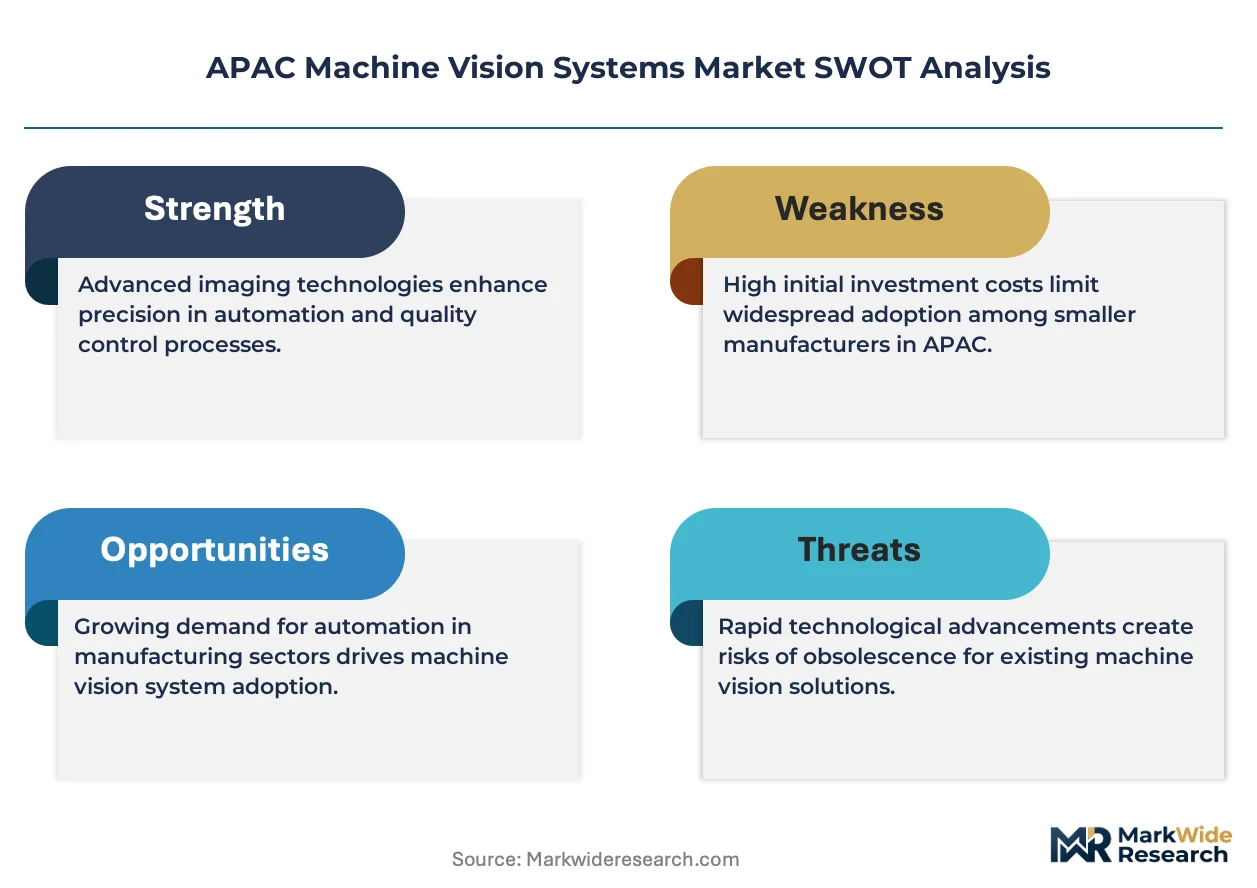
- MIIT Smart Manufacturing Certification:China's state-supported industrial zones mandate vision-enabled quality systems for facility accreditation, pulling adoption through Yangtze River Delta battery and chip plants.
- Semiconductor yield optimization:Defect classification algorithms trained on wafer-level imagery reduce scrap rates in South Korean and Taiwanese foundries below human inspection thresholds.
- EV battery inspection:Electrode coating uniformity checks and cell stacking verification create dedicated machine vision demand at gigafactory scale across the region.
Market Restraints
- Specialized lens supply concentration:High-resolution telecentric optics for sub-micron measurement rely on Japanese and German source bases, exposing integrators to 12-16 week lead time volatility.
- Deep learning training data scarcity:Rare defect categories in specialty glass and ceramic substrates require 10,000+ annotated samples that many mid-tier manufacturers cannot generate internally.
- MFDS equipment safety compliance:South Korea's certification framework filters non-compliant vision hardware from Southeast Asian distribution channels, constraining low-cost import routes.
Strategic Opportunities
- Vietnam electronics assembly expansion:Contract manufacturers relocating from China seek turnkey vision solutions for smartphone and wearable quality gates.
- Hyperspectral imaging convergence:Combining spectral analysis with spatial measurement enables non-destructive food and pharmaceutical inspection previously requiring lab sampling.
- METI productivity subsidies:Japan's incentive programs for Industry 4.0 equipment upgrades reduce payback periods for mid-sized precision component suppliers.
Industry Challenges
- Vision system integration engineering shortage:Deployment of multi-camera synchronized architectures for large-format battery module inspection outpaces trained application engineering availability.
- JIS certification timeline compression:Japanese automotive tier-1 suppliers demand six-month validation cycles for vision-guided robotic welding that strain software release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Machine Vision Systems Market |
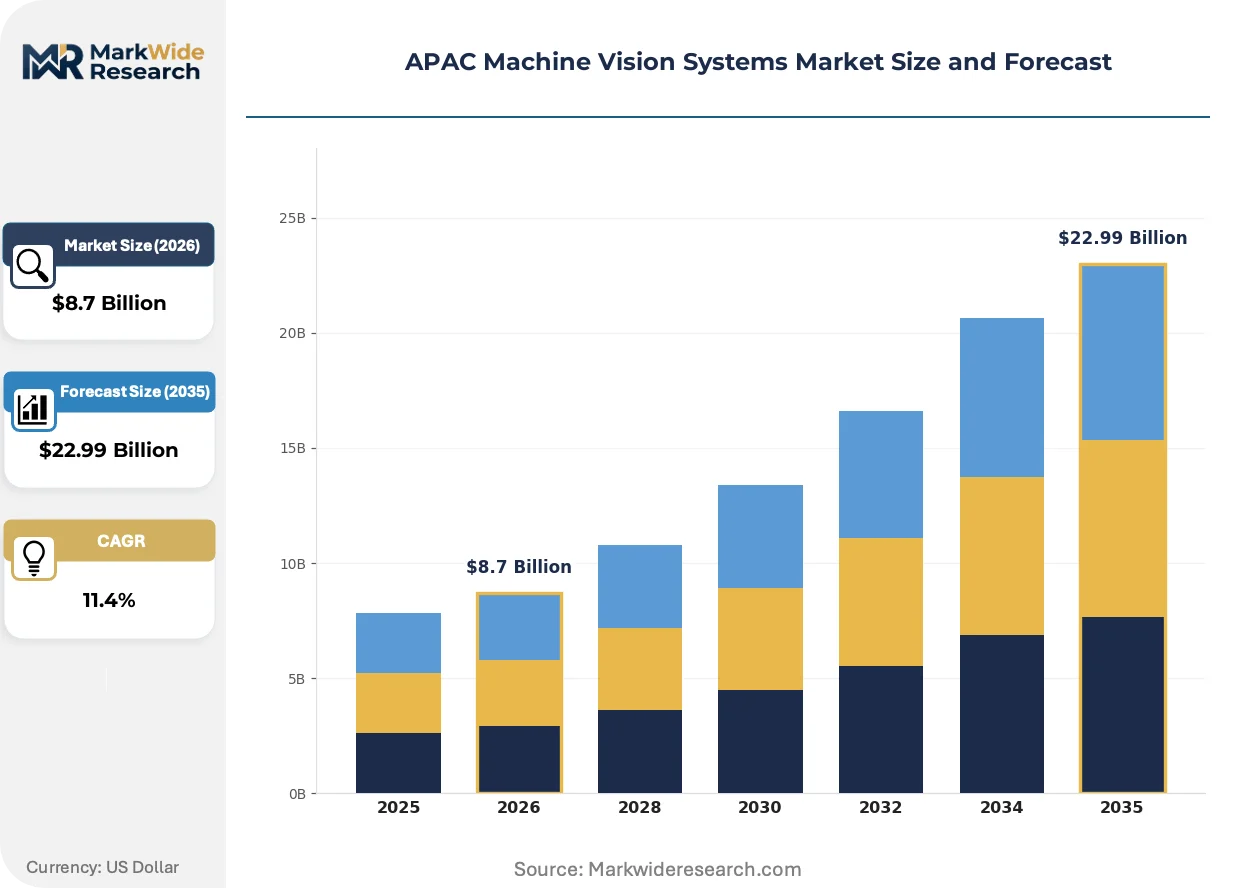
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Cameras, Frame Grabbers, Vision Software, Lighting Equipment Technology: 2D Vision, 3D Vision, Embedded Vision, Deep Learning Application: Quality Assurance, Robot Guidance, Identification, Measurement End User: Manufacturing, Automotive, Food & Beverage, Electronics |
| Companies Covered | Basler AG, Teledyne DALSA, Cognex Corporation, Datalogic SpA, IDS Imaging Development Systems GmbH, Keyence Corporation, National Instruments Corporation, Perceptron Inc, Omron Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Machine Vision Systems Market Strategic Shifts
Edge AI silicon and adaptive optics are collapsing the traditional separation between image acquisition and real-time decision-making across APAC production lines.
Embedded GPU architectures in smart cameras are modularizing inspection system design. Semiconductor fabs in Taiwan and South Korea deploy these units for inline defect classification without external PC controllers. The technology is modularizing system integrator business models toward software-centric recurring revenue.
METI's JIS-compliant vision integration guidelines and productivity subsidies are accelerating standardized data interfaces across Japanese automotive and electronics supply chains. Equipment vendors must now support OPC-UA and MQTT protocols to qualify for incentive programs. Precision component manufacturers in Nagoya and Osaka industrial corridors are prioritizing certified platforms to secure subsidy eligibility.
System procurement through direct factory engineering relationships is displacing traditional distributor channels for complex installations. Chinese EV battery producers in the Yangtze River Delta negotiate directly with camera and software vendors for multi-site deployment frameworks. This pattern concentrates in high-capex verticals where technical validation precedes commercial negotiation.
APAC Machine Vision Systems Market Segmentation
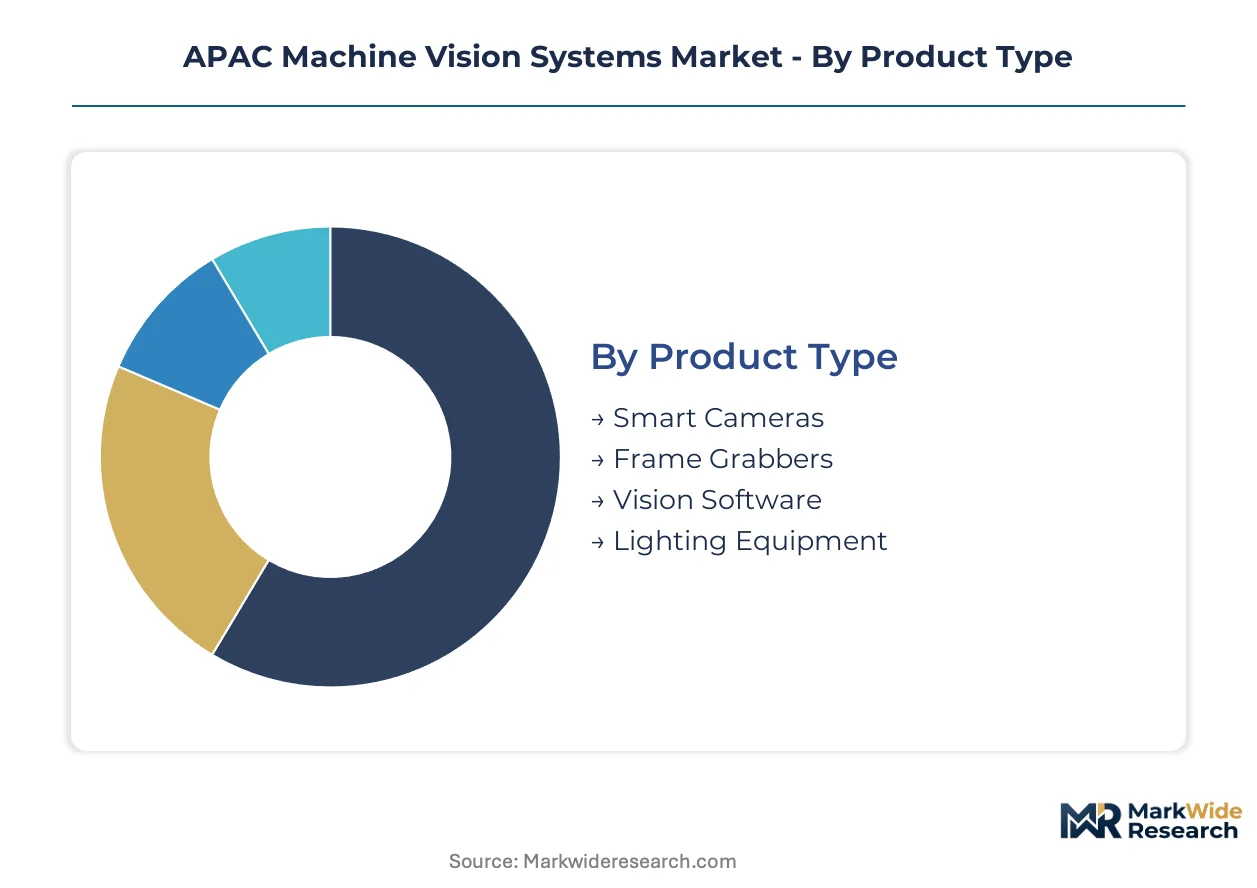
Machine vision procurement across APAC factory floors diverges sharply by technical maturity, integration complexity, and regulatory compliance burden. Buyers prioritize standalone processing capability in high-volume electronics lines while demanding adaptive software layers for semiconductor yield optimization.
Product Type:
Procurement budgets concentrate where processing latency determines throughput economics in battery and chip fabrication.
- Smart Cameras:Embedded processors eliminate external PC dependencies, enabling standalone defect classification at frame rates exceeding 100 fps. South Korean semiconductor fabs deploy these units for inline wafer inspection where space constraints and vibration tolerance matter.
- Vision Software:Customizable analytics pipelines command premium margins across multi-site deployments in China's Yangtze River Delta. Deep learning model training and spectral analysis tools drive recurring revenue models for system integrators serving EV battery producers.
- Frame Grabbers:High-bandwidth data acquisition cards bridge industrial cameras to host PCs in large-format inspection architectures.
- Lighting Equipment:Structured LED arrays and telecentric illuminators stabilize image consistency for sub-micron measurement tasks.
Smart cameras lead on scale; vision software leads on momentum.
Technology:
Inspection granularity requirements separate legacy 2D deployments from next-generation adaptive systems in precision manufacturing.
- Deep Learning:Neural network inference at the edge compresses classification cycle times for rare defect categories in specialty glass and ceramic substrates. Taiwanese foundries train models on 10,000+ annotated wafer images to reduce scrap below human inspection thresholds.
- 2D Vision:Established planar imaging dominates high-throughput electronics assembly where cost sensitivity and proven reliability outweigh dimensional complexity.
- 3D Vision:Stereoscopic and time-of-flight methods enable volumetric measurement for robotic bin-picking and assembly verification.
- Embedded Vision:System-on-chip integration targets power-constrained wearable and mobile device inspection stations.
2D vision retains installed base dominance; deep learning gains share fastest.
Application:
Return-on-investment timelines vary dramatically by task complexity and labor substitution potential.
- Quality Assurance:Automated defect detection replaces manual inspection in smartphone and wearable production lines relocating to Vietnam. Contract manufacturers demand turnkey solutions with sub-50-millisecond cycle times.
- Robot Guidance:Vision-guided welding and assembly systems face compressed validation cycles from Japanese automotive tier-1 suppliers demanding six-month JIS certification timelines.
- Identification:OCR and barcode reading streamline logistics and traceability in pharmaceutical packaging operations.
- Measurement:Sub-micron dimensional verification supports precision component manufacturing in Nagoya and Osaka industrial corridors.
Quality assurance leads on scale; robot guidance leads on momentum.
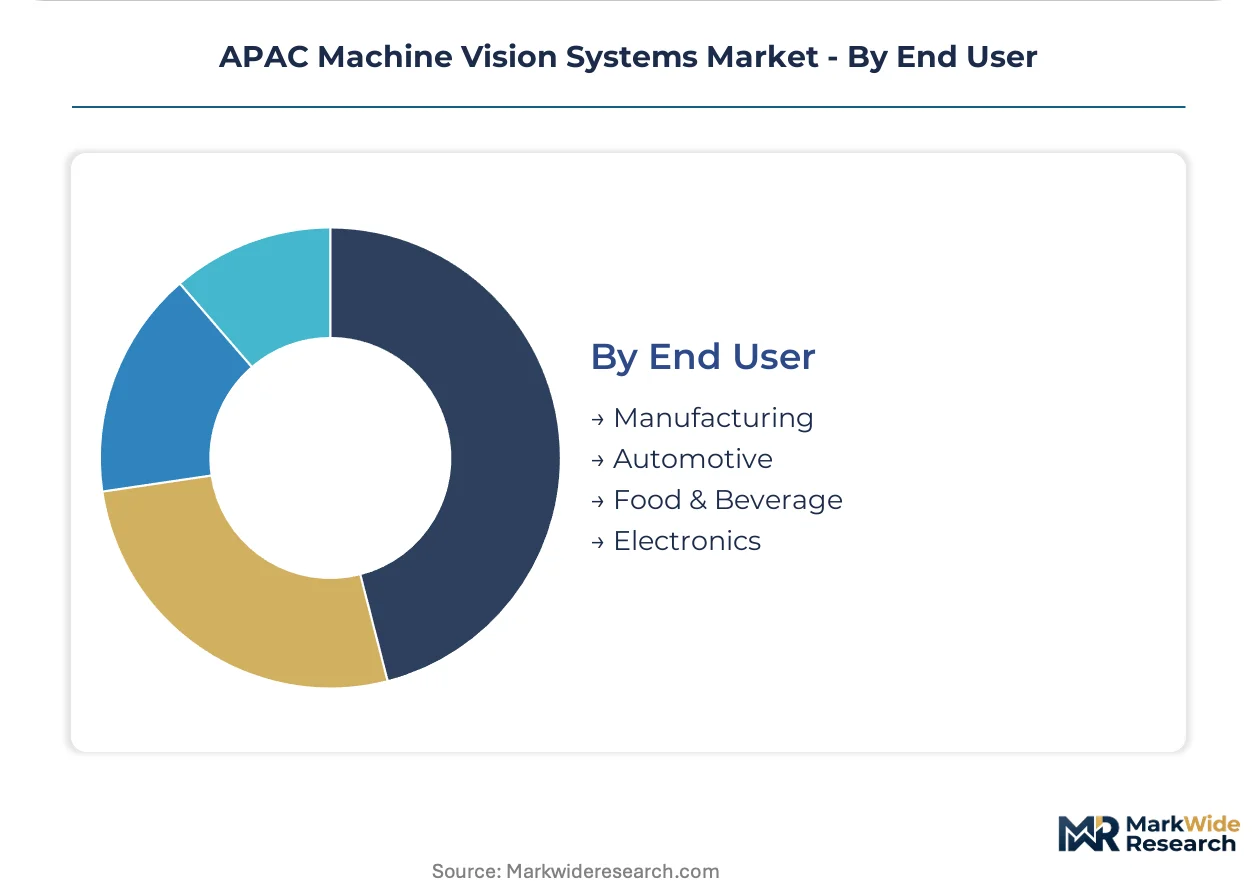
End User:
Capital expenditure intensity and regulatory exposure shape vertical-specific procurement patterns.
- Electronics:Miniaturization trends and assembly density drive the highest camera resolution requirements, with 25-megapixel systems standard for PCB inspection. South Korean and Taiwanese manufacturing lines expand deployment for defect detection as production scales.
- Automotive:METI productivity subsidies reduce payback periods for mid-sized precision component suppliers integrating vision-guided welding and battery module assembly verification.
- Manufacturing:General industrial automation spans metal fabrication, plastics, and packaging with moderate technical complexity.
- Food & Beverage:Hyperspectral imaging enables non-destructive quality assessment previously requiring laboratory sampling.
Electronics leads on scale; automotive leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Application engineers cluster in Taiwan's Hsinchu Science Park and South Korea's Pangyo Techno Valley, anchoring the region's machine vision deployment capacity. These talent pools support semiconductor fabs and battery plants across the Asia-Pacific.
China
MIIT smart manufacturing certification mandates vision-enabled quality systems for state-supported industrial zones. The Yangtze River Delta factory clusters concentrate semiconductor and EV battery producers operating at gigafactory scale. Direct procurement negotiations between battery producers and camera vendors are displacing traditional distributor channels.
Japan
METI productivity subsidies reduce payback periods for mid-sized precision component suppliers upgrading to Industry 4.0 equipment. JIS-compliant vision integration guidelines standardize data interfaces across automotive and electronics supply chains. Nagoya and Osaka industrial corridors prioritize certified platforms to secure subsidy eligibility.
South Korea
Semiconductor yield optimization drives defect classification algorithms trained on wafer-level imagery in foundries. MFDS and KOSHA frameworks impose equipment safety standards that filter non-compliant imports from Southeast Asian channels. Pangyo Techno Valley hosts system integrators serving Samsung and SK Hynix fabrication facilities.
Taiwan
TSMC and United Microelectronics Corporation expand machine vision deployment for sub-micron measurement tasks. The national semiconductor regulator enforces equipment qualification protocols for advanced packaging lines. Hsinchu Science Park concentrates the highest density of vision application engineers in the region.
Vietnam
Contract manufacturers relocating from China seek turnkey vision solutions for smartphone and wearable quality gates. The country's industrial zone authority streamlines equipment import procedures for electronics investors. Bac Ninh and Bac Giang provinces host Foxconn and Luxshare facilities deploying automated defect detection.
APAC Machine Vision Systems Market Competitive Environment
Top-tier vendors anchor premium-tier smart camera and deep learning software segments, while mid-tier specialists compete on modularity and price. The market structure reflects consolidation among Japanese and European-origin firms with direct sales capabilities, alongside fragmentation among Chinese system integrators. Three archetypes dominate: full-stack platform providers, component specialists, and software-centric analytics vendors. Competitive moves center on strategic partnerships with semiconductor equipment makers and capacity expansion in Yangtze River Delta service centers.
Within the full-stack platform tier, Keyence Corporation and Cognex Corporation exemplify contrasting geographic strengths. Keyence's direct sales force dominates Japan's precision electronics sector through proximity to METI-subsidized upgrade cycles. Cognex sustains technology leadership in deep learning-enabled vision tools for complex assembly verification across Taiwanese foundries. Basler AG anchors European-origin quality standards while competing aggressively on camera modularity for Chinese system integrators serving EV battery producers.
| Leading Market Players |
|---|
| Basler AG |
| Teledyne DALSA |
| Cognex Corporation |
| Datalogic SpA |
| IDS Imaging Development Systems GmbH |
| Keyence Corporation |
| National Instruments Corporation |
| Perceptron Inc |
| Omron Corporation |
| Others |
Value Chain & Pricing Dynamics
GPU-accelerated smart camera architectures are collapsing the traditional separation between image acquisition and processing hardware, simultaneously compressing system costs and concentrating procurement leverage among semiconductor fabs in Taiwan and South Korea. This convergence forces tier-2 integrators in China's Yangtze River Delta to choose between premium embedded platforms and modular component sourcing strategies.
Pricing Analysis
Software-hardware bundling splits procurement economics across the APAC machine vision market. Premium smart camera vendors command three-tier pricing structure across premium, standard, and economy levels based on inference acceleration capability and MIIT certification status. Price differentiation hinges on JIS compliance tier and after-sales calibration service inclusion. Cost compression in economy-tier 2D inspection systems intensifies as Chinese domestic camera producers expand modularity offerings. Contract manufacturers in Vietnam exhibit highest price sensitivity due to turnkey solution requirements, while Japanese precision component suppliers prioritize certification-grade platforms regardless of premium positioning.
Supply Chain Analysis
Reverse logistics flows for refurbished smart cameras and recertified frame grabbers remain underdeveloped across APAC machine vision channels, creating aftermarket service gaps that European-origin vendors exploit for recurring revenue. Optical component supply concentrates in Germany and Japan, with telecentric lens production anchored in specialized precision manufacturing clusters. Image sensor fabrication draws from Taiwan and South Korea foundry capacity. Single-source vulnerability in high-resolution telecentric optics exposes integrators to lead time volatility when Japanese suppliers prioritize domestic automotive tier-1 contracts. Distribution runs through direct factory engineering relationships in high-capex verticals, while mid-tier electronics assemblers rely on regional system integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC machine vision deployment functions as a geographic-arbitrage play where Vietnam's electronics assembly expansion absorbs cost-sensitive procurement that China's MIIT-mandated certification requirements have priced out of Yangtze River Delta facilities.
For Market Incumbents: Acquire edge-AI software competency to defend against GPU-native smart camera entrants eroding traditional hardware margins. Deepen backward integration into image sensor supply through foundry partnerships in Taiwan and South Korea. Prioritize METI subsidy qualification pathways to lock in Japanese automotive tier-1 validation cycles before JIS timeline compression accelerates. For New Entrants and Emerging Players: Mid-tier Vietnamese contract manufacturers represent the most penetrable buyer archetype seeking turnkey defect detection without deep integration engineering. Target white-space in hyperspectral food inspection applications where European-origin vendors dominate pricing. Pursue direct sales relationships with EV battery producers in China's Yangtze River Delta bypassing traditional distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among software-centric analytics vendors lacking hardware manufacturing assets but commanding recurring revenue from deep learning model training services. Long-term viability across the analysis window favors platform providers with dual capability in smart camera production and customizable vision software. Monitor MFDS certification timeline acceleration as the inflection signal for Korean market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Partnership | GPU-accelerated smart camera designs compress inspection cycle times for TSMC and Samsung foundries. |
| MIIT Certification Investment | Smart manufacturing accreditation unlocks state-supported industrial zone procurement in Yangtze River Delta clusters. |
| Vietnam Service Center Expansion | Proximity to Foxconn and Luxshare facilities reduces deployment engineering lead times for smartphone quality gates. |
| Hyperspectral Imaging Acquisition | Spectral-spatial convergence enables non-destructive pharmaceutical inspection previously requiring laboratory sampling. |
| JIS-Compliant Platform Development | Standardized OPC-UA and MQTT interfaces secure METI productivity subsidy eligibility for Nagoya precision suppliers. |
Study Parameters
Coverage spans China, Japan, South Korea, Taiwan, and Vietnam, with primary inputs from each market cluster combined with secondary validation. Interviews with semiconductor fab equipment engineers, automotive tier-1 procurement leads, EV battery plant managers, vision system integrators, and METI/MIIT regulatory officials anchored demand-side intelligence. Secondary sources include MIIT smart manufacturing certification databases, METI subsidy disbursement records, JIS standards documentation, MFDS equipment safety filings, and semiconductor equipment trade flow data. Bottom-up unit economics triangulate against top-down industrial automation capex forecasts.
Granularity-level modeling extends to product type, technology architecture, application task, and end-user vertical with country-level resolution for China, Japan, South Korea, Taiwan, and Vietnam. Deployment model splits between standalone smart camera systems and PC-based multi-camera architectures inform hardware revenue allocation. Deep learning adoption curves, MIIT certification penetration rates, and METI subsidy uptake patterns feed growth trajectory assumptions across the projection horizon. CAGRs derive from segment-specific adoption S-curves adjusted for regulatory mandate timing and industrial zone investment cycles.
Underlying measurement precision varies by segment; smart camera unit shipments carry tighter precision than vision software revenue attribution where bundling obscures standalone pricing. Forecasts reflect assumptions regarding MIIT certification timeline enforcement, METI subsidy continuity, and semiconductor capital expenditure cycles. Practitioners should monitor MFDS equipment safety framework expansion and JIS validation cycle compression for early signals of market access restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Intercom Devices Market
Others
Asia Pacific Contract Packaging Market
Others
Electric Chainsaw Market
Others
5G Tester Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Asia-Pacific Medical Simulation Market
Others
Operator Training Simulator Market
Others
Crystal Growth Equipment Market
Others
Middle East 3D Printing Construction Market
Others
Global Pumpkin Candles Market
Others
Edge Computing in Healthcare Market
Others
Radiation Detection Monitoring and Safety Market
Others
TWS Micro-Battery Market
Others
Inflight Entertainment Solutions Market
Others
Griffin Beaker Market
Others
Pin Mills Market