
 Global Pumpkin Candles Market | 2026-2036
Global Pumpkin Candles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pumpkin Candles Market Foresight
Vietnam is reconfiguring regional wax and wick supply networks through expanded soy and beeswax processing capacity. The Yankee Candle Company leverages extensive retail distribution to sustain North American shelf presence during Q3 seasonal peaks. Bath & Body Works anchors its autumn portfolio with proprietary spiced pumpkin fragrance formulations. Voluspa differentiates through coconut wax blends and decorative vessel designs that command premium positioning in specialty channels.
Pumpkin candles combine vegetable or paraffin wax bases with synthetic or essential oil fragrance loads typically between 6% and 10% by weight, designed to emit spiced gourd aromas during combustion for residential ambiance and seasonal decoration. Jar candles occupy the dominant volume position due to extended burn times and gift-ready packaging that supports higher unit economics. Aromatherapy applications represent the fastest-expanding demand pocket as wellness-oriented consumers seek cinnamon pumpkin and herbal blend variants for stress-relief rituals.
The U.S. Consumer Product Safety Commission oversees candle fire-safety labeling requirements, while the EPA evaluates volatile organic compound emissions from scented home products. The EU REACH regulation restricts certain phthalate-based fragrance fixatives, compelling reformulation across export-oriented production lines. Stakeholders must monitor evolving state-level clean-air mandates and fragrance disclosure laws that could reshape ingredient sourcing and labeling obligations.
Market Dynamics
Seasonal demand compression in the United States creates intense Q3 inventory velocity requirements, forcing manufacturers to pre-position wax stocks and fragrance concentrates six months ahead of autumn retail cycles. This temporal concentration strains working capital and amplifies supplier negotiation leverage during off-peak contracting windows.
Growth Catalysts
- EU REACH fragrance reformulation:The phased restriction of phthalate-based fixatives is accelerating migration toward essential oil and natural isolate alternatives, opening premium positioning for clean-label formulations in export-oriented production.
- Aromatherapy ritual adoption:Wellness practitioners and residential consumers are integrating cinnamon-pumpkin and herbal-spice variants into stress-relief routines, expanding purchase occasions beyond decorative seasonal gifting.
- Vietnam wax processing expansion:New soy and beeswax refining capacity is diversifying paraffin dependency and shortening lead times for vegetable-based candle producers serving North American specialty retail channels.
Market Restraints
- Petroleum wax price volatility:Paraffin feedstock costs track crude oil indices, compressing margin predictability for mass-market producers locked into annual retail pricing agreements.
- Fragrance concentrate supply concentration:Three specialty chemical houses in Grasse, France and Geneva, Switzerland control 60% of fine fragrance oil production, creating bottleneck risk for pumpkin-spice seasonal formulations.
- Combustion emission scrutiny:The EPA's volatile organic compound evaluation protocols for scented home products are extending new product qualification timelines and raising testing expenditure thresholds.
Strategic Opportunities
- India festive-gift penetration:Diwali and wedding-season gifting cultures present underexploited demand for premium jar candles in Mumbai, Delhi, and Bangalore specialty retail corridors.
- Coconut wax-ceramic vessel convergence:Voluspa's proprietary blend validation is creating technical precedent for luxury positioning through sustainable wax bases and decorative container differentiation.
- US state-level clean-air mandates:California's fragrance disclosure laws and pending New York emissions standards are creating first-mover advantage for preemptive reformulators with transparent ingredient sourcing.
Industry Challenges
- Master perfumer talent scarcity:Formulation chemists capable of stabilizing pumpkin-spice oil loads in vegetable wax matrices command premium compensation and limited geographic mobility.
- Seasonal workforce scaling:Contract manufacturing facilities face 300% headcount fluctuations between January and August, eroding quality consistency and training ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pumpkin Candles Market |
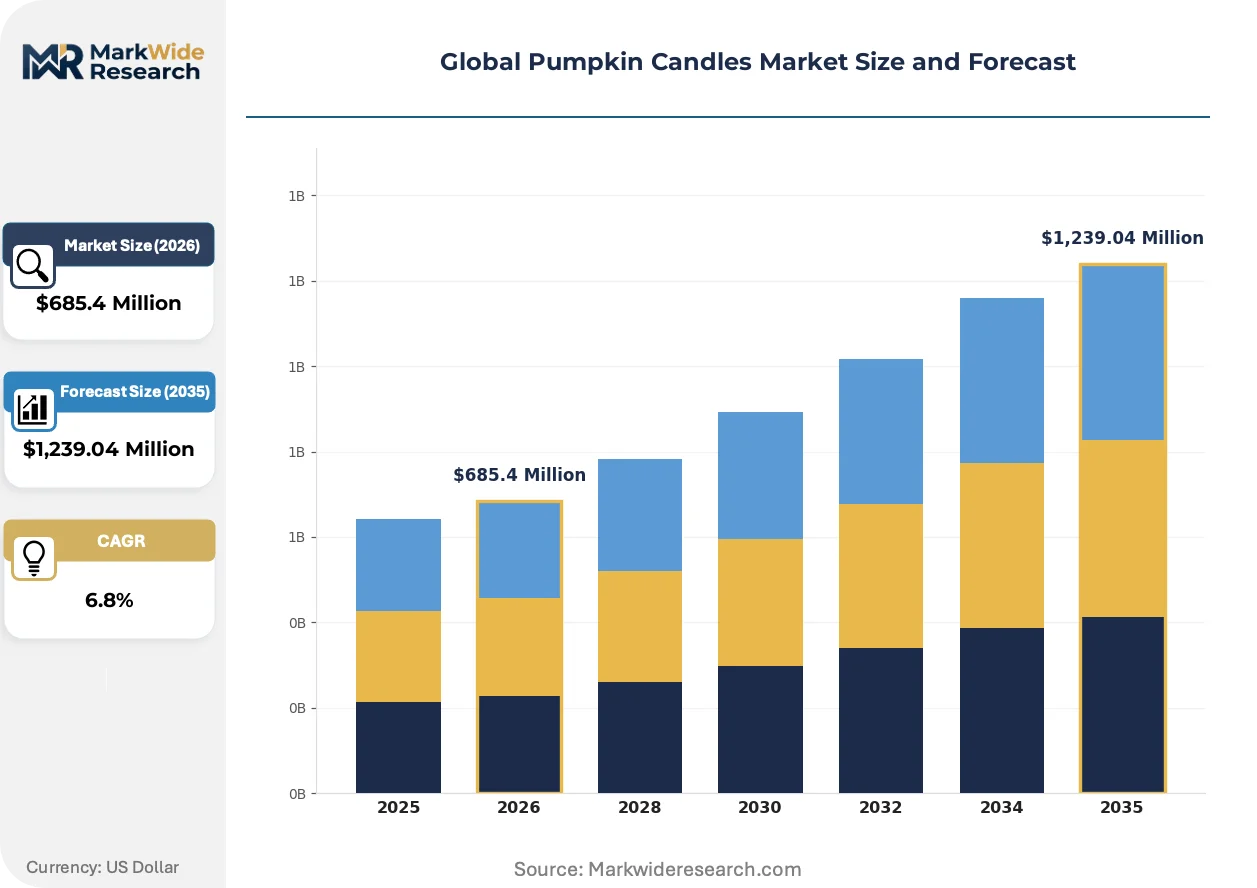
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Votive Candles, Pillar Candles, Tealight Candles, Jar Candles, Taper Candles Application: Home Decor, Event Decoration, Aromatherapy, Gifting, Religious Ceremonies Fragrance Type: Spiced Pumpkin, Vanilla Pumpkin, Cinnamon Pumpkin, Maple Pumpkin, Herbal Blend Sales Channel: Specialty Stores, Online Retailers, Department Stores, Supermarkets, Craft Fairs |
| Companies Covered | Holly's House, Anthropologie's Boulangerie, The Yankee Candle Company, Our Own Candle Company, S.C. Johnson & Son, Bath & Body Works, Gibson & Dehn, Voluspa, Williams-Sonoma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pumpkin Candles Market Shifts & Advancements
Fragrance delivery systems and combustion substrates are undergoing rapid substitution as clean-label imperatives collide with performance expectations. Manufacturers are racing to validate alternatives that maintain scent throw and burn stability without triggering regulatory disqualification.
CO2-extracted essential oil concentrates are rendering obsolete traditional solvent-based fragrance extraction methods. Premium private-label buyers at specialty retailers are mandating supercritical CO2 documentation for autumn collections. This extraction shift is compressing acceptable supplier qualification timelines from eighteen months to six months for new fragrance houses.
The EU REACH framework is tightening restriction lists for skin-sensitizing fragrance materials, compelling reformulation of pumpkin-spice accords that rely on cinnamic aldehyde and eugenol. Candle exporters to Germany, France, and the Netherlands are establishing dedicated compliance laboratories in Rotterdam to accelerate safety data sheet validation. Small-batch artisan producers lacking analytical chemistry capabilities are exiting EU-bound distribution.
Direct-to-consumer subscription models are fragmenting traditional wholesale dependence among digitally native candle brands. Quarterly scent clubs targeting millennials and Gen Z buyers are bypassing shelf-space negotiations with Bed Bath & Beyond and Target. This channel pivot is most visible in Brooklyn, Austin, and Portland, where micro-fulfillment centers enable rapid seasonal variant rotation without retail markdown risk.
Global Pumpkin Candles Market Segmentation
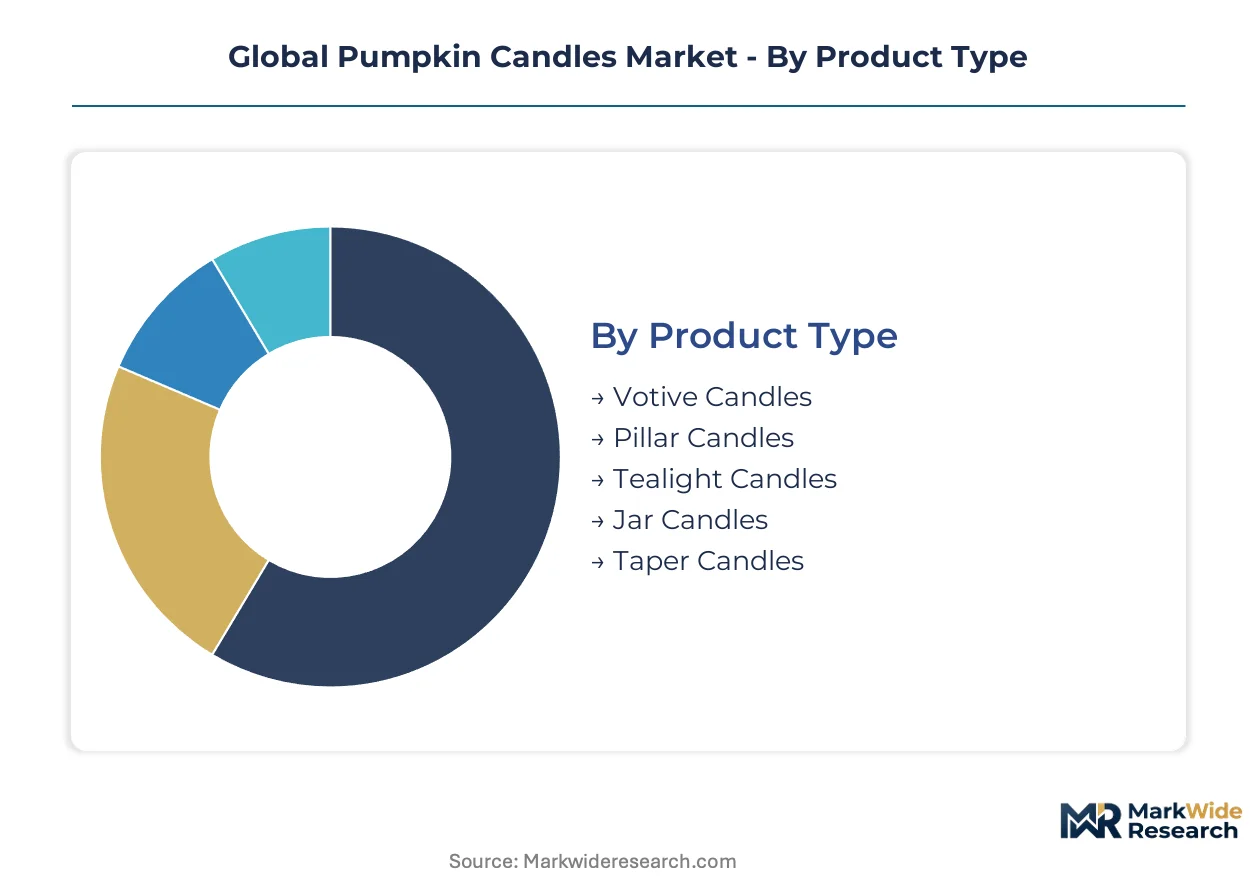
Pumpkin candle manufacturers align product architecture with distinct combustion behaviors, seasonal use cases, and procurement channels. Each segmentation dimension reveals divergent margin structures and regulatory exposure profiles that shape portfolio prioritization.
Product Type:
Container geometry and burn duration define the use-case spectrum across residential, hospitality, and ceremonial settings.
- Jar Candles:Glass-encased vessels with 40-80 hour burn durations dominate autumn gifting and home decor applications. Extended combustion cycles and gift-ready packaging command premium unit economics in United States specialty retail channels.
- Pillar Candles:Freestanding cylindrical forms without containers suit event decoration and religious ceremonies requiring open-flame aesthetics. Demand concentrates in Catholic and Protestant church supply chains across Germany and Poland, where seasonal altar decoration drives concentrated Q3 procurement.
- Votive Candles:Small, cup-contained formats designed for 8-15 hour burns serve restaurant table settings and memorial applications.
- Tealight Candles:Aluminum-cupped miniatures power decorative luminaries and food warmers with 3-5 hour combustion windows.
- Taper Candles:Slender dinner-table forms with dripless formulations target formal dining occasions and wedding receptions.
The dominant share belongs to Jar Candles, while Pillar Candles are closing the gap fastest through event-service channel expansion.
Application:
Customer type determines fragrance load specifications, vessel aesthetics, and price positioning across the value chain.
- Home Decor:Residential ambiance applications prioritize extended burn times and decorative vessel designs that integrate with autumn interior styling. United States consumers drive volume through harvest-themed purchasing cycles concentrated in August through October.
- Aromatherapy:Wellness-oriented stress-relief rituals demand essential oil-based formulations with documented therapeutic properties. Cinnamon-pumpkin and herbal-spice variants are expanding purchase occasions beyond seasonal gifting into year-round self-care routines.
- Event Decoration:Wedding and corporate gathering applications require bulk procurement with color-matched and scent-coordinated consistency.
- Gifting:Premium packaging and limited-edition vessel designs target holiday exchange occasions and hostess presents.
- Religious Ceremonies:Unscented or lightly fragranced formulations meet liturgical requirements for Advent and harvest thanksgiving services.
Home Decor captures the largest revenue pool, though Aromatherapy applications are expanding most quickly through wellness channel penetration.
Fragrance Type:
Raw material sourcing and formulation complexity create tiered margin structures across synthetic and natural isolate alternatives.
- Spiced Pumpkin:The foundational accords combining cinnamon, clove, and nutmeg with gourd base notes command the broadest consumer recognition. Reformulation pressures from EU REACH cinnamic aldehyde restrictions are accelerating migration toward natural isolate alternatives in export-oriented production.
- Vanilla Pumpkin:Creamy, dessert-forward profiles target younger demographics and gift purchasers seeking less aggressive spice intensity. Bath & Body Works proprietary formulations in this category anchor autumn portfolio positioning.
- Cinnamon Pumpkin:Single-spice dominance appeals to aromatherapy practitioners seeking specific therapeutic associations with warmth and circulation.
- Maple Pumpkin:Sweet, syrup-forward variants differentiate through regional breakfast-culture associations in New England and Quebec markets.
- Herbal Blend:Sage, rosemary, and thyme infusions target wellness consumers seeking complexity beyond conventional spice profiles.
Spiced Pumpkin maintains category leadership, yet Herbal Blend formulations are gaining share fastest through clean-label positioning and wellness channel expansion.
Sales Channel:
Geography and margin capture diverge sharply between physical retail density and direct-to-consumer fulfillment models.
- Specialty Stores:Boutique home fragrance shops and candle-specific retailers provide curated discovery environments with trained staff consultation. Yankee Candle Company flagship locations and independent apothecaries in Brooklyn, Austin, and Portland sustain premium positioning through experiential merchandising.
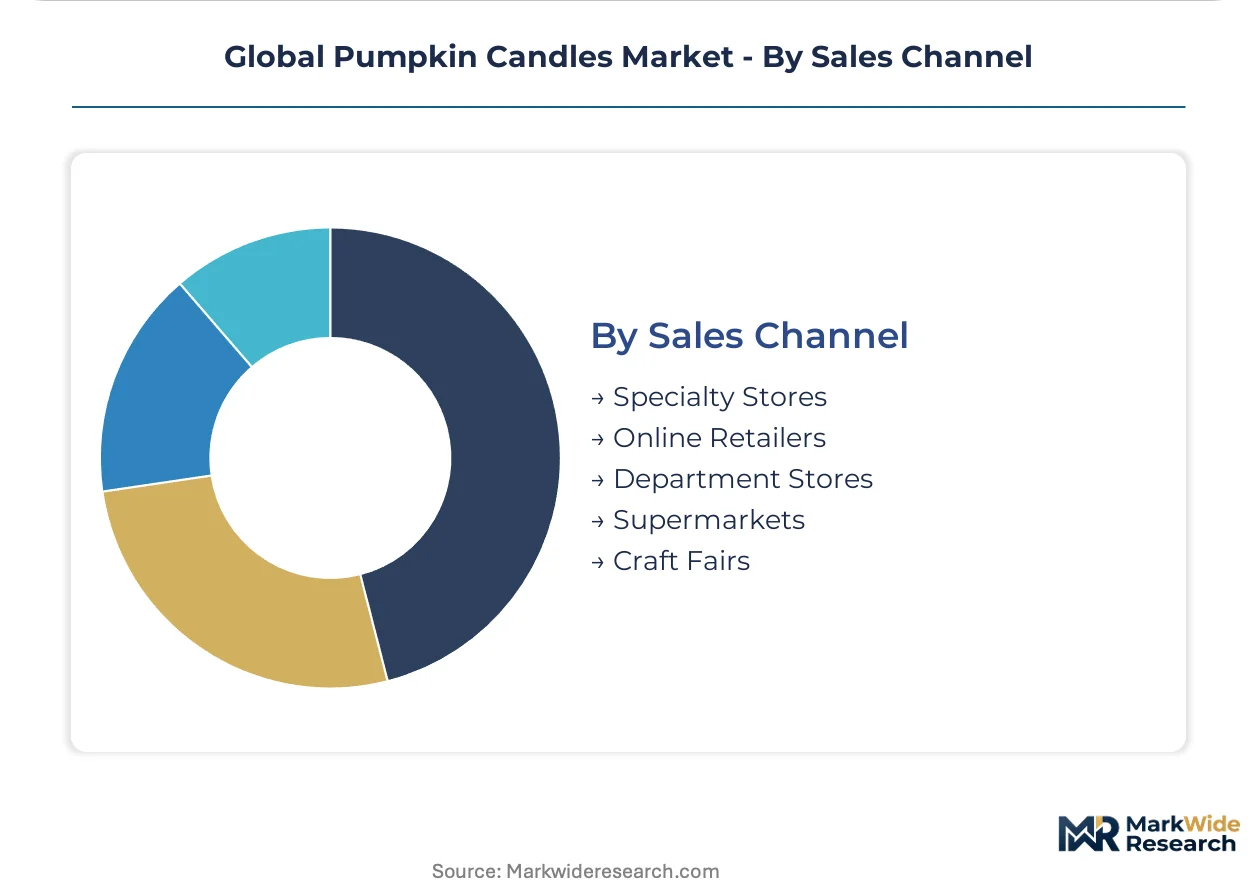
- Online Retailers:Direct-to-consumer subscription models and marketplace platforms enable rapid seasonal variant rotation without retail markdown risk. Quarterly scent clubs targeting millennials and Gen Z buyers are fragmenting traditional wholesale dependence among digitally native brands.
- Department Stores:Multi-brand beauty and home sections provide mass-market exposure with promotional calendar alignment.
- Supermarkets:Impulse-purchase placement near seasonal displays drives volume at compressed margins.
- Craft Fairs:Artisan direct sales enable small-batch producers to test formulations and build local brand equity.
Specialty Stores retain the dominant volume position, while Online Retailers are climbing the fastest through subscription model adoption and micro-fulfillment center expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paraffin refining clusters in Texas and Louisiana supply wax feedstock to North American candle manufacturers, while Vietnamese soy processing expansion is shortening lead times for vegetable-based alternatives. Fragrance formulation compliance laboratories concentrate near Rotterdam to service EU-bound exports.
United States
Autumn harvest-themed retail cycles concentrate pumpkin candle demand in August through October, with specialty retailers pre-positioning inventory six months ahead. The EPA evaluates volatile organic compound emissions from scented home products, extending new product qualification timelines. Brooklyn, Austin, and Portland host micro-fulfillment centers enabling rapid seasonal variant rotation for direct-to-consumer subscription models.
Germany
Catholic and Protestant church supply chains drive concentrated Q3 procurement for seasonal altar decoration with pillar candle formats. The EU REACH framework restricts phthalate-based fragrance fixatives, compelling reformulation of spiced pumpkin accords. Compliance laboratories in Hamburg and Frankfurt accelerate safety data sheet validation for autumn collections bound for domestic and export markets.
France
Grasse-based specialty chemical houses control fine fragrance oil production for pumpkin-spice seasonal formulations, creating supply bottleneck risk. The ANSM enforces skin-sensitizing fragrance material restrictions alongside broader EU REACH tightening. Master perfumer talent scarcity in the Provence-Alpes-Côte d'Azur region commands premium compensation for formulation chemists stabilizing oil loads in vegetable wax matrices.
Vietnam
New soy and beeswax refining capacity is diversifying paraffin dependency for North American specialty retail channels. The country's national chemical safety regulator aligns with export market requirements for clean-label positioning. Processing facilities near Ho Chi Minh City and Hanoi are shortening lead times for vegetable-based candle producers seeking alternatives to petroleum-derived feedstocks.
India
Diwali and wedding-season gifting cultures present underexploited demand for premium jar candles in Mumbai, Delhi, and Bangalore specialty retail corridors. The BIS certification framework governs product safety standards for domestic and export-bound home fragrance goods. Artisan producers in Gujarat and Maharashtra are testing small-batch formulations for regional festive-gift penetration.
Global Pumpkin Candles Market Competitive Landscape
Mass-market fragrance houses and specialty lifestyle retailers split the market between volume-driven paraffin formulations and premium vegetable-wax positioning. The vendor base stratifies across three tiers: vertically integrated multinationals with captive retail networks, boutique private-label specialists, and artisan direct-to-consumer micro-brands. Consolidation pressures favor players with backward integration into wax processing and fragrance compounding. Competitive moves center on geographic expansion into underpenetrated festive-gift markets and preemptive reformulation for emerging clean-air mandates.
Within the specialty retail tier, The Yankee Candle Company and Bath & Body Works occupy positions anchored by extensive North American distribution infrastructure. Voluspa represents the premium coconut-wax convergence archetype through decorative vessel differentiation. Among mass-market fragrance conglomerates, S.C. Johnson & Son exemplifies scale-driven portfolio diversification across home fragrance categories.
| Leading Market Players |
|---|
| Holly's House |
| Anthropologie's Boulangerie |
| The Yankee Candle Company |
| Our Own Candle Company |
| S.C. Johnson & Son |
| Bath & Body Works |
| Gibson & Dehn |
| Voluspa |
| Williams-Sonoma |
| Others |
Supply & Pricing Matrix
Overcapacity in Vietnamese soy wax processing is compressing feedstock premiums while simultaneously enabling aggressive contract pricing for North American specialty retail buyers. This utilization dynamic forces incumbent paraffin-dependent manufacturers to absorb margin erosion or accelerate vegetable-wax conversion timelines.
Pricing Analysis
EU REACH dictates the pricing tier structure through compliance cost stratification across export-bound production lines. Three-tier pricing structure across premium, standard, and economy levels separates clean-label essential oil formulations from synthetic-spice paraffin candles and mass-market petroleum-wax alternatives. Price differentiation hinges on fragrance certification tier and wax provenance transparency. Pricing pressure stems from petroleum wax volatility tracking crude indices. Mass-market supermarket channels exhibit highest price sensitivity, while specialty boutique buyers tolerate premium positioning for documented clean-label credentials.
Supply Chain Analysis
Contract manufacturing concentration sits with seasonal production facilities in Vietnam, China, and domestic United States locations managing 300% headcount fluctuations. Geographic supply concentration spans Vietnam for soy and beeswax refining, France for fine fragrance oil compounding, and Texas-Louisiana for paraffin feedstock. Raw material dependencies center on petroleum-derived wax, CO2-extracted essential oil concentrates, and cotton or wood wick substrates. Supply chain risk manifests in single-source vulnerability for Grasse-based fragrance houses controlling seasonal pumpkin-spice formulations. Distribution runs through specialty retail flagship locations, direct-to-consumer subscription fulfillment centers, and mass-market wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master perfumer chemists capable of stabilizing spice oil loads in vegetable wax matrices command compensation premiums that constrain formulation capacity expansion. This talent scarcity limits clean-label product rollout velocity for aspirational market entrants.
For Market Incumbents: Insulate margin structure through backward integration into Vietnamese wax processing capacity and captive fragrance compounding partnerships. Secure multi-year contracting windows with Grasse chemical houses before seasonal formulation demand peaks. Channel control through direct-to-consumer subscription infrastructure reduces retail markdown exposure during Q3 inventory velocity compression. For New Entrants and Emerging Players: Build out India festive-gift penetration targeting Diwali and wedding-season premium jar candle demand in Mumbai, Delhi, and Bangalore specialty corridors. Subscription-based quarterly scent clubs for millennial and Gen Z buyers bypass wholesale shelf-space negotiations entirely. Go-to-market execution should emphasize micro-fulfillment center partnerships in Brooklyn, Austin, and Portland for rapid seasonal variant rotation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription archetypes with established scent club membership bases. Long-term viability over the projection horizon favors targets with demonstrated clean-label reformulation capabilities and EU REACH compliance infrastructure. Acquisition focus should center on boutique private-label specialists with captive master perfumer relationships. The signal to watch is EPA volatile organic compound evaluation protocol expansion extending new product qualification timelines for non-compliant portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EU REACH cinnamic aldehyde restrictions compel essential oil migration for German and French market access. |
| Direct-to-Consumer Subscription Launch | Quarterly scent clubs fragment wholesale dependence while capturing recurring revenue from millennial buyers. |
| Backward Integration into Wax Processing | Vietnamese soy refining capacity shortens lead times and insulates margin from petroleum price volatility. |
| Compliance Laboratory Establishment | Rotterdam-based safety data sheet validation accelerates EU-bound export clearance for autumn collections. |
| India Festive-Gift Market Entry | Diwali and wedding-season gifting cultures in Mumbai and Delhi present underexploited premium jar candle demand. |
Research Methodology
Cross-validation between primary interviews with fragrance house formulation chemists, specialty retail category buyers, and contract manufacturing plant managers anchors the qualitative findings against secondary sources including customs trade data, EPA emission evaluation protocols, and EU REACH restriction list updates. Bottom-up triangulation through wax processor capacity assessments and top-down validation through retail audit channel checks ensures segmentation integrity.
Calibration against historical seasonal demand patterns and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, application use case, fragrance formulation tier, and sales channel architecture. CAGRs were derived through demand elasticity analysis and substitution scenario testing. Industry-specific forecast inputs include EPA volatile organic compound evaluation protocol progression and Vietnam soy processing capacity utilization trajectories.
Stress conditions across petroleum wax price volatility, master perfumer wage inflation, and EU REACH restriction list expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding seasonal demand compression timing and clean-label conversion adoption curves. Quarterly review of EPA emission standard advancement and state-level fragrance disclosure law progression is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Process Equipment Market
Others
Retail Digital Signage Market
Others
ASEAN Smart Homes Market
Others
North America Cashew Market
Others
Cloud Advertising Market
Others
Global Aircraft Sensors Market
Others
Global Thermally Conductive Grease Market
Others
Wind and Solar Hybrid Street Light Market
Others
Super Computer Market
Others
Gas Radiators Market
Others
Hot Air System Market
Others
Global Hydraulics Market
Others
Africa Lime Market
Others
Port Replicator Market
Others
AI In Government And Public Services Market
Others
Vortexers Market