
 Fluid Bed Systems Market | 2026-2036
Fluid Bed Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Bed Systems Market Foresight
The capability gap between integrated system builders and component assemblers is collapsing as modular architectures lower capital barriers. Glatt GmbH leverages its vertical integration in pharmaceutical-grade containment systems to sustain premium positioning across European installations. Buhler Aeroglide Corp. anchors its presence in food processing through thermal efficiency leadership in large-scale drying lines. Robert Bosch GmbH differentiates via embedded process analytical technology that controls real-time release parameters.
Fluid bed systems suspend particulate solids in upward-flowing gas streams to achieve uniform heat and mass transfer, typically operating at velocities between 0.5 and 3.0 meters per second depending on particle density and size distribution. These units serve primary industrial purposes in drying, granulation, and coating where precise temperature control and product homogeneity determine batch quality. Continuous fluid bed configurations now lead capital deployment in high-volume chemical production, while Wurster coating technology commands the fastest expansion in pharmaceutical oral solid dosage manufacturing. Bottom-spray systems concentrate margin pools where specialized nozzle designs protect heat-sensitive active pharmaceutical ingredients.
FDA's process validation guidance and the EU's MDR framework jointly shape equipment qualification requirements, forcing manufacturers to document design controls and installation qualification protocols. REACH restrictions on nickel alloy emissions influence material selection for fluidizing chambers and exhaust systems. EMA's evolving stance on continuous manufacturing creates compliance pathways that favor validated integrated systems over batch configurations. Stakeholders must monitor regulatory convergence between FDA and EMA on real-time release testing standards, as alignment will determine which technology platforms achieve transatlantic deployment without redundant qualification cycles.
Market Dynamics
Modular fluid bed architectures are collapsing the capability gap between integrated system builders and component assemblers, redistributing margin pools and forcing incumbents to defend premium positioning through embedded process analytical technology and vertical integration into containment systems.
Growth Catalysts
- Continuous manufacturing adoption:Pharmaceutical manufacturers are expanding fluid bed deployment for real-time release operations, driven by EMA's evolving guidance on continuous processing pathways.
- REACH material compliance:Tightening EU restrictions on nickel alloy emissions are accelerating replacement cycles for legacy fluidizing chambers and exhaust infrastructure.
- German engineering clusters:Concentrated demand around Cologne and Hamburg is driving specialized procurement of pharmaceutical-grade containment systems with integrated Wurster coating modules.
Market Restraints
- High-purity alloy input costs:Volatility in pharmaceutical-grade stainless steel and specialty nickel alloy prices compresses margins for system fabricators serving regulated industries.
- Supplier concentration risk:Critical nozzle and atomization component supply concentrates among a limited set of German and Swiss precision engineering houses.
- Technical scale limitations:Batch-to-continuous conversion remains constrained for heat-sensitive active pharmaceutical ingredients requiring precise temperature control windows.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO's alignment with ICH Q13 guidelines creates compliance pathways for validated continuous fluid bed systems in oral solid dosage manufacturing.
- Food processing thermal efficiency:Large-scale drying lines in plant-based protein and specialty grain applications represent underpenetrated demand for continuous fluid bed configurations.
- Real-time release testing convergence:Anticipated FDA-EMA alignment on analytical method validation standards will favor integrated systems capable of transatlantic deployment without redundant qualification cycles.
Industry Challenges
- Process analytical technology integration:Embedding PAT sensors for moisture, particle size, and endpoint detection requires specialized automation engineering talent scarce outside established pharmaceutical equipment hubs.
- Installation qualification timelines:FDA process validation guidance and EU MDR design control documentation extend commissioning cycles, delaying revenue recognition for system builders.
- Legacy batch system interoperability:Retrofitting continuous fluid bed modules into existing oral solid dosage lines demands complex material handling integration and control system harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Bed Systems Market |
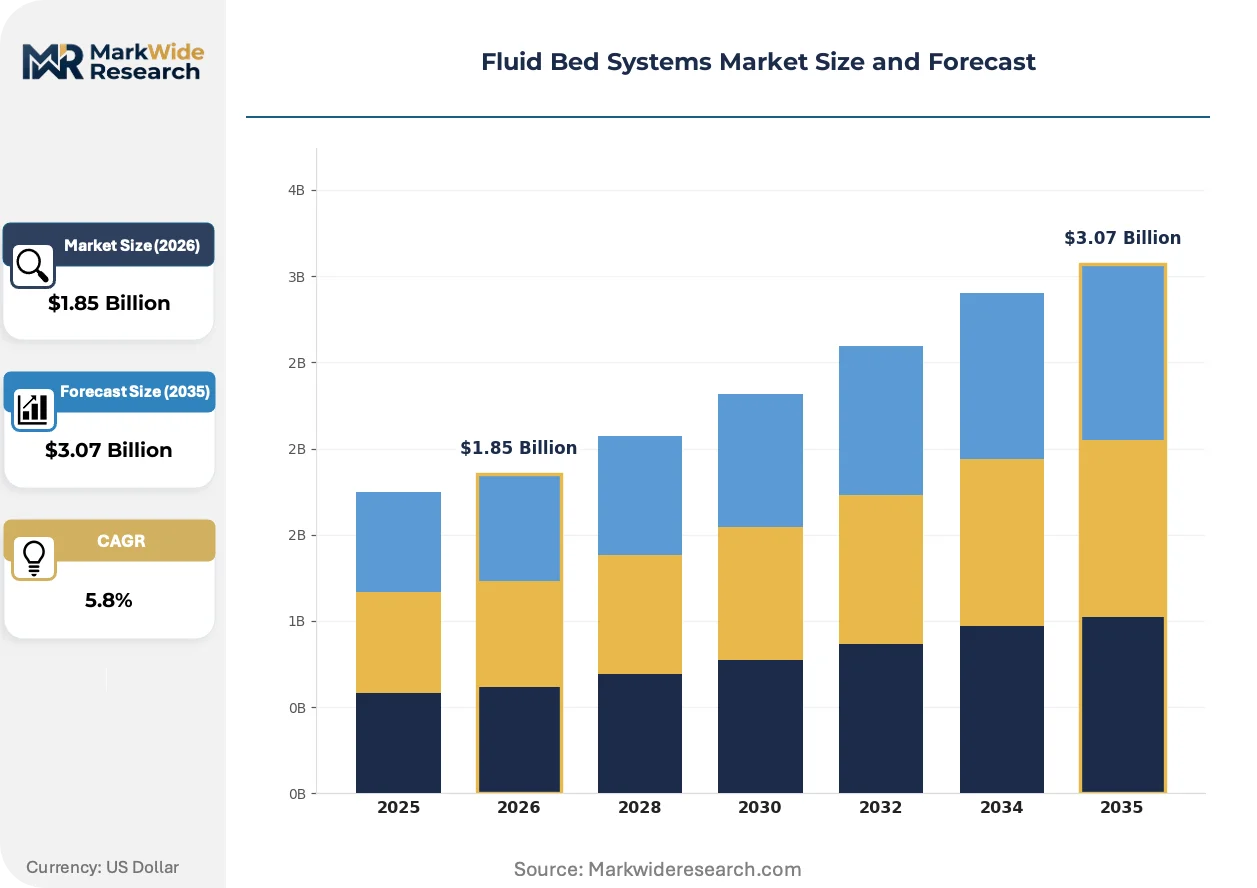
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.07 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Fluid Bed, Continuous Fluid Bed, Integrated Fluid Bed, Customized Fluid Bed Technology: Top-Spray, Bottom-Spray, Tangential-Spray, Wurster Coating Application: Powder Drying, Granulation, Coating, Agglomeration End User: Pharmaceutical Manufacturers, Chemical Producers, Food Processing Units, Agrochemical Firms |
| Companies Covered | Glatt GmbH, Bepex International LLC, FLSmidth Inc., Buhler Aeroglide Corp., L.B. Bohle, Robert Bosch GmbH, Kason Corporation, Spraying Systems Co., Applied Chemical Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Bed Systems Market Shifts & Advancements
Digital twin implementations and advanced process control architectures are actively reshaping how fluid bed systems are specified, commissioned, and operated across pharmaceutical and food processing environments.
Wurster bottom-spray coating technology is fragmenting the pharmaceutical oral solid dosage equipment landscape as manufacturers seek precise control over active ingredient layering and moisture protection. Mid-scale generic drug producers in Eastern Europe and Southeast Asia are adopting modular Wurster configurations at accelerating pace. This technology is fragmenting traditional batch coating margins by enabling smaller-footprint, lower-capital continuous operations that previously required integrated system investments.
EU MDR and REACH frameworks are jointly tightening material traceability and emissions compliance requirements for process equipment sold into European pharmaceutical manufacturing. Manufacturers must now document design controls, biocompatibility assessments, and installation qualification protocols to a depth exceeding prior medical device directives. German and Swiss system builders are responding by captive-producing critical containment components rather than sourcing from distributed supplier bases.
Service unbundling is disrupting traditional fluid bed procurement patterns as pharmaceutical operators separate equipment acquisition from validation, commissioning, and ongoing technical support contracts. Specialized engineering consultancies in Germany and the Netherlands are capturing qualification and PAT integration work previously bundled with hardware sales. This shift is most visible among mid-cap European generic manufacturers seeking to compress total cost of ownership through competitive tendering of service elements.
Fluid Bed Systems Market Segmentation
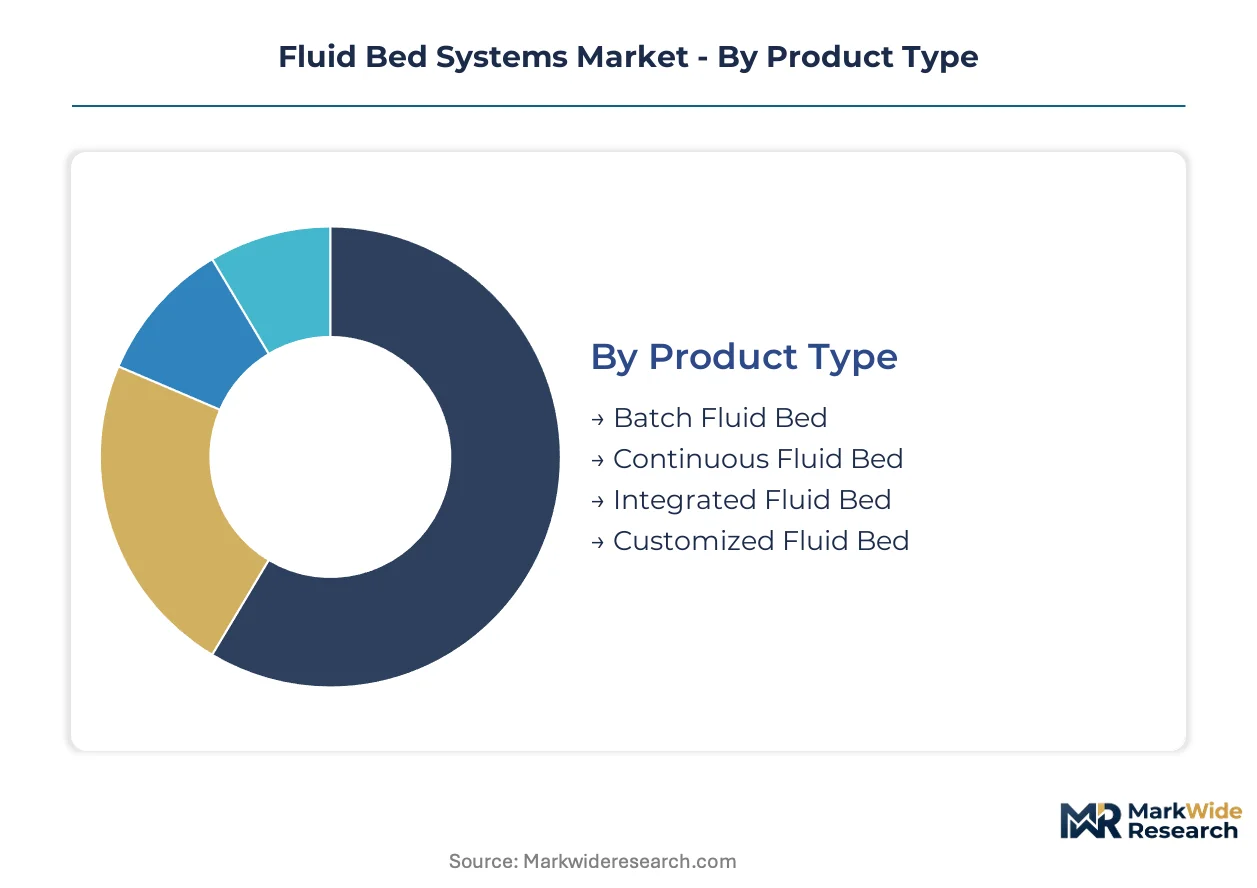
Fluid bed system purchasing decisions bifurcate between validated pharmaceutical installations demanding exhaustive documentation and industrial applications prioritizing throughput economics. Segmentation reveals where modular architectures displace integrated systems and which coating technologies command premium positioning.
Product Type:
Continuous configurations face acute substitution pressure from modular batch systems as capital-constrained operators seek flexible scale-up pathways without integrated system investments.
- Batch Fluid Bed:These units process discrete material loads in sequenced drying, granulation, or coating cycles, with pharmaceutical manufacturers in Germany and Switzerland driving demand for containment-integrated designs meeting EU MDR qualification protocols.
- Continuous Fluid Bed:Uninterrupted material flow enables real-time release operations in high-volume chemical production, though heat-sensitive active pharmaceutical ingredients constrain adoption where precise temperature windows are non-negotiable.
- Integrated Fluid Bed:Pre-engineered modules combine drying, granulation, and coating in unified control architectures.
- Customized Fluid Bed:Engineered-to-order systems address atypical particle properties or facility constraints.
Batch Fluid Bed retains volume leadership; Continuous Fluid Bed holds the steepest expansion curve.
Technology:
Cost tier stratification separates precision coating technologies commanding pharmaceutical premiums from commodity drying applications in food processing.
- Wurster Coating:Bottom-spray nozzle configurations enable precise active ingredient layering and moisture protection for oral solid dosage forms, with specialized procurement concentrating around Hamburg and Cologne engineering clusters serving EU MDR-compliant installations.
- Top-Spray:Downward-directed atomization suits conventional granulation and drying where particle agglomeration tolerance is higher, dominating food processing and bulk chemical applications with lower qualification burdens.
- Bottom-Spray:Upward nozzle orientation protects heat-sensitive actives in pharmaceutical containment environments.
- Tangential-Spray:Rotor-assisted particle motion enables high-density coating for specialized agrochemical and nutritional applications.
Wurster Coating captures the premium tier; Top-Spray maintains broadest installed base penetration.
Application:
Volume concentration in powder drying creates margin compression that coating specialists escape through pharmaceutical validation requirements.
- Coating:Functional film application for taste masking, moisture protection, and controlled release demands embedded process analytical technology and real-time endpoint detection, with EMA's continuous manufacturing guidance accelerating validated system procurement.
- Granulation:Particle size enlargement through binder application serves oral solid dosage manufacturing, where FDA process validation documentation requirements extend commissioning timelines and favor established system builders.
- Powder Drying:Moisture removal in food processing and bulk chemicals represents the largest addressable volume but faces intense thermal efficiency competition.
- Agglomeration:Particle clustering for improved flow and dissolution properties addresses specialty chemical and nutritional applications.
Powder Drying retains volume leadership; Coating holds the steepest expansion curve.
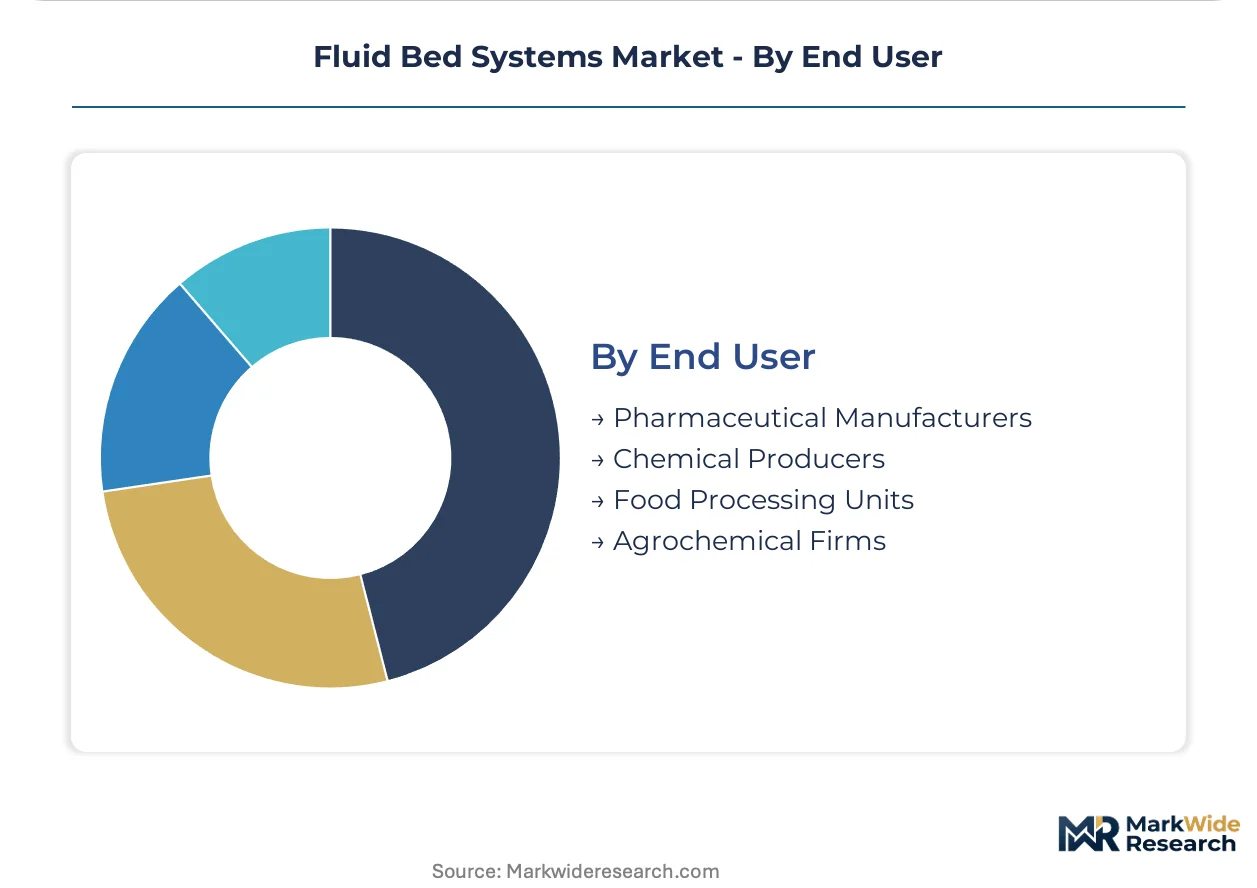
End User:
Customer type determines regulatory burden intensity, with pharmaceutical manufacturers absorbing qualification costs that exclude price-sensitive industrial buyers from advanced technology tiers.
- Pharmaceutical Manufacturers:Oral solid dosage producers deploy fluid beds across granulation, drying, and coating operations with exhaustive installation qualification protocols, REACH material compliance for nickel alloy containment, and real-time release testing integration demanded by converging FDA-EMA standards.
- Food Processing Units:Plant-based protein and specialty grain drying lines prioritize thermal efficiency and large-scale continuous configurations, with underpenetrated demand for advanced process control architectures relative to pharmaceutical adoption rates.
- Chemical Producers:Bulk intermediate and specialty chemical manufacturing employs robust drying and agglomeration systems with moderate qualification requirements.
- Agrochemical Firms:Fertilizer and crop protection formulation utilizes granulation and coating for controlled-release applications.
Pharmaceutical Manufacturers dominate premium system procurement; Food Processing Units represent the most rapidly expanding addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for fluid bed systems diverges sharply across geographies. German pharmaceutical manufacturers absorb premium pricing for EU MDR-compliant containment systems, while Indian and Southeast Asian buyers prioritize modular batch configurations that compress capital outlays.
Germany
Engineering clusters around Cologne and Hamburg concentrate specialized procurement of Wurster coating modules with integrated process analytical technology. REACH restrictions on nickel alloy emissions accelerate replacement cycles for legacy fluidizing chambers. Bavarian and North Rhine-Westphalian system builders are captive-producing critical containment components to satisfy tightened material traceability mandates.
United States
Oral solid dosage manufacturers deploy continuous fluid bed configurations for real-time release operations, with FDA process validation guidance extending commissioning timelines. EPA emissions standards for pharmaceutical manufacturing influence exhaust system design specifications. New Jersey and Massachusetts biopharma corridors anchor demand for validated integrated systems with embedded PAT sensors.
India
CDSCO alignment with ICH Q13 guidelines creates compliance pathways for continuous fluid bed adoption in generic drug production. Maharashtra and Gujarat pharmaceutical clusters drive procurement of modular batch systems that balance qualification requirements against capital constraints. Domestic engineering consultancies are capturing PAT integration work previously bundled with imported hardware.
Switzerland
Precision nozzle and atomization component supply concentrates among Swiss engineering houses serving global pharmaceutical equipment builders. Swissmedic requirements for medical device-grade process equipment reinforce premium positioning for containment-integrated designs. Basel and Zurich metro areas host specialized automation engineering talent for moisture and particle size sensor integration.
China
NMPA evolving stance on continuous manufacturing creates regulatory uncertainty that favors validated batch configurations in near-term procurement. Yangtze River Delta chemical producers deploy large-scale drying lines for bulk intermediate manufacturing. Domestic fabricators are expanding capacity for food-grade fluid bed systems serving plant-based protein processing demand.
Fluid Bed Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in fluid bed system supply. German and Swiss fabricators with in-house containment component production defend premium positioning against modular assemblers from lower-cost manufacturing bases. Three archetypes dominate: vertically integrated pharmaceutical-grade system builders, thermal efficiency specialists in food processing, and precision component suppliers for atomization and nozzle technologies. Competitive dynamics center on strategic partnerships for PAT sensor integration and geographic expansion through localized validation support.
Within the integrated pharmaceutical tier, Glatt GmbH and Robert Bosch GmbH exemplify archetypes combining containment system production with embedded process control architectures. Buhler Aeroglide Corp. occupies a distinct position among thermal efficiency-focused fabricators serving high-volume drying applications. These three anchors illustrate how competitive advantage separates between qualification-heavy regulated installations and throughput-driven industrial deployments.
| Leading Market Players |
|---|
| Glatt GmbH |
| Bepex International LLC |
| FLSmidth Inc. |
| Buhler Aeroglide Corp. |
| L.B. Bohle |
| Robert Bosch GmbH |
| Kason Corporation |
| Spraying Systems Co. |
| Applied Chemical Technology Inc. |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade stainless steel substitution for legacy nickel alloys in fluidizing chambers simultaneously concentrates procurement leverage among German and Swiss fabricators and compresses margin pools for system assemblers dependent on distributed metal sourcing. REACH compliance documentation requirements now constitute a discrete cost layer that separates captive-producers from price-competitive importers.
Pricing Analysis
After-sales service contracts and validation support packages drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-compliant containment-integrated systems from modular batch configurations and commodity drying units. Price differentiation rests on certification grade and embedded process analytical technology density. Cost compression in standard-tier batch systems is intensifying because Indian and Southeast Asian generic manufacturers prioritize capital outlay minimization. Food processing buyers exhibit highest price sensitivity; German pharmaceutical manufacturers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Container availability constraints on Hamburg-Rotterdam and Shanghai-Hamburg trade lanes extend inbound logistics cycles for precision nozzle and atomization components. Geographic supply concentration centers on Germany, Switzerland, and China for fluidizing chambers, containment systems, and control architecture respectively. Raw material dependencies draw from pharmaceutical-grade stainless steel, specialty nickel alloys, and precision-machined atomization nozzles. Single-source vulnerability concentrates among Swiss precision engineering houses for critical coating nozzles. Distribution runs through direct OEM sales for validated pharmaceutical installations and regional distributor networks for industrial drying applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluid bed system incumbents face substitution defense against spray drying and microwave drying technologies encroaching on heat-sensitive pharmaceutical applications. Modular architectures lower capital barriers for these alternatives.
For Market Incumbents: Fortify captive production of containment components and process analytical technology modules to defend premium positioning against modular assemblers. Deepen backward integration into pharmaceutical-grade stainless steel processing to offset nickel alloy price volatility. Prioritize EMA and FDA real-time release testing certification investments to create compliance moats that spray drying substitutes cannot easily replicate. For New Entrants and Emerging Players: PAT integration and validation support services represent a service-layer gap where incumbents under-serve mid-cap Eastern European and Southeast Asian generic manufacturers. Target modular Wurster coating configurations for oral solid dosage producers in Maharashtra and Gujarat seeking ICH Q13 alignment without integrated system capital outlays. Deploy engineering consultancy-led go-to-market models that unbundle hardware from qualification services. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated pharmaceutical-grade system builders with in-house containment production. Long-term viability over a multi-year window rests on regulatory convergence between FDA and EMA creating transatlantic deployment advantages for pre-qualified platforms. Monitor CDSCO enforcement posture on ICH Q13 adoption as the inflection signal determining whether Indian generic expansion sustains modular batch demand or pivots toward continuous configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containment Components | German fabricators captive-produce critical chambers to satisfy EU MDR material traceability mandates. |
| PAT Sensor Partnership Development | Automation engineering alliances with Swiss sensor specialists embed real-time release capabilities. |
| Continuous Manufacturing Certification | EMA pathway validation creates transatlantic deployment advantages without redundant qualification cycles. |
| Service Unbundling and Consultancy Capture | Specialized engineering firms in the Netherlands seize qualification work previously bundled with hardware. |
| Food Processing Thermal Efficiency Positioning | Large-scale drying line specialization addresses underpenetrated plant-based protein demand. |
Research Methodology
A standing panel of pharmaceutical plant engineers, aftermarket service directors, OEM procurement managers, and regulatory affairs specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA guidance documents, EMA continuous manufacturing frameworks, REACH substance restriction databases, and SEC filings of publicly traded equipment manufacturers. Bottom-up segmentation modeling triangulated against top-down industry association estimates from pharmaceutical and food processing trade bodies.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled product type, technology tier, application purpose, and end-user regulatory intensity as core segmentation dimensions. CAGRs were derived from installed base evolution and replacement cycle analysis rather than simple trend extrapolation. Forecast inputs incorporated REACH nickel alloy restriction timelines and CDSCO ICH Q13 alignment progress.
Underlying assumptions cover sustained regulatory convergence between FDA and EMA on real-time release testing, with deviation risk concentrated in NMPA continuous manufacturing stance uncertainty and nickel alloy commodity price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Enterprise Mobility in Healthcare Market
Others
Metal Air Battery Market
Others
Channel-In-A-Box (Ciab) Market
Others
Global Multi-Access Edge Computing Market
Others
Idaas Market
Others
Solar Panel Testers Market
Others
US Mobile MRI Services Market
Others
Latin America 3D Printing Construction Market
Others
Digital Audio Decoders Market
Others
Smart Home and Office Market
Others
Space Cables Market
Others
Cat Food Market
Others
Construction Wearables Market
Others
United States Printed Signage Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Thermal Insulation Solution for LNG and LPG Market