
 Level Measuring Instrument Market | 2026-2036
Level Measuring Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Level Measuring Instrument Market Outlook
The level measuring instrument market is pivoting along a widening gap between premium precision systems and commodity sensor tiers. Emerson Electric leverages its Rosemount instrumentation portfolio to dominate high-reliability applications in hydrocarbon processing. Endress+Hauser anchors its position through dense service networks and calibration capabilities that commodity suppliers cannot replicate. Siemens competes by bundling level sensors with its distributed control system architecture, locking in integrated plant automation contracts.
A level measuring instrument detects, monitors, and quantifies liquid, solid, or slurry heights within vessels, channels, or silos using time-of-flight, capacitance, or buoyancy principles with accuracies typically ranging from ±1 mm to ±10 mm depending on the medium and technology. These devices serve critical functions in process safety, inventory reconciliation, and regulatory compliance across continuous and batch operations. Ultrasonic level sensors lead in water and wastewater applications where non-contact measurement prevents fouling in harsh effluent environments, while guided wave radar technology captures expanding share in oil and gas storage as operators prioritize measurement stability across wide temperature and pressure ranges. Capacitive level sensors retain strongholds in food and beverage tanks where hygienic design and CIP compatibility constrain alternative technologies.
The EPA enforces Clean Water Act effluent limits that compel municipal and industrial facilities to install continuous level monitoring for detention basins and equalization tanks. In Europe, the EU Green Deal and F-Gas Regulation accelerate migration away from mechanical and pneumatic level devices toward electronic non-contact solutions with lower lifecycle emissions. In China, GB standards issued by SAMR mandate explosion-proof certifications for instruments deployed in petrochemical zones, shaping supplier qualification requirements. Stakeholders must weigh technology substitution risks against retrofit timelines as regulatory stringency diverges across jurisdictions.
Market Dynamics
The Level Measuring Instrument Market is bifurcating between precision-grade systems for critical process control and cost-optimized sensors for bulk inventory tracking, with regulatory mandates accelerating this polarization across water utilities and hydrocarbon storage.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is forcing European chemical plants to abandon pneumatic level transmitters in favor of electronic radar and ultrasonic alternatives with lower lifecycle emissions.
- Ultrasonic non-contact measurement:Water and wastewater utilities in Germany and the Netherlands are standardizing on ultrasonic sensors to prevent fouling in harsh effluent environments while meeting stricter effluent discharge mandates.
- Petrochemical cluster expansion:China's coastal refining hubs are driving demand for guided wave radar systems capable of stable measurement across extreme temperature and pressure ranges in storage terminals.
Market Restraints
- Semiconductor component volatility:Supply constraints for specialized analog-to-digital converters and RF modules are extending lead times for radar level transmitters by 12-18 weeks.
- Technical limitation in foamy media:Ultrasonic sensors suffer signal attenuation in aerated liquids, restricting deployment in certain pharmaceutical fermentation and food processing applications.
- Substitution threat from weight-based systems:Load cell and strain gauge technologies are capturing share in small-batch chemical processing where vessel geometry complicates level-based approaches.
Strategic Opportunities
- India's municipal water infrastructure:The country's smart cities mission and AMRUT 2.0 scheme are creating first-time demand for networked level monitoring in distribution reservoirs and pumping stations.
- Technology convergence of radar and IIoT:Integration of 80 GHz radar sensors with edge computing platforms enables predictive maintenance and remote diagnostics for distributed tank farms.
- Brazil's biofuel storage expansion:ANP regulations mandating continuous inventory monitoring for ethanol and biodiesel terminals are opening new application vectors for capacitive and hydrostatic technologies.
Industry Challenges
- Calibration technician scarcity:Qualified personnel capable of performing NIST-traceable calibrations on radar and guided wave systems are concentrated in metropolitan industrial clusters, limiting service coverage.
- Legacy system integration friction:Retrofitting digital level transmitters into existing 4-20 mA HART infrastructures requires protocol gateway investments that complicate total cost justification.
- Explosion-proof certification timelines:ATEX and IECEx approval processes for instruments destined for Zone 0/1 hazardous areas routinely extend product launch schedules by 9-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Level Measuring Instrument Market |
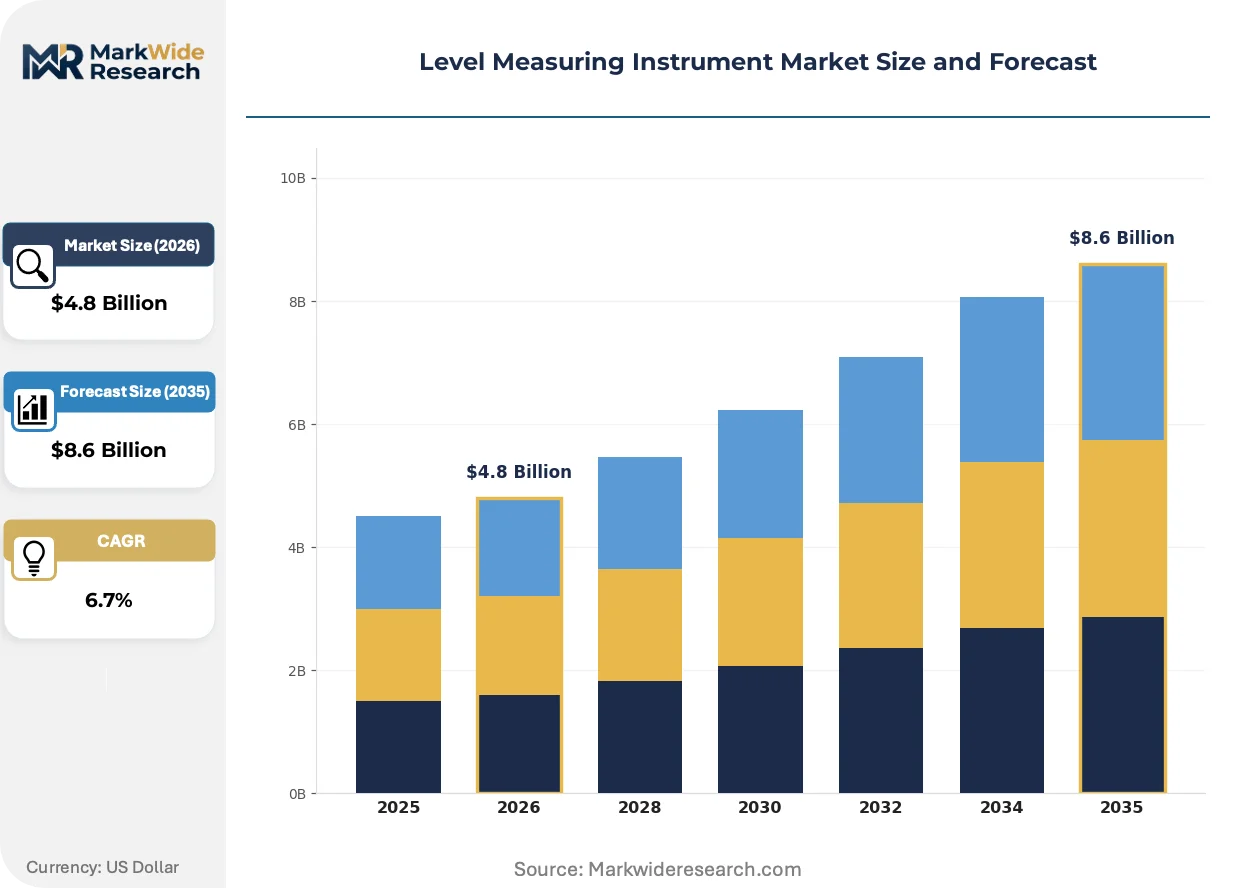
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Level Sensors, Laser Level Sensors, Capacitive Level Sensors, Magnetostrictive Level Sensors Technology: Contact, Non-Contact, Guided Wave Radar, Optical End User: Oil & Gas, Water & Wastewater, Chemical, Food & Beverage Application: Tank Level Monitoring, Flow Measurement, Inventory Management, Level Control |
| Companies Covered | Emerson Electric, Endress+Hauser, Siemens, ABB, Yokogawa Electric, VEGA Grieshaber, KROHNE, AMETEK, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Level Measuring Instrument Market Strategic Shifts
Sensor fusion architectures and software-defined measurement capabilities are redefining how level instrumentation delivers value, shifting competitive advantage from hardware precision toward data integration and predictive analytics.
80 GHz frequency-modulated continuous wave radar is consolidating the high-precision segment by delivering sub-millimeter accuracy in narrow nozzles and agitated tanks where legacy 6 GHz and 26 GHz systems suffered beam divergence and false echo interference. Hydrocarbon storage operators in the US Gulf Coast and Rotterdam port complex are adopting these sensors at accelerating rates. The technology is consolidating supplier margins by reducing the need for stilling wells and mechanical waveguides that previously generated recurring accessory revenue.
The EU Green Deal's industrial emissions monitoring requirements are mandating continuous level surveillance in carbon capture solvent storage and hydrogen buffer tanks, compelling instrument suppliers to certify products for emerging cryogenic and high-purity hydrogen service. German chemical parks are retrofitting existing tank farms with SIL-rated level systems to satisfy TÜV functional safety audits. This regulatory pressure is compressing product development cycles as vendors race to validate materials compatibility with novel process chemistries.
After-sales service unbundling is disrupting traditional channel economics, with end-users in the US water sector increasingly sourcing calibration and repair services from third-party metrology laboratories rather than OEM service networks. Municipal procurement departments in California and Texas are mandating open-architecture specifications that prevent vendor lock-in through proprietary diagnostic protocols. This behavioral shift is most pronounced in large metropolitan water districts managing decentralized instrumentation fleets exceeding ten thousand installed points.
Level Measuring Instrument Market Segmentation
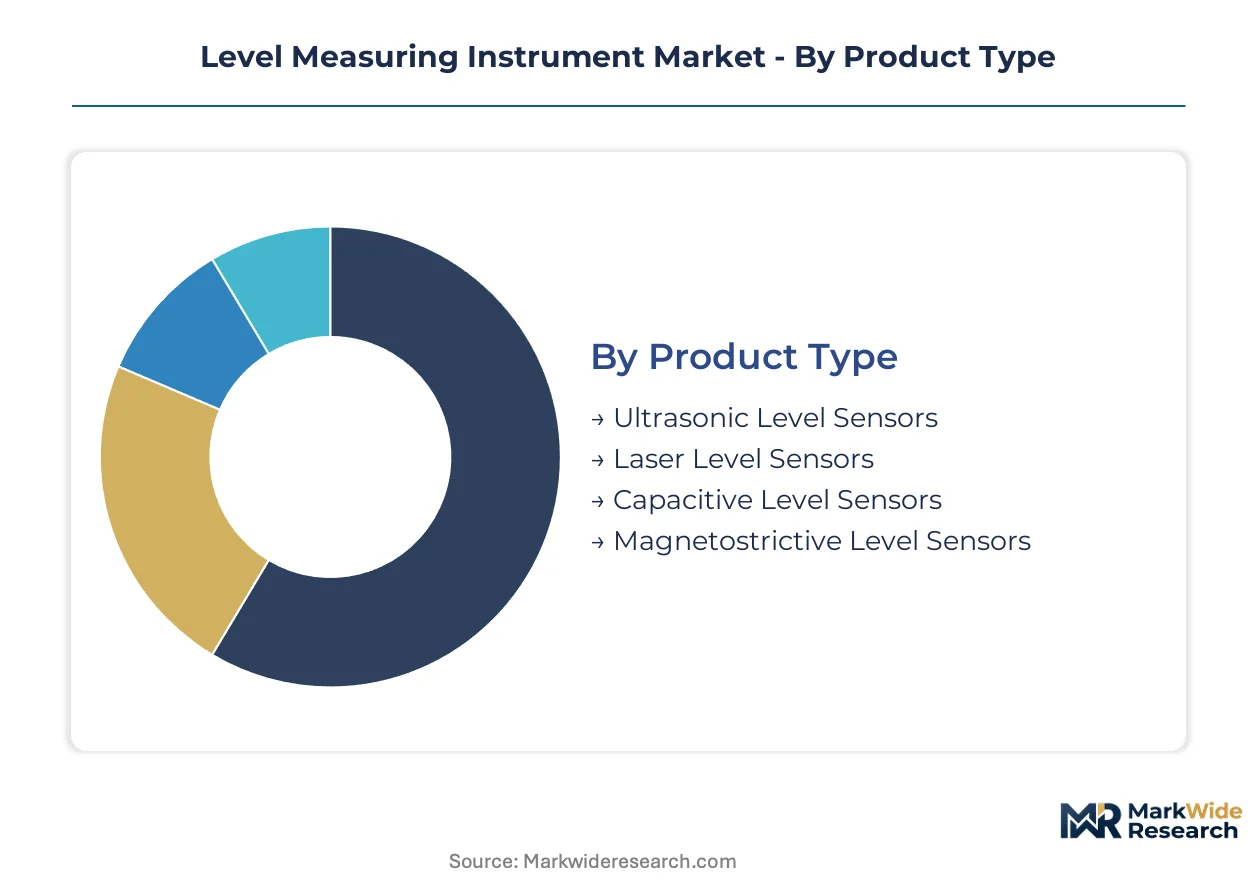
Technology selection in level instrumentation hinges on medium properties, vessel geometry, and regulatory compliance requirements. Each segmentation axis reveals distinct procurement patterns across process industries, from standardized ultrasonic deployments in municipal water to engineered radar systems in hydrocarbon storage.
Product Type:
Standardization dominates ultrasonic and capacitive offerings, while laser and magnetostrictive systems demand application-specific engineering and calibration protocols.
- Ultrasonic Level Sensors:These devices transmit high-frequency acoustic pulses and measure time-of-flight to determine liquid or solid surfaces without medium contact. Water utilities in Germany and the Netherlands specify ultrasonic sensors for primary clarifiers and equalization basins where fouling resistance outweighs precision requirements.
- Capacitive Level Sensors:Probes detect capacitance changes between sensing electrode and vessel wall as medium height varies, enabling continuous measurement in conductive or non-conductive fluids. Food and beverage processors in California dairy clusters favor capacitive probes for CIP-compatible tank monitoring where hygienic design constraints eliminate mechanical alternatives.
- Laser Level Sensors:Time-of-flight laser systems deliver millimeter-grade accuracy for inventory reconciliation in cement and mining silos.
- Magnetostrictive Level Sensors:Float-actuated waveguide technology provides high-resolution output for custody transfer applications in petroleum terminals.
Most installed capacity flows through ultrasonic sensors. Expansion is steepest in laser systems for bulk solids.
Technology:
Margin structures diverge sharply between commodity non-contact electronics and engineered contact systems requiring material compatibility validation.
- Contact:Displacers, floats, and hydrostatic probes maintain cost advantages in benign media applications. Municipal water districts in Texas deploy contact hydrostatic transmitters for reservoir monitoring where temperature stability is assured.
- Non-Contact:Radar and ultrasonic architectures eliminate mechanical wear and enable measurement through sealed vessels. Chemical processors on the US Gulf Coast specify 80 GHz FMCW radar for agitated reactor vessels where foam and vapor complicate alternative approaches.
- Guided Wave Radar:Coaxial or twin-rod waveguides concentrate microwave energy for reliable measurement in low-dielectric media and turbulent conditions.
- Optical:Laser and infrared systems capture share in solids level applications where dust and angle of repose challenge radar performance.
Non-contact systems carry the majority of new project value. Guided wave radar is climbing the fastest in petrochemical storage retrofits.
End User:
Procurement sophistication varies from specification-driven oil and gas engineering to price-sensitive municipal water tendering.
- Oil & Gas:Storage terminal operators demand SIL-rated instruments with ATEX/IECEx certification for Zone 0/1 hazardous areas. Rotterdam port complex refineries specify redundant level systems for floating roof tanks subject to EPA spill prevention regulations.
- Water & Wastewater:Utilities prioritize total cost of ownership and open protocol compatibility over precision specifications. India's AMRUT 2.0 scheme is creating first-time demand for networked level monitoring in distribution infrastructure.
- Chemical:Batch processors require instruments validated for aggressive chemistries and extreme temperature cycling.
- Food & Beverage:Hygienic design standards constrain sensor selection to materials meeting 3A Sanitary and EHEDG guidelines.
Oil and gas accounts for the largest project value. Water and wastewater is expanding most quickly in developing economies.
Application:
Functional requirements determine sensor specification intensity, from safety-critical level control to routine inventory reconciliation.
- Tank Level Monitoring:Continuous measurement for process vessels, storage tanks, and atmospheric silos represents the foundational application. Brazil's ANP regulations mandate continuous inventory monitoring for ethanol terminals, driving capacitive and hydrostatic deployments.
- Inventory Management:Custody transfer accuracy demands traceable calibration and redundant measurement architectures. German chemical parks retrofit tank farms with SIL-rated systems to satisfy TÜV functional safety audits.
- Flow Measurement:Open channel and flume level-to-flow conversions support wastewater discharge compliance monitoring.
- Level Control:High/low switches and continuous control loops enable pump protection and process automation.
Tank level monitoring carries the majority of installed base. Inventory management is gaining share fastest in regulated hydrocarbon storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration technicians and process automation engineers concentrate in Germany's chemical corridor and the US Gulf Coast refining belt, anchoring demand for precision instrumentation expertise.
United States
EPA spill prevention regulations for aboveground storage tanks drive replacement cycles in petroleum terminals along the Houston Ship Channel. The agency's Clean Water Act enforcement compels municipal utilities in California and Texas to deploy continuous level monitoring for detention basins. Refinery operators in the US Gulf Coast specify SIL-rated radar systems for floating roof tanks.
Germany
Chemical and pharmaceutical clusters in Ludwigshafen and Leverkusen demand precision level monitoring for batch reactor vessels and solvent storage. The EU F-Gas Regulation accelerates migration from pneumatic transmitters toward electronic radar alternatives with lower lifecycle emissions. TÜV functional safety audits in German chemical parks mandate certified instrument retrofits.
China
Coastal refining hubs in Zhejiang and Shandong provinces expand storage terminal capacity for crude oil and petrochemical feedstocks. SAMR's GB standards mandate explosion-proof certifications for instruments deployed in Zone 0/1 hazardous areas. State-owned operators in the Yangtze River Delta prioritize guided wave radar for extreme temperature and pressure applications.
India
The AMRUT 2.0 scheme and smart cities mission create first-time demand for networked level monitoring in distribution reservoirs and pumping stations. Central government infrastructure programs require open protocol compatibility for municipal procurement. Metropolitan water districts in Maharashtra and Gujarat deploy ultrasonic sensors for primary clarifier monitoring.
Brazil
ANP regulations mandate continuous inventory monitoring for ethanol and biodiesel terminals supporting biofuel storage expansion. Federal energy policies require certified instruments for custody transfer applications in fuel distribution networks. Terminal operators in São Paulo state retrofit tank farms with hydrostatic and capacitive level systems.
Level Measuring Instrument Market Competitive Environment
Top-tier vendors anchor the precision instrumentation segment, while mid-tier suppliers compete on cost-optimized sensor bundles. The market exhibits tiered concentration with distinct capability gaps between premium and commodity offerings. Three strategic archetypes dominate: integrated automation conglomerates bundling sensors with control systems, specialized instrumentation houses with dense service networks, and component suppliers targeting price-sensitive bulk inventory applications. Competitive moves center on IIoT platform integration and aftermarket service unbundling.
Within the integrated automation tier, Emerson Electric and Siemens occupy positions exemplifying bundled control architecture strategies. Endress+Hauser represents the specialized instrumentation archetype with emphasis on calibration capabilities and application engineering. These three entities anchor the premium segment through distinct competitive vectors rather than overlapping positioning.
| Leading Market Players |
|---|
| Emerson Electric |
| Endress+Hauser |
| Siemens |
| ABB |
| Yokogawa Electric |
| VEGA Grieshaber |
| KROHNE |
| AMETEK |
| Honeywell |
| Others |
Value Chain & Pricing Dynamics
80 GHz frequency-modulated continuous wave radar adoption simultaneously compresses component costs through semiconductor integration and concentrates procurement power among tier-one automation conglomerates capable of vertical RF module sourcing. This technology transition rewards suppliers with captive foundry relationships while squeezing margins for assembly-only vendors dependent on merchant analog-to-digital converter supply.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across the market. Three-tier pricing structure across premium, standard, and economy levels separates SIL-certified radar systems with calibration protocols from commodity ultrasonic sensors and entry-level hydrostatic transmitters. Price differentiation hinges on ATEX/IECEx certification tier and aftermarket service bundling. Cost compression in the standard tier is intensifying because municipal water utilities in California and Texas mandate open-architecture specifications that prevent vendor lock-in. Price sensitivity peaks among developing-economy water infrastructure projects, while oil and gas terminal operators demonstrate lowest sensitivity due to safety-critical procurement protocols.
Supply Chain Analysis
Calibration technician scarcity in Germany, the United States, and China constrains final assembly capacity and extends order fulfillment timelines for precision-grade instruments. RF module production draws from specialized semiconductor foundries in Taiwan and South Korea, while explosion-proof enclosure machining centers on German and Italian metalworking clusters. Single-source vulnerability in 80 GHz radar-on-chip supply creates bottleneck exposure for tier-two assemblers lacking dual-qualified foundry relationships. Distribution runs through OEM-direct channels for large petrochemical contracts and industrial distributors for municipal water tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German chemical parks absorb premium pricing for TÜV-certified SIL systems while Indian municipal tenders prioritize lowest-unit-cost ultrasonic sensors under AMRUT 2.0 procurement rules.
For Market Incumbents: Lock in service network density as the primary defensive moat. Expand calibration technician training programs in secondary Indian and Brazilian industrial clusters to preempt third-party metrology laboratory capture. Deepen backward integration into 80 GHz RF module design to reduce foundry dependency and protect margin structure against merchant semiconductor volatility.
For New Entrants and Emerging Players: IIoT-enabled predictive maintenance platforms offer a technology-first wedge into the aftermarket service unbundling trend. Target Brazil's ANP-mandated ethanol terminal retrofits where incumbent service coverage remains thin and open-protocol specifications level procurement playing fields. Lead with edge-computing integration bundled with capacitive sensors to differentiate from commodity hydrostatic offerings.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional calibration service providers with NIST-traceable capabilities but limited geographic footprint. Long-term viability over the projection horizon rests on explosive-proof certification asset ownership and IIoT platform development capacity. Watch for inflection when Indian smart cities mission procurement shifts from hardware-only to performance-based service contracting.
| Strategic Initiative | Industry Significance |
|---|---|
| 80 GHz Radar Platform Integration | Consolidates supplier margins by eliminating stilling well accessory revenue in US Gulf Coast storage terminals. |
| Calibration Service Network Expansion | Captures aftermarket value as California water districts source third-party metrology over OEM channels. |
| ATEX/IECEx Certification Acceleration | Compresses product launch timelines for Zone 0/1 hazardous area instruments in Rotterdam port complex. |
| Edge Computing Partnership Development | Enables predictive maintenance offerings for distributed tank farms under EU Green Deal monitoring mandates. |
| Open Protocol Specification Adoption | Prevents vendor lock-in objections from municipal procurement departments in Texas and California. |
Study Parameters
Direct dialogue with plant engineers, municipal water procurement officers, aftermarket service managers, and calibration technicians grounded qualitative findings in operational reality. Secondary validation drew from EPA enforcement databases, EU F-Gas Regulation implementation reports, SAMR GB standard filings, and ANP regulatory circulars. Bottom-up instrumentation deployment tallies triangulated against top-down process industry capital expenditure patterns.
Segmentation outputs across technology type, end-user industry, application function, and regional regulatory cluster fed into the analytical framework. CAGRs were derived from installed base replacement cycles and greenfield project pipelines without year-specific anchoring. Forecast inputs incorporated EU Green Deal compliance timelines and India's AMRUT 2.0 disbursement velocity as demand-shaping variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply normalization and explosion-proof certification backlog clearance. Forecasts reflect documented assumptions regarding regulatory stringency trajectories and infrastructure program execution rates. Material deviation in EU F-Gas phase-down pacing or Chinese coastal refinery expansion timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
UK Cat Food Market
Others
South America Automotive LED Lighting Market
Others
Coriolis Meters Market
Others
North America Machine Vision Systems Market
Others
Interference Mitigation Filters Market
Others
Italy Smart Home Market
Others
Hydrostatic Testing Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Vacuum Evaporators Market
Others
US 3D Printing Construction Market
Others
Receiving Scales Market
Others
Finished Leather Market
Others
United States Smart Homes Market
Others
Manometers Market
Others
Delumper Market
Others
Global Smartphone ODM Market