
 Global Smart Devices Market | 2026-2036
Global Smart Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Devices Market Analysis
Platform licensing revenue is tilting away from one-time hardware sales toward recurring software monetization. Samsung Electronics leverages its vertically integrated semiconductor supply chain to control component costs across smartphones and home appliances. Apple Inc. sustains premium pricing power through proprietary silicon design and closed ecosystem architecture. Xiaomi Corporation anchors volume growth in emerging markets with aggressive hardware margin compression offset by internet services income.
Smart devices encompass networked electronic equipment with embedded sensors, microprocessors, and wireless communication modules enabling autonomous data exchange and remote operability. These products typically integrate Bluetooth 5.0 or higher, Wi-Fi 6 protocols, and edge-computing capabilities to execute localized processing with sub-100-millisecond latency for real-time responsiveness. Smartphones retain the dominant value share within product type segmentation, though smart home devices are expanding faster as retrofit installation costs decline. IoT technology underpins connectivity architecture across all categories, while AI integration is becoming the primary margin differentiator in security and entertainment applications.
FCC certification mandates in the United States govern radio frequency emissions and electromagnetic compatibility for all wireless-enabled devices entering the market. The EU AI Act imposes risk-based compliance tiers on smart products employing biometric identification or automated decision-making, directly affecting product development cycles for European market access. China's SAMR enforces national GB standards for data security and interoperability in connected consumer electronics. Stakeholders must weigh regulatory divergence against platform standardization bets when allocating R&D budgets across geographic portfolios.
Market Dynamics
The Global Smart Devices Market is bifurcating between premium ecosystem captives and commodity hardware producers, with AI inference capabilities now determining margin capture rather than component specifications alone.
Growth Catalysts
- EU AI Act compliance mandates:Risk-tiered algorithmic transparency requirements are accelerating replacement cycles for biometric-enabled devices across European consumer markets.
- Remote patient monitoring expansion:United States healthcare providers are deploying connected wearables for chronic disease management, creating institutional demand pull for FDA-cleared devices.
- Shenzhen-Dongguan manufacturing concentration:Coastal China's integrated component ecosystem enables rapid prototyping-to-production scaling for IoT hardware startups.
Market Restraints
- Semiconductor supply concentration:Advanced node fabrication for AI accelerators remains captive to Taiwan and South Korea foundries, exposing volume planning to geopolitical disruption.
- GB standards compliance costs:China's SAMR interoperability mandates require redundant certification testing for foreign OEMs seeking domestic market access.
- Edge AI power constraints:On-device neural processing thermal budgets limit model complexity in battery-operated form factors below smartphone scale.
Strategic Opportunities
- Rural India connectivity gaps:Low-cost smart home retrofit kits priced below $50 are penetrating tier-3 cities where broadband infrastructure is newly deployed.
- Matter protocol convergence:Thread and Wi-Fi unified commissioning is collapsing smart home installation friction, enabling electrician-channel distribution bypassing retail.
- Japan METI carbon labeling:Mandatory lifecycle emissions disclosure for consumer electronics is creating first-mover advantage for supply chains with renewable energy certificates.
Industry Challenges
- FCC Part 15 certification timelines:Radio frequency equipment authorization backlogs in the United States are extending product launch windows by 4-8 months for unlicensed spectrum devices.
- Embedded systems firmware talent scarcity:Real-time operating system expertise for sub-100-millisecond latency applications commands premium compensation in labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Devices Market |
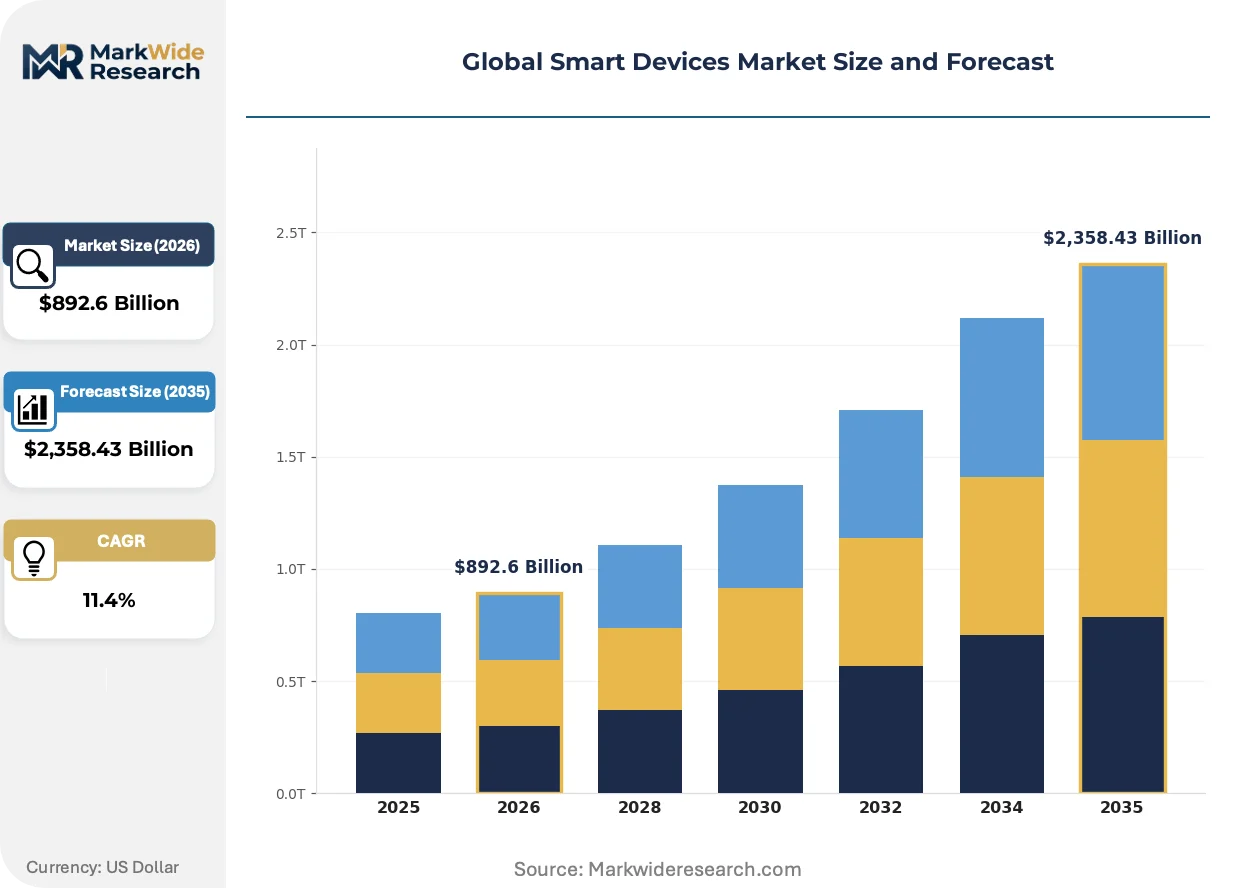
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $2,358.43 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Smartwatches, Smart Home Devices, Smart Speakers Technology: IoT, NFC, Bluetooth, AI Application: Healthcare, Home Automation, Security, Entertainment End User: Consumers, Enterprises, Healthcare Providers, Retailers |
| Companies Covered | Samsung Electronics, Apple Inc., LG Electronics, Amazon.com, Inc., Google LLC, Xiaomi Corporation, Panasonic Corporation, Whirlpool, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Devices Market Emerging Trajectories
Computational workloads are migrating from cloud data centers toward endpoint devices, compressing architecture decisions around thermal design power and memory bandwidth rather than connectivity specifications.
On-device large language model inference is collapsing the distinction between cloud-dependent assistants and autonomous smart speakers. Smart home OEMs in South Korea and China are shipping 7-billion-parameter models running on NPU silicon at sub-5-watt TDP. This capability compression eliminates subscription revenue dependencies for voice control while raising hardware BOM floors by 15-20 percent.
The EU AI Act's high-risk system classification is forcing biometric device developers to maintain algorithmic audit trails and human-in-the-loop override architectures. European market entrants must now budget 12-18 month compliance engineering cycles before CE marking. Security camera and smart lock manufacturers are responding by segregating EU-specific firmware branches from global product lines.
Enterprise buyers in United States healthcare and logistics are unbundling device procurement from managed connectivity services, pressuring OEMs to expose API-first control planes. Hardware margins compress as software monetization shifts to third-party platform licensing. This disintermediation is most visible in industrial wearable deployments where IT departments demand direct fleet management integration rather than vendor-locked dashboards.
Global Smart Devices Market Segmentation
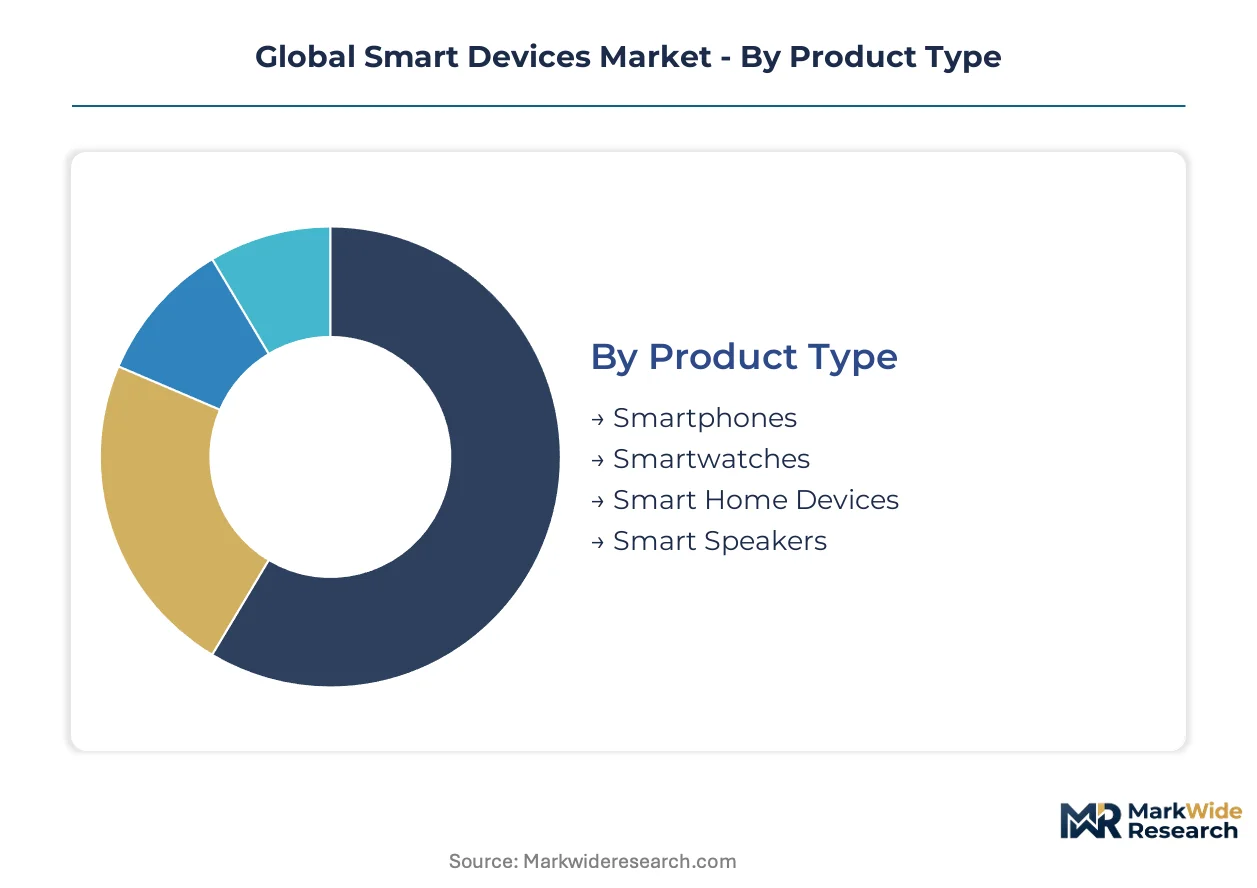
Smart device segmentation reveals how hardware specifications, connectivity protocols, and buyer economics fragment addressable demand. Understanding these divisions exposes where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Use-case spectrum spans pocket-scale personal computing through whole-home infrastructure, with form factor determining thermal budgets, battery constraints, and replacement cadence.
- Smartphones:Pocket-sized computers with embedded biometric sensors, multi-band cellular modems, and sub-6GHz 5G capability. Demand concentrates in replacement cycles driven by on-device AI inference capabilities, with FCC and EU AI Act compliance costs now embedded in BOM calculations.
- Smart Home Devices:Climate controllers, lighting systems, and appliance interfaces leveraging Thread and Wi-Fi 6E protocols. Retrofit installation cost declines below $150 per room are accelerating penetration in United States suburban housing stock and European rental markets.
- Smartwatches:Wrist-worn health monitors with PPG sensors and FDA-cleared ECG algorithms. Institutional procurement by United States hospital systems for remote patient monitoring programs is displacing consumer gift-giving as the primary demand driver.
- Smart Speakers:Far-field microphone arrays with cloud-tethered or on-device natural language processing. Price compression below $30 for entry-tier units in India and Southeast Asia is compressing hardware margins to single digits.
The dominant share belongs to Smartphones, while Smart Home Devices is closing the gap fastest.
Technology:
Connectivity and compute layers determine interoperability boundaries and developer ecosystem lock-in.
- IoT:Mesh networking protocols enabling device-to-device communication without cloud intermediation. Matter standard convergence is collapsing fragmentation between Zigbee, Z-Wave, and proprietary stacks, reducing certification overhead for multi-protocol OEMs.
- AI:Neural processing units executing inference workloads at sub-5-watt TDP for voice recognition and predictive automation. Edge AI deployment is climbing the fastest as privacy regulations in Europe and China mandate local processing for biometric data.
- Bluetooth:Low-energy 5.3 specification delivering sub-100-millisecond latency for audio and input peripherals. Hearing aid compatibility mandates from the United States FDA are expanding addressable market for assistive audio wearables.
- NFC:Near-field secure element integration for contactless payment and access credential emulation. Transit authority procurement in Japan, South Korea, and European capitals is standardizing mobile wallet infrastructure.
IoT retains installed base dominance, though AI commands the steepest expansion trajectory in new product development budgets.
Application:
Functional deployment context dictates certification requirements, pricing tolerance, and replacement frequency.
- Healthcare:Continuous glucose monitors, pulse oximeters, and cardiac event recorders requiring FDA, EMA, or NMPA clearance. United States reimbursement codes for remote therapeutic monitoring are institutionalizing procurement through hospital IT departments rather than direct-to-consumer channels.
- Home Automation:Climate, lighting, and security orchestration through unified control planes. Electrician-channel distribution in Germany and France is bypassing retail margin extraction as Matter protocol simplifies commissioning.
- Security:Video doorbells, perimeter sensors, and biometric access controls. EU AI Act high-risk system classification is forcing algorithmic audit trail architecture that adds 12-18 months to European market entry timelines.
- Entertainment:Streaming devices, gaming peripherals, and immersive audio systems. Japanese METI carbon labeling requirements are creating supply chain differentiation for manufacturers with renewable energy certificates.
Home Automation captures volume leadership, while Healthcare is gaining share fastest through regulatory-enabled reimbursement expansion.
End User:
Procurement authority and budget source determine feature prioritization and pricing elasticity.
- Consumers:Individual purchasers prioritizing ecosystem continuity and aesthetic integration. Replacement cycles are lengthening beyond 36 months in premium smartphone tiers as hardware performance plateaus.
- Enterprises:Fleet deployments for logistics, warehousing, and field service workforce enablement. API-first control plane demands are disintermediating OEM software monetization in favor of third-party platform licensing.
- Healthcare Providers:Hospital systems and payor networks deploying chronic disease management infrastructure. FDA 510(k) clearance requirements are filtering vendor pools to established players with regulatory affairs capabilities.
- Retailers:Inventory management, loss prevention, and customer analytics infrastructure. Edge AI video analytics for foot traffic pattern recognition is displacing cloud-dependent solutions to minimize latency and data egress costs.
Consumers retain absolute volume dominance, though Enterprises are expanding most quickly as IT departments unbundle device procurement from managed connectivity services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States healthcare systems deploy connected wearables for institutional chronic disease management, diverging from China's consumer electronics replacement cycles and India's first-time smart home adoption patterns.
United States
FDA-cleared remote patient monitoring devices command procurement budgets from hospital IT departments, displacing consumer channels. FCC Part 15 certification timelines extend product launches by 4-8 months for unlicensed spectrum devices. Manufacturing concentrates in Austin, Texas, where semiconductor design houses cluster near Apple and Samsung R&D facilities.
China
Shenzhen-Dongguan manufacturing ecosystems enable rapid prototyping-to-production scaling for IoT hardware startups. SAMR enforces national GB standards for data security and interoperability in connected consumer electronics. The Pearl River Delta anchors component sourcing for global OEMs seeking cost-controlled volume production.
Germany
Electrician-channel distribution bypasses retail margin extraction as Matter protocol simplifies smart home commissioning. EU AI Act risk-tiered compliance mandates accelerate replacement cycles for biometric-enabled devices. Industrial automation specialists in Bavaria integrate smart sensors into manufacturing equipment for predictive maintenance.
Japan
METI carbon labeling requirements create supply chain differentiation for manufacturers with renewable energy certificates. Transit authority procurement standardizes mobile wallet infrastructure through NFC secure element integration. Kanto region electronics conglomerates consolidate R&D for edge AI silicon at sub-5-watt thermal design power.
India
Low-cost smart home retrofit kits priced below $50 penetrate tier-3 cities where broadband infrastructure is newly deployed. BIS certification mandates for electronics imports filter vendor pools to established players with testing capabilities. Karnataka's Bangalore cluster hosts IoT startups targeting rural connectivity gaps with localized firmware.
Global Smart Devices Market Vendor Landscape
Capability concentration sits with vertically integrated semiconductor designers; scale advantage sits with contract manufacturing aggregators. The market structures around three tiers: ecosystem captives controlling silicon-to-software stacks, component suppliers licensing platform technologies, and white-label assemblers serving price-sensitive geographies. Strategic moves center on API-first control plane exposure and backward integration into NPU silicon design.
Within the ecosystem captive tier, Samsung Electronics and Apple Inc. anchor opposing architecture philosophies—open component licensing versus closed vertical integration. Xiaomi Corporation occupies a position bridging hardware margin compression with internet services monetization. These three exemplify how AI inference capabilities now determine margin capture rather than connectivity specifications alone.
| Leading Market Players |
|---|
| Samsung Electronics |
| Apple Inc. |
| LG Electronics |
| Amazon.com, Inc. |
| Google LLC |
| Xiaomi Corporation |
| Panasonic Corporation |
| Whirlpool |
| GE Appliances |
| Others |
Supply Flow & Price Mechanics
The Shenzhen-Dongguan freight corridor carries component costs that cascade through tiered hardware pricing, compressing margins for commodity producers while concentrating premium capture among ecosystem captives with captive silicon supply. Contract structures and supplier financing terms now determine competitive position as much as technical specifications.
Pricing Analysis
Long-term offtake agreements dominate procurement for AI accelerator silicon, while spot markets govern commodity memory and passive components. Three-tier pricing structure across premium, standard, and economy levels separates Apple-Samsung ecosystem products from Xiaomi volume plays and white-label Shenzhen assemblers. Price differentiation rests on NPU thermal design power and FDA/CE certification tiers. Cost compression in entry-tier smart speakers intensifies because 7-billion-parameter edge AI models raise hardware BOM floors. Healthcare providers show least price sensitivity due to reimbursement code coverage, while Indian tier-3 consumers drive hardest bargain on sub-$50 retrofit kits.
Supply Chain Analysis
Extended payment terms from Taiwan and South Korea foundries now stretch 90-120 days for advanced node capacity, with supply-chain finance facilities bridging working capital gaps for fabless designers. Component sourcing draws from Taiwan for 3nm AI accelerators, South Korea for memory, and China for PCB assembly and passive integration. Raw material dependencies include high-purity silicon wafers, rare earth magnets for acoustic transducers, and cobalt-bearing lithium cells. Single-source vulnerability concentrates in TSMC's leading-edge fabrication. Distribution runs through Amazon-Alibaba platform marketplaces for consumer tiers and direct enterprise sales for healthcare and logistics fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment: FDA 510(k) clearances and EU AI Act compliance cycles create switching costs that filter vendor pools to established players with dedicated regulatory affairs capabilities.
For Market Incumbents: Pre-empt margin erosion in smartphone tiers by backward integration into sub-5-watt NPU silicon design, locking in thermal efficiency advantages that fabless competitors cannot replicate. Accelerate FDA dual-clearance pathways for remote patient monitoring wearables before reimbursement codes solidify around current vendor pools. Threat of Matter protocol commoditization demands channel control through electrician-direct distribution in Germany and France. For New Entrants and Emerging Players: Pursue rural India connectivity gaps with localized firmware for sub-$50 smart home retrofit kits, exploiting BIS certification barriers that filter out uncommitted competitors. Target enterprise logistics wearables where API-first control plane demands disintermediate incumbent software monetization. Go-to-market angle: fleet management integration partnerships with third-party platform licensors rather than vendor-locked dashboards. For Investors and Strategic Acquirers: Edge AI firmware specialists with real-time operating system expertise command scarcity premia as talent pools tighten for sub-100-millisecond latency applications. Long-term viability favors acquirers who can hold positions through 5-10 year regulatory convergence cycles. Signal to watch: EU AI Act enforcement actions against biometric device developers lacking algorithmic audit trails, which will trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| On-Device LLM Inference Integration | 7-billion-parameter models at sub-5-watt TDP eliminate cloud subscription dependencies for Samsung and Chinese OEMs. |
| FDA 510(k) Dual Clearance Pathway | Remote therapeutic monitoring reimbursement codes in United States hospital systems institutionalize procurement through IT departments. |
| Matter Protocol Certification | Thread and Wi-Fi unified commissioning collapses installation friction for electrician-channel distribution in Germany and France. |
| EU AI Act Compliance Engineering | 12-18 month algorithmic audit trail development filters European market entrants to established regulatory affairs capabilities. |
| Renewable Energy Certificate Procurement | Japanese METI carbon labeling mandates create supply chain differentiation for consumer electronics with verified lifecycle emissions. |
Methodological Framework
Desk research of SEC filings, hyperscaler capex disclosures, and FDA 510(k) clearance databases preceded structured interviews with smart home OEM procurement directors, semiconductor foundry account managers, hospital biomedical engineers, and EU regulatory affairs consultants. Bottom-up smartphone and wearable shipment estimates triangulated against top-down connectivity module production data from Taiwan and South Korea. Primary fieldwork validated secondary projections for Matter protocol adoption curves and edge AI silicon thermal design power trajectories.
Assumption sets held fixed the EU AI Act enforcement timeline and United States remote therapeutic monitoring reimbursement expansion while varying China-Taiwan logistics disruption scenarios and Indian broadband infrastructure deployment rates. Segmentation modeling spanned product type, connectivity protocol, application, and end-user procurement authority across the projection horizon. CAGRs derived from replacement cycle compression in on-device AI tiers and retrofit penetration elasticity in suburban United States housing stock.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or healthcare reimbursement policy would shift the trajectory. Forecasts embed assumptions around GB standards enforcement consistency and FCC Part 15 certification backlog resolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Aircraft Sensors Market
Others
Europe Indoor LBS Market
Others
Defense Optronics Market
Others
Global Smartphone ODM Market
Others
Convenience Stores Market
Others
Digital Transformation of Maritime Freight Market
Others
UK Real Estate Hospitality Market
Others
Cat Food Market
Others
Kuwait Retail Market
Others
Healthcare Bioconvergence Market
Others
Synthetic Leather Market
Others
India Battery E-Commerce Market
Others
Durian Market
Others
Global Military Lighting Market
Others
Lepidolite Market
Others
Pin Mills Market