
 Plastic Films and Sheets Market | 2026-2036
Plastic Films and Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Films and Sheets Market Intelligence
The EU Green Deal is expanding the addressable market for recyclable and bio-based plastic films across European packaging supply chains. Sealed Air Corporation leverages its R&D infrastructure to develop barrier films with reduced material intensity. Amcor PLC anchors its position through geographic manufacturing scale across multiple continents. Berry Global Group, Inc. competes on operational breadth in food and healthcare packaging films.
Plastic films and sheets are thin, flexible polymer substrates typically manufactured through blown film extrusion, cast extrusion, or calendering processes, with thickness ranging from below 25 micrometers for ultra-thin films to several millimeters for rigid sheets. These materials serve as protective barriers, structural layers, or functional surfaces across packaging, agriculture, construction, and electronics applications. Polyethylene dominates volume consumption due to its cost efficiency and versatility in flexible packaging, while polyester commands premium positioning in electronics and high-barrier applications where dimensional stability and optical clarity matter. The biodegradable feature segment is gaining structural importance as brand owners and retailers impose circularity mandates on suppliers.
The EPA regulates volatile organic compound emissions from film extrusion operations under Clean Air Act provisions, while the FDA maintains material contact safety standards for food packaging films in the United States. REACH and the EU Packaging and Packaging Waste Regulation constrain substance composition and end-of-life treatment requirements for films sold in European markets. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical recycling infrastructure investments to align product portfolios with compliance trajectories and circular economy targets.
Market Dynamics
REACH compliance and the EU Packaging and Packaging Waste Regulation are forcing resin substitution across European supply chains, while Chinese agricultural film demand pulls capacity toward Asia-Pacific extrusion assets.
Growth Catalysts
- Food packaging modernization:Fresh produce distributors in China and India are converting from rigid containers to flexible barrier films for shelf-life extension and logistics efficiency.
- EU Green Deal circularity mandates:The European Commission's packaging waste targets are accelerating mechanical recycling infrastructure investment and bio-based polymer qualification programs.
- Agricultural film intensity:Greenhouse cultivation expansion in Shandong Province and Gujarat State is consuming multi-season UV-stabilized polyethylene films at scale.
Market Restraints
- Naphtha feedstock volatility:European crackers dependent on naphtha rather than ethane face margin compression when oil prices spike, constraining film-grade polyethylene output.
- Mechanical recycling contamination limits:Multi-layer barrier structures containing EVOH or aluminum metallization cannot enter current mechanical recycling streams, creating end-of-life liability.
- Paperboard substitution in premium segments:Cosmetic and electronics brands in Germany and France are switching to molded fiber and paper-based packaging for perceived sustainability differentiation.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization investments in the Netherlands and Belgium will enable food-contact recycled content certification previously blocked by mechanical recycling quality limits.
- Healthcare barrier films:Sterile medical device packaging in the United States and Japan is converting from Tyvek to high-performance coextruded films for cost and puncture resistance.
- Smart packaging integration:Printed electronics and time-temperature indicators are converging with flexible substrates, creating sensor-enabled food safety solutions for cold chain monitoring.
Industry Challenges
- Compostable certification timelines:Industrial compostable films require 180-day biodegradation validation under EN 13432, delaying product launches by 12-18 months versus conventional alternatives.
- Extrusion technician scarcity:Blown film line operators with thickness gauge control and die adjustment expertise are retiring faster than vocational programs in the United States and Germany can replace them.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Films and Sheets Market |
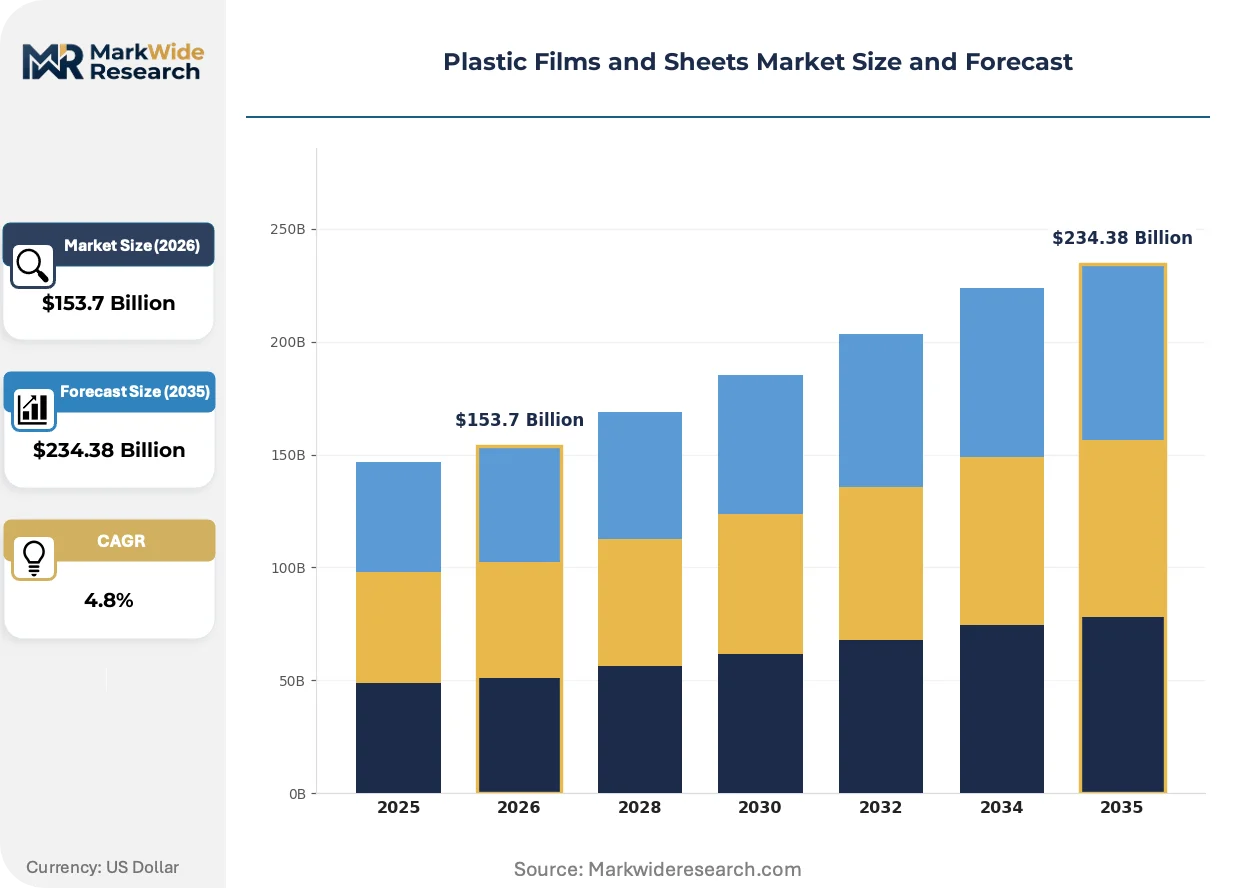
| Market Size in 2026 | $153.7 Billion |
| Market Size in 2035 | $234.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester End Use Industry: Packaging, Agriculture, Construction, Electronics Thickness: Thin Films, Thick Sheets, Medium Thickness, Ultra-Thin Films Feature: Biodegradable, Barrier, Antimicrobial, Transparent |
| Companies Covered | Sealed Air Corporation, SABIC, Amcor PLC, Toyobo Co., Ltd., Uflex Limited, Berry Global Group, Inc., Toray Industries, Inc., DuPont Teijin Films, Jindal Poly Films Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Films and Sheets Market Strategic Shifts & Innovations
Digital process control and regulatory chemistry restrictions are converging to redefine how film producers compete on specification compliance and unit economics.
Machine vision and closed-loop gauge control systems are automating thickness uniformity in blown film extrusion. Major flexible packaging converters in the United States and Germany are retrofitting legacy lines with real-time profile measurement and automatic die adjustment. This technology is automating quality assurance labor and compressing resin giveaway to sub-2% tolerance bands.
The EU Packaging and Packaging Waste Regulation is mandating recyclability-by-design criteria and extended producer responsibility fee modulation based on recyclability scores. Film producers serving European markets must now eliminate incompatible adhesives and standardize polymer families to avoid penalty tariffs. Food brands in France and Italy are responding by simplifying multi-layer structures and qualifying mono-material alternatives.
Brand owners are consolidating supplier bases and demanding recycled content certificates with mass-balance chain of custody documentation. Large retail chains in Germany and the United Kingdom are replacing fragmented regional film sourcing with national framework agreements tied to circularity KPIs. This concentration is visible in the rapid qualification of post-consumer recycled polyethylene suppliers for private-label packaging programs.
Plastic Films and Sheets Market Segmentation
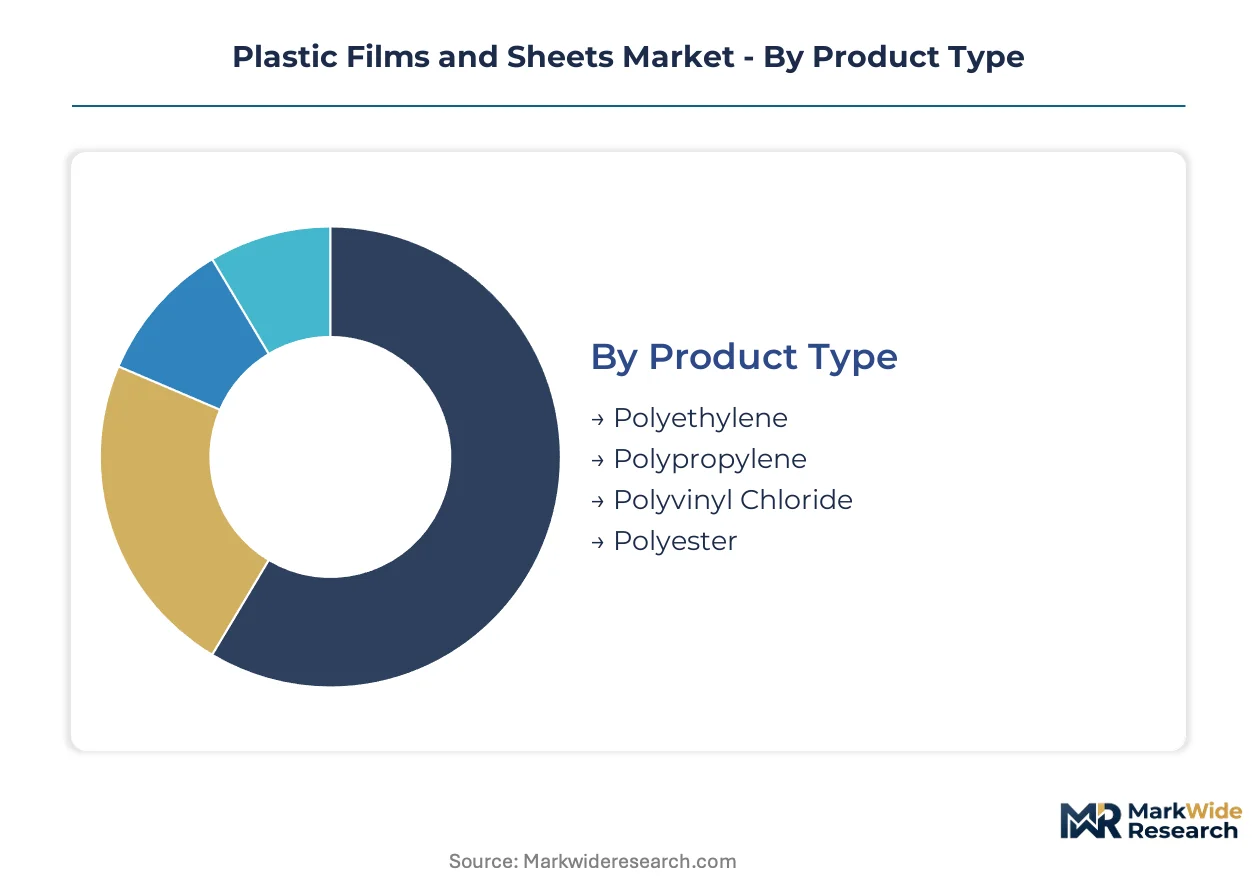
Plastic films and sheets serve divergent performance requirements across packaging durability, agricultural longevity, and electronics precision. Buyers select materials based on barrier properties, mechanical strength, and regulatory compliance rather than commodity pricing alone.
Product Type:
Resin selection separates cost-driven commodity buyers from specification-driven premium purchasers.
- Polyethylene:Linear low-density and high-density grades dominate flexible packaging through blown film extrusion. Chinese fresh produce distributors and Indian retail chains are converting rigid containers to LLDPE barrier films for logistics efficiency and shelf-life extension.
- Polypropylene:Biaxially oriented films deliver stiffness and clarity for snack food lamination and label facestock. Cast PP films are displacing PVC in pharmaceutical blister packs across German and Italian manufacturing sites due to recyclability mandates.
- Polyvinyl Chloride:Rigid calendered sheets serve construction glazing and stationery applications with cost advantages over polyester.
- Polyester:PET films command premium positioning in electronics substrates and high-barrier food packaging where dimensional stability and optical clarity are non-negotiable.
Volume sits with Polyethylene; growth tilts toward Polyester.
End Use Industry:
Application maturity determines whether buyers prioritize unit economics or compliance certification.
- Packaging:Flexible food packaging consumes the majority of film extrusion output, with fresh produce, meat, and dairy driving multi-layer barrier specifications. EU Green Deal circularity mandates are forcing simplification of multi-layer structures toward mono-material alternatives.
- Agriculture:Greenhouse cultivation in Shandong Province and Gujarat State consumes UV-stabilized polyethylene films for multi-season durability. Soil fumigation films and silage wraps add seasonal demand spikes.
- Construction:Vapor barriers, geomembranes, and temporary protective films serve building envelopes and civil engineering projects with thickness requirements from 100 micrometers to several millimeters.
- Electronics:Release films, flexible circuit substrates, and display optical films require cleanroom manufacturing and tight thickness tolerances that command 3-5x commodity film pricing.
Revenue concentrates in Packaging; margin expansion is steepest in Electronics.
Thickness:
Gauge specification correlates directly with processing equipment investment and end-use performance thresholds.
- Thin Films:Below 50 micrometers, these substrates serve lightweight packaging and overwrap applications where material yield per kilogram drives procurement decisions.
- Thick Sheets:Above 500 micrometers, rigid sheets serve thermoformed trays, signage, and construction protection where impact resistance outweighs flexibility requirements.
- Medium Thickness:The 50-500 micrometer range captures the majority of industrial films including agricultural mulch, industrial liners, and heavy-duty sacks.
- Ultra-Thin Films:Sub-25 micrometer films enable downgauging initiatives in snack packaging and battery separator applications where micron-level uniformity determines performance.
Equipment utilization favors Medium Thickness; technology investment flows toward Ultra-Thin Films.
Feature:
Functional additives and material chemistry separate compliance-driven from performance-driven purchasing.
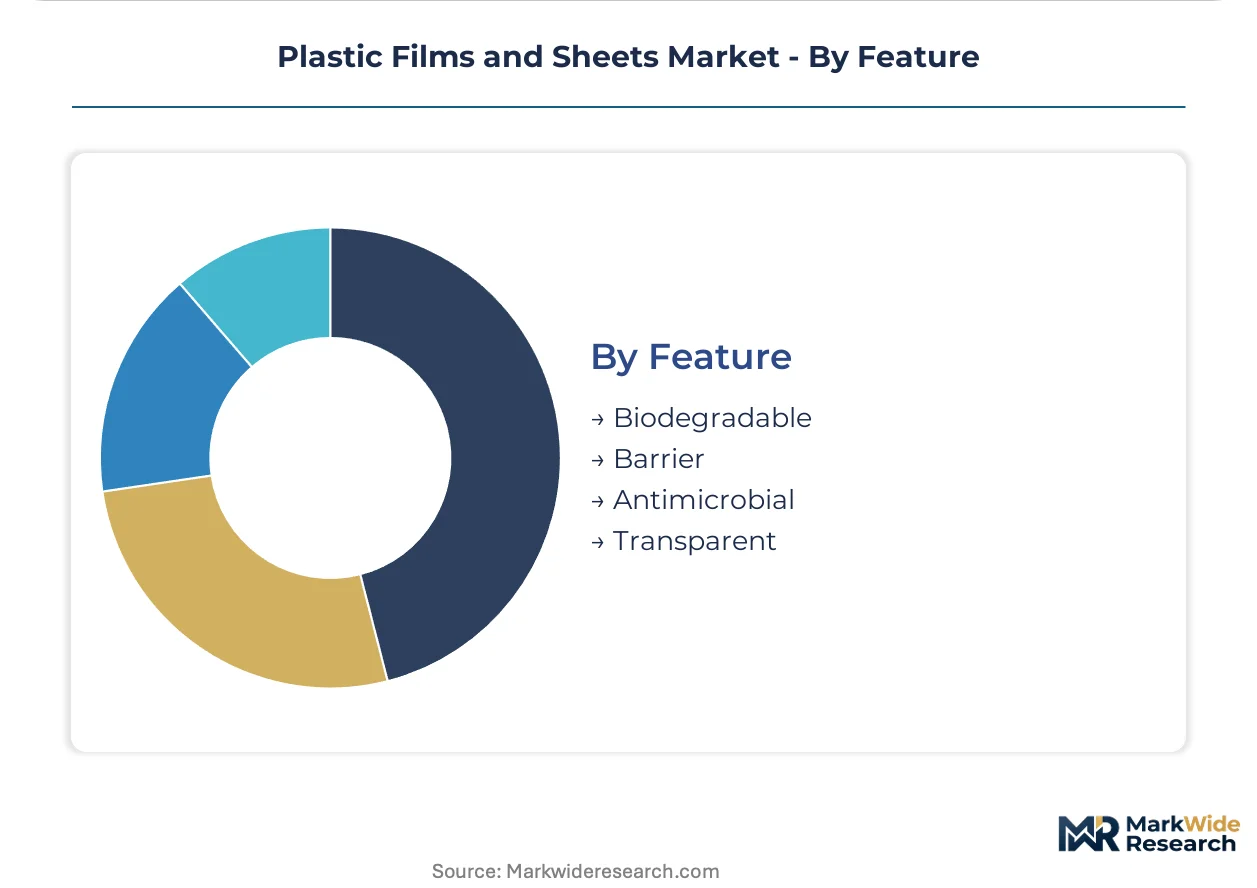
- Biodegradable:PLA and starch-based films require industrial composting infrastructure and EN 13432 certification, delaying product launches 12-18 months versus conventional alternatives. French and Italian food brands are qualifying these for private-label circularity commitments.
- Barrier:EVOH and metallized layers extend shelf life in meat and cheese packaging. Multi-layer structures containing these materials face mechanical recycling contamination limits, creating end-of-life liability under extended producer responsibility frameworks.
- Antimicrobial:Silver-ion and organic additive films serve healthcare packaging and food contact surfaces where surface bioburden reduction is specified.
- Transparent:Optical-grade clarity films serve display applications, food retail presentation, and medical device packaging where visual inspection is required.
Current volume rests with Barrier; qualification activity is expanding most quickly in Biodegradable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China extrudes more polyethylene film than any other nation, yet Germany and the United States still anchor premium specification development. This production-consumption divide shapes where capacity expands versus where margins concentrate.
China
Shandong Province and Jiangsu Province house the densest clusters of blown film extrusion lines serving fresh produce logistics and agricultural greenhouse demand. The Ministry of Ecology and Environment enforces stricter plastic pollution action plans that phase out non-degradable mulch films by 2025. Qingdao and Weifang manufacturers are retrofitting lines for UV-stabilized multi-season films that meet the new biodegradability mandates.
Germany
Flexible packaging converters in North Rhine-Westphalia supply meat and dairy barrier films across the EU single market. REACH compliance and the EU Packaging and Packaging Waste Regulation force resin substitution toward mono-material structures eligible for mechanical recycling. The Düsseldorf-Cologne corridor hosts chemical recycling pilot plants that will depolymerize multi-layer waste into food-contact certified feedstock.
United States
Midwest flexible packaging plants in Illinois and Wisconsin serve protein processors and retail private-label programs. The FDA maintains material contact safety standards while the EPA regulates volatile organic compound emissions from extrusion operations under Clean Air Act provisions. Chicago-area converters are automating blown film lines with machine vision gauge control to compress resin giveaway below two percent tolerance bands.
India
Gujarat State and Maharashtra dominate domestic film consumption for agricultural mulch and retail carry bags. The Bureau of Indian Standards mandates thickness minimums for plastic carry bags while state-level bans on single-use items accelerate bio-based film qualification. Ahmedabad and Mumbai extruders are scaling cast polypropylene lines to displace PVC in pharmaceutical blister packs.
Japan
Electronics-grade polyester film production concentrates in Shiga Prefecture and Aichi Prefecture for display optical films and flexible circuit substrates. METI promotes domestic supply chain resilience for semiconductor materials through subsidy programs. The Nagoya industrial corridor maintains cleanroom manufacturing capabilities that command three-to-five times commodity film pricing.
Plastic Films and Sheets Market Key Industry Players
The competitive structure tilts toward diversified packaging conglomerates with geographic manufacturing scale. Tier-one players anchor positions through backward integration into resin supply and forward integration into converting equipment. Three archetypes dominate: multinational material science firms with polymer research depth, regional flexible packaging specialists with customer intimacy, and diversified industrial conglomerates with extrusion asset breadth. Consolidation through acquisition and capacity relocation toward Asian demand centers represent the dominant competitive moves.
Among multinational packaging specialists, Sealed Air Corporation, Amcor PLC, and Berry Global Group, Inc. occupy positions that exemplify scale-driven and specification-driven archetypes respectively. Sealed Air represents the technology-intensive vector with barrier film development infrastructure. Amcor anchors geographic diversification across multiple continents. Berry Global sits within the operational breadth tier serving food and healthcare packaging films. These three illustrate how competitive positioning separates resin efficiency from compliance certification capabilities.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| SABIC |
| Amcor PLC |
| Toyobo Co., Ltd. |
| Uflex Limited |
| Berry Global Group, Inc. |
| Toray Industries, Inc. |
| DuPont Teijin Films |
| Jindal Poly Films Limited |
| Others |
Cost & Logistics Intelligence
Backward integration into resin production anchors both supply security and margin control for major film extruders serving European packaging markets. Producers with captive polyethylene supply command pricing power when naphtha feedstock volatility squeezes merchant resin margins, while converters dependent on spot purchases face cost pass-through delays that erode profitability.
Pricing Analysis
Cost-down pressure on commodity-grade polyethylene film accelerates because Chinese agricultural buyers and Indian retail chains negotiate volume tenders against excess regional capacity. Three-tier pricing structure across premium barrier, standard multi-layer, and economy mono-material levels separates food-contact certified films from industrial-grade alternatives. Certification under EU REACH and FDA food-contact standards commands 15-25 percent premiums over uncertified equivalents. Brand owners in Germany and France exhibit lowest price sensitivity for circularity-compliant films, while Asian agricultural distributors drive hardest bargain on UV-stabilized greenhouse films.
Supply Chain Analysis
Reverse logistics for post-industrial film scrap and post-consumer agricultural mulch flows through mechanical reprocessing hubs in Germany and emerging pyrolysis facilities in the Netherlands. Raw material supply concentrates in China, Saudi Arabia, and the United States for polyethylene resin, with biaxially oriented polypropylene feedstock anchored in South Korea and Thailand. European extruders face single-source vulnerability for EVOH barrier resins sourced primarily from Japanese and Belgian producers. Distribution runs through national flexible packaging converters who hold framework agreements with retail chains, consolidating fragmented regional sourcing into centralized procurement pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive survival in plastic films and sheets hinges on vertical-integration depth, with upstream resin security and downstream converting control separating margin leaders from price-takers.
For Market Incumbents: Deepen captive resin supply through offtake agreements with Middle Eastern crackers or European chemical recycling ventures to insulate against naphtha cost spikes. Consolidate regional converting assets in North Rhine-Westphalia and Illinois to capture scale efficiencies and defend against Asian import competition in standard-grade films. For New Entrants and Emerging Players: Chemical recycling technology licensing offers entry into food-contact recycled content certification previously blocked to mechanical recyclers. Target biodegradable film qualification for French and Italian private-label programs where EN 13432 compliance creates 12-18 month qualification barriers for established players. Partner with agricultural cooperatives in Gujarat and Shandong for direct-to-grower distribution bypassing incumbent converter networks. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty barrier film developers with healthcare and electronics certifications that command acquisition premiums over commodity packaging assets. Long-term viability favors producers with demonstrated chemical recycling feedstock access and mass-balance chain-of-custody infrastructure. Monitor EU Packaging and Packaging Waste Regulation enforcement timelines as inflection signal for recyclability-by-design investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyethylene feedstock from Saudi crackers insulates European extruders from naphtha volatility. |
| Chemical Recycling Scale-Up | Pyrolysis investments in Rotterdam and Antwerp unlock food-contact recycled content certification. |
| Mono-Material Structure Simplification | EVOH elimination enables mechanical recycling compliance under EU extended producer responsibility. |
| Healthcare Barrier Film Qualification | Tyvek replacement in sterile medical packaging commands 3-5x commodity film pricing in US and Japan. |
| Smart Packaging Integration | Printed electronics convergence with flexible substrates creates sensor-enabled cold chain monitoring solutions. |
Research Approach
Document review covered trade customs databases, SEC 10-K filings, and EU regulatory submissions, complemented by interviews with blown film plant managers, flexible packaging procurement leads, agricultural distributor category buyers, and chemical recycling technology developers. Primary fieldwork across North Rhine-Westphalia, Illinois, and Shandong Province validated secondary data on extrusion capacity utilization and resin sourcing patterns. Bottom-up volume estimates from individual production lines triangulated against top-down resin consumption figures from industry associations.
Segment-level projections across resin type, end-use industry, thickness category, and functional feature were generated through elasticity modeling of substitution patterns and regulatory compliance timelines. CAGRs were derived from regression analysis of historical capacity additions correlated with agricultural greenhouse expansion and food packaging modernization rates. Forecast inputs incorporated UV-stabilizer additive cost curves, mechanical recycling contamination limits, and bio-based polymer qualification delays.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt oil price shocks or accelerated EU single-use plastic bans. Practitioners should monitor chemical recycling food-contact approval timelines and Chinese agricultural film biodegradability mandate enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Enterprise Video Market
Others
Hotel Wardrobe Market
Others
Gym Wipes Market
Others
Receiving Scales Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Taiwan Retail Market
Others
DNA Data Storage Market
Others
Pet Care Packaging Market
Others
Video Conferencing Hardware Market
Others
Global Lavender Extracts Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Wind and Solar Hybrid Street Light Market
Others
Global Cigarette Packaging Market
Others
Smart Home and Office Market
Others
Global Application Testing Services Market
Others
Land Surveying Equipment Market