
 Global Compact Wheel Loaders Market | 2026-2036
Global Compact Wheel Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Compact Wheel Loaders Market Intelligence
The integration of electric powertrains and advanced telematics is reconfiguring the design and operational capabilities of compact wheel loaders. Caterpillar Inc. leverages its extensive global dealer network to support both diesel and emerging electric models. Komatsu Ltd. specializes in hydraulic system efficiency and automated controls to improve job site productivity. Wacker Neuson SE competes by focusing on the zero-emission equipment segment for sensitive urban construction sites.
Compact wheel loaders are versatile earth-moving machines, typically defined by an operating weight under 20,000 pounds and engine power below 100 horsepower. Their primary industrial purpose is material handling, loading, and transport in confined spaces where larger equipment cannot operate efficiently. Articulated product types command a significant share due to superior maneuverability in tight job sites. While construction sites remain the dominant application, the agriculture fields segment represents a key growth opportunity.
Engine technology is directly influenced by emissions standards such as the EPA's Tier 4 Final in the United States and Stage V regulations in Europe. These mandates push manufacturers toward cleaner diesel and alternative powertrains like electric motors. In China, similar national standards also shape available powertrain options. Equipment owners must now weigh the total cost of ownership for electric models against the established service infrastructure for diesel fleets.
Market Dynamics
The convergence of stringent emissions regulations and advancements in battery technology constitutes the central structural force shaping the compact wheel loader market. This dynamic compels manufacturers to re-engineer powertrains, shifting investment from diesel optimization to full electrification for urban applications.
Growth Catalysts
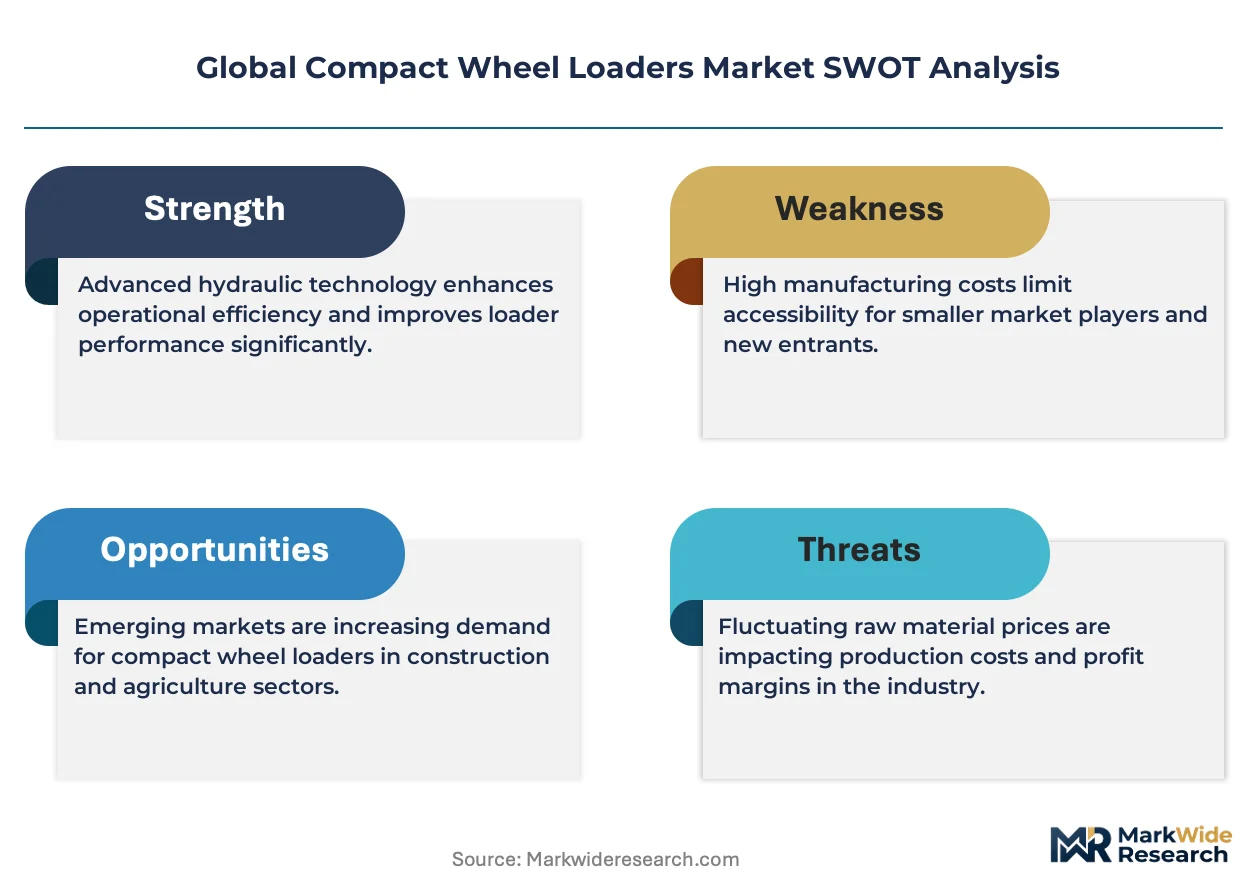
- Urban Renewal Projects:Concentrated demand from large-scale urban redevelopment and infrastructure projects in North American and European cities provides a consistent pipeline for compact equipment used in confined job sites.
- Emissions Regulations:Mandates such as Europe's Stage V and the EPA's Tier 4 Final create a non-negotiable incentive for fleet owners to adopt cleaner diesel or zero-emission electric models to maintain compliance.
- Agricultural Modernization:The agriculture fields segment is adopting compact wheel loaders for tasks like material handling and feed management, representing a significant expansion beyond traditional construction applications.
Market Restraints
- High Initial Capital Outlay:The purchase price for electric compact wheel loaders remains substantially higher than for comparable diesel models, presenting a significant barrier to adoption for smaller contractors and rental companies.
- Charging Infrastructure Deficit:A lack of standardized, high-capacity charging infrastructure on construction and agricultural sites limits the practical operational range and uptime for battery-electric equipment.
- Threat of Substitution:In certain applications, compact track loaders and telehandlers offer overlapping capabilities with superior reach or traction, posing a direct substitution threat for specific material handling tasks.
Strategic Opportunities
- Integrated Telematics Services:Manufacturers can develop subscription-based services around advanced telematics, offering fleet management, predictive maintenance, and operational efficiency analytics as a new revenue stream.
- Battery-as-a-Service Models:Offering batteries on a lease or subscription basis can significantly lower the initial purchase price of electric loaders, accelerating adoption by de-risking the technology for buyers.
- Autonomous Operation in Controlled Environments:Developing autonomous or remote-controlled loaders for repetitive tasks in controlled environments like nurseries or feedlots opens a new high-value application segment.
Industry Challenges
- Service Technician Skill Gaps:The transition to electric powertrains and complex onboard electronics requires significant retraining of dealer and independent service technicians who are traditionally skilled in diesel mechanics and hydraulics.
- Battery Supply Chain Volatility:Securing a stable and cost-effective supply of lithium-ion battery cells and packs is a major challenge, exposing manufacturers to price fluctuations and geopolitical supply risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Compact Wheel Loaders Market |
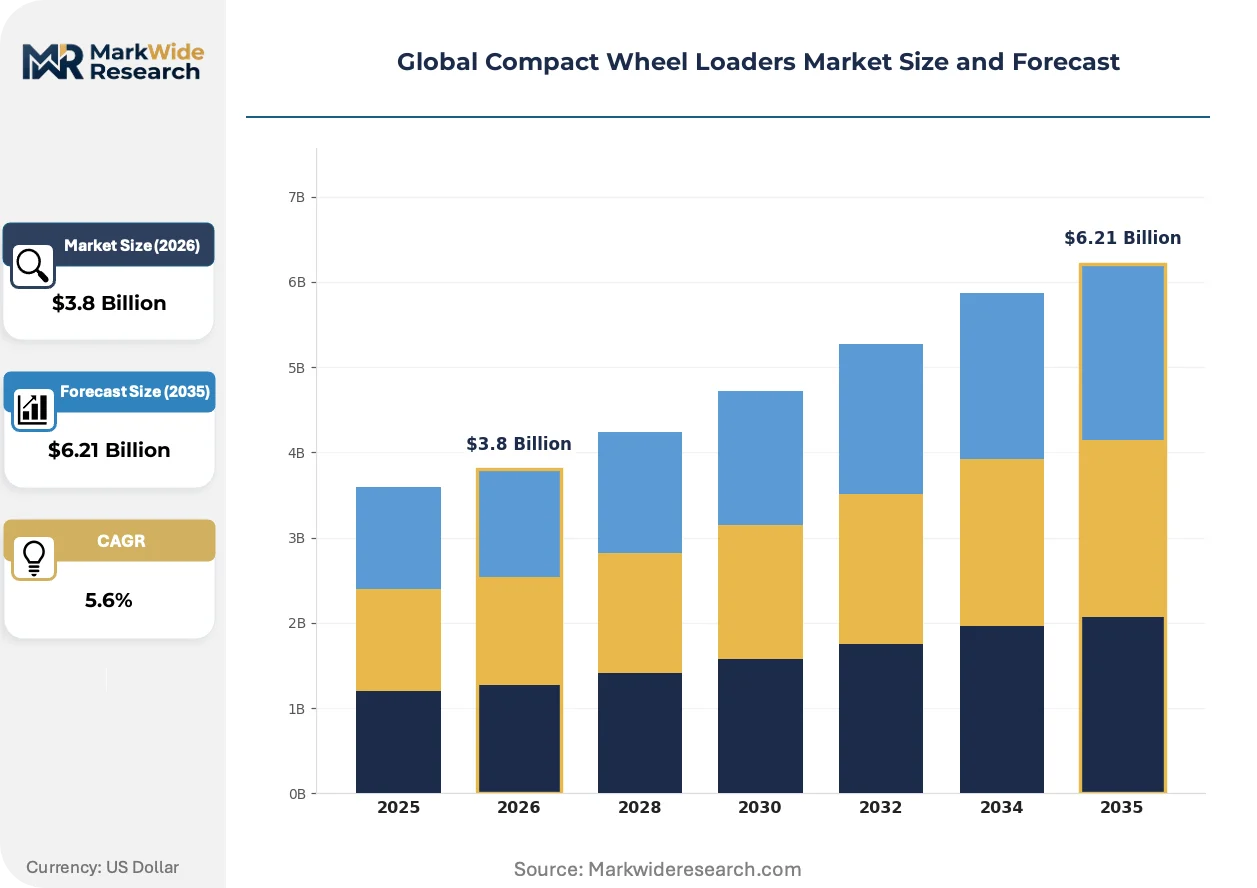
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated, Rigid Frame, Skid Steer, Backhoe Loader, Track Loader Technology: Diesel Engine, Electric Motor, Hybrid Powertrain, Hydraulic System, Automated Controls Application: Construction Sites, Agriculture Fields, Landscaping, Material Handling, Road Maintenance End User Industry: Building Contractors, Agricultural Operators, Landscaping Firms, Municipal Services, Mining Companies |
| Companies Covered | Komatsu Ltd., Kubota Corporation, Caterpillar Inc., Liebherr Group, Wacker Neuson SE, Deere & Company, Volvo Construction Equipment, J.C. Bamford Excavators Limited, CNH Industrial N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Compact Wheel Loaders Market Strategic Shifts & Innovations
The dual evolution toward electrification and advanced digitalization is reconfiguring the fundamental design, operational economics, and service models for compact wheel loaders. This shift moves the competitive focus from mechanical power to intelligent, zero-emission performance in sensitive environments.
Advanced telematics systems provide real-time data on equipment location, fuel consumption, and diagnostic fault codes. Large fleet owners in the construction and rental sectors are the primary adopters, seeking to maximize asset utilization and reduce downtime. The market's value proposition is migrating from raw machine performance toward total operational efficiency and uptime, which data analytics directly enables.
European Union regulations, particularly the Stage V emissions standards under the Green Deal framework, set stringent limits on particulate matter and NOx from off-road machinery. This directly compels manufacturers to accelerate investment in both advanced diesel after-treatment systems and battery-electric powertrains. Consequently, the zero-emission equipment segment sees heightened product development activity for use in urban low-emission zones.
Rental agreements are increasingly supplanting direct equipment ownership, especially among small to mid-sized contractors. This trend shifts the primary customer for manufacturers from the end-user to large, national rental fleet companies, altering sales cycles and support requirements. This procurement model is most advanced in the mature equipment rental markets of North America and Western Europe.
Global Compact Wheel Loaders Market Segmentation
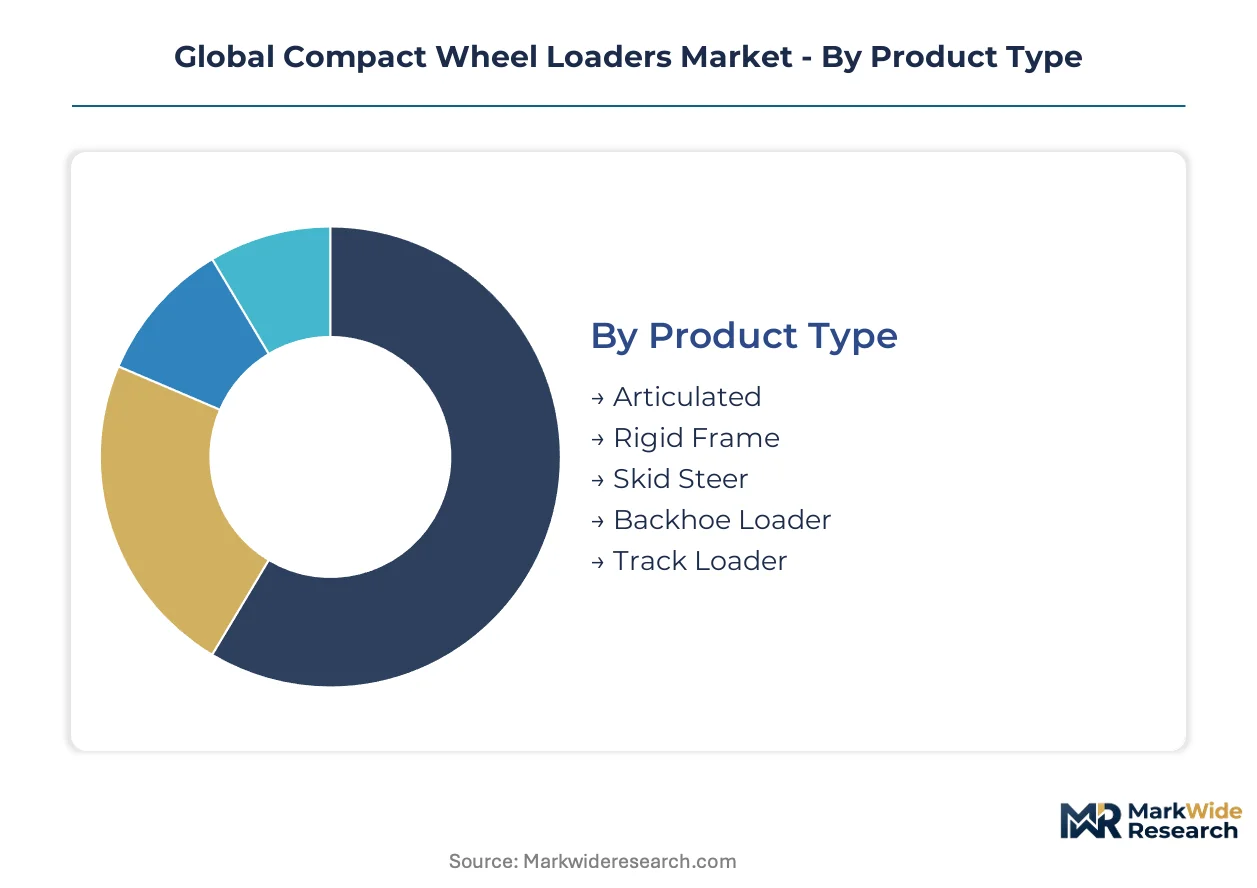
The compact wheel loaders market segments reflect distinct design philosophies, technological advancements, and end-user requirements. Understanding these segments is critical for manufacturers to tailor product development and for fleet owners to optimize procurement strategies for specific operational contexts.
Product Type:
Product types exhibit varying replacement cycles, with some models seeing faster turnover due to intense usage patterns or technological obsolescence.
- Articulated:Articulated compact wheel loaders feature a pivot point between the front and rear axles, allowing for exceptional steering flexibility and a tight turning radius. Demand concentrates in European urban renewal projects, where maneuverability in confined spaces is critical for material placement.
- Rigid Frame:Rigid frame loaders offer a robust, unarticulated chassis, providing stability for heavy lifting and demanding tasks, though with less maneuverability. These models maintain a steady presence in industrial material handling facilities.
- Skid Steer:Skid steer loaders are compact machines with a rigid frame and independent wheel speed control, enabling zero-radius turning for extreme agility. Landscaping firms in the United States frequently utilize these for precise site work.
- Backhoe Loader:Backhoe loaders combine a loader bucket on the front and a backhoe on the rear, offering dual functionality for digging and loading tasks. Small to mid-sized construction companies often prefer their versatility.
- Track Loader:Track loaders utilize continuous tracks instead of wheels, providing superior traction and stability on uneven or soft terrain. Adoption is accelerating among North American landscaping firms for site preparation tasks requiring minimal ground disturbance.
Articulated product types dominate the installed base. Track loaders represent the fastest-growing trajectory.
Technology:
Technology segments differentiate by initial investment costs and long-term operational expenditures, influencing fleet owner procurement decisions.
- Diesel Engine:Diesel engines remain the traditional power source, offering robust performance and established refueling infrastructure for heavy-duty applications. Their widespread use continues across construction sites in North America, supported by a mature service network.
- Electric Motor:Electric motors provide zero-emission operation and significantly reduced noise levels, making them ideal for sensitive urban environments and indoor applications. Demand is concentrating in European cities, driven by stringent EU Green Deal emissions regulations.
- Hybrid Powertrain:Hybrid powertrains combine diesel engines with electric motors, optimizing fuel efficiency and reducing emissions for varied operational demands. Manufacturers are investing in these systems for markets with evolving emissions standards.
- Hydraulic System:Advanced hydraulic systems optimize power delivery and implement automated controls, improving machine responsiveness and fuel efficiency. Komatsu Ltd. specializes in these systems to enhance job site productivity.
- Automated Controls:Automated controls integrate sensors and software to assist operators with repetitive tasks, improving precision and reducing operator fatigue. These systems are gaining traction in large-scale material handling operations.
Diesel Engine technology maintains the largest operational footprint. Electric Motor technology is gaining share fastest as regulatory pressures intensify.
Application:
Application segments highlight diverse operational requirements, from heavy-duty construction tasks to specialized agricultural material handling.
- Construction Sites:Construction sites represent the primary application for compact wheel loaders, involving tasks like excavation, grading, and material transport. Urban renewal projects in major North American cities drive consistent demand for these versatile machines.
- Agriculture Fields:Agriculture fields increasingly utilize compact wheel loaders for tasks such as feed distribution, bale handling, and general farm maintenance. Modernization efforts in European agricultural operations are expanding this segment's uptake.
- Landscaping:Landscaping applications involve moving soil, mulch, and other materials, as well as light grading and site preparation. Landscaping firms depend on compact wheel loaders for efficiency in diverse outdoor settings.
- Material Handling:General material handling applications, including loading trucks and stacking pallets, leverage the lifting and carrying capabilities of these machines. Warehouses and industrial facilities often deploy them for internal logistics.
- Road Maintenance:Road maintenance tasks, such as clearing debris, loading asphalt, and small-scale excavation, utilize compact wheel loaders for their maneuverability and power. Municipal services find these machines essential for local infrastructure upkeep.
Construction Sites account for the majority of compact wheel loader deployments. Agriculture Fields exhibit the steepest expansion trajectory.
End User Industry:
End user industries categorize demand patterns based on specific operational needs and procurement strategies.
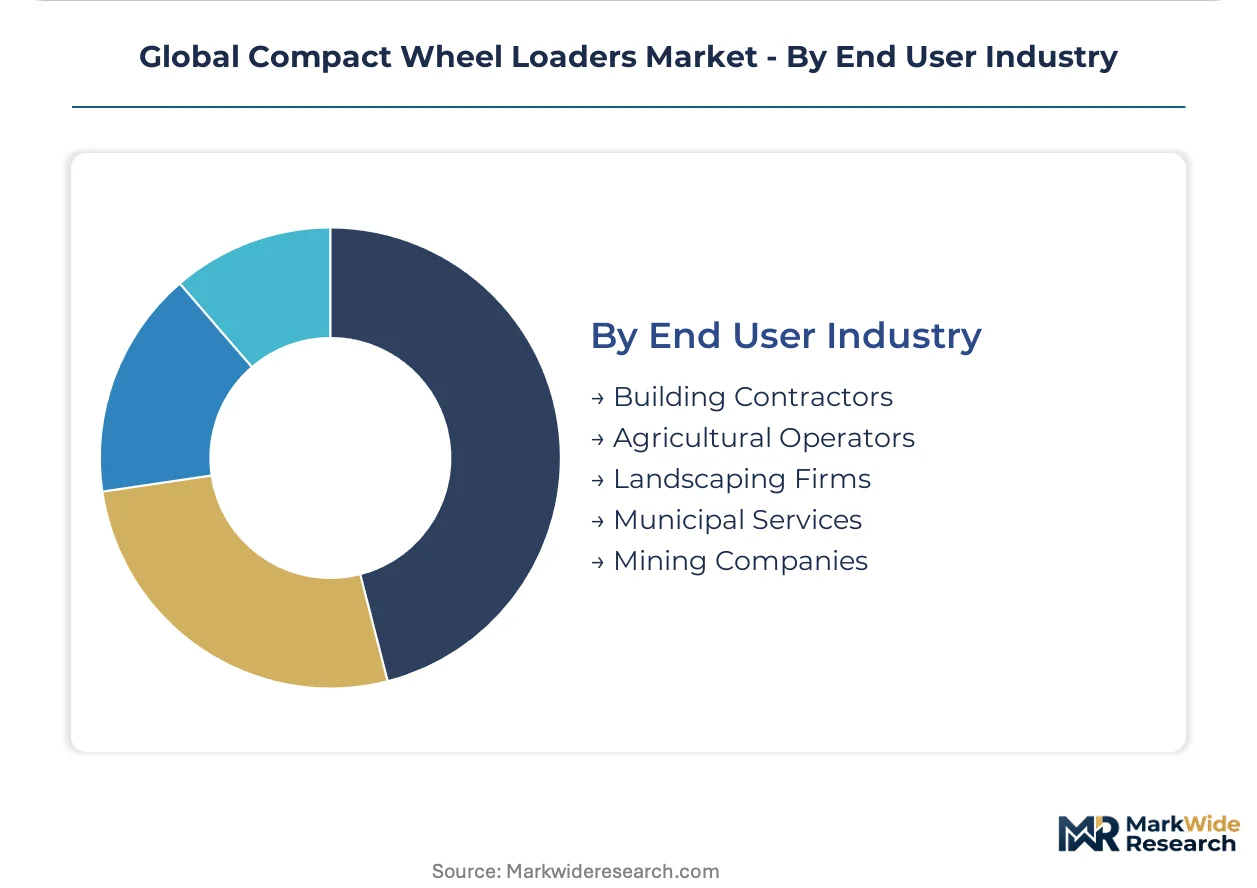
- Building Contractors:Building contractors represent a significant end-user group, deploying compact wheel loaders for site preparation, material loading, and general earth-moving tasks. Their demand is concentrated in residential and commercial development projects across North America.
- Agricultural Operators:Agricultural operators increasingly rely on compact wheel loaders for efficient material handling, such as silage and grain management, within farm operations. European agricultural modernization initiatives are driving their procurement of these machines.
- Landscaping Firms:Landscaping firms use compact wheel loaders for tasks like moving soil, mulch, and stones, as well as for light grading on commercial and residential properties. These firms value the machines' compact size and versatility.
- Municipal Services:Municipal services utilize compact wheel loaders for public works projects, including road maintenance, snow removal, and waste management. Local governments acquire these machines for their diverse utility in urban environments.
- Mining Companies:Mining companies deploy compact wheel loaders for specific tasks like underground material transport and tunnel maintenance, where larger equipment cannot operate effectively. These applications require robust and often specialized models.
Building Contractors form the largest customer base. Agricultural Operators are expanding their fleet acquisitions most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers from Europe frequently supply advanced compact wheel loaders to North American construction and landscaping sectors, reflecting established trade flows and shared regulatory drivers. This global market sees distinct regional demands shaped by infrastructure development, emissions mandates, and agricultural modernization initiatives.
United States
The United States experiences consistent demand for compact wheel loaders in urban renewal projects and among landscaping firms. EPA's Tier 4 Final emissions standards drive the adoption of cleaner diesel and electric models. Major cities like New York and Los Angeles see concentrated demand for maneuverable equipment in confined job sites.
Germany
German construction and agricultural sectors represent a significant market for compact wheel loaders, particularly zero-emission models for sensitive urban environments. The EU Green Deal and Stage V emissions standards compel operators towards electric powertrains. Cities such as Berlin and Munich deploy quiet, emission-free equipment for infrastructure projects.
China
China's robust infrastructure development and expanding construction industry fuel demand for compact wheel loaders in material handling and earth-moving tasks. National emissions standards influence powertrain options available in the market. Large urban centers like Shanghai and Beijing adopt these machines for versatility in dense construction zones.
India
India's rapid urbanization and ongoing infrastructure projects create substantial demand for compact wheel loaders. Government focus on cleaner construction practices pushes for compliance with evolving national emissions norms. Metropolitan areas like Mumbai and Delhi are key demand centers for efficient material handling equipment.
Canada
Canadian mining companies deploy compact wheel loaders for specialized underground material transport and tunnel maintenance. Federal and provincial emissions regulations influence fleet procurement towards cleaner options. Urban centers like Toronto and Vancouver utilize these machines for diverse construction and road maintenance tasks.
Global Compact Wheel Loaders Market Key Industry Players
On the supply side, the industry is moderately consolidated, characterized by a mix of established global conglomerates and specialized equipment manufacturers. These players often compete by differentiating their product portfolios across diesel and electric powertrains. Key strategic archetypes include full-line providers, niche zero-emission specialists, and regional players focusing on specific application segments. Competitive moves center on new product development, leveraging extensive dealer networks, and strategic partnerships for technology advancement.
Leading global equipment manufacturers, such as Caterpillar Inc., exemplify the full-line provider archetype, offering extensive product ranges and leveraging vast dealer networks for both traditional diesel and emerging electric models. Komatsu Ltd. sits within the specialized segment focusing on hydraulic system efficiency and automated controls to enhance job site productivity. Wacker Neuson SE anchors the zero-emission equipment segment, catering to sensitive urban construction sites and driving product development in battery-electric solutions.
| Leading Market Players |
|---|
| Komatsu Ltd. |
| Kubota Corporation |
| Caterpillar Inc. |
| Liebherr Group |
| Wacker Neuson SE |
| Deere & Company |
| Volvo Construction Equipment |
| J.C. Bamford Excavators Limited |
| CNH Industrial N.V. |
| Others |
Cost & Logistics Intelligence
Under-capacity in battery cell production for off-road equipment drives supplier behavior and influences pricing posture for electric compact wheel loaders. This dynamic forces manufacturers to secure long-term supply agreements and manage cost volatility for critical components.
Pricing Analysis
The technology-generation pricing gap between electric and diesel models significantly impacts fleet procurement decisions. Per-unit transactional pricing remains the dominant model for compact wheel loaders. Price differentiation stems from brand premium and the inclusion of advanced telematics services. Pricing softness reflects the higher initial capital outlay for electric models, creating pressure on manufacturers. Smaller contractors and rental companies represent the most price-sensitive buyer segments, while large infrastructure project consortia are less sensitive to upfront costs.
Supply Chain Analysis
Battery supply chain volatility, particularly for lithium-ion cells, presents a significant structural risk for electric compact wheel loader manufacturers. Geographic supply concentration for these cells centers on China, South Korea, and Japan. Key component dependencies include electric motors, power electronics, and advanced hydraulic systems. The dominant downstream distribution model runs through established dealer networks, which also provide crucial after-sales service and parts support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmented demand from diverse applications like landscaping and agriculture creates a significant fragmentation opportunity within the compact wheel loader market, enabling specialized product development.
For Market Incumbents: Pre-empt emerging competitive threats from specialized zero-emission equipment manufacturers by accelerating investment in electric powertrain R&D. Consolidate market share through strategic acquisitions of technology firms specializing in battery management systems or autonomous controls. Leverage extensive dealer networks to provide comprehensive training for electric model maintenance, addressing the service technician skill gap.
For New Entrants and Emerging Players: Pursue white-space opportunities in specific application segments like specialized agricultural operations or sensitive urban construction sites. Target the European market, which exhibits the most penetrable segment for zero-emission equipment due to stringent regulations. A go-to-market angle focused on Battery-as-a-Service models can significantly lower adoption barriers for smaller firms.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the electric compact wheel loader sub-segment, driven by battery manufacturing and advanced R&D. The long-term viability favors firms with robust intellectual property in electric powertrains and telematics. Target acquisition archetypes include specialized component suppliers or software developers for autonomous functionality. A key signal to watch is the standardization and expansion of charging infrastructure across key markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate Electrification R&D | Manufacturers can meet stringent emissions regulations and capture demand in urban low-emission zones. |
| Develop Integrated Telematics Platforms | Enhance operational efficiency and create new recurring revenue streams for fleet owners. |
| Expand Charging Infrastructure Partnerships | Overcome adoption barriers for electric models by ensuring practical site-level power availability. |
| Invest in Technician Training Programs | Address the critical skill gap in maintaining advanced electric and automated equipment. |
| Implement Battery-as-a-Service Models | Reduce initial capital outlay for buyers, accelerating the transition to electric fleets. |
Research Approach
A spread of perspectives from equipment manufacturers, rental fleet managers, construction project leads, and agricultural operators converged on the working assumptions for the compact wheel loaders market. This involved combining primary interviews with extensive secondary validation from government emissions reports, construction industry association data, and agricultural modernization studies. The analytical process integrated both bottom-up market sizing and top-down validation.
The demand-supply-balance framing informed the quantitative analytical framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, and end-user industry, alongside regional regulatory frameworks. Compound annual growth rates were derived through a combination of historical trend analysis and forward-looking projections based on infrastructure spending and agricultural equipment adoption rates. Forecast inputs included battery technology cost curves and regional emissions mandate schedules.
Sensitivities concentrate around the pace of battery technology advancements and the global expansion of charging infrastructure. Forecasts reflect assumptions documented regarding regulatory enforcement and end-user willingness to adopt new technologies. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Social Media Management Market
Others
South Korea Automotive LED Lighting Market
Others
Smart Home Platforms Market
Others
Refractometer Market
Others
Deep Sea Mining Market
Others
Spinner Flask Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
US Cat Food Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Synthetic Leather Market
Others
Infant Positioning Aids Market
Others
Hybrid System Market
Others
China Online Gambling Market
Others
Toy Packaging Market
Others
Global Electronic Filters Market
Others
Chip Card Scanners Market