
 Global Wireless Asset Management Market | 2026-2036
Global Wireless Asset Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Asset Management Market Outlook
REACH is repositioning hardware compliance costs across European supply chains. Cisco Systems Inc. leverages its networking infrastructure to dominate enterprise-grade wireless deployments. Siemens AG anchors industrial IoT integration for factory-floor asset visibility. Zebra Technologies specializes in ruggedized RFID endpoints for logistics environments.
Wireless asset management encompasses hardware-software systems that use radio-frequency identification, GPS transceivers, and mesh networking protocols to locate, monitor, and maintain physical equipment across distributed operations. These systems typically operate on 2.4 GHz or sub-GHz spectrum bands with battery lifespans engineered for multi-year field deployment, serving industrial users seeking to eliminate manual inventory audits and unplanned equipment downtime. RFID and GPS product types currently capture the largest installed base, though Bluetooth Low Energy tags represent the fastest-growing hardware category as unit costs decline and smartphone-based readers proliferate. Cloud-based deployment models lead new bookings as manufacturers prefer subscription pricing and remote firmware management over capital-intensive on-premises server farms.
The FCC governs spectrum allocation for unlicensed IoT transmissions in the United States, while the EU AI Act imposes algorithmic transparency requirements on predictive maintenance software that processes asset telemetry. ISO 55000 standards for asset management are reshaping procurement specifications as enterprises seek certified wireless platforms that integrate with enterprise resource planning systems. Stakeholders must decide whether to build captive IoT connectivity stacks or rely on carrier-managed networks as 5G private networks mature.
Market Dynamics
The EU AI Act is forcing predictive maintenance platforms to re-architect their data pipelines, splitting inference workloads between edge devices and sovereign cloud instances to satisfy cross-border algorithmic transparency mandates.
Growth Catalysts
- 5G Private Networks:Manufacturing plants in Germany and Japan are deploying dedicated spectrum slices to eliminate latency in real-time asset tracking, replacing Wi-Fi mesh systems that fail under metallic interference.
- ISO 55000 Certification:Asset-intensive industries are mandating certified wireless platforms that integrate directly with enterprise resource planning systems, creating procurement pull for standardized telemetry protocols.
- Battery Chemistry Advances:Sub-GHz transceivers with lithium thionyl chloride cells now deliver decade-long field lifespans, eliminating the labor cost of annual tag replacement in remote infrastructure monitoring.
Market Restraints
- Semiconductor Supply Concentration:RF front-end modules for sub-GHz bands depend on a narrow supplier base concentrated in Taiwan, exposing deployment timelines to foundry capacity constraints.
- Spectrum Fragmentation:The FCC's unlicensed rules diverge from ETSI's SRD harmonics across 868 MHz, forcing hardware vendors to maintain multiple SKUs and complicating economies of scale.
- Cellular LPWAN Substitution:NB-IoT and LTE-M modules from carrier ecosystems are capturing indoor asset-tracking contracts that RFID and Bluetooth Low Energy previously dominated.
Strategic Opportunities
- India's Industrial Corridors:The PLI scheme for electronics manufacturing is attracting contract manufacturers to Gujarat and Tamil Nadu, creating localized demand for wireless asset visibility in greenfield facilities.
- Predictive Maintenance Convergence:Vibration sensors fused with thermal imaging cameras are opening new service contracts in rotating equipment monitoring, displacing scheduled maintenance regimes.
- CSRD Reporting Mandates:The EU's Corporate Sustainability Reporting Directive is compelling asset owners to instrument energy consumption at the equipment level, driving sensor deployments that feed carbon accounting systems.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for ultra-low-power mesh networking remains a niche skill, with universities producing insufficient graduates familiar with Contiki-NG or Zephyr RTOS stacks.
- Legacy SCADA Integration:Brownfield manufacturing sites operate Modbus and Profibus networks that predate IP protocols, requiring costly protocol gateways to bridge wireless telemetry into existing control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Asset Management Market |
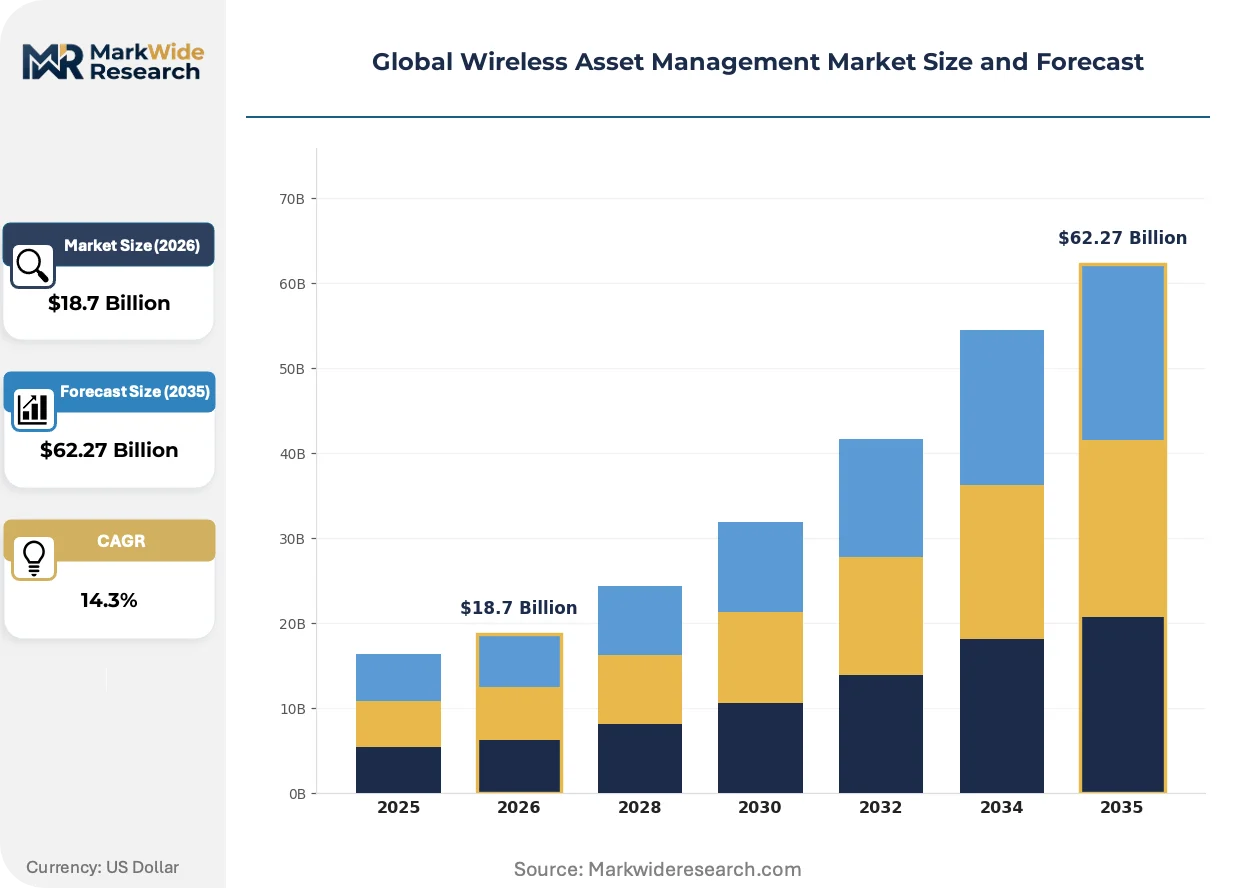
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $62.27 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RFID, GPS, Bluetooth, Zigbee End User: Manufacturing, Transportation, Healthcare, Retail Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Application: Inventory Management, Fleet Tracking, Asset Tracking, Facility Management |
| Companies Covered | Cisco Systems Inc., Siemens AG, Zebra Technologies, Honeywell International Inc., IBM Corporation, Verizon Communications Inc., Hitachi Ltd., Stanley Black and Decker, Inc., Intelligent InSites Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Asset Management Market Strategic Shifts
Radio-frequency identification is ceding ground to active beacon technologies that enable continuous location streaming rather than point-in-time detection, reshaping hardware procurement specifications across logistics and manufacturing verticals.
Bluetooth Low Energy 5.3 with direction-finding capabilities is electrifying real-time location systems in healthcare and warehousing, enabling sub-meter precision without the infrastructure cost of ultra-wideband. Hospital networks in the United States are piloting these systems for patient flow optimization, compressing capital deployment cycles from years to quarters. The technology is enabling smartphone-based asset discovery without dedicated handheld readers, collapsing the total cost of ownership for mid-scale deployments.
REACH substance restrictions are compelling hardware vendors to reformulate printed circuit board solder masks and antenna substrates, eliminating legacy halogenated flame retardants from supply chains serving European industrial customers. Component suppliers are accelerating qualification of phosphorus-based alternatives to maintain market access. The regulation is most acutely affecting ruggedized tags destined for outdoor infrastructure and mining equipment, where thermal and mechanical stress previously favored legacy material sets.
Subscription-based firmware management is displacing perpetual-license on-premises deployments as the dominant commercial model, with manufacturers preferring operational expenditure treatment and remote security patching over capital-intensive server farms. Industrial buyers in Germany and Japan are negotiating multi-year service agreements that bundle hardware replacement and predictive analytics. This shift is most visible in warehouse automation investments, where scaling operations demand elastic connectivity capacity without facility-by-facility infrastructure builds.
Global Wireless Asset Management Market Segmentation
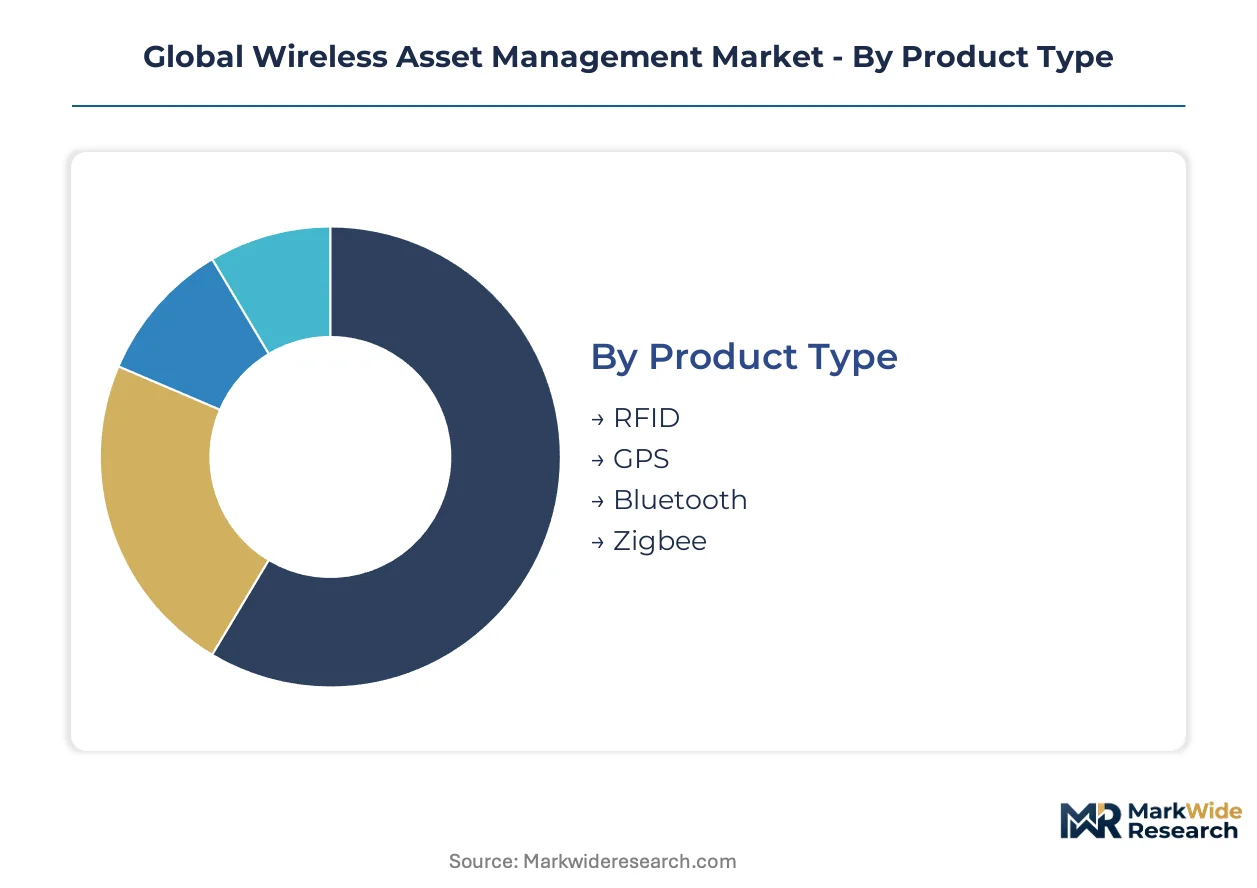
Wireless asset management vendors structure their portfolios around four distinct dimensions that determine certification requirements, integration complexity, and recurring revenue potential. Each segmentation axis carries different margin profiles and regulatory exposure across industrial, commercial, and institutional deployments.
Product Type:
RFID and GPS hardware must satisfy FCC Part 15 emissions limits in the United States and ETSI EN 300 220 spectrum compliance across European markets, while Bluetooth and Zigbee modules face additional SIG certification and Zigbee Alliance interoperability testing burdens that extend procurement cycles.
- RFID:Passive and active radio-frequency identification tags operate across UHF and HF bands with read ranges from centimeters to tens of meters. ISO 18000-6C compliance dominates manufacturing plant deployments in Germany and Japan where metallic interference demands ruggedized antenna designs. ISO 55000 certification requirements are concentrating procurement around vendors with integrated enterprise resource planning connectors.
- GPS:Satellite-based transceivers deliver meter-level outdoor positioning for fleet and infrastructure assets. Transportation corridors across the United States and India's industrial corridors under the PLI scheme are driving demand for multi-constellation receivers that combine GPS with GLONASS and NavIC signals.
- Bluetooth:Low-energy beacons with direction-finding capabilities enable sub-meter indoor positioning without dedicated reader infrastructure.
- Zigbee:Mesh networking protocols optimized for industrial sensor networks with self-healing topology and decade-long battery lifespans.
RFID sits at the top of the volume ranking, with Bluetooth climbing the fastest.
End User:
Customer type determines the balance between capital expenditure tolerance and operational technology integration depth, with manufacturing and transportation buyers prioritizing deterministic latency while healthcare and retail operators emphasize smartphone compatibility and rapid deployment.
- Manufacturing:Factory-floor deployments demand real-time location systems that integrate with SCADA and MES layers. Brownfield sites in Germany and Japan require protocol gateways to bridge Modbus and Profibus networks into wireless telemetry streams.
- Transportation:Fleet operators combine GPS with cellular LPWAN for continuous visibility across distributed vehicle assets. Compliance with the EU AI Act is forcing predictive maintenance platforms to split inference workloads between edge devices and sovereign cloud instances.
- Healthcare:Hospital networks prioritize BLE 5.3 direction-finding for patient flow optimization and equipment location without infrastructure-heavy ultra-wideband.
- Retail:Warehouse automation investments favor subscription-based firmware management and elastic connectivity capacity without facility-by-facility server builds.
Manufacturing commands the largest installed base, though healthcare is expanding most quickly as hospital networks compress capital deployment cycles.
Deployment:
Delivery model selection reflects buyer preferences for operational versus capital expenditure treatment, with cloud and hybrid architectures gaining share as manufacturers seek remote security patching and predictive analytics bundling.
- Cloud-Based:Subscription pricing with remote firmware management and multi-tenant analytics platforms. German and Japanese industrial buyers are negotiating multi-year service agreements that bundle hardware replacement.
- On-Premises:Perpetual-license server deployments retained by defense contractors and critical infrastructure operators with air-gapped security requirements.
- Hybrid:Edge computing nodes with cloud analytics aggregation, balancing latency-sensitive local processing with centralized machine learning model training.
- Mobile:Smartphone-based reader applications that collapse total cost of ownership for mid-scale deployments by eliminating dedicated handheld terminals.
Cloud-Based deployment leads new bookings, with Hybrid architectures gaining share fastest among asset-intensive industries.
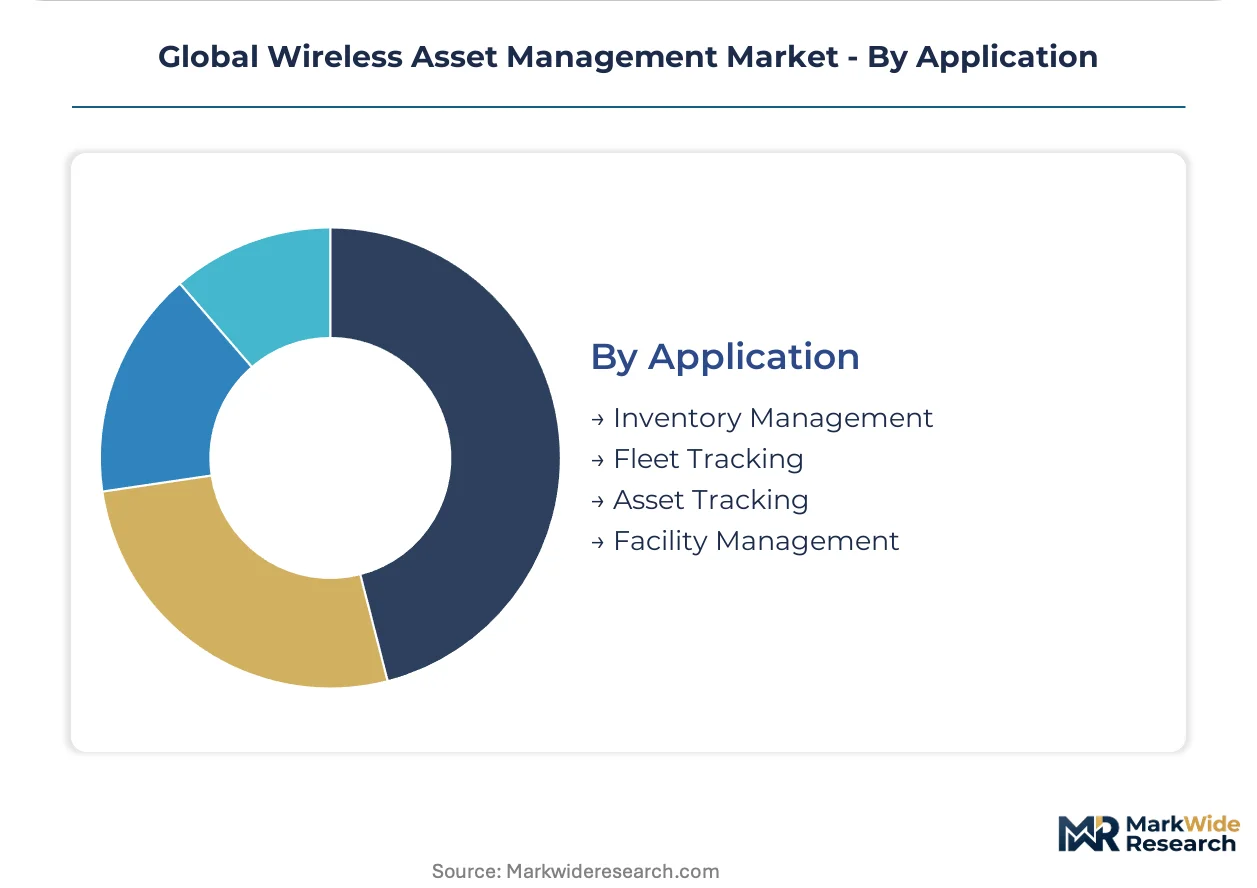
Application:
Use case segmentation determines sensor fusion requirements and data retention policies, with inventory and fleet applications driving highest tag volumes while facility management commands premium pricing for integrated environmental monitoring.
- Inventory Management:Automated cycle counting and shrinkage reduction through RFID and BLE beacon networks. REACH substance restrictions are compelling hardware vendors to reformulate printed circuit board solder masks for European supply chains.
- Fleet Tracking:Continuous vehicle location combined with driver behavior analytics and predictive maintenance alerts.
- Asset Tracking:Equipment location and utilization monitoring across construction, mining, and oil and gas operations where decade-long battery lifespans eliminate annual tag replacement labor.
- Facility Management:Integrated environmental sensing for energy consumption instrumentation feeding CSRD carbon accounting systems.
Inventory Management holds the highest tag shipment volumes, with Facility Management ascending fastest on sustainability reporting mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless asset management technology first achieved industrial scale in the United States during the early 2000s warehouse automation wave, then diffused through German automotive plants and Japanese precision manufacturing facilities before expanding into emerging industrial corridors.
United States
Warehouse automation investments in the United States continue scaling as e-commerce fulfillment centers deploy RFID and BLE beacon networks for real-time inventory visibility. FCC Part 15 regulations govern unlicensed IoT spectrum allocation, creating a predictable regulatory environment for hardware certification. The Chicago-Milwaukee industrial corridor and Dallas-Fort Worth logistics hub concentrate demand from third-party logistics providers retrofitting legacy facilities.
Germany
German manufacturing plants are deploying 5G private networks to eliminate latency in real-time asset tracking on factory floors with heavy metallic interference. The EU AI Act imposes algorithmic transparency requirements on predictive maintenance software processing cross-border telemetry, forcing vendors to re-architect data pipelines. Bavaria's automotive clusters and North Rhine-Westphalia's steel and chemical operations anchor industrial IoT integration demand.
Japan
Japanese precision manufacturers are replacing Wi-Fi mesh systems with dedicated 5G spectrum slices to achieve deterministic latency for automated guided vehicles and robotic workcells. METI industrial standards promote interoperability between wireless asset platforms and existing SCADA architectures. The Chubu region around Nagoya and Kansai manufacturing belt near Osaka concentrate deployments in automotive and electronics assembly.
India
India's PLI scheme for electronics manufacturing is attracting contract manufacturers to Gujarat and Tamil Nadu, creating localized demand for wireless asset visibility in greenfield semiconductor and component assembly facilities. TRAI spectrum policies for unlicensed IoT bands remain in development, creating uncertainty for sub-GHz deployment strategies. The Delhi-Mumbai Industrial Corridor and Sri City electronics cluster in Andhra Pradesh represent early adoption centers for RFID-based supply chain tracking.
China
Chinese logistics operators are integrating Bluetooth Low Energy tags with smartphone-based readers to collapse total cost of ownership for mid-scale warehouse deployments. MIIT certification requirements for radio transmission equipment extend procurement cycles for imported hardware platforms. The Yangtze River Delta around Shanghai and Pearl River Delta manufacturing zones concentrate demand from export-oriented electronics and apparel fulfillment operations.
Global Wireless Asset Management Market Competitive Environment
The competitive structure tilts toward diversified technology conglomerates with captive networking infrastructure. Market concentration remains moderate, with enterprise networking specialists and industrial automation providers commanding premium positions through integrated hardware-software stacks. Three archetypes dominate: infrastructure-anchored platforms leveraging existing customer relationships, specialized RFID endpoint manufacturers with ruggedized hardware expertise, and carrier-backed connectivity providers bundling managed services. Competitive dynamics center on strategic partnerships between hardware vendors and cloud analytics platforms, plus geographic expansion into India's emerging industrial corridors.
Within the infrastructure-anchored tier, Cisco Systems Inc. and Siemens AG represent contrasting geographic and vertical specializations, with the former exemplifying enterprise networking dominance and the latter embodying industrial IoT integration depth. Zebra Technologies occupies a distinct position as a specialist in ruggedized endpoint hardware for logistics environments. These three companies illustrate the segmentation between horizontal networking platforms, vertical industrial systems, and dedicated hardware specialists that defines competitive positioning across deployment scenarios.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Siemens AG |
| Zebra Technologies |
| Honeywell International Inc. |
| IBM Corporation |
| Verizon Communications Inc. |
| Hitachi Ltd. |
| Stanley Black and Decker, Inc. |
| Intelligent InSites Inc. |
| Others |
Value Chain & Pricing Dynamics
German automotive OEM procurement programs anchor pricing power for enterprise-grade wireless asset platforms, with multi-year service agreements bundling hardware replacement and predictive analytics displacing transactional per-tag sales. Subscription-based firmware management now dominates commercial models as manufacturers prefer operational expenditure treatment over capital-intensive server farms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies around certification grade and integration complexity. Premium tiers command positioning through ISO 55000 certification and direct ERP connector availability, while economy tiers serve mid-scale warehouse deployments with smartphone-based reader compatibility. Cost compression in standard tiers is intensifying because Bluetooth Low Energy tag commoditization erodes hardware margins. Healthcare networks exhibit lowest price sensitivity due to patient-flow optimization imperatives, whereas retail logistics operators prioritize total cost of ownership minimization.
Supply Chain Analysis
Firmware engineering talent scarcity across Taiwan, South Korea, and Japan constrains RF front-end module production capacity for sub-GHz transceivers. Lithium thionyl chloride cell supply draws from Japanese and South Korean chemical manufacturers, while printed circuit board substrates hinge on REACH-compliant phosphorus-based flame retardant qualification. Single-source vulnerability concentrates in Taiwan foundry capacity for sub-GHz RF front-end modules. Distribution runs through carrier-managed network partnerships and direct enterprise sales teams serving asset-intensive industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless asset management market functions as a stable compounder, with industrial automation investments sustaining recurring revenue streams through multi-year service agreements and remote firmware management subscriptions.
For Market Incumbents: Cement dominance in 5G private network deployments by deepening captive supply of edge computing nodes and predictive analytics engines. Prioritize ISO 55000 certification maintenance to defend against carrier-backed LPWAN substitution threatening RFID and Bluetooth Low Energy contracts. Capacity addition in India's Gujarat and Tamil Nadu industrial corridors secures localized manufacturing presence under the PLI scheme. For New Entrants and Emerging Players: Begin with India's greenfield electronics manufacturing facilities where TRAI spectrum policy uncertainty creates incumbent hesitation and first-mover windows. Hospital networks in the United States present the most penetrable segment due to compressed capital deployment cycles and BLE 5.3 direction-finding pilot expansion. A smartphone-based reader application go-to-market angle collapses total cost of ownership for mid-scale deployments without dedicated handheld terminal infrastructure. For Investors and Strategic Acquirers: Enterprise networking specialists with captive infrastructure assets are the most active acquirer in this space, seeking vertical industrial systems to complete integrated hardware-software stacks. Long-term viability centers on subscription revenue durability and sovereign cloud compliance capabilities under the EU AI Act. Acquisition target archetypes include ruggedized RFID endpoint manufacturers with mining and outdoor infrastructure certification depth. Watch for 5G private network spectrum allocation acceleration in Germany and Japan as inflection indicator for industrial IoT integration demand.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Private Network Deployment | Eliminates latency in German and Japanese manufacturing plants with heavy metallic interference. |
| ISO 55000 Certification Investment | Creates procurement pull from asset-intensive industries mandating ERP-integrated telemetry protocols. |
| BLE 5.3 Direction-Finding Launch | Enables sub-meter precision in United States hospital networks without ultra-wideband infrastructure cost. |
| India PLI Scheme Manufacturing Footprint | Captures localized demand from Gujarat and Tamil Nadu greenfield electronics facilities. |
| Predictive Maintenance Platform Integration | Addresses EU AI Act algorithmic transparency mandates through edge-cloud workload splitting. |
Study Parameters
Bottom-up manufacturing plant deployment modeling reconciled against top-down RF module shipment tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combine with secondary validation from FCC Part 15 filings, ETSI EN 300 220 certification databases, SEC 10-K hardware revenue disclosures, and industrial automation trade association reports. Triangulation between demand-side installation data and supply-side component bill-of-materials analysis ensures cross-verified volume estimates.
Historical trendline analysis of RFID, GPS, Bluetooth, and Zigbee hardware shipments across product type, end user, deployment model, and application dimensions establishes baseline growth patterns. CAGRs derive from regression analysis against industrial automation capex cycles, warehouse automation investment waves, and 5G private network deployment trajectories. Forecast inputs include battery chemistry advance curves, REACH substance restriction implementation timelines, and CSRD reporting mandate compliance deadlines across European asset owners.
Several conditions sit outside the modeled scope, including sudden TRAI spectrum policy reversals in India, Taiwan foundry capacity disruptions from geopolitical events, and unanticipated EU AI Act enforcement interpretations affecting cross-border data flows. Forecasts reflect documented assumptions regarding sustained industrial automation investment continuity and carrier LPWAN pricing stability. Material deviation in semiconductor supply concentration or 5G private network adoption velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East 3D Printing Construction Market
Others
Binoculars Market
Others
Free Space Optics (FSO) Market
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Industrial Tablet PC Market
Others
Powder Coating Equipment Market
Others
Japan Coal Market
Others
Storm Surge Barriers Market
Others
Wingboards Market
Others
Global Personal Care Packaging Market
Others
Fibert Market
Others
5G Tester Market
Others
Digital Education Projector Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Live IP Broadcast Equipment Market
Others
Latin America Contract Packaging Market