
 Mexico 3D Printing Construction Market | 2026-2036
Mexico 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico 3D Printing Construction Market Insights
Housing developer consolidation in Mexico City's metropolitan zone is repositioning procurement power toward volume buyers who can underwrite multi-unit printed construction projects. CEMEX leverages its cement distribution network to supply specialized concrete mixes for gantry-based printing systems. COBOD International anchors the technology layer through its BOD2 printer deployments with Mexican construction partners. TridiMX competes as a domestic integrator, adapting European hardware to local seismic codes and labor practices.
Mexico 3D printing construction deploys computer-controlled deposition of cementitious or polymer-based materials through extrusion nozzles or powder-bed fusion systems, typically achieving layer heights of 10-50 millimeters and compressive strengths exceeding 25 MPa for structural wall elements. Its primary purpose is to reduce formwork costs, construction timelines, and material waste in vertical and horizontal building components. Concrete mix formulations dominate current material procurement due to established supply chains and regulatory familiarity, while composite materials represent the fastest-expanding category as fiber-reinforced geopolymers gain traction for seismic-resistant applications. Binder jetting technology occupies the premium segment for architectural-scale projects requiring complex geometries, whereas FDM systems sustain broader contractor adoption for prototyping and non-structural elements.
Mexico's national construction standards under the Ministry of Agrarian, Territorial and Urban Development (SEDATU) and the Federal Commission for Protection against Sanitary Risks (COFEPRIS) for material emissions shape product certification pathways and market access timelines for imported printing materials. The national standardization body coordinates with local state building departments to align municipal permits with emerging additive construction methods, creating fragmented but evolving compliance terrain. Stakeholders must monitor how SEDATU's anticipated technical appendices for 3D-printed structural elements interact with state-level enforcement capacity across Mexico's 32 federal entities.
Market Dynamics
Housing developer consolidation in Mexico City's metropolitan zone is repositioning procurement power toward volume buyers who can underwrite multi-unit printed construction projects, compressing supplier margins while accelerating technology adoption timelines.
Growth Catalysts
- SEDATU Technical Appendices:Mexico's national construction standards regulator is developing dedicated compliance pathways for 3D-printed structural elements, reducing permitting uncertainty for early adopters.
- Central Mexico Corridor Concentration:Industrial clusters and university research centers co-locating across Mexico City, Querétaro, and Puebla create localized ecosystems for equipment testing and workforce training.
- Geopolymer Formulations:Fiber-reinforced geopolymers are gaining traction for seismic-resistant applications, opening new material procurement categories beyond conventional concrete.
Market Restraints
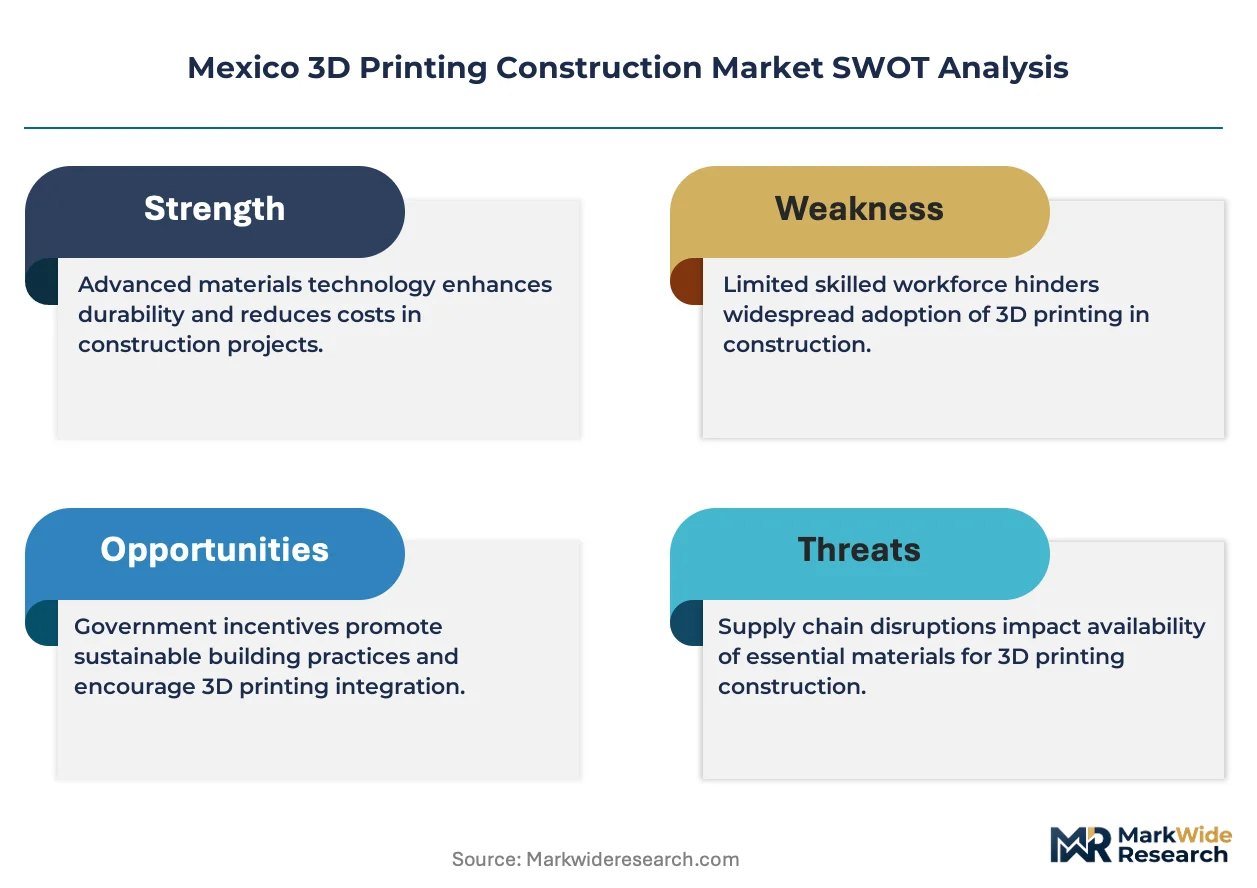
- Portland Cement Price Volatility:Specialized concrete mix formulations depend on cement supply chains where CEMEX maintains dominant distribution control, creating input cost exposure for gantry-based printing operators.
- State-Level Enforcement Fragmentation:Municipal permit alignment varies across Mexico's 32 federal entities, generating regulatory friction that extends project timelines.
- Conventional Formwork Substitution:Traditional cast-in-place construction retains cost advantages for single-unit projects below the threshold where additive manufacturing achieves formwork savings.
Strategic Opportunities
- Puebla Industrial Corridor:Automotive supplier parks and aerospace clusters present captive demand for rapid-build warehousing and cleanroom facilities using printed structural shells.
- Binder Jetting Convergence:Integration of powder-bed fusion systems with architectural-scale robotics enables complex geometries for premium commercial facades.
- COFEPRIS Material Emissions Pathways:Certification for low-carbon printed materials aligns with federal sustainability procurement mandates for public housing projects.
Industry Challenges
- Seismic Engineering Certification:Validating layer adhesion and interlayer bond strength under cyclic loading requires extended testing protocols with Mexico's national standardization body.
- Equipment Operator Training:Gantry-based printing systems demand hybrid skill sets combining concrete placement expertise with CNC programming, creating workforce pipeline constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico 3D Printing Construction Market |
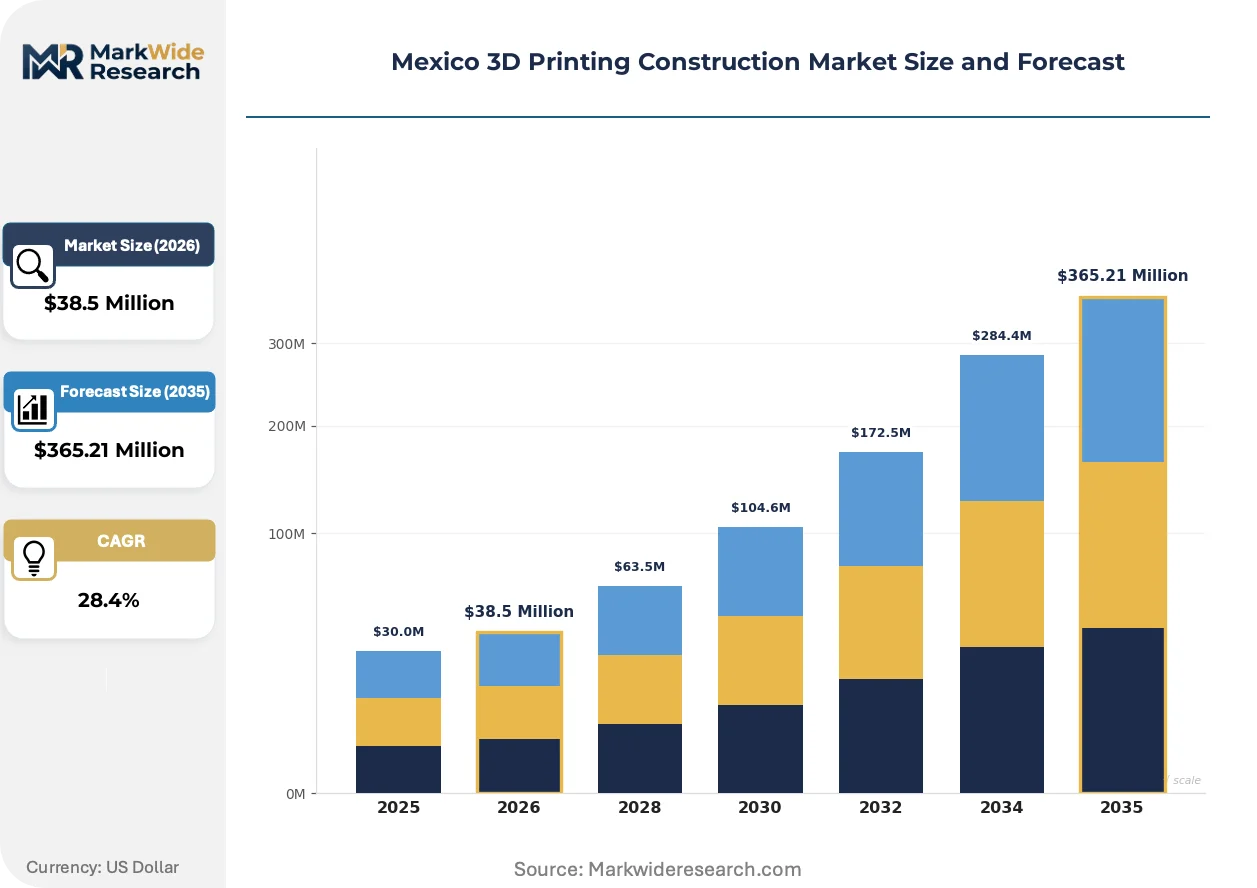
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $365.21 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Mix, Filament, Composite Materials, Smart Materials Application: Residential Buildings, Commercial Structures, Infrastructure Development, Artistic Installations Technology: FDM, SLS, DLP, Binder Jetting End User: Construction Firms, Architects, Artists, Contractors |
| Companies Covered | CEMEX, COBOD International, ICON, Apis Cor, Winsun, TridiMX, Boja 3D, Bayro Mexicana, InMateriis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico 3D Printing Construction Market Trends and Innovations
Material science advances and regulatory clarification are converging to expand addressable project types beyond pilot demonstrations into commercial-scale residential and industrial construction.
Fiber-reinforced geopolymer composites are expanding into structural wall applications previously reserved for conventional reinforced concrete. Housing developers in Mexico City's metropolitan zone are specifying these materials for mid-rise residential blocks, attracted by compressive strengths exceeding 25 MPa and reduced curing times. This expansion is compressing the payback period for gantry-based printer capital investments.
SEDATU's anticipated technical appendices for 3D-printed structural elements are forcing alignment between federal standards and state-level building departments. Industrial consequence includes accelerated material certification timelines for imported printing materials that satisfy COFEPRIS emissions requirements. Central Mexico corridor municipalities with established university research partnerships are responding fastest, creating regulatory arbitrage opportunities.
Volume buyers in Mexico City's consolidated developer landscape are unbundling design-build contracts to retain direct control over material procurement and printer deployment schedules. Traditional general contractors are being displaced by specialized additive construction integrators who assume risk for structural performance guarantees. This pattern is most visible in affordable housing projects where timeline compression directly impacts financing costs.
Mexico 3D Printing Construction Market Segmentation
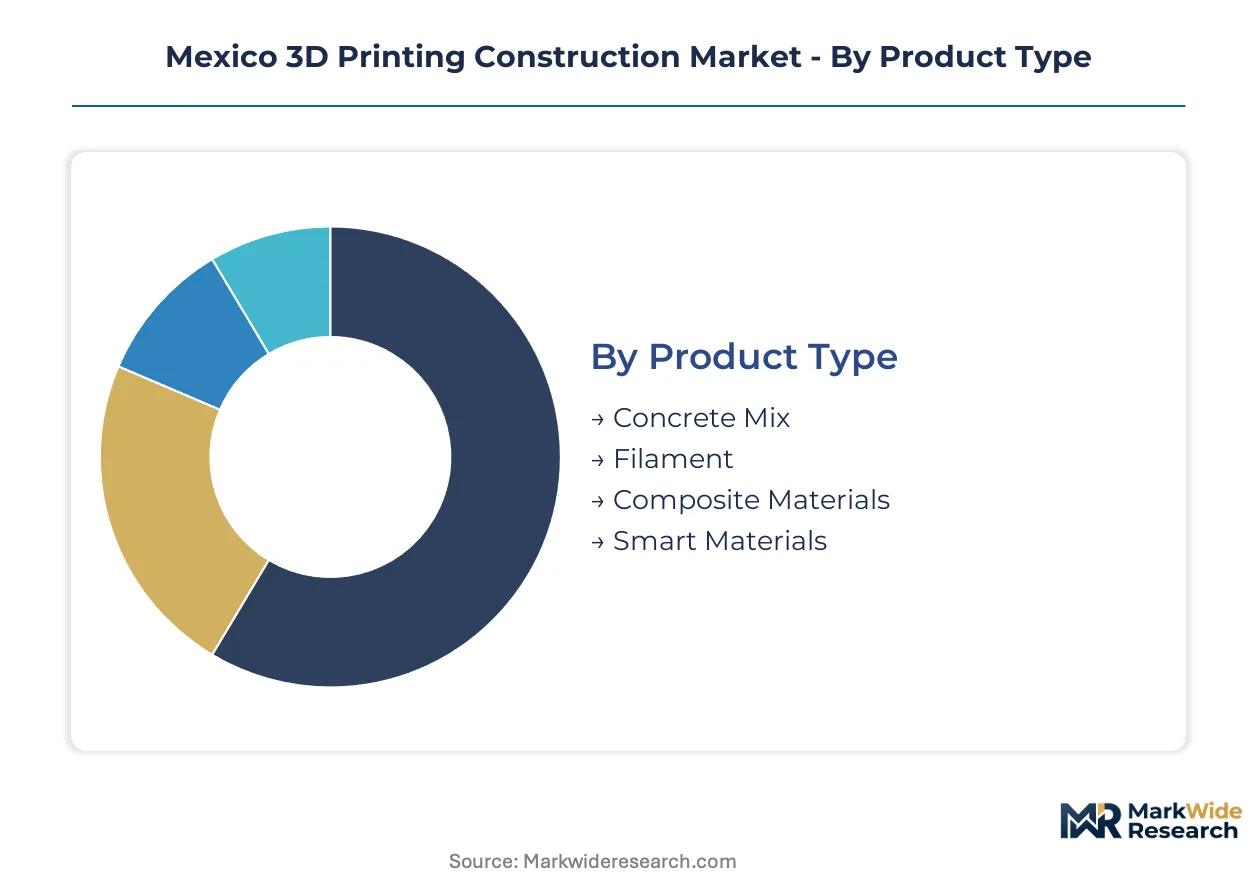
Material selection and technology deployment in Mexico's additive construction sector follow distinct procurement patterns across project scales and regulatory exposure. Segmentation clarity enables stakeholders to align capital allocation with the specific compliance and performance requirements of each application cluster.
Product Type:
Standalone material formulations dominate structural applications, while embedded smart systems require integration with building management infrastructure during design phase.
- Concrete Mix:Portland cement-based formulations with specialized rheology modifiers achieve layer heights of 10-50 millimeters in gantry-based systems. Demand concentrates in Mexico City's affordable housing corridor where CEMEX distribution networks enable just-in-time delivery to multi-unit residential sites facing SEDATU compliance deadlines.
- Composite Materials:Fiber-reinforced geopolymer matrices deliver compressive strengths exceeding 25 MPa with reduced curing cycles versus conventional concrete. Procurement is accelerating across Puebla and Querétaro industrial zones where seismic-resistant specifications for warehouse structures create captive demand beyond residential applications.
- Filament:Polymer-based feedstocks serve prototyping and non-structural element production for architectural visualization models.
- Smart Materials:Self-sensing concrete formulations with embedded conductive networks remain nascent, constrained by COFEPRIS certification pathways for emissions compliance in occupied structures.
Concrete Mix leads volumes today; Composite Materials is gaining share fastest.
Application:
Cost tier stratification separates high-volume standardized housing from premium commercial projects where geometric complexity justifies technology premiums.
- Residential Buildings:Mid-rise affordable housing blocks in Mexico City's metropolitan zone represent the primary volume deployment, with developer consolidation enabling multi-unit printer utilization rates that amortize capital costs across 50-plus unit phases.
- Commercial Structures:Cleanroom facilities and rapid-build warehousing in Puebla's automotive supplier parks command higher material specifications and accelerated timeline premiums, creating margin expansion opportunities for specialized integrators.
- Infrastructure Development:Bridge components and drainage structures face extended seismic certification protocols with Mexico's national standardization body, compressing near-term addressable market scope.
- Artistic Installations:Non-structural facades and sculptural elements utilize binder jetting for complex geometries with reduced regulatory burden.
Residential Buildings anchors current deployment; Commercial Structures shows steepest expansion trajectory.
Technology:
Maturity gradients separate established extrusion platforms from emerging powder-bed systems requiring specialized operator training pipelines.
- Binder Jetting:Powder-bed fusion integrated with architectural-scale robotics enables complex facade geometries for premium commercial projects. Adoption concentrates in Mexico City design-build firms serving international developer clients with sustainability certification requirements.
- FDM:Fused deposition modeling sustains broad contractor adoption for prototyping, formwork molds, and non-structural elements where capital constraints limit gantry system acquisition.
- SLS:Selective laser sintering of polymer composites serves specialized architectural components with high dimensional tolerance requirements.
- DLP:Digital light processing remains confined to detailed scale models and ornamental fixtures given build volume limitations.
FDM dominates installed base; Binder Jetting is climbing the fastest.
End User:
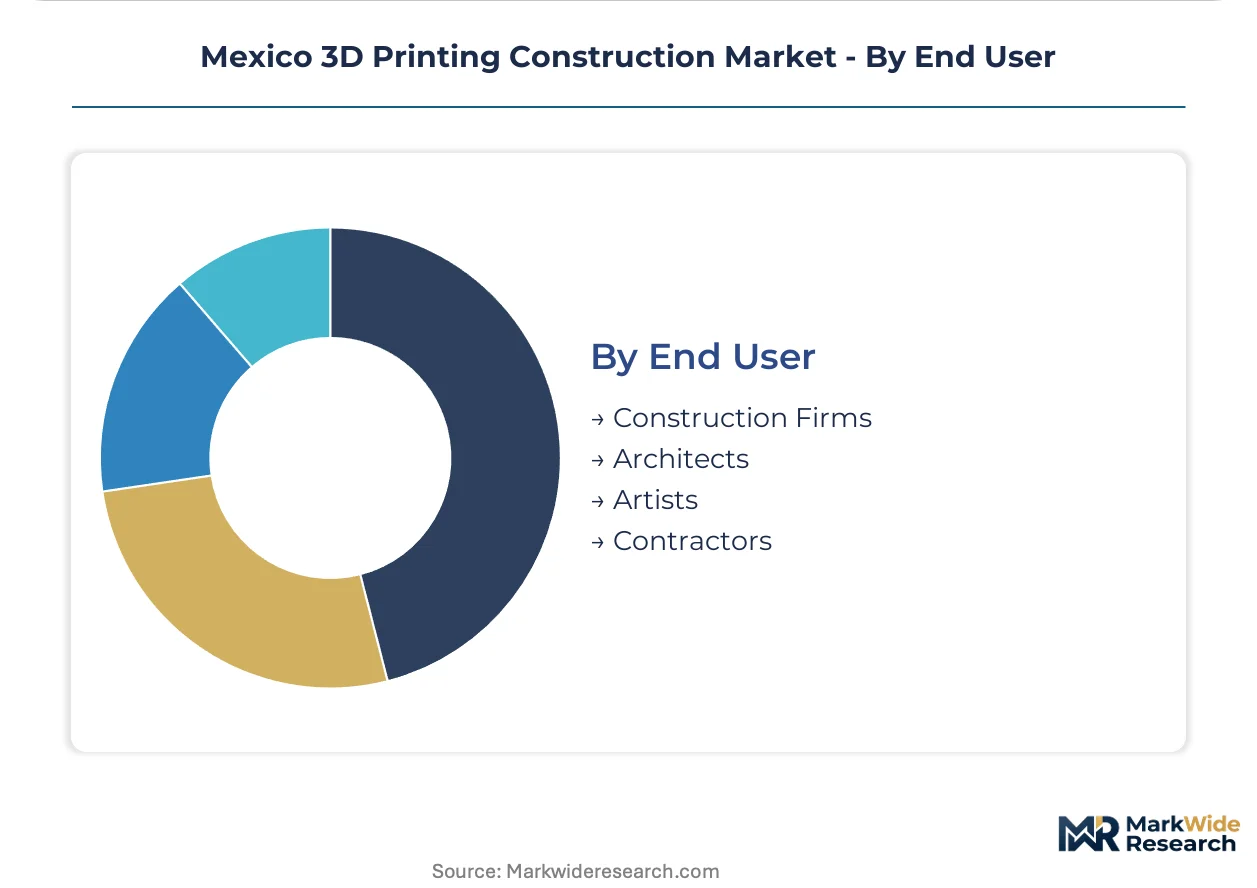
Customer type fragmentation creates distinct procurement patterns between risk-aggregating developers and specification-driven design professionals.
- Construction Firms:Volume buyers in Mexico City's consolidated developer landscape are unbundling design-build contracts to retain direct control over material procurement and printer deployment schedules, displacing traditional general contractor relationships.
- Architects:Design professionals specify printed elements for geometric complexity premiums in commercial facades, though structural performance guarantees require partnership with specialized additive construction integrators.
- Contractors:Subcontractor networks face workforce pipeline constraints combining concrete placement expertise with CNC programming competencies.
- Artists:Independent creators utilize desktop systems for limited-run installations with minimal regulatory exposure.
Construction Firms command procurement volume; Architects is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's additive construction sector outpaces Brazil's nascent deployment by roughly five years in regulatory maturity, while both trail UAE's state-backed megaproject integration. Central Mexico's industrial corridor concentrates equipment deployment and material testing infrastructure.
Mexico City Metropolitan Zone
Housing developer consolidation across the capital's periphery drives multi-unit printed residential procurement at scale. SEDATU's anticipated technical appendices for 3D-printed structural elements reduce permitting friction for early adopters. University research partnerships in Coyoacán and Tlalpan accelerate gantry system operator training pipelines.
Querétaro
Aerospace supplier parks and automotive clusters generate captive demand for rapid-build cleanroom facilities. State-level building departments here align fastest with federal additive construction standards, creating regulatory arbitrage. Industrial zones around El Marqués host equipment testing sites for seismic-resistant geopolymer formulations.
Puebla
Automotive manufacturing concentration drives warehouse and logistics facility construction with compressed timelines. Municipal permit offices coordinate directly with SEDATU on pilot project approvals, shortening certification cycles. The Atlixco corridor attracts gantry-based printer deployments for mid-rise industrial shells.
Nuevo León
Monterrey's construction sector experiments with printed structural elements for commercial facades in premium developments. State building codes incorporate seismic performance testing protocols earlier than southern counterparts. The Apodaca industrial zone hosts material certification laboratories serving northern Mexico demand.
Jalisco
Guadalajara's design-build firms integrate binder jetting systems for architectural complexity in hospitality projects. COFEPRIS emissions certification for printed materials progresses through state-level environmental offices. The Zapopan technology corridor attracts specialized additive construction integrators displacing traditional contractors.
Mexico 3D Printing Construction Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Mexico's additive construction sector, creating a tiered structure where capital depth separates scalable deployers from project-bound integrators. Cement distribution networks anchor material supply control, while equipment licensors and domestic adapters occupy distinct technology layers. Two strategic archetypes dominate: multinational hardware suppliers leveraging global R&D pipelines, and regional integrators customizing foreign platforms to local seismic codes. Competitive moves concentrate on gantry system deployment partnerships and material formulation exclusivity arrangements with housing developers.
Within the multinational equipment tier, COBOD International A/S and ICON Technology, Inc. exemplify divergent approaches to market development—Danish gantry system standardization versus Texas-based vertical integration into project delivery. TridiMX occupies a position bridging these models as a domestic integrator adapting European hardware to SEDATU compliance requirements and local labor practices. CEMEX S.A.B. de C.V. anchors the materials layer through captive concrete mix distribution networks that supply specialized rheology modifiers for extrusion-based systems. These three entities represent the dominant competitive anchors across technology licensing, domestic adaptation, and material supply respectively.
| Leading Market Players |
|---|
| CEMEX |
| COBOD International |
| ICON |
| Apis Cor |
| Winsun |
| TridiMX |
| Boja 3D |
| Bayro Mexicana |
| InMateriis |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between SEDATU-compliant structural elements and uncertified prototyping materials splits Mexico's additive construction market into parallel pricing and sourcing ecosystems. Premium gantry-based systems serving Mexico City housing developers command material cost premiums tied to CEMEX's specialized rheology modifier distribution, while FDM prototyping tiers compete on commoditized polymer feedstock spot markets with minimal regulatory overlay.
Pricing Analysis
Capacity additions in Querétaro's aerospace supplier corridor are reshaping price floors for rapid-build commercial structures. Project-based contracting dominates, with price differentiation resting on seismic certification grade and volume scale across multi-unit residential phases. Cost compression in standard-grade concrete mixes is intensifying because housing developer consolidation concentrates procurement leverage. Single-unit contractors exhibit highest price sensitivity, whereas volume buyers in Mexico City's metropolitan zone prioritize timeline certainty over per-unit material savings.
Supply Chain Analysis
Domestic-content mandates under SEDATU's technical appendices are reshaping sourcing patterns for imported printing materials and gantry system components. Manufacturing concentration spans Denmark, China, and domestic Mexican assembly operations for equipment adaptation. Raw material dependencies center on Portland cement, fiber-reinforced geopolymer precursors, and specialized extrusion nozzles. Single-source vulnerability concentrates in CEMEX's cement distribution network. Distribution runs through CEMEX's just-in-time delivery infrastructure to multi-unit residential sites facing SEDATU compliance deadlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's additive construction sector functions as a geographic-arbitrage play where SEDATU regulatory clarity outpaces Brazil's nascent standardization, capturing capital flows seeking early-mover certification advantages.
For Market Incumbents: Extend gantry system deployment partnerships into Puebla's automotive supplier parks before regional integrators consolidate cleanroom facility contracts. Cement distribution exclusivity agreements with CEMEX anchor material cost control against emerging geopolymer suppliers. Capacity addition in Querétaro's state-aligned building departments offers regulatory arbitrage leverage over slower-adopting federal entities. For New Entrants and Emerging Players: Binder jetting convergence for architectural-scale commercial facades offers technology-first wedge positioning against established extrusion platforms. White-space targets concentrate in Guadalajara's hospitality sector where design-build firms seek geometric complexity premiums with reduced seismic certification burden. Go-to-market angle: partner with university research centers in Coyoacán for operator training pipeline co-development. For Investors and Strategic Acquirers: Consolidation pressure builds where equipment operator training constraints limit scalable deployment of gantry-based systems. Long-term viability frames additive construction as infrastructure-light manufacturing displacing conventional formwork across Mexico's affordable housing deficit. Acquisition target archetype: regional integrators with SEDATU compliance expertise and established municipal permit relationships. Signal to watch: COFEPRIS emissions certification acceleration for low-carbon printed materials in public housing procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Material Certification Investment | SEDATU technical appendix alignment accelerates multi-unit residential permitting timelines. |
| Regional Training Partnership | University research center collaboration in Tlalpan builds gantry operator pipeline capacity. |
| Geopolymer Formulation Development | Fiber-reinforced seismic-resistant specifications unlock Puebla warehouse demand beyond housing. |
| State-Level Regulatory Arbitrage | Querétaro's early building code alignment compresses project certification cycles versus southern counterparts. |
| Equipment Deployment Partnership | Gantry system placement with consolidated Mexico City developers amortizes capital across 50-plus unit phases. |
Research Methodology
Coverage spans Mexico's central corridor, northern industrial zones, and Pacific coast design-build clusters, with primary inputs from each. Interviews with housing development executives, SEDATU regulatory affairs leads, CEMEX procurement managers, gantry system operators, and university research directors combined with secondary validation from customs records, SEC filings of multinational equipment suppliers, SEDATU technical documentation, and COFEPRIS emissions registries. Bottom-up project pipeline assessment triangulates against top-down cement demand modeling for specialized rheology modifiers.
Granularity-level modeling deployed product type, application scale, technology maturity, and end-user procurement power as core segmentation dimensions across the projection horizon. CAGRs derive from equipment deployment run-rate analysis and material formulation adoption curves. Industry-specific forecast inputs include SEDATU technical appendix implementation timing and state-level building department alignment velocity.
The model holds under continued SEDATU regulatory clarification and stable Portland cement supply; deviation in COFEPRIS emissions protocol stringency or CEMEX distribution network disruption would shift material cost assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Augmented Reality in Energy and Utilities Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Japan Coal Market
Others
Digital Transformation of Maritime Freight Market
Others
Global Maritime Freight Transport Market
Others
Surgical Simulation Market
Others
Industrial Hooters Market
Others
Liquid Density Meters Market
Others
Document Camera Market
Others
Interference Mitigation Filters Market
Others
Gas Holders Market
Others
Canada Feed Additives Market
Others
Asia-Pacific Air Separation Unit Market
Others
HPHT Diamond Cubic Press Market
Others
Subtilisin Market
Others
Smart Card Contactless Ticketing Market