
 Global Smokeless Tobacco Market | 2026-2036
Global Smokeless Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smokeless Tobacco Market Outlook
Subscription-based replenishment services for moist snuff and pouch formats is rebalancing how manufacturers capture recurring revenue and consumer loyalty. Altria Group leverages its retail network depth to sustain dominant shelf presence across American convenience channels. Swedish Match anchors Scandinavian supply chains through specialized manufacturing infrastructure for portioned snus products. British American Tobacco competes by extending its portfolio into reduced-risk oral nicotine derivatives alongside traditional chewing blends.
Smokeless tobacco comprises fermented or pasteurized leaf products designed for oral absorption without combustion, typically containing moisture-adjusted tobacco with alkaline pH modifiers to enhance nicotine bioavailability through buccal mucosa permeation. Its primary commercial purpose centers on delivering nicotine satisfaction in environments where smoking restrictions apply or consumer preference favors discrete consumption. Moist snuff and snuff categories occupy the largest margin pools due to established brand equity and repeat purchase frequency, while dissolvable tobacco represents the fastest-evolving segment as manufacturers navigate novel product classification frameworks. Distribution through convenience stores dominates volume throughput, though online retail channels are gaining structural importance among younger adult demographics seeking flavor variety and subscription convenience.
The FDA Center for Tobacco Products enforces premarket authorization requirements that determine which novel smokeless formulations achieve legal sale status in the United States. The European Medicines Agency and national regulators such as Sweden's Public Health Agency apply divergent classification standards that either permit snus under harm-reduction frameworks or restrict newer oral nicotine products as medicinal devices. India's Food Safety and Standards Authority and BIS labeling mandates create additional compliance layers for chewing tobacco and gutkha variants. Stakeholders must monitor how evolving toxicological review standards and flavor restriction proposals in multiple jurisdictions will reshape permissible product architectures and portfolio prioritization decisions.
Market Dynamics
Pre-market authorization requirements from the FDA Center for Tobacco Products are compressing product development timelines and forcing manufacturers to prioritize reduced-risk formulations over incremental line extensions.
Growth Catalysts
- Harm-reduction policy frameworks:Sweden's Public Health Agency permits snus under differentiated risk classifications, creating regulatory space for pasteurized oral products. Adult recreational users in Scandinavian markets demonstrate sustained loyalty to portioned formats.
- Moisture-adjusted pouch manufacturing:Specialized alkaline pH modification processes enhance buccal nicotine absorption rates. Production infrastructure investments in Gothenburg and Stockholm anchor supply reliability for export markets.
- Convenience channel density:American retail networks achieve shelf presence dominance through direct-store-delivery systems. Urban clusters in Texas, Florida, and North Carolina concentrate repeat purchase frequency.
Market Restraints
- Flavor additive restrictions:The EU Tobacco Products Directive prohibits characterizing flavors in oral nicotine products, eliminating differentiation levers for new entrants.
- Raw leaf supply concentration:Premium dark-fired tobacco cultivation concentrates in Kentucky and Tennessee, exposing manufacturers to weather-driven yield volatility.
- Medical device classification risk:The European Medicines Agency evaluates novel oral nicotine pouches under pharmaceutical frameworks, extending approval timelines beyond tobacco pathways.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-consumer platforms bypass convenience store margin structures. Urban adult demographics in Seattle, Denver, and Austin demonstrate willingness to automate recurring orders.
- Reduced-risk derivative portfolios:Synthetic nicotine formulations fall outside certain tobacco-specific regulations. Product architectures incorporating non-tobacco nicotine sources access distinct compliance pathways.
- Indian chewing tobacco modernization:India's Food Safety and Standards Authority mandates BIS labeling compliance that rewards standardized manufacturing. Mumbai and Delhi manufacturing clusters upgrade from informal production.
Industry Challenges
- Toxicological review capacity constraints:FDA premarket tobacco product application backlogs delay launch timelines. Manufacturers face 18-24 month authorization windows for novel formulations.
- Legacy ERP integration friction:Track-and-trace compliance mandates require serialization system overlays. Batch-level genealogy tracking conflicts with decades-old manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smokeless Tobacco Market |
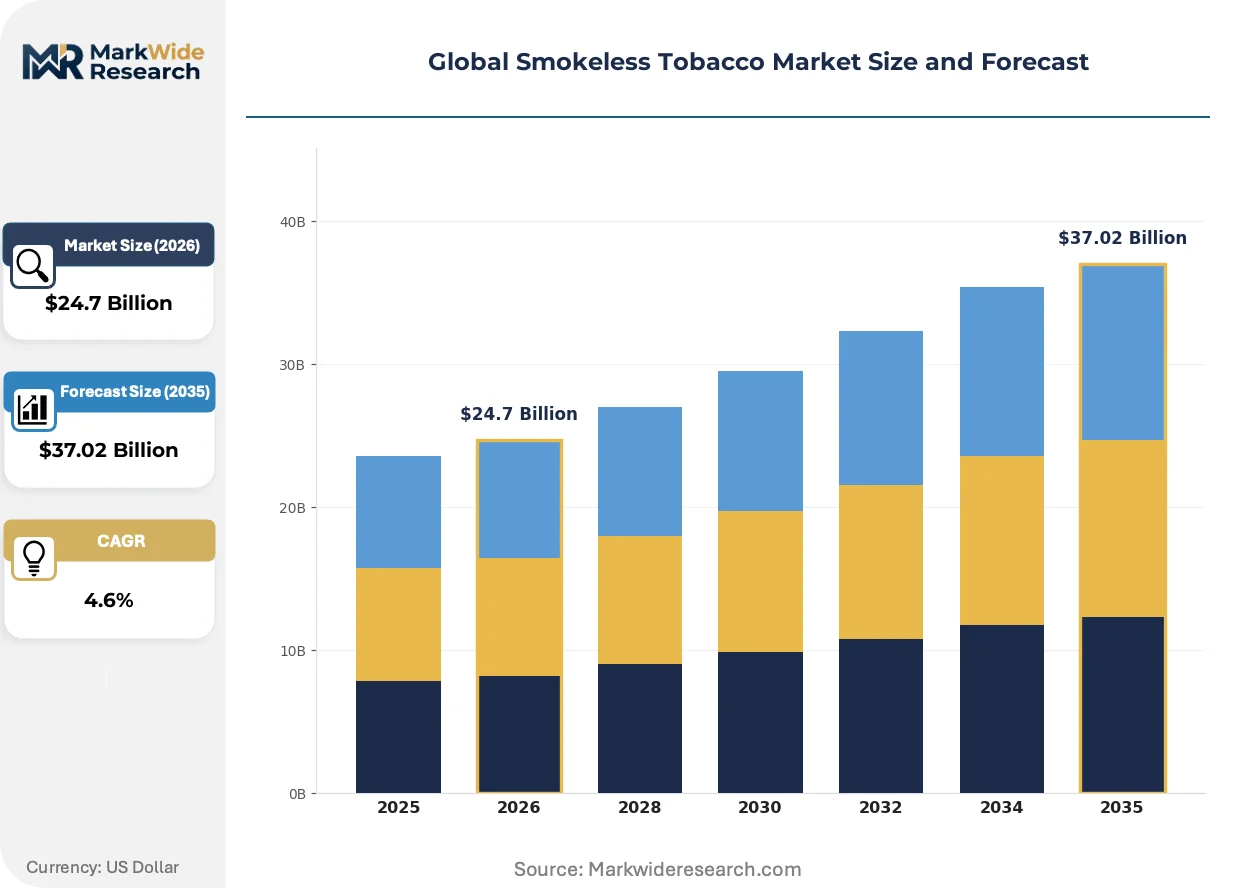
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $37.02 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewing Tobacco, Snuff, Dissolvable Tobacco, Moist Snuff End User: Adults, Young Adults, Premium Users, Casual Users Distribution Channel: Online Retail, Convenience Stores, Supermarkets, Vending Machines Packaging Type: Cans, Pouches, Bottles, Packs |
| Companies Covered | Altria Group, Philip Morris International, British American Tobacco, Imperial Brands, Japan Tobacco, Swedish Match, DS Group, Swisher International, Mac Baren Tobacco Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smokeless Tobacco Market Strategic Shifts
Oral nicotine delivery architectures are bifurcating between pasteurized leaf traditions and synthetic nicotine derivatives, with regulatory classification determining which pathway captures margin.
Alkaline pH buffering technology is electrifying nicotine bioavailability in next-generation pouch formats. Adult recreational users in American coastal metros adopt these products at rates exceeding moist snuff transitions. The technology is compressing differentiation cycles as manufacturers race to optimize absorption profiles ahead of flavor restriction deadlines.
REACH chemical registration requirements are reshaping additive sourcing for European-bound products. Manufacturers reformulate flavor matrices to exclude substances requiring extended toxicological dossiers. Swedish exporters face particular pressure as their domestic harm-reduction permissions do not transfer automatically to EU-wide market access.
Channel disintermediation through specialized e-commerce platforms fragments historical convenience store dominance. Younger adult demographics in Minneapolis, Portland, and San Francisco prioritize flavor variety access over immediate retail availability. Geographic demand rotation follows platform marketing spend rather than traditional wholesale distribution patterns.
Global Smokeless Tobacco Market Segmentation
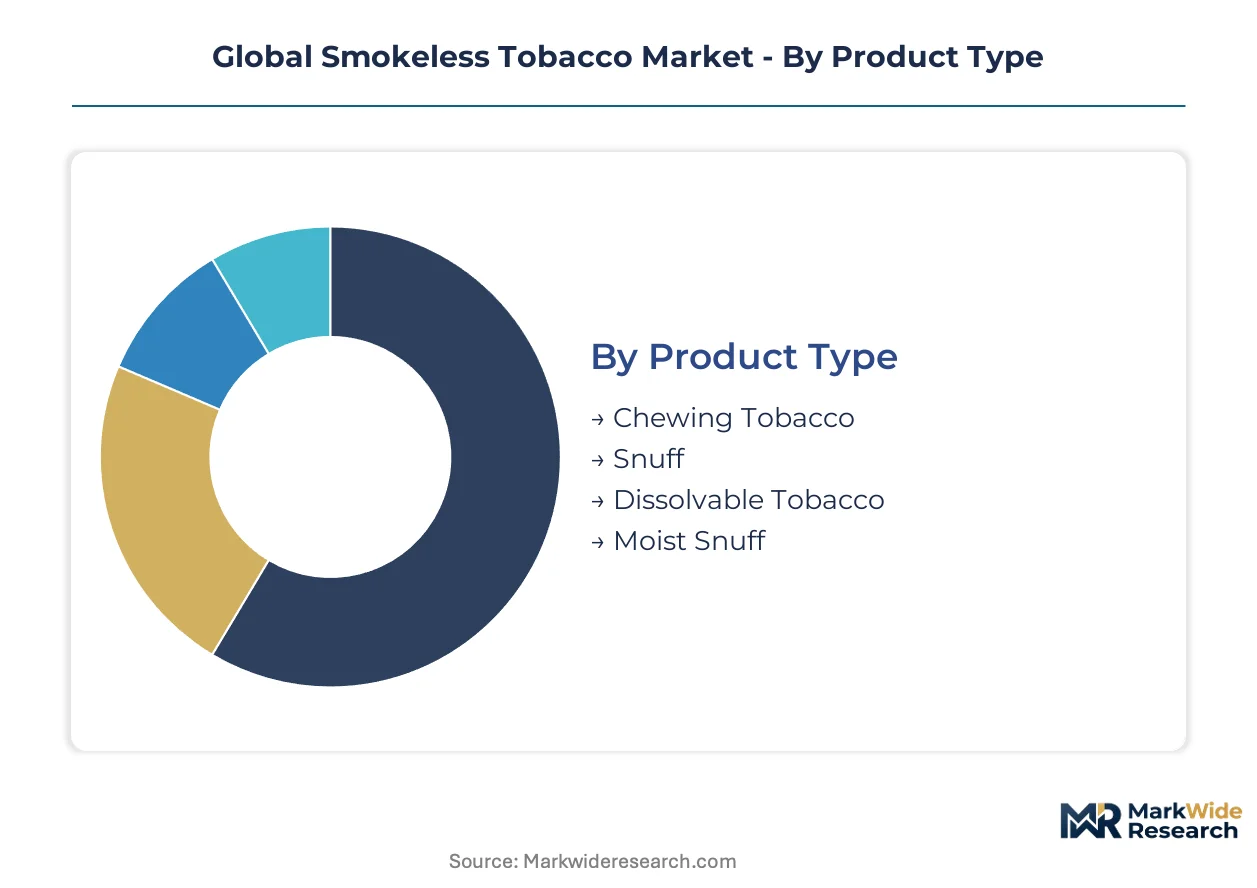
Product architecture, user demographics, and channel configuration determine margin capture in smokeless tobacco. Manufacturers optimize portfolio mix across these dimensions to align with divergent regulatory thresholds and consumption rituals.
Product Type:
Standalone oral products dominate shelf space, while embedded nicotine systems increasingly blur category boundaries.
- Moist Snuff:Pasteurized tobacco leaf with alkaline pH modifiers enables efficient buccal nicotine absorption. Demand concentrates in American convenience channels across Texas, Florida, and North Carolina, driven by established brand loyalty and repeat purchase frequency. Moist snuff leads volumes today; dissolvable tobacco is gaining share fastest.
- Snuff:Finely ground dry tobacco traditionally inhaled through the nasal cavity, though oral use variants persist in European markets. Scandinavian consumers in Sweden sustain portioned snus formats under differentiated harm-reduction frameworks permitted by the country's Public Health Agency.
- Chewing Tobacco:Fermented leaf strands requiring mastication for nicotine release, predominantly consumed in rural American markets and Indian subcontinent clusters.
- Dissolvable Tobacco:Compressed or molded products designed to dissolve completely in the mouth, navigating novel FDA premarket authorization pathways as non-combustible derivatives.
Moist snuff commands the largest revenue pool; dissolvable formats face the steepest regulatory climb.
End User:
Cost tier stratification separates ritual-dependent daily users from occasional purchasers sensitive to price-per-dose economics.
- Adults:Core demographic spanning recreational and habitual consumption patterns, with purchasing decisions influenced by workplace smoking restrictions and discrete usage requirements. Urban clusters in Seattle, Denver, and Austin demonstrate willingness to adopt subscription replenishment models.
- Premium Users:Consumers prioritizing flavor sophistication, packaging aesthetics, and provenance signaling over unit economics. This segment concentrates in coastal American metros and Scandinavian capitals where harm-reduction narratives justify price premiums.
- Young Adults:Demographic cohort accessing products through e-commerce platforms seeking flavor variety and social media-influenced brand discovery.
- Casual Users:Occasional purchasers with low switching costs, typically entering through convenience store impulse placement or social sharing contexts.
Adult recreational users anchor volume; premium users expand most quickly as manufacturers introduce elevated-tier pouch formats.
Distribution Channel:
Geographic concentration of channel infrastructure shapes regional competitive dynamics and margin structures.
- Convenience Stores:Direct-store-delivery systems achieve shelf dominance through American retail network density. Texas and Florida represent volume throughput leaders where immediate availability drives brand selection.
- Online Retail:Specialized e-commerce platforms fragment historical wholesale patterns among younger demographics in Minneapolis, Portland, and San Francisco. Subscription automation captures recurring revenue outside traditional margin structures.
- Supermarkets:Mass retail placement exposes products to broader demographic cross-sections, though shelf space allocation competes with combustible tobacco and nicotine replacement therapies.
- Vending Machines:Limited deployment in controlled-access environments such as industrial workplaces and military installations where smoking restrictions apply.
Convenience stores maintain volume leadership; online retail climbs the fastest as platform marketing spend rotates geographic demand patterns.
Packaging Type:
Supply concentration in specialized manufacturing clusters determines format availability and cost structures.
- Cans:Standardized cylindrical containers dominating moist snuff and chewing tobacco formats, with production infrastructure concentrated in Kentucky and Tennessee manufacturing bases.
- Pouches:Portioned sachets enabling discrete consumption and controlled dosing, manufactured through specialized alkaline pH modification processes in Gothenburg and Stockholm facilities.
- Packs:Flexible packaging for multi-unit retail presentation, common in Indian chewing tobacco and gutkha variants subject to BIS labeling mandates.
- Bottles:Rigid containers for loose snuff and granular products, declining share as portioned formats displace bulk packaging.
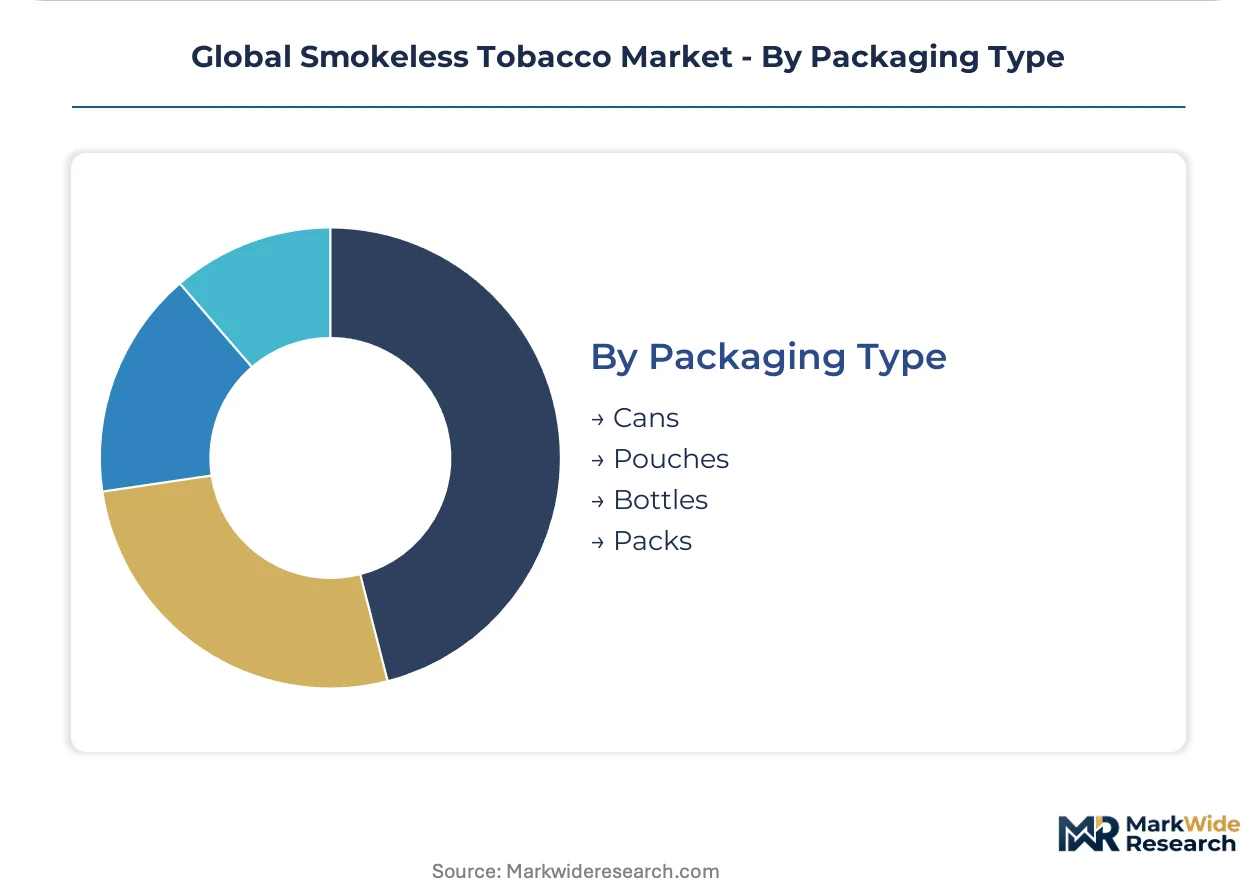
Cans lead installed base; pouches represent the steepest expansion trajectory as manufacturers prioritize portioned format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's harm-reduction framework permits snus under differentiated risk classifications, while India's FSSAI imposes strict BIS labeling mandates that reshape manufacturing compliance. These divergent regulatory environments create distinct competitive terrain for pasteurized leaf products versus chewing tobacco variants.
United States
Moist snuff demand concentrates in Texas, Florida, and North Carolina convenience channels where direct-store-delivery systems sustain repeat purchase frequency. The FDA Center for Tobacco Products enforces premarket tobacco product application requirements that compress development timelines for novel formulations. Urban clusters in Seattle, Denver, and Austin demonstrate accelerating adoption of subscription-based replenishment models.
Sweden
Portioned snus formats command sustained loyalty among adult recreational users under the Public Health Agency's differentiated risk classifications. REACH chemical registration requirements from ECHA reshape additive sourcing for products bound for broader European markets. Gothenburg and Stockholm manufacturing facilities anchor specialized alkaline pH modification infrastructure serving export demand.
India
Chewing tobacco and gutkha consumption persists across Mumbai and Delhi manufacturing clusters upgrading from informal production. The Food Safety and Standards Authority mandates BIS labeling compliance that rewards standardized manufacturing investments. Maharashtra and Gujarat production bases modernize quality systems to meet evolving packaging and traceability requirements.
Germany
Oral nicotine products face pharmaceutical classification review under EMA frameworks that extend approval timelines beyond tobacco pathways. The EU Tobacco Products Directive prohibits characterizing flavors, eliminating differentiation levers for new entrants. Bavaria and North Rhine-Westphalia distribution hubs navigate complex compliance layers for reduced-risk derivative portfolios.
United Kingdom
Reduced-risk oral nicotine derivatives gain traction among urban adult demographics seeking discrete consumption alternatives. MHRA evaluation protocols determine whether novel pouch formats achieve medicinal or consumer product status. London and Southeast England retail networks balance convenience channel presence with emerging e-commerce platform fragmentation.
Global Smokeless Tobacco Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated leaf processors commanding margin pools in moist snuff while synthetic nicotine formulators access distinct compliance pathways. The competitive structure concentrates around three archetypes: legacy combustible tobacco diversifiers, Scandinavian harm-reduction specialists, and emerging synthetic nicotine pure-plays. Consolidation pressure intensifies as FDA authorization backlogs favor incumbents with regulatory submission capacity. Geographic expansion and portfolio diversification represent the dominant competitive moves, with manufacturers acquiring regional distribution networks to bypass wholesale margin structures.
Among American market anchors, Altria Group exemplifies the legacy diversifier archetype through retail network depth, while Swedish Match occupies a position as the Scandinavian harm-reduction specialist with Gothenburg-based manufacturing infrastructure. British American Tobacco represents the multinational portfolio approach, extending across reduced-risk oral nicotine derivatives and traditional chewing blends. These three entities illustrate how regulatory navigation capabilities and channel control determine competitive positioning.
| Leading Market Players |
|---|
| Altria Group |
| Philip Morris International |
| British American Tobacco |
| Imperial Brands |
| Japan Tobacco |
| Swedish Match |
| DS Group |
| Swisher International |
| Mac Baren Tobacco Company |
| Others |
Value Chain & Pricing Dynamics
Specialized alkaline pH modification technicians in Gothenburg and Stockholm command wage premiums that compress manufacturing cost spreads between premium portioned snus and economy moist snuff tiers. Labor-cost differentials between Scandinavian specialized production and American mass-market facilities directly determine pricing-tier spreads across subscription and convenience channel offerings.
Pricing Analysis
Capacity additions in Kentucky and Tennessee dark-fired tobacco cultivation are reshaping price floors for moist snuff categories. Three-tier pricing structure across premium, standard, and economy levels separates FDA-authorized pouch formats from grandfathered loose snuff and value-tier chewing tobacco. Price differentiation stems from certification investment burdens and flavor sophistication R&D spend. Casual users in convenience channels exhibit highest price sensitivity; premium users in Scandinavian and coastal American metros demonstrate lowest elasticity due to harm-reduction narrative alignment.
Supply Chain Analysis
Premium dark-fired tobacco leaf supply rests on Kentucky and Tennessee cultivation belts with limited alternative sourcing. Raw material dependencies center on cured leaf grades, alkaline pH modifiers, and food-grade pouch substrates. Single-source vulnerability concentrates in specialized Gothenburg manufacturing infrastructure serving global portioned format demand. Distribution runs through direct-store-delivery systems dominating American convenience channels, with e-commerce platforms fragmenting downstream access among younger demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Sweden's harm-reduction regulatory permissions and India's BIS-mandated manufacturing modernization cost curves.
For Market Incumbents: Acquire specialized alkaline pH modification manufacturing facilities in Gothenburg and Stockholm to lock in portioned format capacity. Secure backward integration into Kentucky dark-fired tobacco cultivation to hedge weather-driven yield volatility. Channel control through direct-store-delivery systems defends against subscription-platform disintermediation threatening convenience store margin structures.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian chewing tobacco modernization offers white-space entry through BIS-compliant manufacturing investments. Target Mumbai and Delhi manufacturing clusters upgrading from informal production. Synthetic nicotine derivative portfolios bypass tobacco-specific FDA pathways. Direct-to-consumer subscription platforms in Seattle, Denver, and Austin urban clusters enable format trial without wholesale margin burdens.
For Investors and Strategic Acquirers: Scandinavian harm-reduction specialists are the most active acquirer in this space, consolidating specialized manufacturing infrastructure. Long-term viability hinges on regulatory navigation capacity across divergent FDA, EMA, and FSSAI frameworks. Acquisition target archetype: vertically integrated pouch manufacturers with REACH-compliant additive sourcing. Watch FDA premarket tobacco product application backlog resolution as inflection indicator for novel formulation launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Authorization Investment | FDA premarket tobacco product applications determine legal sale status for novel pouch formats in the United States. |
| Specialized Manufacturing Capacity Expansion | Gothenburg and Stockholm alkaline pH modification facilities anchor global portioned snus supply reliability. |
| Direct-to-Consumer Platform Launch | Subscription automation in Seattle, Denver, and Austin bypasses convenience store margin structures. |
| Backward Integration into Leaf Supply | Kentucky and Tennessee dark-fired tobacco cultivation concentration creates weather-exposure vulnerabilities. |
| Synthetic Nicotine Portfolio Development | Non-tobacco nicotine sources access distinct compliance pathways outside tobacco-specific regulations. |
Study Parameters
Coverage spans North America, Scandinavia, and South Asia, with primary inputs from each regional cluster. Primary interviews combined regulatory affairs specialists at FDA and EMA, manufacturing executives at Gothenburg and Stockholm production facilities, and convenience channel category buyers in Texas and Florida. Secondary validation drew from FDA Center for Tobacco Products filings, ECHA REACH registration databases, FSSAI compliance notifications, and customs trade records. Bottom-up volume triangulation across product formats reconciled with top-down market sizing.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product architecture, user demographic tier, and channel configuration. Modeled dimensions included moist snuff versus dissolvable formats, premium versus casual user segments, and convenience store versus online retail channels. CAGRs derived from historical consumption pattern analysis and regulatory timeline overlay. Industry-specific forecast inputs incorporated FDA authorization backlog projections and REACH chemical registration compliance costs.
Caveats apply where FDA premarket review capacity constraints, EU flavor restriction implementations, or Indian BIS enforcement intensity could materially shift the outlook. Forecasts reflect assumptions about regulatory pathway stability and consumer substitution elasticity between formats. A small set of named triggers warrants ongoing watch: FDA authorization timeline compression, EMA pharmaceutical classification rulings, and FSSAI traceability mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
Tobacco Products Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Luxury Cigarette Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
E-Cigarette and Vaping Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
Japan Heated Tobacco Products Market