
 Moonstone Market | 2026-2036
Moonstone Market Size, Share, and Industry Trends Forecast 2026-2036
Moonstone Market Outlook
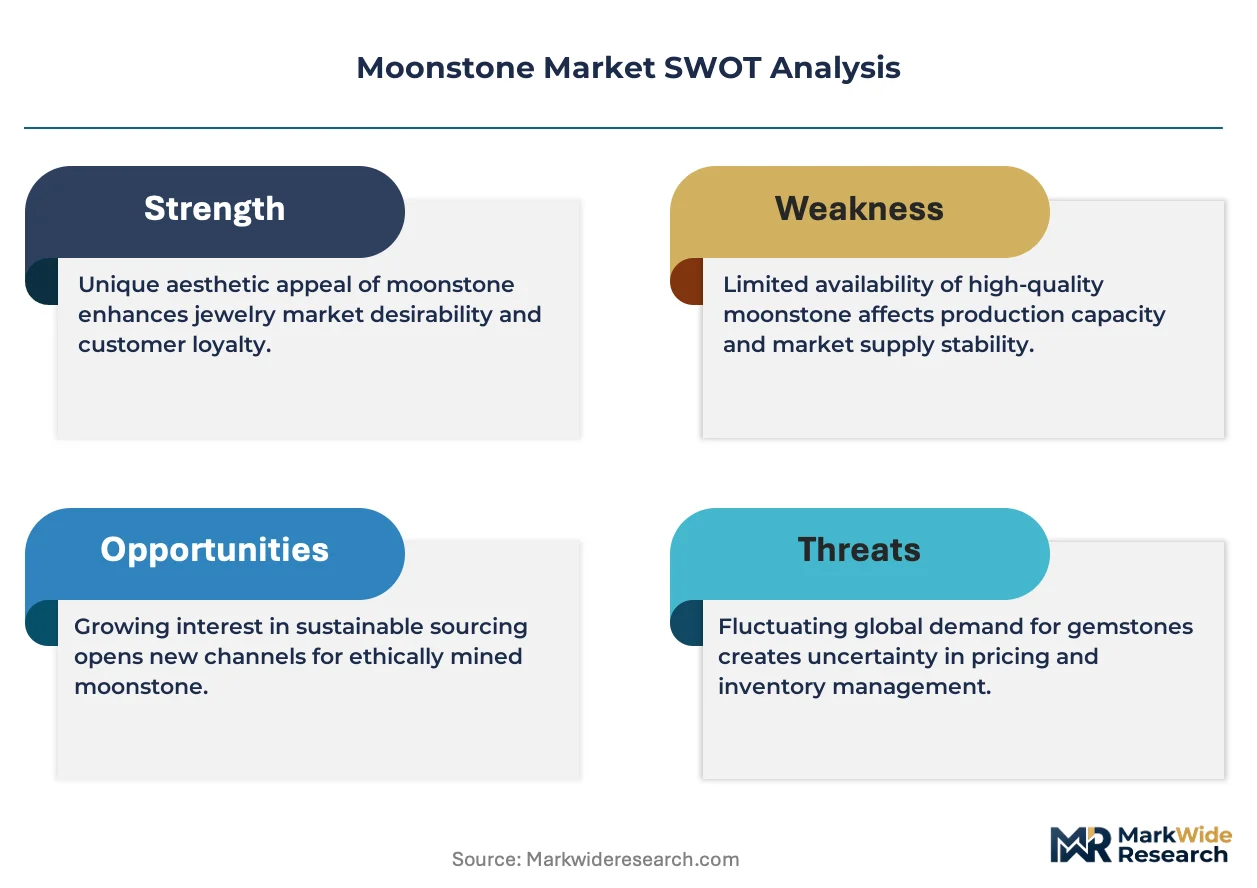
Subscription-based gem certification and digital provenance tracking is consolidating how moonstone gets sold, shifting value from one-time transactions to recurring trust services. Purin Mineral Group Company leverages captive Sri Lankan mines to sustain rough supply consistency. Asia Mineral Processing Co. Ltd. anchors Southeast Asian distribution through Bangkok's gem trading hub. GP Minerals differentiates via specialized heat-treatment capabilities that stabilize adularescence in lower-grade rough.
Moonstone is a potassium aluminum silicate feldspar characterized by its distinctive adularescence—a billowy, milky sheen caused by alternating orthoclase and albite layers typically measuring 0.3 to 0.5 microns in thickness. Gem cutters orient cabochons perpendicular to these lamellar structures to maximize optical effect, serving both ornamental jewelry and metaphysical retail segments. The jewelry product category commands the deepest margin pools due to finished-setting premiums, while raw stones represent a volume-driven, price-sensitive trade serving lapidary workshops and crystal therapy distributors. Online retail channels are expanding fastest among distribution pathways, though physical stores in Istanbul, Jaipur, and Bangkok retain dominance for high-value, inspection-dependent transactions.
India's BIS mandates laboratory certification for imported gemstones, while Sri Lanka's National Gem and Jewellery Authority enforces export licensing for rough moonstone. The EU's REACH framework restricts certain chemical treatments used to enhance adularescence, reshaping processing standards for European-bound material. Stakeholders must monitor evolving traceability requirements and decide whether to invest in blockchain-based provenance systems or risk exclusion from premium market tiers.
Market Dynamics
India's BIS certification mandate is compressing import timelines for rough moonstone while simultaneously elevating quality thresholds, forcing procurement networks to reconfigure around accredited testing laboratories rather than informal broker channels.
Growth Catalysts
- EU REACH framework:Restrictions on chemical adularescence enhancement are pushing processors toward heat-treatment methods, creating specialized capability premiums for compliant workshops.
- Bridal jewelry demand:Indian designers are expanding calibrated cabochon procurement for wedding collections, anchoring volume commitments in Jaipur's cutting cluster.
- Blockchain provenance systems:Digital traceability infrastructure is converting one-time gem transactions into recurring certification revenue streams across European and Middle Eastern buyer networks.
Market Restraints
- Sri Lankan supply concentration:Rough moonstone export licensing through the National Gem and Jewellery Authority creates single-point vulnerability for upstream material access.
- Adularescence stabilization limits:Lower-grade rough requires heat-treatment to maintain optical performance, constraining yield rates and usable output volumes.
- Labradorite substitution:Feldspar alternatives with similar schiller effects compete for price-sensitive metaphysical retail segments, compressing entry-grade moonstone pricing.
Strategic Opportunities
- Subscription certification models:Recurring trust services are displacing transactional gem sales, enabling annuity revenue capture from collector and investor segments.
- Online retail channel expansion:Digital platforms are accelerating fastest among distribution pathways, particularly for standardized cabochon grades below inspection-dependent transaction thresholds.
- Thailand's Bangkok hub:Southeast Asian trading infrastructure offers underutilized consolidation points for rough material flowing from Sri Lankan mines to Indian processing centers.
Industry Challenges
- Lapidary skill scarcity:Cabochon cutters capable of orienting stones perpendicular to 0.3-0.5 micron lamellar structures are concentrated in aging artisan pools across Jaipur and Istanbul.
- Blockchain integration complexity:Legacy inventory systems in family-run gem trading houses resist seamless connection to emerging provenance tracking platforms.
- BIS laboratory backlog:Certification queue compression is delaying import clearances and extending working capital cycles for rough procurement operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moonstone Market |
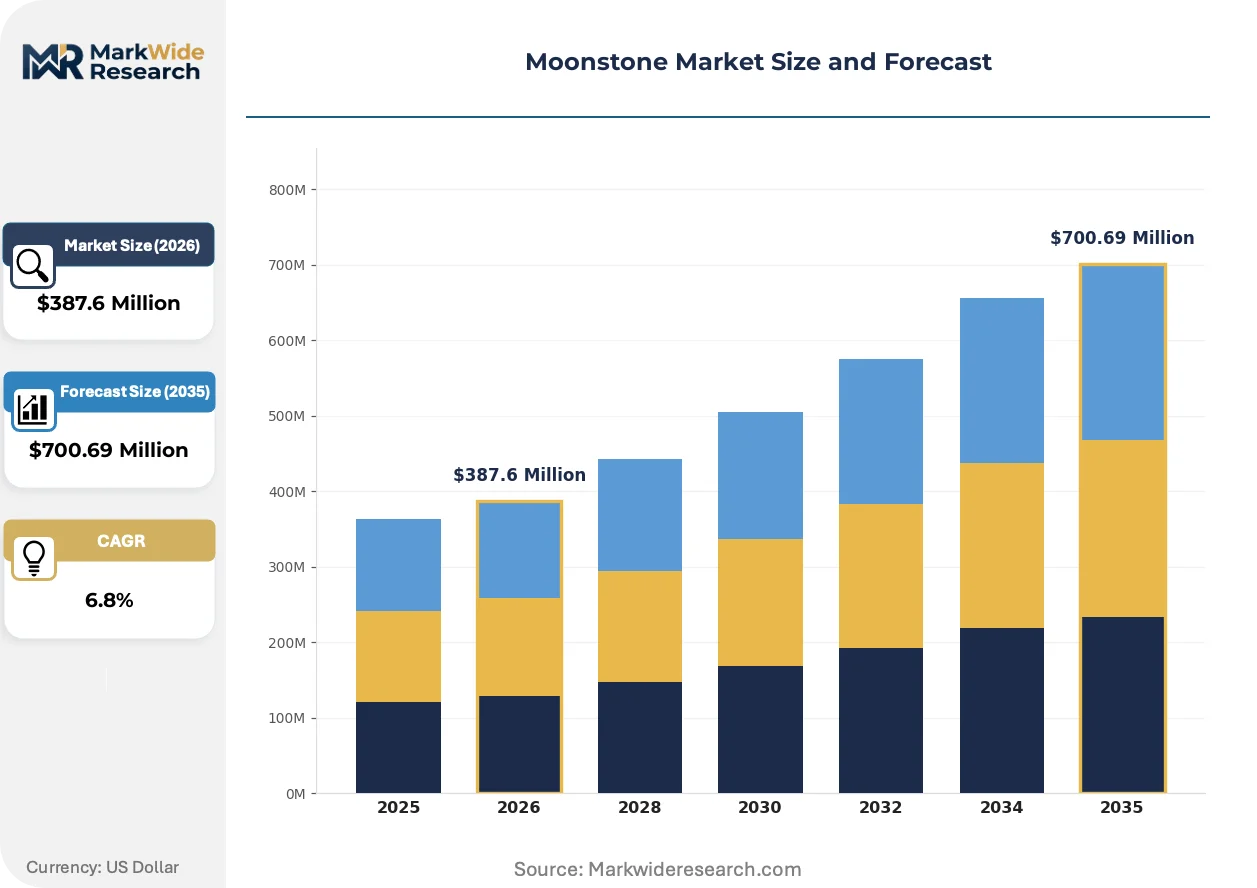
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jewelry, Beads, Cabochons, Raw Stones End User: Retail Customers, Jewelry Designers, Collectors, Manufacturers Distribution Channel: Online Retail, Physical Stores, Trade Shows, Wholesale Market Segment: Luxury, Fashion, Handmade, Others |
| Companies Covered | Purin Mineral Group Company, Hunan Jinxuan Hailing Trading Co., Ltd., Asia Mineral Processing Co. Ltd., ABK Styl, Zucchelli Preziosi, GP Minerals, Incusa Industrias Del Cuarzo, Abrar Enterprises, Micronized Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moonstone Market Strategic Shifts
Digital infrastructure is reconstruing how moonstone moves from mine to finished setting, with three distinct vectors reshaping competitive positioning across extraction, processing, and retail layers.
Spectral imaging systems for lamellar structure mapping are converging with automated cutting guidance software to reduce yield loss in cabochon production. Mid-scale Jaipur workshops are piloting these systems to optimize orientation decisions previously dependent on individual cutter judgment. The technology is converging with traditional hand-finishing stages, preserving artisanal output quality while compressing rough-to-polished cycle times.
India's BIS laboratory certification mandate for imported gemstones is tightening documentary requirements and eliminating informal entry channels previously used for lower-grade rough. Processing workshops must now route all material through accredited testing facilities before cutting operations commence. Small-volume importers are consolidating purchasing power through buying cooperatives to amortize per-lot certification costs across larger shipments.
Collector preference is rotating toward documented provenance and treatment disclosure over purely aesthetic assessment. Physical retail channels in Istanbul, Jaipur, and Bangkok are responding by unbundling certification services from merchandise sales, offering subscription-based verification renewals. This behavioral shift is most pronounced in European buyer networks where resale liquidity depends on transferable documentation packages.
Moonstone Market Segmentation
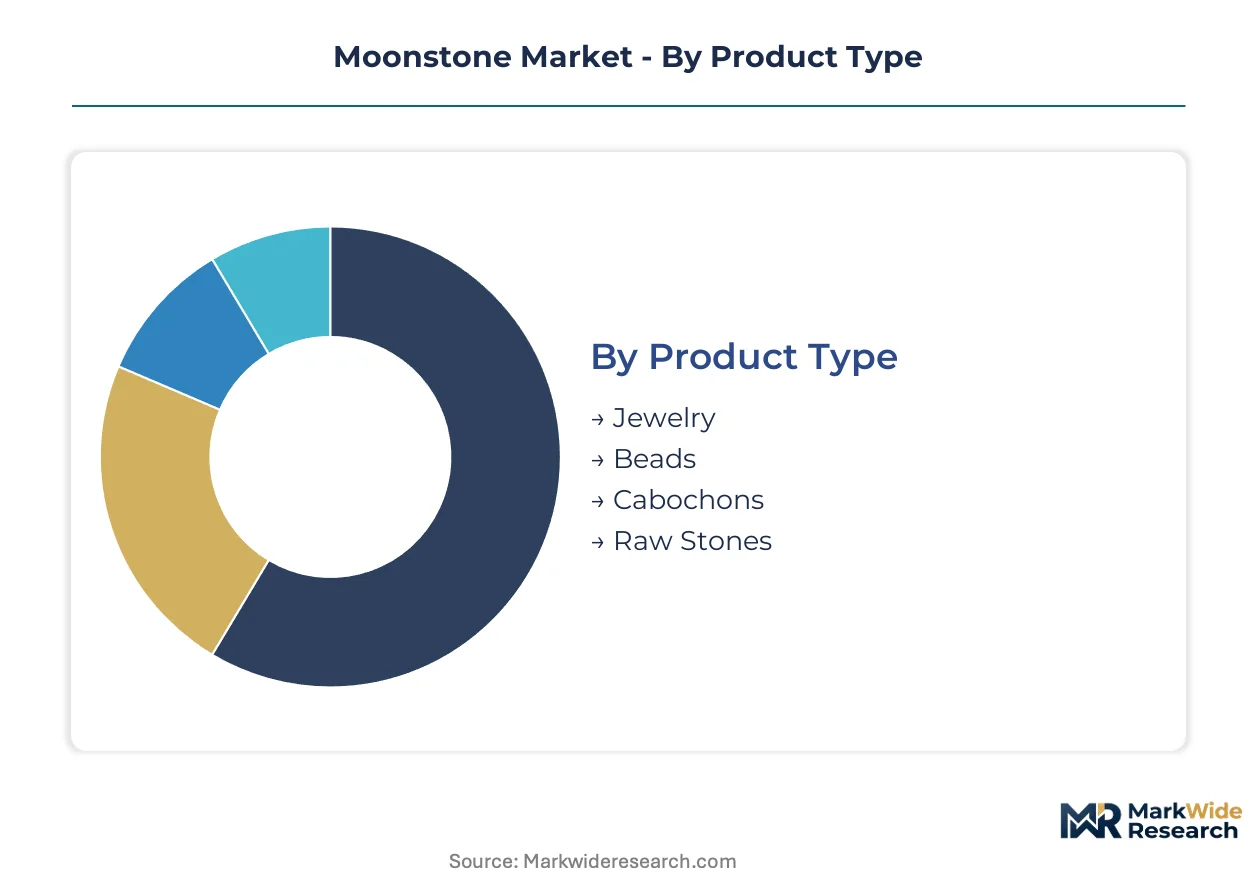
Moonstone segmentation reveals how value migrates across transformation stages, from unprocessed rough through finished jewelry settings. Understanding these category boundaries exposes where margin pools concentrate and which buyer types drive specification requirements.
Product Type:
Buyers differentiate by processing depth and optical performance requirements rather than mineral composition alone.
- Jewelry:Finished settings command premium multiples through design IP and metalwork integration. Indian bridal collections in Jaipur anchor volume demand for calibrated pieces with documented adularescence stability.
- Raw Stones:Unprocessed rough from Sri Lankan mines flows to cutting clusters under export licensing constraints. Procurement networks prioritize consistent lamellar structure over carat weight for yield optimization.
- Cabochons:Polished domes require perpendicular orientation to 0.3-0.5 micron layers. Istanbul and Jaipur workshops specialize in maximizing optical effect for inspection-dependent transactions.
- Beads:Drilled spheres serve volume-driven metaphysical retail with lower specification thresholds. Price sensitivity dominates procurement decisions in this tier.
Jewelry leads volumes today; raw stones are gaining share fastest through vertically integrated mine-to-cutting networks.
End User:
Specification authority varies dramatically by buyer sophistication and purchase frequency.
- Jewelry Designers:Calibrated cabochon procurement for bridal collections drives volume commitments. BIS certification mandates force documentary rigor on Indian designers sourcing imported rough.
- Retail Customers:Individual purchasers prioritize aesthetic adularescence over technical documentation. Online channels capture standardized grades below inspection thresholds.
- Collectors:Documented provenance and treatment disclosure outweigh pure visual assessment. Subscription-based certification renewals generate recurring revenue from this segment.
- Manufacturers:Lapidary workshops and crystal therapy distributors process volume-driven material with yield-sensitive pricing.
Jewelry designers anchor current procurement volumes; collectors are expanding most quickly through provenance-premium transactions.
Distribution Channel:
Channel selection tracks transaction value and inspection dependency rather than buyer type alone.
- Online Retail:Digital platforms accelerate fastest for standardized cabochon grades. Bangkok-based traders leverage this channel for Southeast Asian distribution reach.
- Physical Stores:Istanbul, Jaipur, and Bangkok locations retain dominance for high-value, inspection-dependent sales. Optical performance verification requires direct handling.
- Wholesale:Bulk material flows from Sri Lankan mines through accredited testing facilities before cutting operations commence.
- Trade Shows:Periodic consolidation points enable rough material inspection and relationship maintenance across dispersed mining and cutting networks.
Physical stores dominate value concentration; online retail climbs the fastest as certification standardization reduces inspection requirements.
Market Segment:
Positioning tiers separate by price point, production method, and customer occasion rather than material grade alone.
- Luxury:Documented provenance and treatment disclosure enable resale liquidity. European buyer networks demand transferable certification packages for collector-grade material.
- Fashion:Trend-driven jewelry cycles prioritize design refresh speed over long-term value retention. Volume throughput characterizes this tier.
- Handmade:Artisan production methods command modest premiums through craft narrative. Istanbul and Jaipur workshops specialize in this positioning.
- Others:Industrial and metaphysical applications occupy price-sensitive volume tiers with minimal specification requirements.
Fashion commands the broadest volume base; luxury shows the steepest expansion trajectory through provenance-premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India commands rough moonstone processing volume while Sri Lanka controls upstream mine supply, creating interdependent trade flows that define regional competitive dynamics across Asia's gem corridor.
India
Jaipur's cutting and polishing cluster processes calibrated cabochons for bridal jewelry collections, driving procurement volume from domestic designers. The BIS gemstone certification mandate tightens quality thresholds for imported rough, eliminating informal broker channels. Processing workshops now route all material through accredited testing facilities before cutting operations commence.
Sri Lanka
The National Gem and Jewellery Authority enforces export licensing for rough moonstone, concentrating upstream supply control in state-regulated channels. Purin Mineral Group Company leverages captive domestic mines to sustain rough supply consistency for international buyers. Colombo-based exporters face documentary rigor that delays shipments but elevates material traceability premiums.
Thailand
Bangkok's gem trading hub anchors Southeast Asian distribution infrastructure for moonstone flowing from Sri Lankan mines to Indian processing centers. Asia Mineral Processing Co. Ltd. consolidates regional wholesale throughput through established trading relationships. The city's physical auction houses retain dominance for high-value, inspection-dependent rough transactions.
Turkey
Istanbul's Grand Bazaar district maintains artisanal cutting specialization for cabochon orientation perpendicular to lamellar structures. Retail storefronts serve Middle Eastern collector networks demanding documented provenance for resale liquidity. Turkish workshops compete on craft narrative premiums rather than volume scale.
Italy
Vicenza's jewelry manufacturing district integrates moonstone into fashion-forward silver and gold settings for European luxury brands. Zucchelli Preziosi exemplifies mid-scale Italian fabricators balancing design IP with gemstone procurement flexibility. The EU REACH framework restricts chemical adularescence enhancement, pushing Italian processors toward heat-treatment compliance.
Moonstone Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated mine-to-retail operators commanding premium positioning while trading houses compete on procurement network breadth. The vendor base organizes around three strategic archetypes: captive mine operators controlling Sri Lankan rough supply, specialized heat-treatment workshops stabilizing optical performance, and certification-integrated retailers capturing recurring trust revenue. Consolidation pressure concentrates among mid-scale Indian cutting workshops facing BIS compliance cost amortization challenges. Dominant competitive moves include backward integration into Sri Lankan mining concessions and technology licensing for spectral imaging-based cutting optimization.
Among mine-origin specialists, Purin Mineral Group Company exemplifies captive supply control through Sri Lankan concessions. GP Minerals anchors the processing tier through specialized heat-treatment capabilities that stabilize adularescence in lower-grade rough. Asia Mineral Processing Co. Ltd. represents Bangkok-based distribution consolidation, channeling Southeast Asian material flows toward Indian fabrication centers. These three archetypes illustrate how competitive positioning fragments across extraction, processing, and trading layers rather than concentrating in integrated conglomerates.
| Leading Market Players |
|---|
| Purin Mineral Group Company |
| Hunan Jinxuan Hailing Trading Co., Ltd. |
| Asia Mineral Processing Co. Ltd. |
| ABK Styl |
| Zucchelli Preziosi |
| GP Minerals |
| Incusa Industrias Del Cuarzo |
| Abrar Enterprises |
| Micronized Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between BIS-accredited laboratory material and informal-channel rough creates divergent margin structures across Indian processing workshops and Sri Lankan export channels. This tier split manifests in procurement cost differentials of roughly 15-25% for equivalent carat weights, with certified material commanding working capital premiums that informal brokers cannot match.
Pricing Analysis
Capacity additions in Jaipur's cutting cluster are reshaping price floors for calibrated cabochons as automated spectral imaging reduces yield loss and compresses rough-to-polished cycle times. Three-tier pricing structure across premium, standard, and economy levels tracks adularescence stability, treatment disclosure completeness, and lamellar structure consistency. Pricing pressure stems from labradorite substitution in metaphysical retail segments, eroding entry-grade moonstone price points. Manufacturers and bead distributors exhibit highest price sensitivity, while European collectors prioritize documented provenance over per-carat cost.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in moonstone distribution, though collector-grade material generates secondary market recertification demand through subscription-based provenance renewals. Sri Lanka, India, and Thailand anchor upstream-to-downstream flows, with rough extraction concentrated in Sri Lankan mines under National Gem and Jewellery Authority licensing. Processing draws from orthoclase-albite layered deposits, heat-treatment stabilization capacity, and BIS laboratory certification infrastructure. Single-source vulnerability concentrates in Sri Lankan export licensing, where regulatory delays cascade through Indian cutting schedules. Distribution runs through Bangkok's gem trading hub for Southeast Asian consolidation, with physical auction houses retaining dominance for inspection-dependent rough transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification mandate functions as a regulatory compounder, accelerating consolidation among mid-scale cutting workshops unable to amortize per-lot testing costs across sufficient shipment volumes.
For Market Incumbents: Deploy spectral imaging automation to compress yield loss and defend margin position against Jaipur workshops adopting comparable technology. Consolidate purchasing power through buying cooperatives to offset BIS laboratory backlog delays. Labradorite substitution in price-sensitive metaphysical channels threatens entry-grade volume; respond with treatment-disclosure transparency that alternative feldspars cannot match. For New Entrants and Emerging Players: Blockchain-based provenance infrastructure offers technology-first entry into European collector networks where resale liquidity depends on transferable documentation packages. Target underpenetrated online retail channels for standardized cabochon grades below inspection-dependent transaction thresholds. Partner with Bangkok-based traders for Southeast Asian distribution reach without building physical auction infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS compliance costs exceed small-volume importer cash flow capacity, creating acquisition opportunities for scaled operators. Long-term viability favors vertically integrated mine-to-certification networks with captive Sri Lankan rough supply. Monitor blockchain provenance adoption rates in European buyer networks as inflection indicator for recurring revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sri Lankan Mining Concessions | Purin Mineral Group Company's captive supply model eliminates export licensing exposure for rough procurement. |
| Heat-Treatment Capability Investment | GP Minerals' specialized stabilization technology commands premium positioning under EU REACH chemical treatment restrictions. |
| Blockchain Provenance Platform Deployment | Digital infrastructure converts one-time gem transactions into recurring certification revenue from collector segments. |
| Buying Cooperative Formation | Small-volume Indian importers amortize BIS per-lot certification costs across consolidated shipment volumes. |
| Online Retail Channel Expansion | Bangkok-based traders leverage digital platforms for standardized cabochon distribution across Southeast Asia. |
Study Parameters
Multiple input streams — primary interviews with mine operators, cutting workshop owners, and gem certification laboratory directors; secondary validation through Sri Lankan National Gem and Jewellery Authority export records, Indian BIS laboratory processing statistics, and Bangkok gem auction transaction data; plus customs documentation for rough material flows — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned Jaipur cluster supervisors, Istanbul Grand Bazaar artisans, European jewelry procurement managers, and metaphysical retail distributors.
Data-stream reconciliation anchored volume and value projections across product type, end user sophistication, distribution channel, and market positioning tier dimensions. CAGRs were derived from segmented growth rate modeling incorporating bridal jewelry procurement cycles, collector documentation preference shifts, and online retail penetration trajectories. Industry-specific inputs included adularescence stabilization yield rates and BIS laboratory queue compression effects on import clearance timelines.
The model holds under stable Sri Lankan export licensing enforcement and continued BIS mandate expansion; deviation in regulatory relaxation or blockchain provenance standardization would shift competitive positioning toward informal channels or technology-integrated retailers respectively. Practitioners should monitor EU REACH enforcement intensity and Indian laboratory capacity additions for early signals of processing cost trajectory changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Computing Devices Market
Others
Quadrant Scale Market
Others
Gas Radiators Market
Others
Refractometer Market
Others
Global Process Equipment Market
Others
Advertising Intelligence Solution Market
Others
Brown Ht Market
Others
Couscous Market
Others
Light Meter Market
Others
North America Machine Vision Systems Market
Others
Hip Tendinitis Market
Others
Video Paas Market
Others
Japan Indoor LBS Market
Others
North America IT Device Market
Others
Global Military and Aerospace Sensors Market
Others
Sports Events Market