
 Latin America IT Device Market | 2026-2036
Latin America IT Device Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America IT Device Market Foresight
Direct-to-enterprise distribution is narrowing as manufacturers bypass traditional wholesalers in Brazil and Mexico. Dell Technologies leverages vertical integration to control server-to-workstation bundles for Latin American banks. Lenovo Group anchors its regional position through localized assembly capacity in São Paulo state. Samsung Electronics competes on display panel technology leadership across the education procurement channel.
Latin America IT devices encompass computing hardware with processors, memory modules, storage systems, and network interfaces designed for data processing, communication, and enterprise workflow execution. These systems typically operate on x86 or ARM architectures with thermal design power ratings between 15W and 250W depending on form factor and workload intensity. Laptops and tablets capture expanding share as hybrid work protocols persist across regional enterprises, while desktop workstations retain margin concentration in engineering and media production verticals. Cloud Computing integration through edge-ready devices is displacing legacy on-premise infrastructure spending among mid-market buyers.
ANATEL certification requirements in Brazil and IFETEL standards in Mexico govern electromagnetic compatibility and radio frequency emissions for all networked IT equipment entering these markets. Brazil's Lei Geral de Proteção de Dados and Mexico's Federal Law on Protection of Personal Data Held by Private Parties mandate hardware-level encryption capabilities, redirecting procurement budgets toward security-certified device portfolios. Stakeholders must monitor evolving data-localization mandates as regulators across Colombia, Chile, and Peru draft comparable frameworks that will reshape supplier qualification criteria and channel economics.
Market Dynamics
Enterprise cloud migration is restructuring procurement authority across Latin America, shifting budget control from IT departments to finance-led cloud governance committees that specify edge-ready hardware requirements.
Growth Catalysts
- LGPD Hardware Mandates:Brazil's Lei Geral de Proteção de Dados forces replacement cycles for non-compliant storage devices, creating pull for encryption-certified workstations in São Paulo's banking corridor.
- Edge Computing Deployment:Manufacturing automation in Mexico's Bajío region demands ruggedized industrial PCs with localized processing capabilities to reduce latency for quality control systems.
- Education Technology Procurement:Chile's national digital classroom program drives volume demand for ARM-based tablets and ChromeOS devices through centralized ministry tenders.
Market Restraints
- Import Duty Structure:Brazil's industrialized goods tax (IPI) and Mercosur external tariff add cost layers that inflate endpoint prices versus North American benchmarks.
- Panel Supply Concentration:Display module sourcing clusters in East Asian fabrication facilities, exposing Latin American assemblers to ocean freight volatility and currency mismatch risks.
- Local Content Requirements:Argentina's import substitution mandates for government procurement create SKU fragmentation that elevates inventory carrying costs for distributors.
Strategic Opportunities
- Colombia Financial Services:Bogotá's expanding fintech ecosystem lacks mature workstation procurement channels, creating first-mover advantage for direct enterprise sales models.
- 5G-Enabled Field Devices:Convergence of millimeter-wave modules with fanless industrial designs opens mobile inspection and agricultural monitoring applications across Brazilian agribusiness.
- Peru Data Localization Draft:Pending personal data protection legislation mirrors LGPD hardware requirements, positioning encryption-capable device portfolios ahead of regulatory finalization.
Industry Challenges
- ANATEL Certification Timelines:Brazil's electromagnetic compatibility testing backlog extends product launch windows by four to six months, compressing revenue recognition for new form factors.
- Legacy Infrastructure Integration:Mexican enterprise buyers operate heterogeneous Windows 7 and Linux environments that complicate modern endpoint management platform rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America IT Device Market |
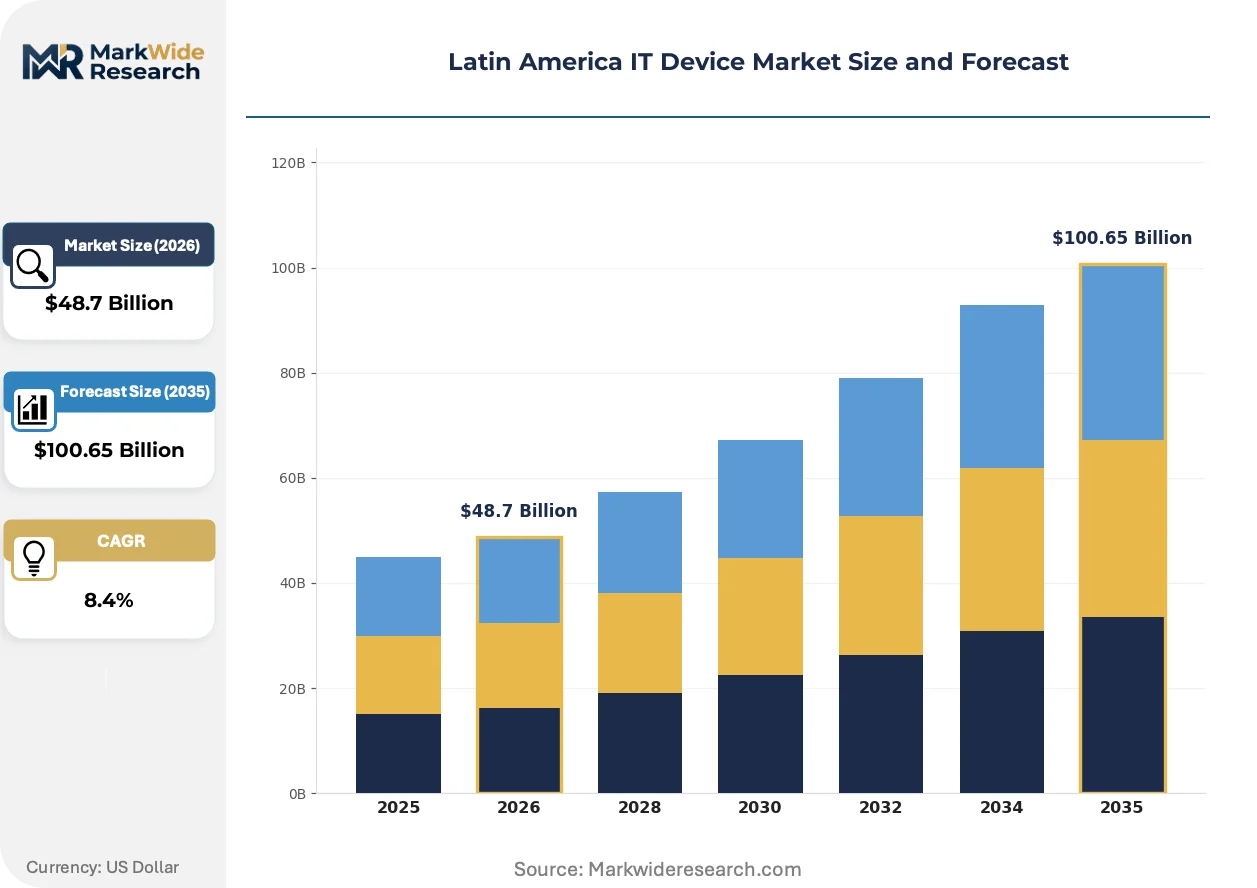
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Desktops, Tablets, Workstations Technology: Cloud Computing, Artificial Intelligence, IoT, Virtual Reality End User: Education Sector, Government Agencies, Enterprises, Healthcare Providers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Value-Added Resellers |
| Companies Covered | Dell Technologies, Xiaomi Corporation, Samsung Electronics, ASUSTek Computer Inc, Huawei Technologies, Lenovo Group, HP Inc, Acer Group, Apple Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America IT Device Market Shifts & Advancements
Compute architectures are fragmenting across workload-specific optimizations, with artificial intelligence inference and video collaboration demands pulling hardware design in divergent thermal and memory directions.
Arm-based system-on-chip designs are migrating from mobile-first positioning into enterprise laptop and desktop segments. Brazilian software development houses and Mexico City creative agencies are adopting these platforms for battery endurance and thermal efficiency in shared workspace environments. The transition is migrating from niche procurement experiments toward mainstream corporate standardization as Windows-on-Arm application compatibility matures.
ANATEL certification requirements in Brazil and IFETEL standards in Mexico now mandate hardware-level secure boot and firmware attestation for all networked equipment categories. These frameworks disqualify gray-market imports and uncertified refurbished devices from legitimate channel distribution. Enterprise buyers in São Paulo's financial district are responding by consolidating supplier relationships around manufacturers with established local testing laboratory partnerships.
Device-as-a-service contracting is displacing capital expenditure purchasing among mid-market Latin American enterprises. Managed service providers in Mexico and Colombia are bundling hardware refresh cycles with helpdesk and endpoint security services under per-seat monthly arrangements. This model concentrates most visibly in professional services and healthcare verticals where balance sheet optimization outweighs ownership preferences.
Latin America IT Device Market Segmentation
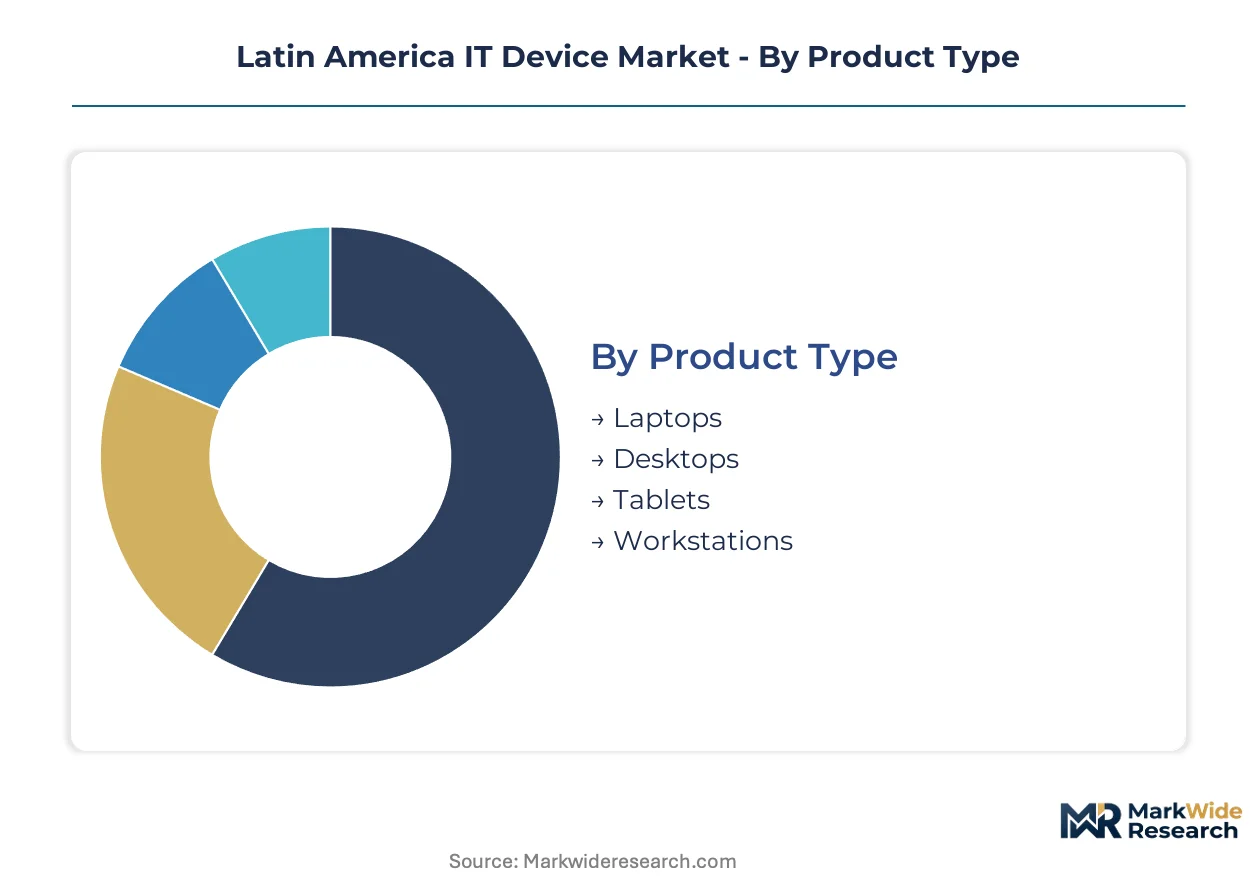
Latin America IT device procurement patterns diverge sharply across customer types and technical specifications, with regulatory mandates and channel economics driving portfolio fragmentation. Understanding these splits reveals where encryption requirements, certification timelines, and localization pressures reshape supplier economics.
Product Type:
Cost tier stratification separates volume-driven segments from margin-protected categories across Brazilian and Mexican procurement channels.
- Laptops:These mobile computing platforms integrate x86 or ARM processors with thermal envelopes between 15W and 65W, balancing performance against battery endurance for hybrid work environments. Demand concentrates in São Paulo's professional services firms and Mexico City corporate headquarters where LGPD-compliant encryption modules are becoming non-negotiable procurement criteria.
- Workstations:High-performance fixed computing systems with discrete GPUs and 250W thermal design power ratings serve engineering simulation and media rendering workloads. Financial services clusters in São Paulo's Faria Lima corridor and Bogotá's fintech district drive replacement cycles as data-localization mandates force hardware-level security upgrades.
- Desktops:Standard office computing systems with integrated graphics and 65W processors dominate education ministry tenders and government procurement frameworks across Chile and Colombia.
- Tablets:ARM-based slate devices with passive cooling and cellular connectivity serve field inspection and agricultural monitoring applications across Brazilian agribusiness operations.
Laptops hold installed capacity. Workstations are rotating up the share rankings.
Technology:
Application intensity separates infrastructure-enabling platforms from emerging interface technologies in regional enterprise budgets.
- Cloud Computing:Edge-ready hardware configurations with localized processing capabilities reduce latency for distributed enterprise workloads. Manufacturing automation in Mexico's Bajío region and quality control systems across Brazilian industrial parks are pulling these devices into operational technology environments previously served by on-premise servers.
- Artificial Intelligence:Inference-optimized accelerators with dedicated neural processing units enable real-time pattern recognition for financial fraud detection and medical imaging analysis. Deployment concentrates in São Paulo's banking corridor where ANATEL-certified secure boot requirements intersect with AI governance frameworks.
- IoT:Networked sensor gateways and industrial controllers with hardened enclosures serve predictive maintenance and supply chain visibility applications.
- Virtual Reality:Head-mounted displays with positional tracking and high-refresh panels support training simulation and design visualization in specialized enterprise verticals.
Cloud Computing holds installed capacity. Artificial Intelligence is climbing the fastest.
End User:
Customer type determines procurement authority structures and compliance burden intensity across national markets.
- Enterprises:Private sector organizations with finance-led technology governance committees specify edge-ready hardware requirements and device-as-a-service contracting terms. Procurement authority in Mexico City and São Paulo has shifted from IT departments to cloud governance structures that mandate security-certified portfolios.
- Education Sector:Ministry-led centralized tenders across Chile, Colombia, and Peru drive volume demand for ARM-based tablets and ChromeOS devices with specific local content requirements.
- Government Agencies:Public sector procurement frameworks in Brazil and Argentina impose local assembly mandates and ANATEL certification requirements that fragment SKU availability.
- Healthcare Providers:Hospital systems and clinic networks prioritize hardware-level encryption for patient data protection under evolving data-localization regulations.
Enterprises hold installed capacity. Education Sector is gaining share fastest.
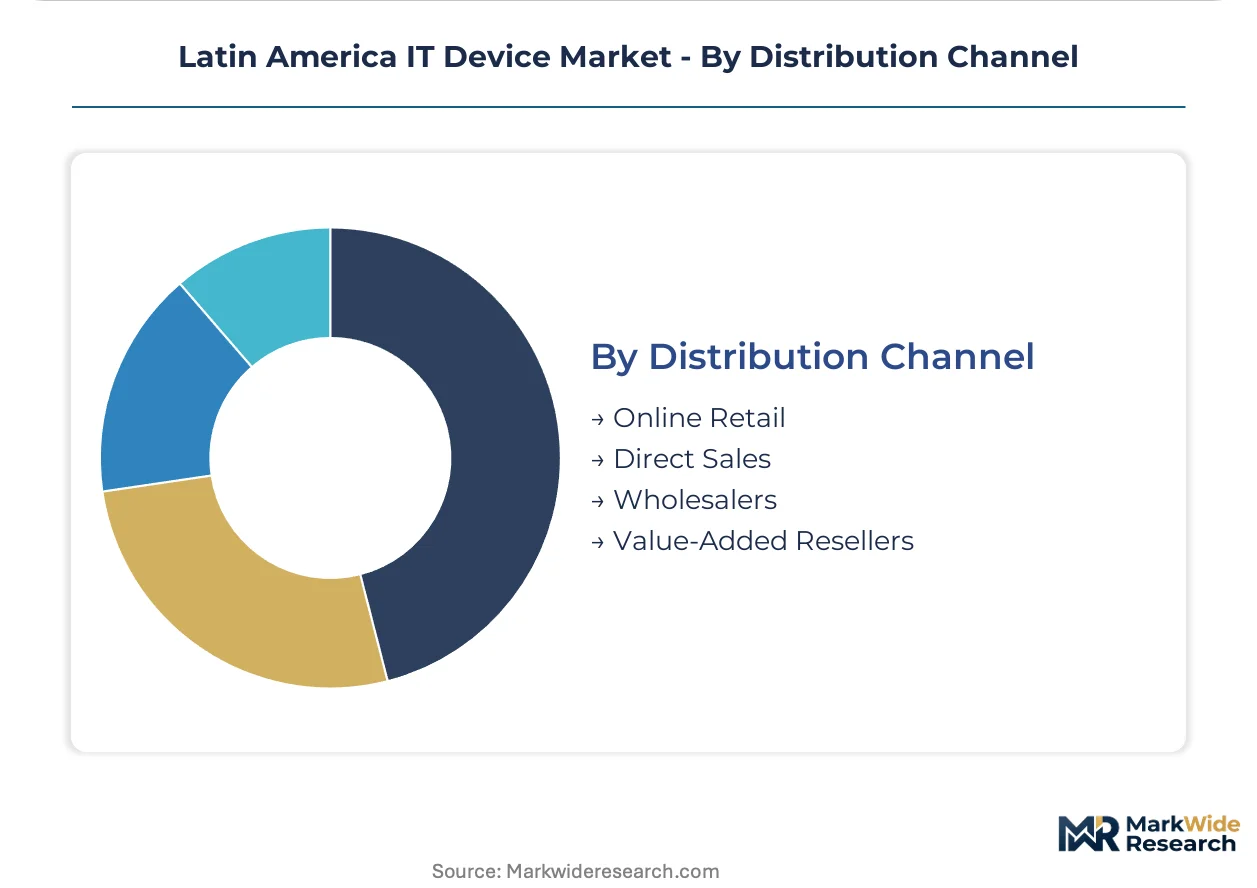
Distribution Channel:
Supply concentration patterns separate direct manufacturer relationships from intermediary-dependent routes to market.
- Direct Sales:Manufacturer-to-enterprise relationships bypass traditional wholesale margins for large-volume accounts with standardized configurations. Dell Technologies and Lenovo Group have built dedicated account teams for São Paulo financial services and Mexico City corporate technology clusters.
- Value-Added Resellers:Systems integrators bundle hardware with deployment services and endpoint management platforms for mid-market buyers lacking internal IT capacity. These partners concentrate in Colombia and Peru where distribution infrastructure remains underdeveloped relative to Brazil and Mexico.
- Online Retail:E-commerce platforms serve small business and consumer segments with standardized SKUs and rapid fulfillment.
- Wholesalers:Traditional distributors maintain inventory positions for fragmented regional markets but face margin compression as manufacturers consolidate direct relationships.
Direct Sales holds installed capacity. Value-Added Resellers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANATEL certification requirements and LGPD data protection mandates are redirecting procurement budgets toward security-certified device portfolios across Latin American enterprise markets. Brazil's industrial policy incentives and Mexico's manufacturing automation drive concentrate demand in specific metropolitan corridors.
Brazil
São Paulo's financial services corridor generates concentrated demand for encryption-certified workstations as LGPD compliance deadlines force hardware replacement cycles. ANATEL electromagnetic compatibility testing creates four-to-six-month product launch delays that compress revenue recognition windows. Localized assembly capacity in São Paulo state anchors Lenovo Group's regional manufacturing footprint.
Mexico
Manufacturing automation in the Bajío region pulls ruggedized industrial PCs with edge-processing capabilities into operational technology environments. IFETEL radio frequency standards govern networked equipment certification alongside hardware-level secure boot mandates. Mexico City's enterprise technology cluster hosts finance-led cloud governance committees that specify edge-ready hardware requirements.
Chile
The national digital classroom program drives volume procurement of ARM-based tablets and ChromeOS devices through centralized ministry tenders. Data-localization draft legislation positions encryption-capable device portfolios ahead of regulatory finalization. Santiago's public sector procurement frameworks impose specific local content requirements that fragment SKU availability.
Colombia
Bogotá's expanding fintech ecosystem lacks mature workstation procurement channels, creating openings for direct enterprise sales models. Pending personal data protection legislation mirrors Brazilian LGPD hardware requirements for encryption modules. Value-added resellers concentrate in this market where distribution infrastructure remains underdeveloped relative to regional peers.
Argentina
Import substitution mandates for government procurement create SKU fragmentation that elevates inventory carrying costs for traditional distributors. Buenos Aires-based enterprise buyers operate heterogeneous legacy environments that complicate modern endpoint management platform rollouts. Local content requirements redirect public sector budgets toward domestically assembled device portfolios.
Latin America IT Device Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with established local testing laboratory partnerships and certified distribution channels. Tiered competitive positioning separates premium workstation specialists from volume-driven laptop assemblers and component-integrated systems providers. Strategic archetypes include vertical integrators controlling server-to-workstation bundles, localized assemblers leveraging in-country manufacturing, and display technology leaders competing on panel specifications. Dominant competitive moves encompass direct-to-enterprise relationship building that bypasses wholesale margins, and certification pre-positioning ahead of regulatory deadline waves.
Within the vertical integrator tier, Dell Technologies exemplifies supply chain control through bundled hardware portfolios. Among Asia-Pacific-based manufacturers, Xiaomi Corporation and Samsung Electronics occupy positions spanning consumer mobile devices through enterprise display technologies. These three anchors represent distinct strategic postures: Dell Technologies anchors direct enterprise sales models, Samsung Electronics competes on display panel leadership, and Xiaomi Corporation challenges established pricing structures across mid-market segments.
| Leading Market Players |
|---|
| Dell Technologies |
| Xiaomi Corporation |
| Samsung Electronics |
| ASUSTek Computer Inc |
| Huawei Technologies |
| Lenovo Group |
| HP Inc |
| Acer Group |
| Apple Inc |
| Others |
Supply & Pricing Matrix
São Paulo state's localized assembly capacity anchors Lenovo Group's regional manufacturing footprint, concentrating cost efficiencies that translate into pricing leverage for encryption-certified workstations across Brazil's banking corridor. This geographic concentration of production capability interacts with ANATEL certification timelines to compress revenue recognition windows while elevating procurement premiums for compliant device portfolios.
Pricing Analysis
Certification level (ANATEL/IFETEL-grade) creates the primary spread between compliant and non-compliant device tiers across Latin American procurement channels. Three-tier pricing structure across premium encryption-certified, standard enterprise-grade, and economy education-focused levels segments buyer budgets by compliance burden. Cost compression in mid-market laptops is intensifying because manufacturers bypass traditional wholesale margins through direct-to-enterprise relationships. Education ministry buyers in Chile and Peru exhibit highest price sensitivity, while São Paulo financial services firms prioritize security certification over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor fabrication equipment limit regional access to cutting-edge processor architectures, forcing Latin American assemblers to source from Tier 2 foundry allocations. Component flows concentrate in China, South Korea, and Taiwan for display modules, memory chips, and system-on-chip designs. Panel supply rests on East Asian fabrication facilities, exposing regional distributors to ocean freight volatility and currency mismatch risks. Single-source vulnerability in NAND flash storage creates inventory pressure during allocation cycles. Distribution runs through direct manufacturer relationships for enterprise accounts, with value-added resellers serving fragmented mid-market segments in Colombia and Peru.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ANATEL certification and LGPD hardware mandates constructs formidable defensive moats for established suppliers with localized testing partnerships. Switching costs escalate as enterprise buyers consolidate around certified device portfolios and device-as-a-service contracting structures.
For Market Incumbents: Insulate market position by deepening backward integration into secure firmware development and expanding São Paulo state assembly capacity ahead of local content requirement expansions. Certification investment in pre-positioned ANATEL laboratory partnerships defends against four-to-six-month launch delays that threaten revenue recognition. Channel control through direct enterprise sales teams in Mexico City's technology cluster counters margin compression from wholesale bypass. For New Entrants and Emerging Players: Build out white-space presence in Colombia's fintech procurement channel where mature workstation distribution remains underdeveloped relative to regional peers. Bogotá's expanding financial services ecosystem offers first-mover advantage for direct sales models with encryption-certified portfolios. Peru's pending data localization legislation presents comparable entry timing before regulatory finalization hardens incumbent positions. Device-as-a-service bundling with endpoint security services penetrates professional services verticals where balance sheet optimization outweighs ownership preferences. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because certification entrenchment and data-localization mandates progressively tighten supplier qualification criteria. Acquisition targets should display established local testing laboratory partnerships and ANATEL pre-certification track records. The signal to watch is draft legislation progression across Colombia, Chile, and Peru that will replicate Brazilian LGPD hardware requirements and trigger replacement cycle waves.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Certification Pre-Positioning | Four-to-six-month testing backlogs compress revenue recognition for unprepared suppliers. |
| Localized Assembly Capacity Expansion | São Paulo state manufacturing anchors cost competitiveness against import duty structures. |
| Device-as-a-Service Platform Launch | Per-seat monthly arrangements displace capital expenditure purchasing among mid-market enterprises. |
| Direct Enterprise Sales Channel Buildout | Bypassing wholesale margins captures São Paulo banking corridor and Mexico City corporate clusters. |
| Encryption-Certified Portfolio Development | LGPD and pending data-localization mandates redirect procurement toward security-certified hardware. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings across the Latin America IT Device landscape. Conversations with enterprise procurement officers, channel distribution managers, ANATEL certification laboratory directors, device-as-a-service platform operators, and education ministry technology coordinators informed demand-side dynamics. Secondary sources include ANATEL electromagnetic compatibility filing databases, SEC 10-K hardware segment disclosures, Chilean education ministry tender documentation, and Brazilian customs import records. Bottom-up unit shipment modeling triangulates against top-down enterprise IT spending estimates from finance-led cloud governance committees.
Calibration against historical replacement cycle patterns and regulatory deadline waves shapes the projection framework across the analysis window. Segmentation dimensions encompass product type, technology integration level, end-user procurement authority structure, and distribution channel concentration. CAGRs derive from installed base turnover rates intersecting with compliance-driven replacement mandates. Forecast inputs incorporate ANATEL certification timeline distributions and LGPD enforcement phase transitions.
Stress conditions across currency volatility bands, ocean freight rate spikes, and semiconductor allocation cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory finalization timelines and enterprise cloud migration velocity. Cross-checking against hyperscaler edge hardware capex disclosures and regional GPO contract awards is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Street Lighting Market
Others
Australia Content Services Platform Market
Others
Textile Composites Market
Others
Europe Digital Experience Platform Market
Others
Africa Cotton Market
Others
Belt Loader Market
Others
Liquid-Cooled Heat Sink Market
Others
India Foundry Market
Others
Vegan Confectionery Market
Others
Nuclear Power Cables Market
Others
Sunflower Husk Pellets Market
Others
CAR T Cell Therapy Market
Others
DNA Data Storage Market
Others
Augmented Shopping Market
Others
Global Active Speaker Market
Others
Global Animal Feed Protein Ingredients Market