
 Undercarriage Systems Market | 2026-2036
Undercarriage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Undercarriage Systems Market Intelligence
Chinese forged-component capacity is repositioning competitive dynamics across the undercarriage supply base. Caterpillar leverages captive metallurgy expertise to sustain premium positioning in high-abrasion mining applications. Komatsu anchors its footprint through integrated heat-treatment lines serving construction OEMs across East Asia. Thyssenkrupp differentiates via precision-machined track chains engineered for European railway maintenance equipment.
Undercarriage systems comprise the tracked running gear of heavy machinery, including track chains, rollers, idlers, sprockets, and track shoes fabricated from high-manganese steel alloys through forging, casting, and heat treatment to withstand impact loads exceeding 50 tons. These assemblies transmit machine weight to terrain while enabling propulsion and steering across unpaved surfaces in construction, mining, and forestry operations. Track chains and rollers together capture the dominant margin pool due to replacement-frequency economics, while heat-treated sprockets represent the fastest-growing technology segment as OEMs prioritize wear-life extension over first-cost reduction. Forging retains volume leadership in mining-grade applications where material integrity governs safety certification.
EPA Tier 4 Final and EU Stage V emission frameworks are compressing undercarriage weight budgets as engine after-treatment systems add mass to machine platforms. OSHA walkaround inspection standards and ISO 10265 stability requirements shape track-geometry specifications for North American and European market access. China's GB standards on construction machinery safety and India's CEA mechanization directives are tightening test protocols for imported undercarriage assemblies. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving scrap-steel traceability rules recalibrate sourcing economics between integrated mills and specialty forge shops.
Market Dynamics
EU F-Gas Regulation and Stage V emission norms are compressing undercarriage weight budgets as engine after-treatment systems add mass to machine platforms. Mining fleet operators in Australia and Chile are accelerating replacement cycles as ore extraction depths exceed 500 meters.
Growth Catalysts
- India's CEA mechanization directives:Domestic contractors are scaling mechanized earthmoving capacity, creating concentrated demand for track chains and rollers in highway and rail corridor projects.
- High-manganese steel forging advances:Heat-treatment protocols now achieve 50+ ton impact-load tolerance, extending wear life in deep-pit mining applications.
- Deep ore extraction in Chile:Open-pit mines approaching end-of-life are transitioning to underground operations, forcing complete fleet renewal with specialized narrow-gauge undercarriage assemblies.
Market Restraints
- Scrap-steel traceability rules:Carbon-border adjustment mechanisms are recalibrating sourcing economics between integrated mills and specialty forge shops, compressing margin pools for non-integrated suppliers.
- High-manganese alloy input volatility:Manganese ore concentration in South Africa and Gabon creates geopolitical exposure for forging capacity dependent on seaborne raw material flows.
- ISO 10265 stability requirements:Track-geometry certification timelines for North American market access extend 14-18 months, freezing design iteration cycles for mid-tier OEMs.
Strategic Opportunities
- Railway maintenance equipment in Germany:Precision-machined track chains engineered for tamping machines and ballast regulators represent an underserved premium segment with replacement-frequency economics superior to construction applications.
- Remanufactured component channels:Mining contractors in Western Australia are unbundling after-sales service from OEM captive networks, creating opening for independent rebuilders with certified heat-treatment capabilities.
- Dual carbon goals in China:GB standards on construction machinery safety are tightening test protocols, advantaging domestic suppliers with integrated metallurgy and forging operations over import-dependent assemblers.
Industry Challenges
- Heat-treatment technician scarcity:Specialized furnace operators capable of maintaining 1,050°C austenitizing protocols with ±5°C tolerance are concentrated in legacy industrial clusters, constraining forge shop expansion.
- Legacy track-geometry integration:New sprocket designs with extended wear-life profiles must maintain backward compatibility with installed roller and idler populations, complicating product line transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Undercarriage Systems Market |
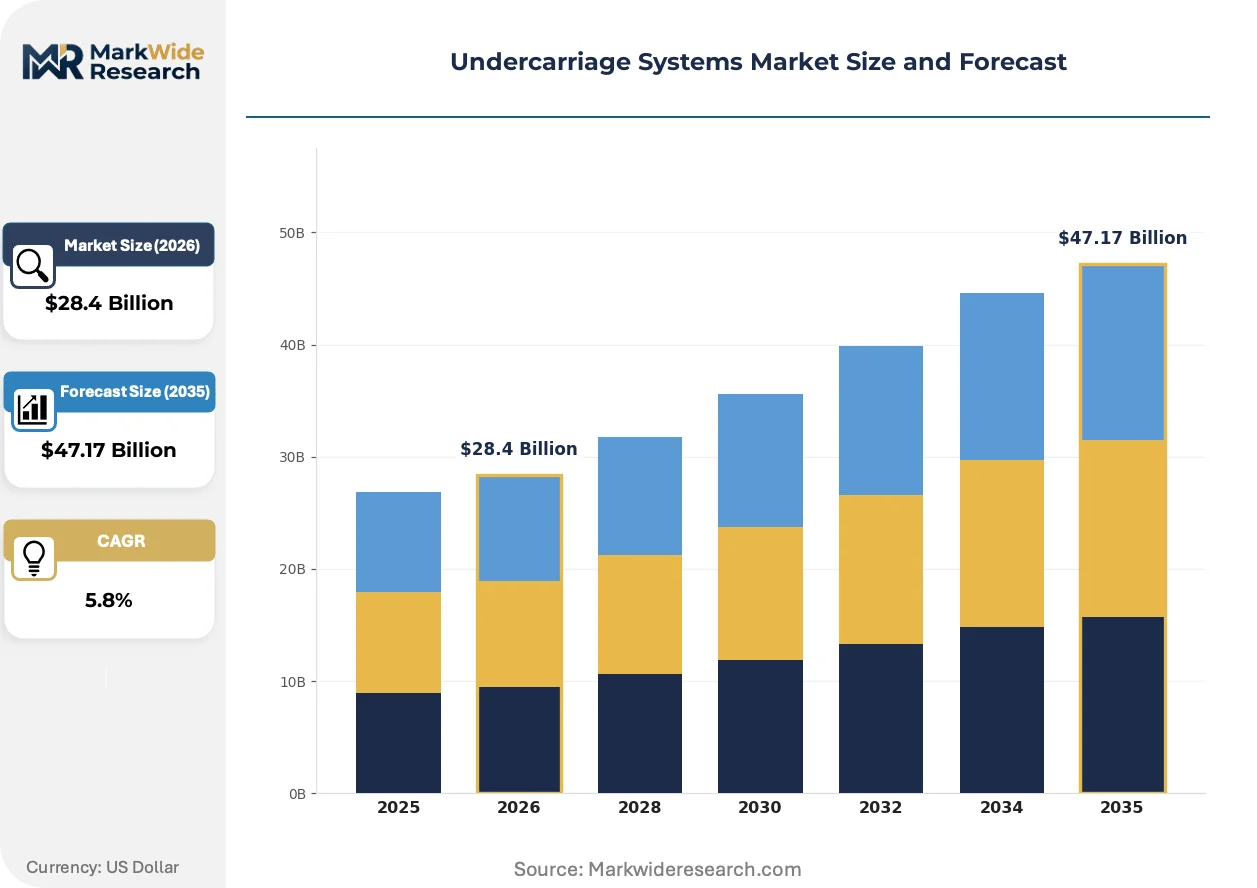
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $47.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Track Chains, Idlers, Rollers, Sprockets, Track Shoes, Carrier Rollers Technology: Forging, Casting, Heat Treatment, Machining, Welding, Coating Application: Construction Machinery, Mining Equipment, Forestry Machines, Agricultural Tractors, Excavators End User: Equipment Manufacturers, Rental Services, Contractors, Heavy Equipment Dealers |
| Companies Covered | John Deere, Thyssenkrupp, Caterpillar, USCO SpA, Titan International, Komatsu, Topy Industry, Dozco, Volvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Undercarriage Systems Market Strategic Shifts & Innovations
Material science advances and regulatory weight compression are forcing concurrent evolution in undercarriage design philosophy. The tension between durability requirements and platform mass constraints is reshaping supplier technical roadmaps.
Induction-hardened sprocket teeth are absorbing wear loads previously managed through thicker cross-sections, enabling 15-20% mass reduction in final-drive assemblies. Australian mining contractors are specifying these configurations in new fleet orders despite 8-12% first-cost premiums. The technology is absorbing margin pressure from emission-driven weight budgets while extending replacement intervals beyond 8,000 operating hours.
EU F-Gas Regulation is banning hydrofluorocarbon-based quenching media in heat-treatment operations, forcing forge shops to retrofit polymer-quench or pressurized-gas systems. The industrial consequence is capital intensity elevation of 20-30% for certification-compliant furnace lines. European railway maintenance equipment manufacturers are responding by consolidating supplier bases to forge shops with verified alternative-quench capability.
Service-contract unbundling is fragmenting procurement authority between fleet operators and independent rebuilders. Mining contractors in Western Australia are disintermediating OEM captive parts networks, sourcing remanufactured track chains through certified third-party channels at 40-50% discount to new assemblies. The shift is most visible in Pilbara iron ore operations where 24/7 utilization rates accelerate wear-part consumption beyond OEM logistics capacity.
Undercarriage Systems Market Segmentation
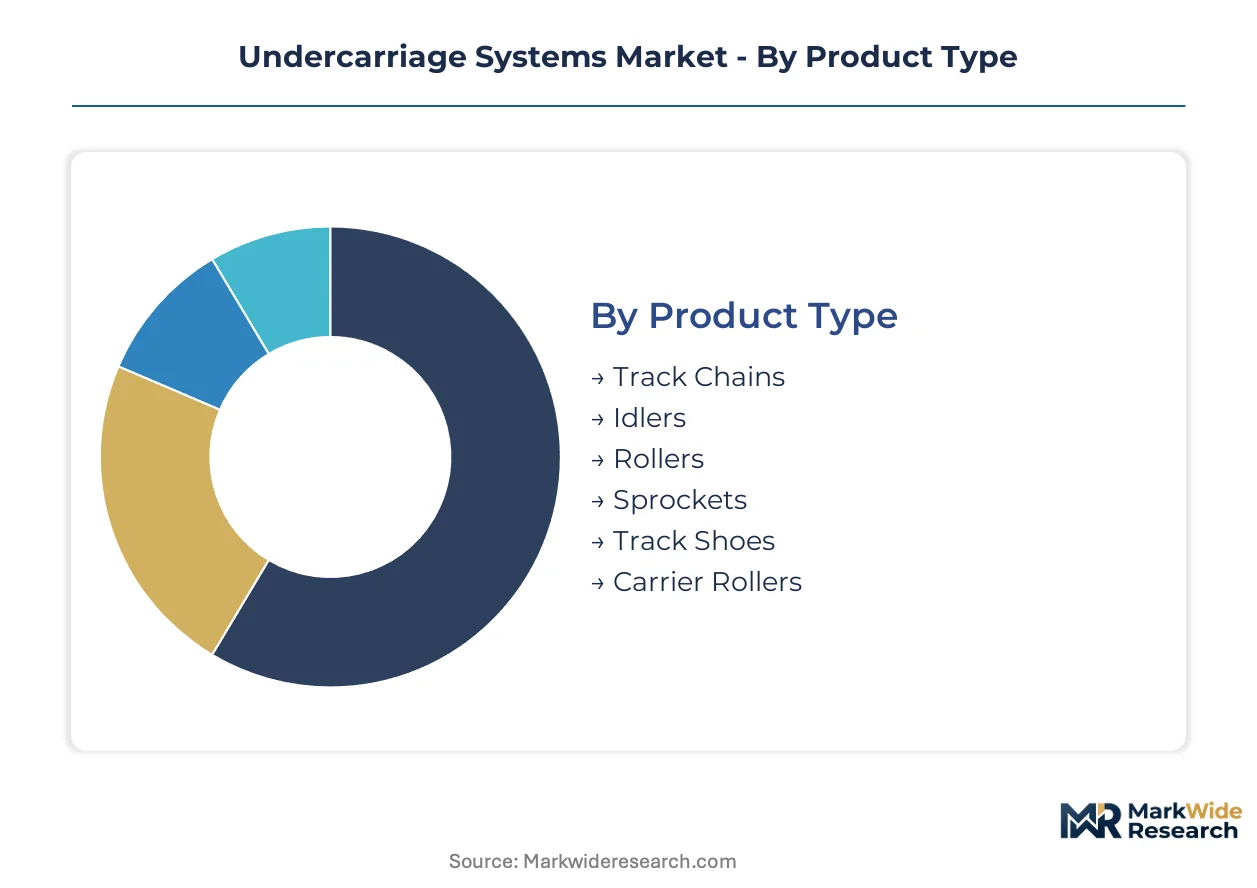
Undercarriage component economics vary sharply by wear rate, material specification, and captive versus aftermarket procurement channels. Mining contractors in Western Australia unbundle service contracts from OEM networks, while Indian highway builders concentrate demand in track chains and rollers through CEA mechanization directives.
Product Type:
Supply concentration in track chains and rollers dominates margin capture due to replacement-frequency economics in high-utilization mining fleets.
- Track Chains:Fabricated from high-manganese steel alloys through precision forging and heat treatment to withstand impact loads exceeding 50 tons. Demand concentrates in India's infrastructure build-out where domestic contractors scale mechanized earthmoving capacity for highway and rail corridor projects.
- Rollers:Transmit machine weight to terrain while enabling propulsion across unpaved surfaces; bottom and carrier variants differ in load distribution geometry. Australian mining fleet operators accelerate replacement cycles as ore extraction depths exceed 500 meters, forcing complete fleet renewal with specialized narrow-gauge assemblies.
- Idlers:Maintain track tension and alignment through spring-loaded or hydraulic adjustment mechanisms.
- Sprockets:Heat-treated drive components with induction-hardened teeth absorbing wear loads previously managed through thicker cross-sections.
- Track Shoes:Ground-engaging plates bolted to track chains; grouser profiles vary by traction requirements.
- Carrier Rollers:Support upper track run and prevent chain sag on long-wheelbase machines.
Today's leader: Track Chains. Tomorrow's challenger: Heat-treated Sprockets.
Technology:
Cost tier stratification separates capital-intensive forging operations from flexible machining and coating subcontractors serving fragmented aftermarket channels.
- Forging:Retains volume leadership in mining-grade applications where material integrity governs safety certification; 1,050°C austenitizing protocols with ±5°C tolerance require specialized furnace operators concentrated in legacy industrial clusters.
- Heat Treatment:EU F-Gas Regulation bans hydrofluorocarbon-based quenching media, forcing retrofit of polymer-quench or pressurized-gas systems and elevating capital intensity 20-30% for certification-compliant furnace lines.
- Casting:Lower-cost alternative for non-critical structural components in construction machinery.
- Machining:Precision finishing of forged blanks for European railway maintenance equipment specifications.
- Welding:Assembly of segmented track shoes and repair of cracked chain links.
- Coating:Surface hardening and corrosion protection for extended wear life in abrasive environments.
Process leadership sits with Forging. Fastest capability expansion: Heat Treatment retrofitting for F-Gas compliance.
Application:
Volume distribution tracks earthmoving intensity across ore extraction depths and infrastructure mechanization waves.
- Mining Equipment:Open-pit and underground operations demand specialized narrow-gauge undercarriage assemblies as Chilean mines transition below 500-meter depths.
- Construction Machinery:EPA Tier 4 Final and EU Stage V emission frameworks compress undercarriage weight budgets as engine after-treatment systems add mass to machine platforms.
- Excavators:Highest unit volume for standard-duty track chains and rollers in general earthmoving.
- Forestry Machines:Corrosion-resistant specifications for acidic soil and moisture exposure.
- Agricultural Tractors:Lower duty cycles and price-sensitive procurement through dealer networks.
Current volume anchor: Mining Equipment. Steepest expansion trajectory: Construction Machinery in India.
End User:
Customer type fragmentation splits procurement authority between captive OEM supply chains and independent rebuilders in Western Australia's unbundled service market.
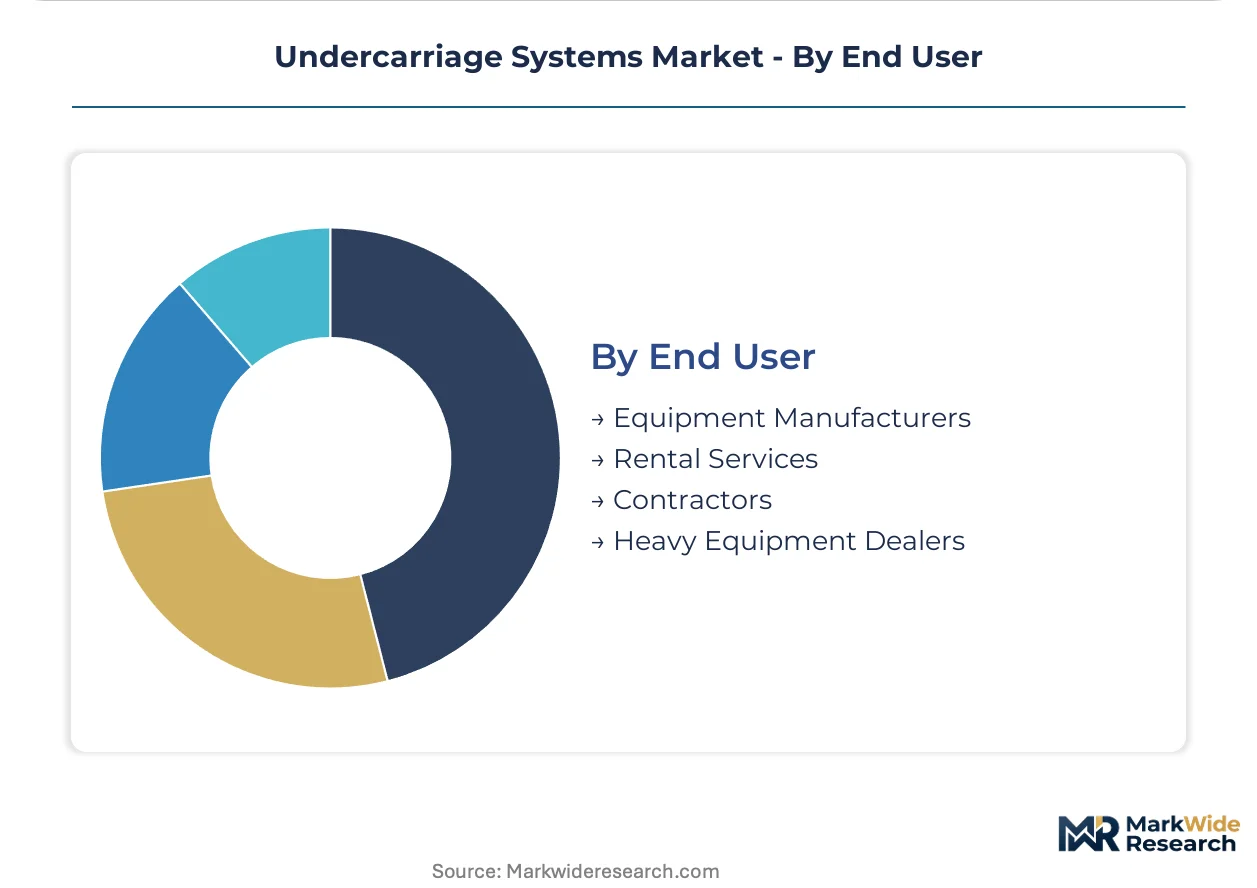
- Equipment Manufacturers:Caterpillar leverages captive metallurgy expertise to sustain premium positioning; Komatsu anchors footprint through integrated heat-treatment lines serving construction OEMs across East Asia.
- Contractors:Mining operators in Western Australia's Pilbara region source remanufactured track chains through certified third-party channels at 40-50% discount to new assemblies.
- Rental Services:Fleet turnover economics prioritize first-cost over wear-life extension.
- Heavy Equipment Dealers:Inventory carrying costs constrain stocking depth for slow-moving specialized components.
Margin capture leader: Equipment Manufacturers. Disruption vector: Contractors unbundling from OEM captive networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting forging capacity toward jurisdictions with lower compliance costs for F-Gas and emission standards. Production migration favors integrated metallurgy clusters with captive energy and raw material access.
United States
Mining fleet operators in Arizona and Nevada are accelerating undercarriage replacement cycles as copper extraction depths exceed prior thresholds. EPA Tier 4 Final standards compress weight budgets for construction machinery platforms. Pittsburgh-area forge shops maintain heat-treatment lines serving captive OEM networks for domestic mining equipment.
Germany
Railway maintenance equipment manufacturers concentrate procurement of precision-machined track chains for tamping and ballast regulation fleets. EU F-Gas Regulation bans hydrofluorocarbon quenching media, forcing furnace retrofits and supplier consolidation. Ruhr Valley industrial clusters host certified polymer-quench operations serving European OEM compliance requirements.
China
Domestic contractors scaling mechanized earthmoving for high-speed rail and highway corridors drive concentrated demand for track chains and rollers. GB standards on construction machinery safety tighten test protocols for imported assemblies. Yangtze River Delta forging clusters leverage integrated steel mills to supply both domestic OEMs and export markets.
Australia
Pilbara iron ore operators unbundle service contracts from OEM captive networks, sourcing remanufactured components through independent rebuilders. ISO 10265 stability requirements extend certification timelines for North American market access. Perth-based rebuilders with certified heat-treatment capabilities capture aftermarket share from 24/7 mining operations.
India
CEA mechanization directives accelerate highway and rail corridor projects requiring expanded earthmoving fleets. Domestic contractors scale mechanized capacity, creating demand concentration in standard-duty track chains. Gujarat and Maharashtra industrial corridors attract forging investments to serve infrastructure build-out procurement.
Undercarriage Systems Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue remanufacturing and aftermarket channels as OEM networks face disintermediation. The market structures around three tiers: integrated metallurgy specialists with captive forging, regional machine shops serving fragmented construction demand, and certified rebuilders capturing mining aftermarket share. Competitive moves concentrate on furnace line retrofits for F-Gas compliance and strategic partnerships with mining contractors seeking service-contract unbundling.
Among integrated forging specialists, Caterpillar and Komatsu exemplify the captive-metallurgy archetype with in-house heat-treatment operations. Thyssenkrupp occupies a position representing precision-machined specialization for European railway applications. These three anchors demonstrate how technical differentiation in quenching protocols and alloy specification separates premium positioning from commodity forging.
| Leading Market Players |
|---|
| John Deere |
| Thyssenkrupp |
| Caterpillar |
| USCO SpA |
| Titan International |
| Komatsu |
| Topy Industry |
| Dozco |
| Volvo |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation compliance gates qualified supply access and premium-tier pricing power for undercarriage assemblies, forcing forge shops to absorb 20-30% capital intensity elevation for alternative-quench furnace retrofits while OEMs consolidate procurement toward certified suppliers. Mining contractors in Western Australia unbundle service contracts from captive networks, creating price arbitrage between remanufactured third-party channels and OEM new-assembly premiums.
Pricing Analysis
Distributor margins in the aftermarket channel absorb the spread between OEM list pricing and independent rebuilder rates, with remanufactured track chains trading at 40-50% discounts to new assemblies. Three-tier pricing structure across premium, standard, and economy levels separates Caterpillar's captive-metallurgy positioning from regional forge shops and import-dependent assemblers. Pricing pressure stems from carbon-border adjustment mechanisms recalibrating scrap-steel sourcing economics. Rental services exhibit highest price sensitivity due to fleet turnover economics prioritizing first-cost, while mining contractors in deep-pit operations prioritize wear-life extension.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from integrated equipment manufacturers, while fragmented aftermarket distribution runs through independent rebuilders and heavy equipment dealers constrained by inventory carrying costs. Supply concentrates in China's Yangtze River Delta forging clusters, Germany's Ruhr Valley heat-treatment operations, and India's Gujarat industrial corridor. High-manganese steel alloys, specialized furnace equipment, and polymer-quench media constitute critical input dependencies. Single-source vulnerability in South African and Gabonese manganese ore concentration creates geopolitical exposure. Distribution stratifies between captive OEM supply chains and unbundled contractor procurement in Western Australia's Pilbara region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The undercarriage systems market functions as a stable compounder anchored by replacement-frequency economics in 24/7 mining operations where wear-part consumption exceeds OEM logistics capacity.
For Market Incumbents: Lock in heat-treatment technician pipelines through apprenticeship partnerships with legacy industrial clusters in Pittsburgh and the Ruhr Valley. Secure backward integration into high-manganese steel supply through offtake agreements with Australian ore processors. Defend against independent rebuilder disintermediation by embedding predictive maintenance sensors in track chain assemblies to capture aftermarket data streams. For New Entrants and Emerging Players: The 40-50% price-point gap between premium OEM assemblies and economy-tier imports creates entry space for certified rebuilders with polymer-quench capability. Target Western Australia's unbundled procurement market where 24/7 utilization rates accelerate wear-part consumption beyond incumbent logistics capacity. Pursue railway maintenance equipment specifications in Germany as a white-space segment with superior replacement-frequency economics. For Investors and Strategic Acquirers: Roll-up economics work for certified heat-treatment specialists because EU F-Gas compliance has stranded non-retrofitted furnace capacity and fragmented the supplier base. Five-to-ten year viability hinges on exposure to mining aftermarket channels rather than construction OEM cyclicality. Monitor manganese ore price volatility as the inflection signal for forging margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Line Retrofit for F-Gas Compliance | Polymer-quench certification preserves European market access for Ruhr Valley forge shops. |
| Backward Integration into Manganese Supply | Captive ore offtake from Australian processors insulates against South African supply disruption. |
| Remanufacturing Channel Certification | Third-party heat-treatment accreditation captures Pilbara iron ore aftermarket share from OEM networks. |
| Railway Maintenance Equipment Partnership | Precision-machined track chain supply to German tamping machine OEMs opens premium replacement cycle economics. |
| Predictive Maintenance Sensor Integration | Embedded wear monitoring in track assemblies locks in aftermarket data revenue streams. |
Research Approach
Bottom-up mining and construction equipment fleet modeling reconciled against top-down forging capacity tracking forms the analytical core of this study. Primary interviews with maintenance directors at Pilbara iron ore operators, OEM procurement teams at Caterpillar and Komatsu, aftermarket service heads at Perth-based rebuilders, and heat-treatment furnace operators in the Ruhr Valley combined with secondary validation from EPA Tier 4 Final filings, EU F-Gas Regulation compliance databases, Indian CEA mechanization directives, and Australian Bureau of Statistics mining capital expenditure records. Top-down and bottom-up estimates triangulated through cross-referencing import-export customs data for high-manganese steel alloy shipments.
Input-output matrices mapped undercarriage component demand to installed mining equipment base, ore extraction depth trajectories, and infrastructure mechanization waves across the projection horizon. Segmentation dimensions modeled include product type, technology process, application equipment class, and end-user procurement channel. CAGRs derived from regression analysis against historical replacement cycle data and fleet utilization intensity. Industry-specific forecast inputs incorporated manganese ore price volatility indices and F-Gas compliance cost curves for furnace retrofit economics.
The model assumes a particular technology adoption path; alternative pathways for induction-hardened sprocket teeth displacing thicker cross-section designs would alter the outlook for mass reduction and wear-life extension trade-offs. Forecasts reflect assumptions regarding mining fleet renewal rates, emission regulation implementation timelines, and scrap-steel traceability rule enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
Engine Oil Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Global Automotive Stampings Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Friction Pads Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Automotive Canister Purge Valve Market