
 Global Automotive Plastic Fuel Tank Market | 2026-2036
Global Automotive Plastic Fuel Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Plastic Fuel Tank Market Intelligence
EPA Tier 3 is recalibrating the cost-of-entry calculus for automotive fuel tank suppliers, mandating sub-54 mg/m²/day permeation rates that force retooling of single-layer production lines. TI Fluid Systems leverages its blow molding expertise to anchor North American supply contracts with Detroit Three automakers. Plastic Omnium competes through integrated fuel system modules that extend from tank to pump assembly. YAPP Automotive Systems dominates China's domestic OEM channel with scaled HDPE operations serving BYD and Geely.
Global automotive plastic fuel tanks are high-density polyethylene or multi-layer coextruded reservoirs, typically six-layer structures with ethylene-vinyl alcohol barrier cores, manufactured through extrusion blow molding or sequential welding to contain gasoline and diesel while limiting hydrocarbon vapor escape. Blow molded tanks occupy the volume majority in passenger cars due to cost-efficient cycle times and geometric flexibility for underbody packaging. Multi-layer tanks are capturing margin pools as Euro 6 and EPA regulations tighten, while welded tank architectures sustain demand in commercial trucks requiring modular repairability and structural reinforcement for high-capacity configurations.
Federal EPA regulations in the United States, ECHA REACH compliance in Europe, and China's GB standards under SAMR collectively dictate barrier performance, material composition, and recycling mandates that shape product development roadmaps. Japan's METI energy efficiency guidelines and India's BIS automotive component standards further fragment certification requirements across supply chains. Stakeholders must monitor regulatory divergence between California Air Resources Board waivers and federal harmonization debates to anticipate tooling investment cycles and regional sourcing strategies.
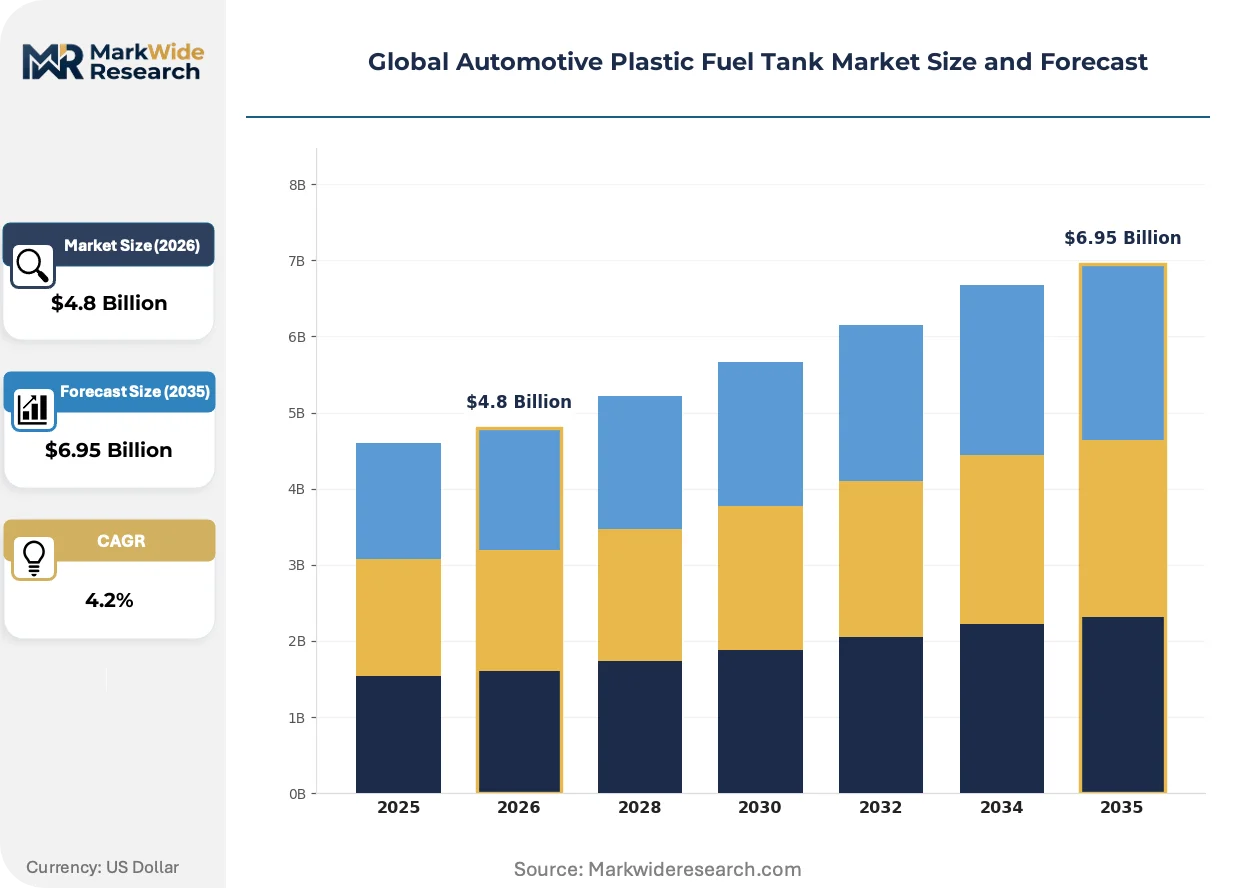
Market Dynamics
Multi-layer coextrusion technology is compressing the cost gap between barrier-compliant and legacy single-layer tanks, forcing simultaneous retooling across three continents as automakers consolidate supplier bases around emissions-certified platforms.
Growth Catalysts
- EPA Tier 3 permeation mandates:Sub-54 mg/m²/day hydrocarbon limits are eliminating single-layer HDPE from US passenger vehicle programs and redirecting capital toward six-layer EVOH barrier lines.
- China NEV transition:Extended-range electric vehicles retain internal combustion range extenders, sustaining demand for compact plastic tanks with crash-resistant geometries in BYD and Geely supply chains.
- Cross-linked polyethylene:XLPE blow molding is penetrating commercial truck segments where impact resistance and repairability outweigh the premium over standard HDPE.
Market Restraints
- Ethylene-vinyl alcohol resin concentration:EVOH barrier layer supply concentrates among three Asian petrochemical suppliers, exposing tank molders to input cost volatility and allocation risk.
- Tooling amortization burden:Six-layer coextrusion dies and barrier welding stations require capital intensity that excludes sub-scale regional suppliers from Tier 1 procurement pools.
- Metal tank residual share:Stainless steel architectures retain foothold in heavy-duty trucks above 150-liter capacity where structural reinforcement costs favor welded metal over plastic overmolding.
Strategic Opportunities
- India BS-VI compliance timeline:Domestic tank capacity lags behind passenger vehicle emission enforcement, creating import substitution openings for barrier-certified suppliers with localized blow molding.
- Integrated fuel system modules:Tank-to-pump assembly consolidation is unifying vapor management, pressure sensing, and filtration into single-supplier modules that capture margin from discrete component vendors.
- Recyclate-ready barrier structures:Mono-material compatible coextrusion recipes are aligning with EU Green Deal circularity mandates and positioning early adopters for end-of-life regulation.
Industry Challenges
- Permeation testing certification backlog:EPA and CARB laboratory capacity constraints are extending validation timelines for new tank geometries, delaying program launches and compressing development cycles.
- Multi-layer defect detection:Non-destructive testing for EVOH layer continuity requires capital-intensive ultrasonic or X-ray systems that strain quality assurance budgets at mid-volume suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Plastic Fuel Tank Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blow Molded Tanks, Welded Tanks, Injection Molded Tanks, Multi-Layer Tanks Technology: High-Density Polyethylene, Cross-Linked Polyethylene, Polypropylene, Nylon, Composite Materials End User: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Off-Road Vehicles Application: Passenger Cars, Delivery Vans, Construction Equipment, Agricultural Machinery |
| Companies Covered | TI Fluid Systems, Magna International, Plastic Omnium, Hanon Systems, Fuel Total Systems, YAPP Automotive Systems, Yachiyo Industry, Marelli, Kautex Textron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Plastic Fuel Tank Market Strategic Shifts & Innovations
Blow molding process control and barrier material science are converging to enable thinner-wall, higher-performance tanks that reduce mass while tightening emissions compliance.
Sequential coextrusion blow molding is unifying six-layer barrier construction with complex underbody geometries previously requiring welded tank halves. Tier 1 suppliers in Germany and Japan are adopting these lines for 2025-model passenger vehicle programs. The technology is compressing the tooling cost premium between standard HDPE and barrier-compliant tanks from 40% to under 15%.
REACH SVHC candidate list expansion is restricting certain plasticizers and stabilizers in fuel-contact layers, compelling reformulation of inner-layer HDPE grades. ECHA compliance deadlines are accelerating material qualification cycles. European OEMs are responding by consolidating supplier approvals around pre-certified resin systems.
Fleet procurement departments are compressing supplier qualification cycles from 36 months to 18 months as platform electrification timelines accelerate. Direct OEM-tank maker relationships are displacing traditional fuel system integrators in North American commercial vehicle channels. This pattern is most visible in Detroit Three heavy-duty truck programs where cost transparency outweighs module integration convenience.
Global Automotive Plastic Fuel Tank Market Segmentation
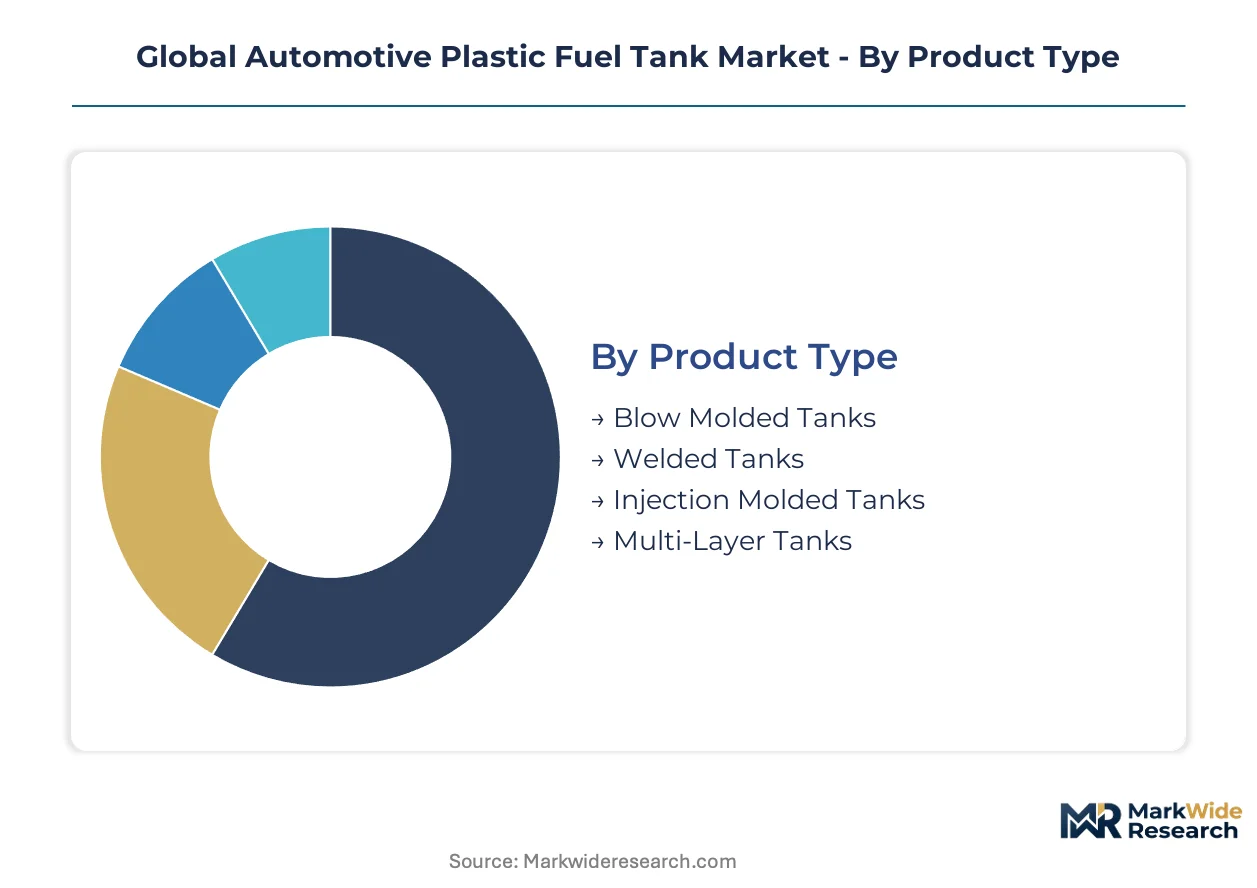
Plastic fuel tank segmentation reveals divergent technology bets across passenger and commercial vehicle programs. Suppliers must align barrier-layer investments with specific OEM platform requirements while managing material cost volatility across resin categories.
Product Type:
Blow molded tanks command volume leadership through cycle-time efficiency and geometric flexibility for underbody packaging. Welded architectures retain commercial relevance where repairability and structural reinforcement justify higher unit costs.
- Blow Molded Tanks:Six-layer coextrusion blow molding integrates EVOH barrier cores with complex fuel filler neck geometries in a single production cycle. Detroit Three automakers in the United States concentrate procurement here for light-duty truck platforms where packaging density matters.
- Multi-Layer Tanks:Sequential barrier construction achieves sub-54 mg/m²/day permeation rates mandated by EPA Tier 3 and Euro 6 regulations. Germany and Japan OEMs are consolidating supplier approvals around these architectures as emissions enforcement tightens.
- Welded Tanks:Modular half-shell welding supports field-repairable configurations in heavy-duty applications. HDPE seam welding with barrier layer overlap addresses commercial truck demand for damage tolerance.
- Injection Molded Tanks:Limited to auxiliary fuel reservoirs and range-extender systems where wall-thickness precision outweighs production speed. China's NEV programs source compact injection molded units for plug-in hybrid architectures.
Mature deployment sits with blow molded tanks. Newer deployment is concentrated in multi-layer barrier architectures.
Technology:
Material selection tracks the tension between permeation compliance and processing economics. HDPE maintains cost leadership while barrier additives and cross-linking chemistries capture premium positioning.
- High-Density Polyethylene:Standard HDPE grades dominate single-layer legacy production and form the structural substrate in multi-layer coextrusion. Virgin and recycled HDPE blends are qualifying for inner-layer fuel contact applications under ECHA REACH reformulation timelines.
- Cross-Linked Polyethylene:XLPE blow molding delivers impact resistance and stress-crack immunity for commercial truck fuel systems. Japanese heavy-duty OEMs specify XLPE for construction vehicle applications where vibration fatigue threatens conventional HDPE.
- Polypropylene:Lower density than HDPE offers mass reduction potential for compact passenger car tanks. India's domestic suppliers are qualifying PP grades for BS-VI compliant two-wheeler fuel reservoirs.
- Nylon:Barrier-layer applications leverage nylon's hydrocarbon resistance in composite tank designs. Limited adoption due to moisture sensitivity and adhesion challenges in coextrusion.
- Composite Materials:Glass-reinforced thermoplastic composites address structural load cases in off-road vehicle fuel cells. Agricultural machinery OEMs in Germany specify composite overmolding for rollover protection.
Volume concentration favors HDPE. Margin expansion is concentrating in cross-linked polyethylene for commercial durability requirements.
End User:
Customer segmentation reflects divergent regulatory exposure and durability specifications. Passenger vehicle programs drive barrier technology adoption while commercial applications prioritize damage tolerance.
- Passenger Vehicles:Global OEM platform consolidation is standardizing six-layer EVOH tank specifications across sedan, SUV, and crossover architectures. Euro 6 and EPA Tier 3 permeation limits have eliminated single-layer HDPE from new vehicle programs.
- Commercial Trucks:Fleet procurement departments in the United States are compressing supplier qualification cycles. Direct OEM-tank maker relationships are displacing traditional fuel system integrators in Detroit Three heavy-duty channels.
- Two-Wheelers:India's BS-VI compliance timeline is forcing domestic tank capacity expansion. Compact blow molded HDPE reservoirs serve scooter and motorcycle platforms where cost sensitivity constrains barrier-layer adoption.
- Off-Road Vehicles:Construction and mining equipment specifications prioritize impact resistance over permeation performance. Welded HDPE architectures with steel reinforcement bands sustain demand in this segment.
Technology transfer is accelerating from passenger vehicles to commercial trucks. Two-wheelers remain the most price-constrained end-user category.
Application:
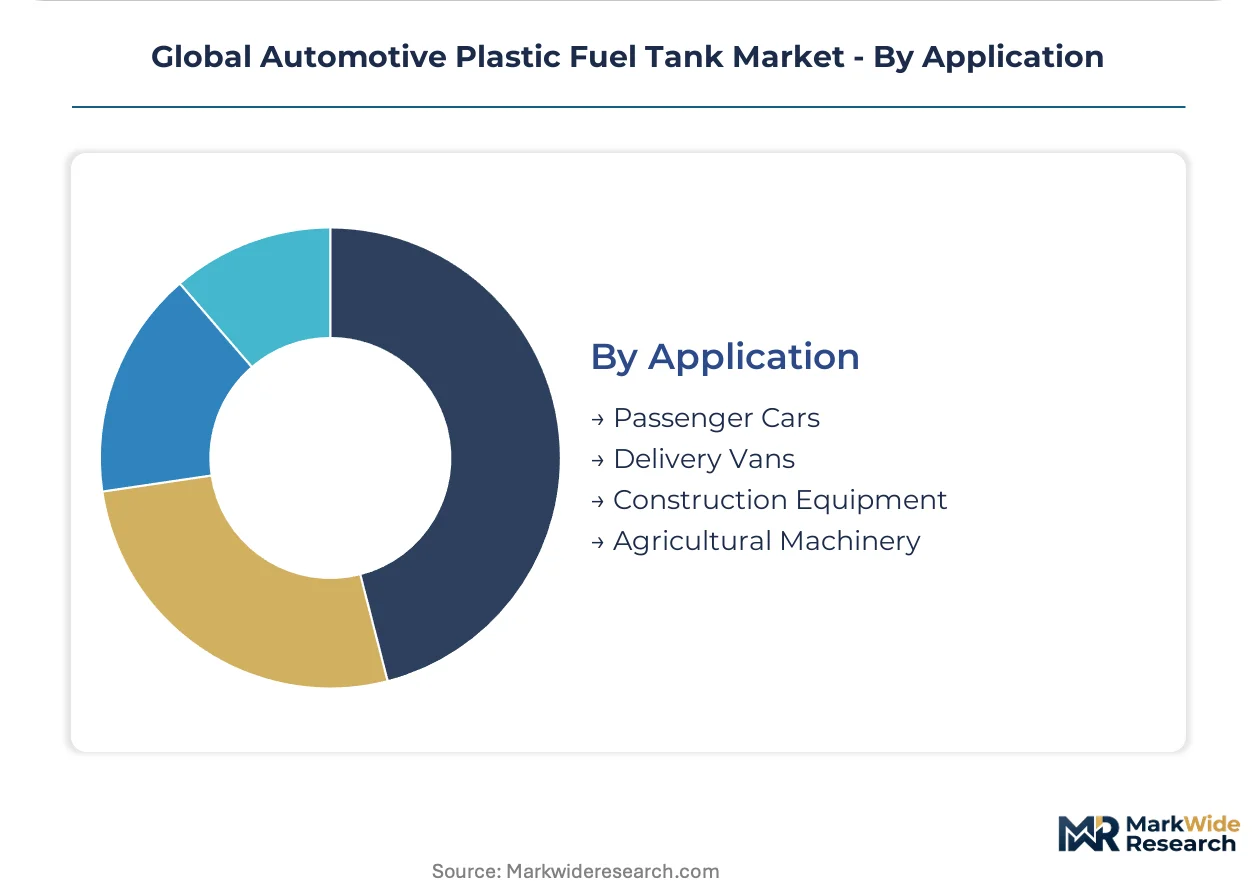
Application-level segmentation tracks vehicle duty cycles and fuel system integration complexity. Delivery van electrification is fragmenting demand between full-electric and range-extended hybrid configurations.
- Passenger Cars:Underbody packaging constraints favor blow molded tanks with integrated vapor management components. Germany's premium OEMs specify complex fuel filler neck geometries that sequential coextrusion enables.
- Delivery Vans:Last-mile electrification is bifurcating demand. Full-electric vans eliminate fuel tanks while range-extended hybrids retain compact plastic reservoirs for combustion range extenders.
- Construction Equipment:Vibration and impact loading drive XLPE and composite material specification. Japan's construction machinery OEMs source tanks with integrated rollover valves and flame arrestors.
- Agricultural Machinery:Extended field operation cycles demand high-capacity welded tanks with modular repair access. German and United States agricultural equipment manufacturers specify 300+ liter configurations with steel band reinforcement.
Standardization pressure is highest in passenger cars. Custom engineering concentration sits with agricultural and construction machinery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate blow molding capacity serving BYD and Geely electrification programs. Germany's automotive corridor and Japan's Kanto industrial belt anchor multi-layer barrier technology deployment for Euro 6 and EPA Tier 3 compliance.
United States
Detroit Three automakers drive six-layer EVOH tank procurement for light-duty truck platforms. EPA Tier 3 permeation mandates below 54 mg/m²/day eliminate single-layer HDPE from passenger vehicle programs. Michigan and Ohio industrial clusters host blow molding operations supplying F-150 and Silverado fuel systems.
Germany
Premium OEMs specify complex fuel filler neck geometries enabled by sequential coextrusion technology. ECHA REACH SVHC restrictions accelerate material qualification cycles for inner-layer HDPE grades. Bavaria and Baden-Württemberg manufacturing corridors concentrate barrier-certified supplier approvals.
China
Extended-range electric vehicles retain combustion range extenders sustaining compact plastic tank demand. GB standards under SAMR dictate barrier performance and recycling mandates for domestic OEMs. Yangtze River Delta production bases scale HDPE operations for BYD and Geely supply chains.
Japan
METI energy efficiency guidelines fragment certification requirements for fuel system component suppliers. Heavy-duty construction vehicle OEMs specify XLPE blow molding for vibration fatigue resistance. Kanto and Chubu industrial regions anchor multi-layer technology adoption for 2025-model passenger programs.
India
BS-VI compliance timelines force domestic tank capacity expansion ahead of emission enforcement. BIS automotive component standards shape product development roadmaps for two-wheeler and passenger vehicle segments. Maharashtra and Gujarat manufacturing clusters attract barrier-certified suppliers with localized blow molding investments.
Global Automotive Plastic Fuel Tank Market Key Industry Players
German and Japanese producers anchor one tier in multi-layer barrier technology; Chinese specialists hold volume positions in standard HDPE fabrication. The supplier base consolidates around emissions-certified platforms as automakers reduce approved vendor lists. Three archetypes dominate: integrated fuel system module suppliers, scaled regional blow molding operations, and niche commercial truck specialists. Strategic moves center on six-layer coextrusion line investments and direct OEM qualification bypassing traditional fuel system integrators.
Within the integrated module tier, TI Fluid Systems and Plastic Omnium exemplify suppliers extending from tank fabrication to pump assembly consolidation. YAPP Automotive Systems occupies a position among scaled regional producers serving China's domestic OEM channel through concentrated HDPE operations. These three anchors represent divergent competitive vectors: North American supply contract leverage, European fuel system integration, and Chinese manufacturing scale.
| Leading Market Players |
|---|
| TI Fluid Systems |
| Magna International |
| Plastic Omnium |
| Hanon Systems |
| Fuel Total Systems |
| YAPP Automotive Systems |
| Yachiyo Industry |
| Marelli |
| Kautex Textron |
| Others |
Cost & Logistics Intelligence
Barrier-certification tier divergence between six-layer EVOH-compliant tanks and legacy single-layer HDPE architectures manifests in both pricing premiums and supply chain consolidation patterns. Automakers with EPA Tier 3 and Euro 6 compliance mandates pay lead-time premiums for certified suppliers while spot-market HDPE tanks face price erosion from capacity overhang in Asia.
Pricing Analysis
Short lead-time pricing premiums dominate contract negotiations as OEMs compress platform development cycles. Six-layer coextrusion tanks command three-tier pricing structure across premium, standard, and economy levels based on EVOH barrier grade and permeation certification tier. Price differentiation stems from EPA Tier 3 validation status and volume scale commitments. Cost compression in standard HDPE tiers is intensifying because Chinese capacity expansion outpaces demand growth in two-wheeler segments. Fleet procurement departments at Detroit Three automakers show lowest price sensitivity due to total-cost-of-ownership framing, while Indian domestic OEMs remain most sensitive to unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Tier 1 automakers mandate multi-supplier qualification for EVOH barrier resin and blow molding capacity. Geographic supply concentration centers on Germany, China, and Japan for multi-layer coextrusion equipment and barrier-grade resin systems. Raw material dependencies rest on ethylene-vinyl alcohol resin from Asian petrochemical suppliers, virgin HDPE feedstock, and cross-linking agent chemicals. Single-source vulnerability concentrates in EVOH resin allocation from three dominant suppliers. Distribution runs through Tier 1 fuel system integrators in North America and direct OEM relationships in European commercial vehicle channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over EVOH barrier resin supply and six-layer coextrusion tooling determines margin capture. Players are pursuing backward integration into barrier material compounding to secure allocation and compress input cost volatility.
For Market Incumbents: Cement barrier-certification leadership by locking long-term EVOH supply contracts with Korean and Japanese resin suppliers before allocation constraints tighten. Add six-layer coextrusion capacity in Michigan and Ohio industrial clusters to defend against Chinese competitors qualifying for Detroit Three programs. TI Fluid Systems and Plastic Omnium anchor positions through integrated fuel system modules that extend from tank fabrication to pump assembly consolidation. For New Entrants and Emerging Players: Begin with India's BS-VI compliance gap where domestic barrier-certified capacity lags passenger vehicle emission enforcement timelines. Target Maharashtra and Gujarat manufacturing clusters with localized blow molding investments serving Maruti Suzuki and Tata Motors supply chains. Pursue direct OEM qualification bypassing traditional fuel system integrators to capture margin from discrete component vendors. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional blow molding specialists given EPA Tier 3 and Euro 6 regulatory catalysts forcing automaker supplier base consolidation. Five-to-ten year viability favors operations with pre-certified six-layer lines and established OEM platform relationships. Monitor EVOH resin allocation announcements from Korean petrochemical suppliers as the inflection signal for input cost pressure and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Certified Capacity Expansion | Six-layer coextrusion line investments in Michigan and Ohio capture Detroit Three light-duty truck platform awards. |
| Backward Integration into EVOH Compounding | In-house barrier resin production reduces exposure to Asian petrochemical supplier allocation volatility. |
| Direct OEM Qualification Bypass | Tank-to-pump module consolidation displaces traditional fuel system integrators in North American commercial channels. |
| India Localized Manufacturing Footprint | Maharashtra and Gujarat blow molding plants address BS-VI compliance demand from Maruti Suzuki and Tata Motors. |
| Recyclate-Ready Barrier Structure Development | Mono-material compatible coextrusion aligns with EU Green Deal circularity mandates for end-of-life regulation. |
Research Approach
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, and EVOH resin technical specialists underwrites the qualitative findings. Primary interviews with blow molding plant managers, automotive regulatory affairs directors, and aftermarket distribution channel heads combined with secondary validation from EPA certification databases, ECHA REACH substance registrations, and vehicle production data from IHS Markit. Bottom-up tank unit demand modeling triangulates against top-down fuel system market value estimates.
Comparable-period anchoring to historical EPA Tier 2 and Euro 5 regulatory transitions informed the projection framework across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture, barrier layer technology tier, and regional production cluster. CAGRs derive from unit demand trajectories weighted by content-per-vehicle value and technology mix shifts. Industry-specific inputs incorporate EVOH resin price indices and six-layer coextrusion line capacity utilization rates.
Underlying measurement precision varies by segment; six-layer barrier tank forecasts carry tighter precision than single-layer HDPE legacy estimates due to regulatory enforcement clarity. Forecasts reflect assumptions around EPA Tier 3 permeation testing certification timelines and EVOH supplier capacity expansion plans. Deviation in CARB waiver harmonization with federal standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Speed Bump Market
Automotive Parts
Road Marking Machine Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Automotive Forging Market
Automotive Parts
Qatar Commercial Vehicles Lubricants Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Cycloid Gear Market