
 Specialty Tire Market | 2026-2036
Specialty Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Tire Market Analysis
Market Context
Modular tire-and-wheel bundling is shifting buyer choice from standalone replacement toward integrated system procurement in mining and construction fleets. Continental AG leverages captive supply chains for radial OTR assemblies across European quarry operations. Michelin anchors premium positioning through sustained R&D intensity in all-terrain tread compounds. Bridgestone dominates replacement channels in North American agricultural applications through direct dealer networks.
Technical Definition and Structural Segments
Specialty tires are engineered pneumatic or non-pneumatic structures designed for off-highway, severe-service, or terrain-specific applications, typically featuring reinforced sidewalls, custom tread geometries, and load ratings exceeding standard highway specifications to withstand abrasive surfaces, extreme temperatures, and sustained heavy loads. Agricultural Tires represent the mature revenue base with stable replacement cycles, while Construction Tires capture expanding margin pools from infrastructure stimulus programs. Radial Tread Type configurations lead technology transitions due to superior fuel efficiency and heat dissipation, whereas Non-Pneumatic variants occupy emerging niches in autonomous mining where puncture elimination reduces downtime.
Regulatory Frame and Outlook
EPA tailpipe and particulate standards constrain compound formulations and manufacturing emissions in the United States, while REACH and EU F-Gas Regulation in Europe mandate chemical disclosure and restrict fluorinated greenhouse gas use in tire production processes. China's GB standards and MIIT industrial policy directives shape domestic product certification and export eligibility for specialty tire manufacturers. Stakeholders must monitor evolving carbon-border adjustment mechanisms and treadwear testing protocols to preserve market access across jurisdictions.
Market Dynamics
Radial tread technology is compressing replacement cycles across mining and construction fleets while EPA particulate standards force compound reformulation, creating simultaneous pull and push pressures on specialty tire manufacturers.
Growth Catalysts
- Infrastructure stimulus deployment:Government-funded road and port projects in India and Brazil are accelerating earthmoving equipment utilization, driving replacement tire volumes for articulated dump trucks and motor graders.
- REACH chemical disclosure mandates:European tire manufacturers are reformulating tread compounds to eliminate restricted substances, creating premium positioning for compliant suppliers serving regulated quarry and agricultural markets.
- Autonomous mining adoption:Driverless haul truck fleets in Australian iron ore operations prioritize non-pneumatic tire architectures that eliminate puncture-related downtime in remote pit environments.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and speculative commodity trading compress margin predictability for manufacturers dependent on latex-sourced elastomers.
- Carbon black supply concentration:Chinese furnace black producers control approximately three-fifths of global specialty-grade output, exposing non-integrated tire makers to input bottlenecks during energy-rationing periods.
- Technical limitation in sidewall flex resistance:Ultra-large radial tires for 400-ton haul trucks experience heat buildup at sustained speeds above fifty kilometers per hour, constraining operational flexibility in open-pit coal operations.
Strategic Opportunities
- Underpenetrated African mining corridors:Copper-cobalt extraction in the Democratic Republic of Congo and Zambia lacks established tire service infrastructure, creating first-mover advantage for mobile fitting and retreading networks.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases in tire curing processes are accelerating demand for water-based curing systems and steam-based alternatives among European manufacturers.
- Telematics-treadwear convergence:Integration of embedded sensors with predictive analytics platforms enables usage-based tire management contracts for construction equipment lessors seeking to unbundle rubber procurement from asset ownership.
Industry Challenges
- Compound formulation expertise scarcity:Experienced rubber chemists capable of balancing abrasion resistance, heat dissipation, and rolling efficiency for severe-service applications command premium compensation and limited geographic mobility.
- OTR tire mold capex intensity:Single curing presses for 63-inch mining radials require capital commitments exceeding fifteen million dollars per unit, concentrating production capability among manufacturers with balance sheet scale.
- GB standards certification timelines:China's mandatory product testing protocols for construction machinery tires extend approval cycles by eight to fourteen months, delaying market entry for non-domestic suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Tire Market |
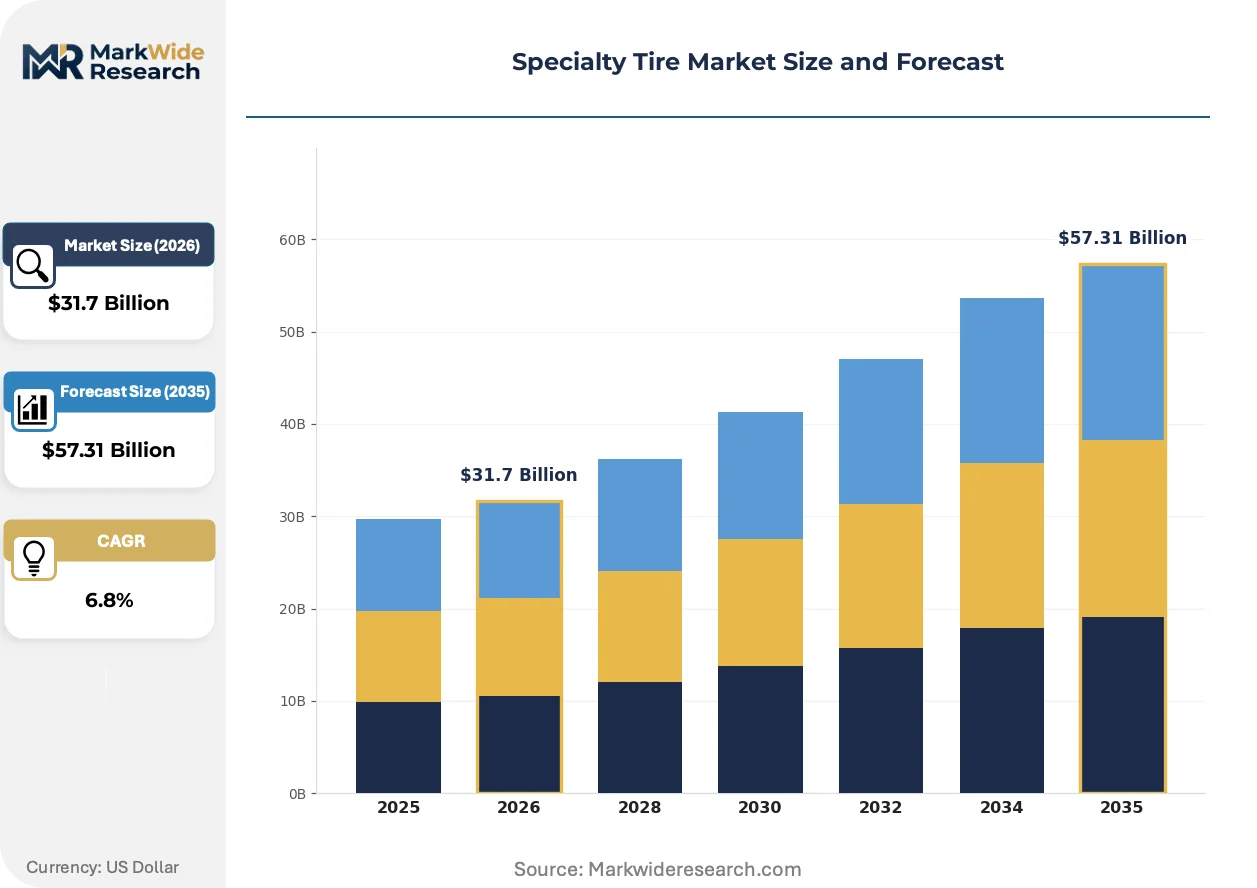
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $57.31 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agricultural Tires, Forestry Tires, Industrial Tires, Construction Tires End User: Agriculture, Construction, Mining, Transportation Tread Type: Radial, Bias, Non-Pneumatic, All-Terrain Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | Continental AG, Hankook Tire & Technology, Michelin, Toyo Tire Group Global, Yokohama Rubber, Bridgestone, Pirelli Tyre, Sumitomo Rubber Industries, Goodyear Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Tire Market Emerging Trajectories
Digitalization of tire lifecycle management is converging with materials science advances to transform how fleet operators specify, procure, and retire specialty tires across severe-service applications.
Sensor-embedded intelligent tires are rewriting maintenance economics in mining operations. These systems transmit real-time pressure, temperature, and tread depth data to fleet control centers. Major copper and iron ore producers in Chile and Western Australia are retrofitting existing haul fleets with aftermarket sensor kits while specifying native integration for new equipment purchases. The technology is compressing unplanned downtime intervals and enabling condition-based replacement rather than calendar-based discard.
EPA tailpipe and particulate standards are tightening compound formulation constraints for US-manufactured specialty tires. The regulations restrict aromatic oil extenders and mandate lower volatile organic compound emissions during curing processes. Agricultural tire producers serving Midwest grain operations are reformulating tread stocks with alternative plasticizers and accelerating investments in electron beam curing systems to maintain compliance without sacrificing cut resistance.
Fleet operators are consolidating vendor relationships and demanding integrated tire-and-wheel assemblies rather than standalone rubber procurement. Mining contractors in Canada's oil sands region are awarding multi-year supply agreements to single-source providers responsible for mounting, balancing, field service, and end-of-life retreading. This bundling compresses the addressable market for pure-play tire distributors while elevating technical service capabilities as a competitive differentiator.
Specialty Tire Market Segmentation
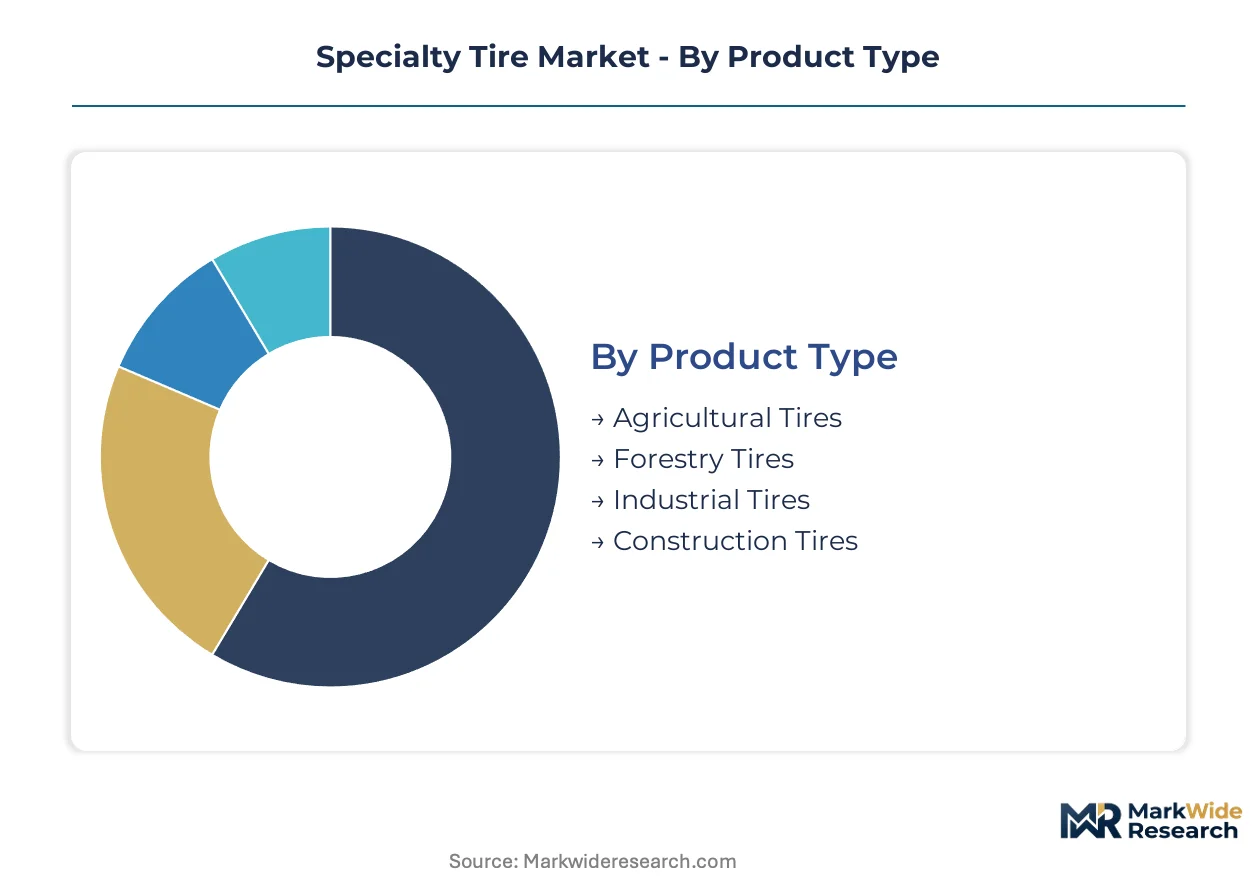
Specialty tire procurement patterns diver sharply across equipment types and operating environments. Fleet managers specify tread geometries, load ratings, and sidewall constructions based on duty severity, terrain abrasiveness, and downtime cost exposure rather than unit price alone.
Product Type:
Buyers differentiate primarily by replacement cycle predictability and margin contribution from integrated service bundles.
- Construction Tires:Reinforced bead bundles and cut-resistant tread compounds withstand steel rebar and fractured rock surfaces. Demand clusters in Indian road-building corridors and Brazilian port expansion zones where articulated dump trucks operate sixteen-hour shifts. Infrastructure stimulus programs in these geographies are accelerating earthmoving equipment utilization and compressing replacement intervals.
- Agricultural Tires:Flexible sidewall designs and flotation tread patterns reduce soil compaction in row-crop applications. Midwest grain operations in the United States specify these for combines and tractors during narrow harvest windows. EPA particulate standards are forcing compound reformulation with alternative plasticizers to maintain cut resistance under compliance constraints.
- Forestry Tires:Steel-belted carcasses resist puncture from stumps and slash debris in mechanized logging operations.
- Industrial Tires:Solid or cushion designs for forklifts and material handlers prioritize load stability over speed rating in warehouse and port environments.
Volume sits with Agricultural Tires; growth tilts toward Construction Tires.
End User:
Operating cost structures and downtime penalties shape specification intensity across verticals.
- Mining:Ultra-large radial configurations for 400-ton haul trucks demand heat-resistant compounds for sustained high-load operation. Australian iron ore producers prioritize non-pneumatic architectures in autonomous fleets to eliminate puncture-related downtime in remote pit environments. Telematics integration is enabling condition-based replacement rather than calendar-based discard.
- Construction:Mixed fleets of motor graders, loaders, and articulated trucks require rapid field service response. Canadian oil sands contractors are consolidating vendor relationships and demanding integrated tire-and-wheel assemblies with mounting, balancing, and end-of-life retreading from single-source providers.
- Agriculture:Seasonal demand spikes during planting and harvest windows strain distributor inventory positioning.
- Transportation:Port terminal tractors and airport ground support equipment specify specialty designs for tight turning radius and load stability.
Mining commands premium pricing; Construction shows the steepest expansion trajectory from infrastructure deployment.
Tread Type:
Technology transitions follow fuel efficiency mandates and heat dissipation requirements in severe-service duty cycles.
- Radial:Steel-cord belt packages and optimized crown profiles reduce rolling resistance and operating temperatures compared to bias constructions. Mining and construction fleets in Chile and Western Australia are retrofitting haul trucks with sensor-embedded radials that transmit pressure and temperature data to fleet control centers. The technology compresses unplanned downtime intervals.
- Non-Pneumatic:Polymer spoke architectures eliminate air pressure maintenance and puncture risk entirely. These occupy emerging niches in autonomous mining where elimination of human intervention for tire repair justifies higher acquisition cost.
- Bias:Cross-ply nylon or polyester cord constructions retain cost advantage in low-speed, short-haul agricultural applications.
- All-Terrain:Hybrid tread geometries balance traction across loose surfaces and hard-packed roads for utility vehicles and crossover equipment.
Radial dominates installed base; Non-Pneumatic is climbing the fastest from autonomous fleet adoption.
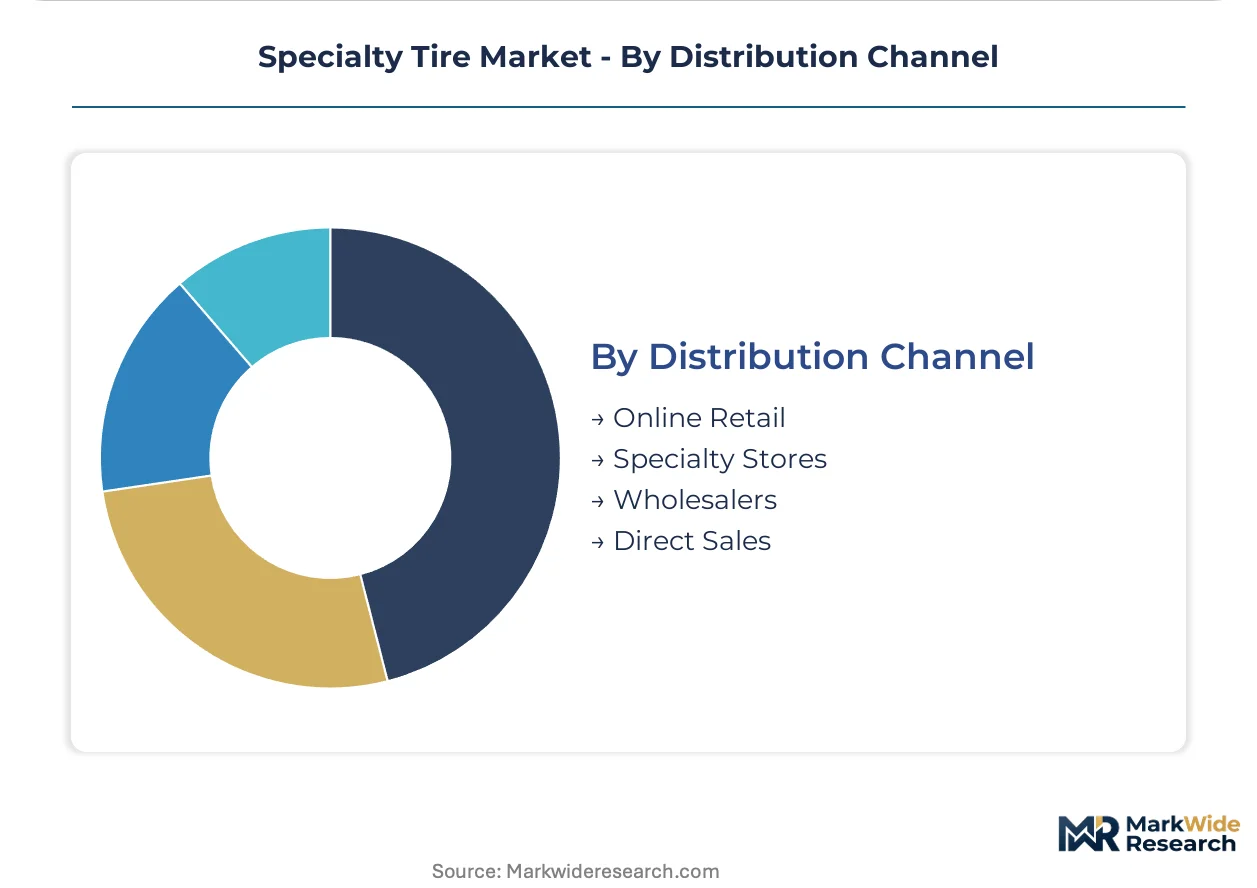
Distribution Channel:
Channel selection reflects fleet scale, technical service requirements, and procurement centralization trends.
- Direct Sales:Original equipment manufacturers and large mining contractors negotiate multi-year supply agreements with captive mounting and field service obligations. European quarry operations source radial OTR assemblies through direct relationships that bundle technical consultation with volume commitments.
- Specialty Stores:Independent dealers with hydraulic mounting equipment and certified technicians serve mid-size agricultural and construction fleets requiring rapid turnaround during critical operating windows.
- Wholesalers:Regional distributors aggregate demand from smaller fleet operators and independent repair shops.
- Online Retail:Digital platforms capture standard-size agricultural and industrial tire specifications where fitment verification is straightforward and price transparency matters.
Direct Sales captures mining and large construction volume; Specialty Stores retain agricultural replacement loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty tire production concentrates in Germany, Japan, and the United States while consumption gravity shifts toward Chinese construction corridors and Australian mining pits. This geographic asymmetry creates trade flow dependencies and regional pricing disparities.
United States
Midwest grain operations drive agricultural tire replacement cycles during narrow planting and harvest windows. EPA tailpipe and particulate standards constrain compound formulations for domestic manufacturers. Ohio-based production clusters supply radial OTR assemblies to Canadian oil sands contractors seeking integrated tire-and-wheel procurement.
Germany
European quarry operations source premium radial configurations through direct supply relationships bundling technical consultation. REACH chemical disclosure mandates and EU F-Gas Regulation force tread compound reformulation toward water-based curing systems. Continental AG anchors captive supply chains across Bavarian manufacturing centers serving mining fleets in Scandinavia.
China
Domestic construction machinery output scales drive demand concentration for earthmoving equipment tires in road-building corridors. MIIT industrial policy directives and GB standards certification protocols shape product eligibility for export markets. Shandong Province production clusters supply articulated dump truck tires to Indian infrastructure projects.
Australia
Iron ore producers in Western Australia prioritize non-pneumatic architectures for autonomous haul truck fleets eliminating puncture-related downtime. Sensor-embedded intelligent tires transmit real-time pressure and temperature data to fleet control centers. Pilbara region mining contractors compress replacement cycles through condition-based rather than calendar-based discard protocols.
Brazil
Government-funded port expansion zones accelerate articulated dump truck utilization driving replacement tire volumes. ANVISA chemical registration requirements intersect with import regulations affecting compound formulation transparency. São Paulo state distributors aggregate demand from mid-size construction fleets requiring rapid field service response during sixteen-hour operating shifts.
Specialty Tire Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers and service intensity levels. The vendor base stratifies between premium-tier manufacturers with captive R&D pipelines and mid-tier assemblers dependent on outsourced compound formulations. Three archetypes dominate: integrated rubber-to-road suppliers controlling curing press capacity, technology licensors monetizing tread pattern patents, and service-intensive operators bundling mounting and field maintenance. Competitive moves concentrate on multi-year supply agreement capture and telematics platform integration.
Within the diversified conglomerate tier, Continental AG and Bridgestone exemplify scale-driven positioning through balance sheet capacity for fifteen-million-dollar curing press commitments. Michelin occupies a premium-tier position representing sustained R&D intensity in severe-service tread compounds. Among Asia-Pacific-based manufacturers, Hankook Tire & Technology and Yokohama Rubber sit within technology-transition archetypes balancing radial adoption against bias-ply cost advantages in emerging markets.
| Leading Market Players |
|---|
| Continental AG |
| Hankook Tire & Technology |
| Michelin |
| Toyo Tire Group Global |
| Yokohama Rubber |
| Bridgestone |
| Pirelli Tyre |
| Sumitomo Rubber Industries |
| Goodyear Tire & Rubber Company |
| Others |
Supply Flow & Price Mechanics
Integrated tire-and-wheel procurement mandates from Canadian oil sands contractors and Australian iron ore producers are forcing manufacturers to absorb mounting capex burdens for curing press capacity and field service networks, compressing margin pools for non-integrated competitors unable to bundle assembly logistics with rubber supply.
Pricing Analysis
Margin tightening in premium mining radials reflects fifteen-million-dollar curing press commitments and captive R&D pipelines at diversified conglomerates. Three-tier pricing structure across premium, standard, and economy levels separates sensor-embedded intelligent tires with telematics integration from basic radial configurations and bias-ply agricultural alternatives. Pricing pressure stems from natural rubber price volatility and carbon black supply rationing in China. Construction fleets in India and Brazil exhibit highest price sensitivity due to infrastructure stimulus procurement protocols, while autonomous mining operators in Australia prioritize uptime value over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns serving mining corridors in Australia and construction zones in China. Manufacturing draws from Southeast Asian latex plantations and Chinese furnace black producers controlling three-fifths of specialty-grade output. Single-source vulnerability concentrates in carbon black feedstock during energy-rationing periods. Distribution runs through direct sales channels for large mining contractors and specialty stores with hydraulic mounting equipment for mid-size agricultural fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phase-down and REACH chemical disclosure mandates erect compliance barriers that favor incumbent manufacturers with reformulated water-based curing systems and established certification pathways.
For Market Incumbents: Deepen backward integration into carbon black production and captive curing press capacity to defend against input bottlenecks and fifteen-million-dollar capex barriers blocking mid-tier entrants. Consolidate field service networks in underpenetrated African mining corridors to preempt mobile fitting and retreading challengers. Prioritize telematics platform integration to lock in multi-year supply agreements with condition-based replacement protocols.
For New Entrants and Emerging Players: Independent dealers with hydraulic mounting equipment and certified technicians offer the most penetrable channel wedge for mid-size agricultural and construction fleets requiring rapid turnaround during critical operating windows. Target copper-cobalt extraction zones in the Democratic Republic of Congo and Zambia where established tire service infrastructure remains absent. Lead with water-based curing system compliance to capture EU F-Gas Regulation-driven supplier switches.
For Investors and Strategic Acquirers: The window for entry favors technology-transition archetypes balancing radial adoption against bias-ply cost advantages in emerging markets, with acquisition premiums justified by compound formulation expertise scarcity and GB standards certification timelines. Monitor autonomous mining fleet deployment rates in Australian iron ore operations as the inflection signal for non-pneumatic architecture demand acceleration. Long-term viability hinges on telematics-treadwear convergence enabling usage-based tire management contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Black Production | Chinese furnace black concentration exposes non-integrated manufacturers to energy-rationing bottlenecks. |
| Telematics Platform Integration | Sensor-embedded intelligent tires enable condition-based replacement contracts with Chilean copper producers. |
| Water-Based Curing System Transition | EU F-Gas Regulation phase-down accelerates demand for compliant European manufacturers. |
| Mobile Fitting Network Expansion | Copper-cobalt corridors in Zambia lack established tire service infrastructure for 400-ton haul trucks. |
| Multi-Year Supply Agreement Capture | Canadian oil sands contractors consolidate vendor relationships for integrated tire-and-wheel procurement. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combined with primary interviews across plant managers at curing press facilities, procurement leads at mining contractors, distribution channel partners with hydraulic mounting capabilities, and aftermarket service heads at agricultural equipment dealers. Bottom-up triangulation against top-down macroeconomic indicators validated volume and value estimates across the analysis window.
Segmentation granularity modeled product type, end user vertical, tread technology configuration, and distribution channel at the country level across the projection horizon. CAGRs derived from equipment utilization rates, replacement cycle compression patterns, and infrastructure stimulus deployment timelines. Industry-specific inputs included EPA particulate standard compliance costs and autonomous mining fleet adoption curves.
Caveats apply where natural rubber price volatility, carbon black supply rationing, or GB standards certification timeline extensions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Heavy Duty Tire Market