
 Tire Vulcanizer Market | 2026-2036
Tire Vulcanizer Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Vulcanizer Market Analysis
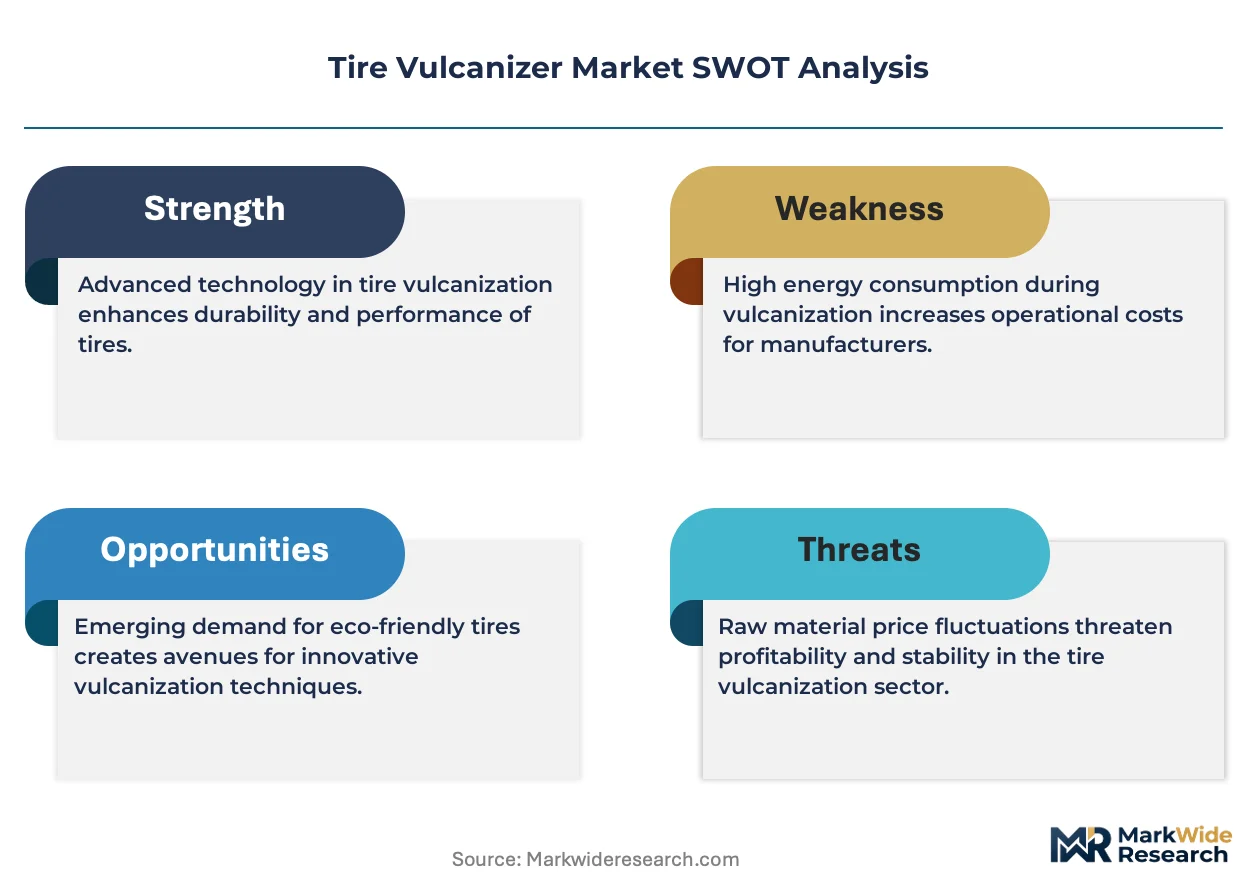
Direct sales from machinery builders to tire plants is reconfiguring as Asian manufacturers expand local service networks. HF TireTech Group leverages its European engineering base to sustain premium positioning in hydraulic systems. MESNAC anchors its competitive stance through integrated automation solutions for Chinese tire producers. Kobe Steel differentiates via metallurgical expertise in press frame durability.
A tire vulcanizer applies heat and pressure to cure raw rubber compounds into finished tire casings, typically operating at temperatures between 150°C and 200°C with clamping forces exceeding 200 tons. The equipment transforms uncured green tires into dimensionally stable, elastic products through cross-linking of sulfur bonds within the rubber matrix. Production vulcanizers command the largest installed base due to continuous throughput requirements at major tire factories, while electric vulcanizers are gaining fastest penetration where energy costs and carbon accounting intensify. Steam vulcanization retains dominance in legacy facilities though microwave technology attracts R&D investment for reduced cycle times.
EPA emissions guidelines and OSHA workplace safety standards shape equipment specifications in the United States, while REACH compliance and CE marking govern material selection and machine safety in Europe. China's SAMR enforces GB standards on industrial machinery energy consumption, pressuring domestic manufacturers toward electric heating systems. Stakeholders must weigh capital intensity against regulatory trajectory when selecting between established steam infrastructure and emerging electric platforms.
Market Dynamics
Energy efficiency mandates are compressing the operational lifespan of steam-based vulcanization infrastructure while electric heating platforms capture capital allocation from fleet operators and OEM tire plants. China's Shandong province concentrates manufacturing demand, creating procurement gravity that reshapes equipment specification standards across Asia-Pacific.
Growth Catalysts
- EU Ecodesign requirements:Energy consumption limits on industrial machinery are accelerating replacement cycles for legacy steam vulcanizers across European tire plants. German and Italian manufacturers face compliance deadlines that favor electric platform adoption.
- Commercial fleet electrification:Battery-electric truck rollouts in California and the Netherlands are generating specialized tire demand requiring advanced curing precision. Fleet operators specify vulcanizers capable of handling silica-compound formulations optimized for reduced rolling resistance.
- Shandong manufacturing clusters:Tire production concentration in China's eastern province creates localized procurement volumes that justify dedicated service infrastructure. Equipment suppliers establish captive maintenance networks to capture aftermarket revenue streams.
Market Restraints
- Steel price volatility:Press frame fabrication depends on specialized alloy grades subject to commodity fluctuation. Japanese and South Korean metallurgical supply constraints transmit cost pressure to vulcanizer builders.
- Hydraulic system supply concentration:Precision pump and valve manufacturing concentrates among German and Italian component specialists. Geographic concentration creates lead time vulnerability for vulcanizer assembly schedules.
- Steam infrastructure lock-in:Existing boiler investments at legacy tire plants in Thailand and Indonesia create switching friction against electric platform migration. Sunk capital in steam distribution networks delays replacement decisions.
Strategic Opportunities
- India tire manufacturing expansion:PLI scheme incentives for automotive component production are attracting greenfield tire plants in Gujarat and Tamil Nadu. Domestic vulcanizer demand will outpace local equipment supply capacity.
- Microwave-assisted curing convergence:Hybrid heating systems combining electric and microwave energy sources promise cycle time compression. Technology integration opportunities exist for press builders with RF engineering partnerships.
- Service contract unbundling:Predictive maintenance platforms using vibration and thermal sensors enable outcome-based pricing separate from equipment sale. Channel innovation targets mid-size tire producers lacking in-house technical staff.
Industry Challenges
- Automation integration complexity:Tire plants seek vulcanizer-to-warehouse robotics coordination requiring specialized control engineering. Equipment suppliers must develop programmable logic controller compatibility across multiple OEM automation architectures.
- Certification timeline compression:CE marking and China's GB standard updates demand simultaneous documentation preparation. Compliance teams face overlapping regulatory deadlines that delay product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Vulcanizer Market |
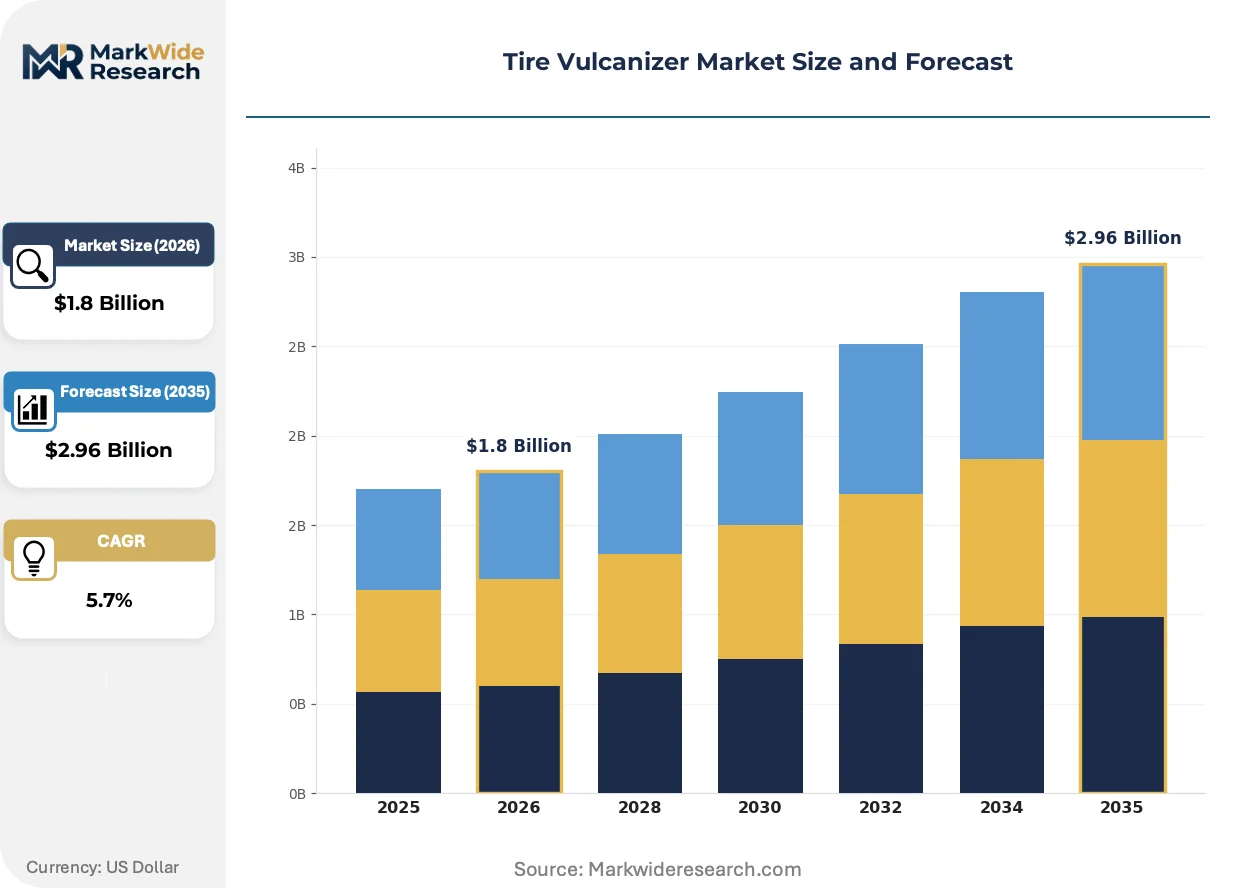
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Vulcanizers, Electric Vulcanizers, Portable Vulcanizers, Production Vulcanizers Application: Passenger Tires, Truck Tires, Motorcycle Tires, Agricultural Tires End User: Tire Manufacturers, Repair Shops, Fleet Operators, Retail Outlets Technology: Steam Vulcanization, Hot Air Vulcanization, Cold Vulcanization, Microwave Vulcanization |
| Companies Covered | HF TireTech Group, Larsen & Toubro, Guilin Rubber Machinery, Alfred Herbert, MESNAC, Kobe Steel, Beijing BAMTRI Dingsheng Technology, Qingdao Yadong Rubber Machinery Group, McNeil & NRM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Vulcanizer Market Emerging Trajectories
Digitalization of curing process control is converging with energy management systems to create integrated production platforms. Equipment specification increasingly prioritizes real-time monitoring capabilities alongside mechanical throughput metrics.
Induction heating modules for tire vulcanization apply electromagnetic energy directly to press platens, eliminating thermal lag associated with steam or resistive systems. Premium tire manufacturers in Germany and Japan are piloting these installations for high-performance product lines. Conventional boiler infrastructure is rendering obsolete for new capacity additions where carbon accounting affects supplier qualification.
China's GB standards on industrial machinery energy consumption, enforced by SAMR, mandate efficiency testing and labeling for vulcanizers sold domestically. Domestic manufacturers must redesign heating architectures to meet tiered consumption thresholds. Export-oriented tire plants in Vietnam and Indonesia are adopting these specifications preemptively to maintain supply chain access.
Direct procurement relationships between tire OEMs and specialized vulcanizer builders are displacing traditional distributor intermediaries. Major fleet operators in Texas and São Paulo now specify equipment directly, sourcing aftermarket support through captive service agreements. This pattern is most visible in North America and Brazil where consolidation among commercial vehicle operators concentrates buying power.
Tire Vulcanizer Market Segmentation
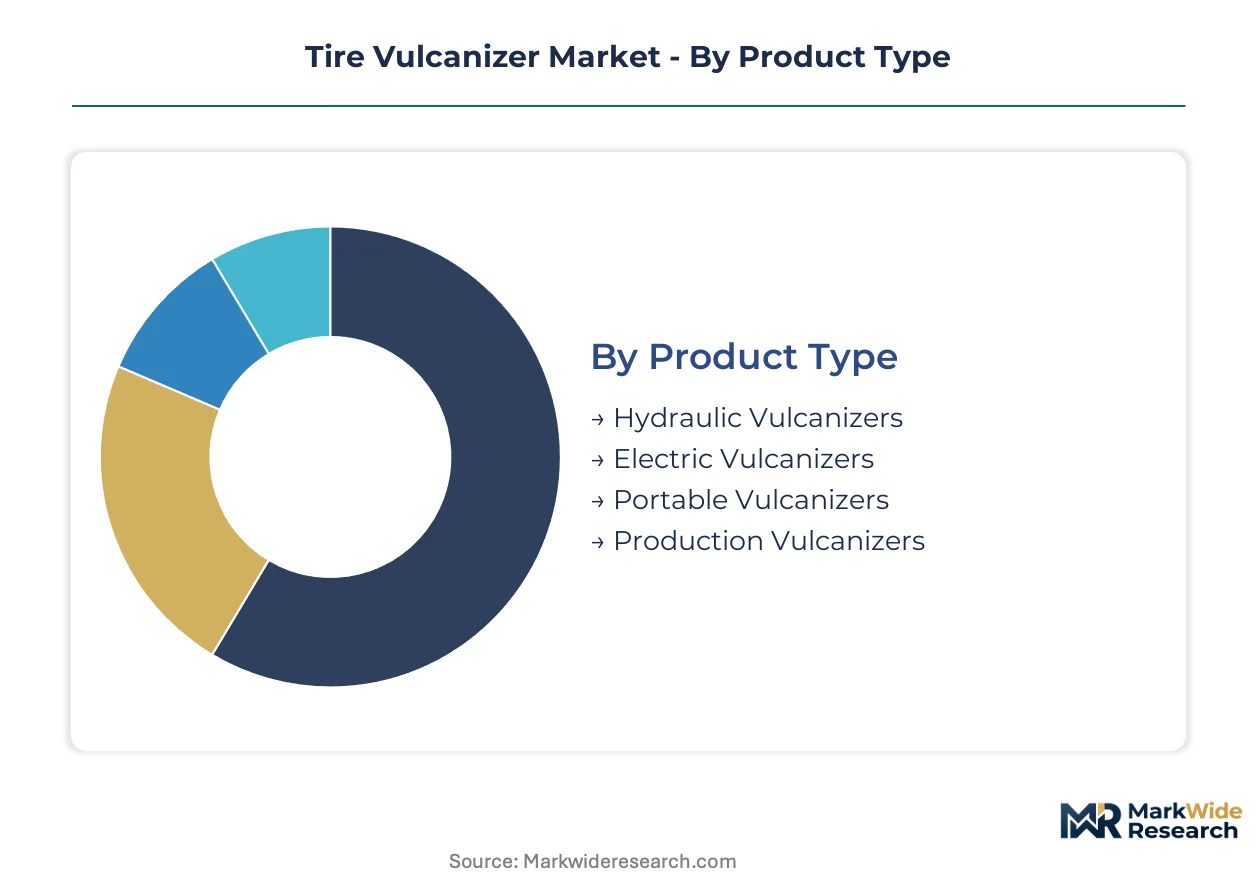
Tire vulcanizer segmentation reveals diverging equipment requirements across curing intensity, tire geometry, and operational scale. Procurement patterns split between OEM tire plants demanding continuous throughput infrastructure and aftermarket operators prioritizing mobility and batch flexibility.
Product Type:
Mature hydraulic platforms dominate installed capacity while electric architectures emerge as the specified choice for greenfield installations under tightening energy regulations.
- Hydraulic Vulcanizers:These systems deploy high-pressure fluid actuation to generate clamping forces exceeding 200 tons, utilizing specialized alloy press frames engineered for decades of cyclic loading. Demand concentrates among legacy tire plants in Thailand and Indonesia where existing boiler infrastructure sustains steam-hydraulic hybrid configurations despite efficiency penalties.
- Electric Vulcanizers:Resistive and induction heating modules eliminate thermal lag and enable precise temperature profiling for silica-compound curing. German and Japanese premium tire manufacturers specify these platforms for high-performance product lines where curing precision affects rolling resistance metrics.
- Portable Vulcanizers:Compact units mounted on service vehicles address roadside tire repair for commercial fleets operating across extended highway networks.
- Production Vulcanizers:Continuous-feed systems integrate with automated tire building and inspection lines at major OEM facilities.
Production vulcanizers retain volume leadership; electric vulcanizers hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity replacement demand from precision-engineered original equipment specifications.
- Passenger Tires:High-volume curing requirements favor automated production vulcanizers with rapid mold-change capabilities. China's Shandong province concentrates manufacturing demand for radial passenger tires exported to North American and European replacement markets.
- Truck Tires:Heavy-duty bias and radial configurations demand extended curing cycles and reinforced press frames. Fleet electrification in California and the Netherlands generates specialized demand for vulcanizers handling silica-compound formulations optimized for battery-electric truck weight distribution.
- Motorcycle Tires:Smaller mold dimensions and lower clamping force requirements enable compact equipment footprints.
- Agricultural Tires:Deep-lug tread patterns and reinforced sidewalls necessitate customized mold designs for farm implement specifications.
Passenger tires retain volume leadership; truck tires hold the steepest expansion curve.
End User:
Customer type determines service intensity, with captive maintenance networks displacing traditional distributor channels among consolidated fleet operators.
- Tire Manufacturers:OEM plants specify integrated automation solutions requiring programmable logic controller compatibility across robotics and warehouse systems. MESNAC anchors supply relationships with Chinese producers through localized engineering support.
- Repair Shops:Independent service facilities prioritize equipment mobility and rapid heat-up characteristics for same-day turnaround.
- Fleet Operators:Commercial vehicle consolidators in Texas and São Paulo now direct-procure vulcanizers with captive aftermarket agreements, bypassing equipment distributors.
- Retail Outlets:Consumer-facing tire dealers favor compact electric units for seasonal replacement demand.
Tire manufacturers retain volume leadership; fleet operators hold the steepest expansion curve.
Technology:
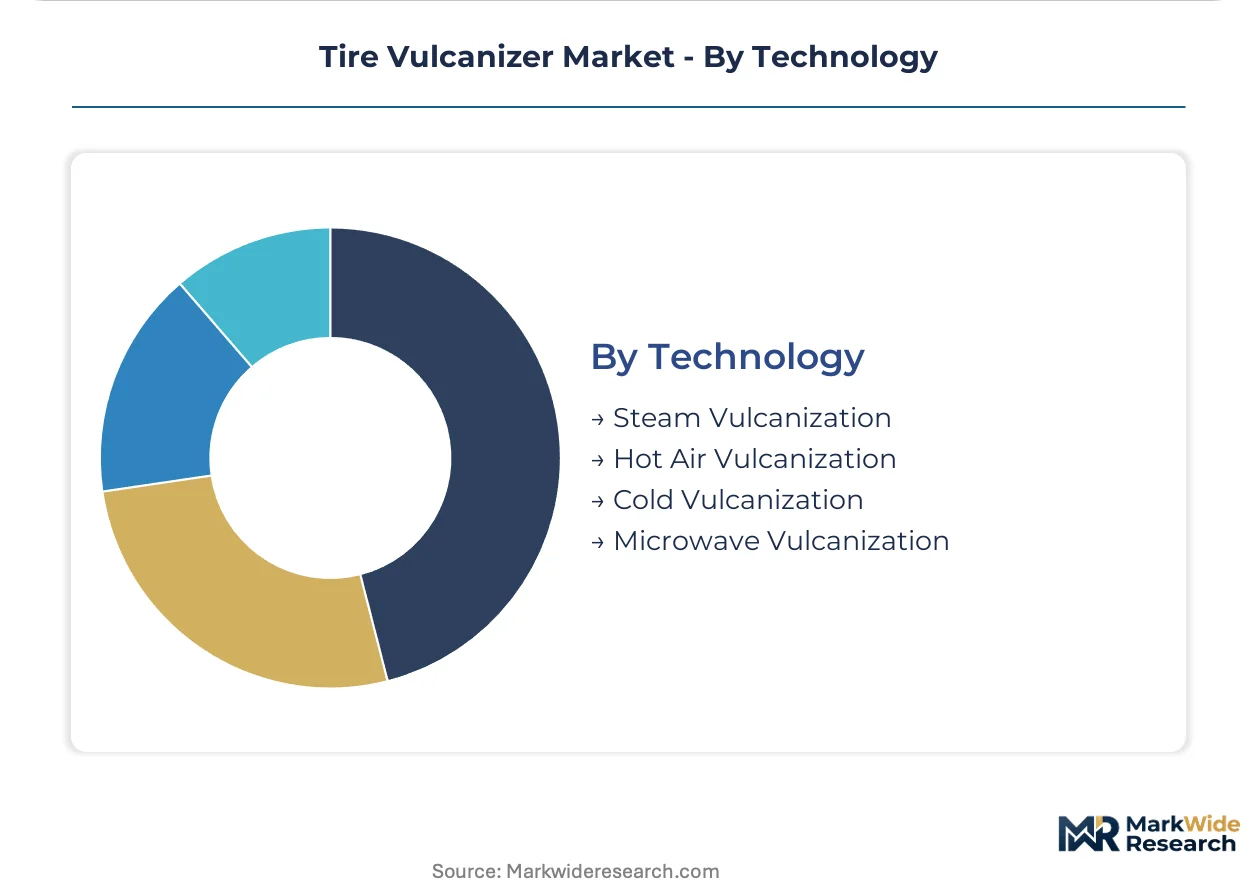
Supply concentration in heating architecture creates switching friction against platform migration despite efficiency mandates.
- Steam Vulcanization:Saturated steam distribution through press platens delivers uniform heat transfer proven over decades of industrial operation. Legacy facilities in Thailand and Indonesia face sunk-cost constraints from existing boiler investments that delay replacement decisions.
- Hot Air Vulcanization:Forced convection systems circulate heated air for curing applications where direct steam contact risks surface contamination.
- Cold Vulcanization:Chemical curing agents enable field repairs without pressurized heating equipment, serving emergency roadside applications.
- Microwave Vulcanization:RF energy penetration accelerates cross-linking kinetics for cycle time compression. Hybrid electric-microwave systems attract R&D investment from press builders with RF engineering partnerships.
Steam vulcanization retains volume leadership; microwave vulcanization holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command pricing premiums for precision-engineered hydraulic systems while Chinese fabricators compete on throughput scale and localized service density. This asymmetry shapes procurement patterns across tire production clusters worldwide.
China
Shandong province concentrates tire manufacturing demand with procurement volumes justifying dedicated vulcanizer service infrastructure. SAMR enforces GB standards on industrial machinery energy consumption that mandate efficiency testing for domestic equipment sales. Qingdao and Yantai host machinery builders expanding maintenance networks to capture aftermarket revenue from coastal tire exporters.
Germany
Premium tire OEMs specify electric vulcanizers with precise temperature profiling for silica-compound curing applications. EU Ecodesign requirements impose energy consumption limits that accelerate replacement cycles for legacy steam systems. Baden-Württemberg engineering clusters supply precision hydraulic components to press builders serving Continental and Michelin specifications.
United States
Commercial fleet operators in Texas direct-procure vulcanizers with captive aftermarket agreements bypassing traditional equipment distributors. EPA emissions guidelines and OSHA workplace safety standards shape press specifications for domestic tire plants. Southeast manufacturing corridors attract greenfield capacity serving replacement tire demand from consolidated trucking fleets.
Japan
Metallurgical expertise in specialized alloy press frames differentiates domestic machinery builders serving high-performance tire lines. METI industrial efficiency programs incentivize electric heating platform adoption at legacy facilities. Nagoya and Osaka industrial zones concentrate tire machinery engineering talent alongside automotive OEM supply chains.
India
PLI scheme incentives for automotive component production attract greenfield tire plants in Gujarat and Tamil Nadu with domestic vulcanizer demand outpacing local equipment supply. BIS certification requirements for industrial machinery create compliance barriers for imported press systems. Chennai and Ahmedabad manufacturing corridors concentrate procurement from fleet operators expanding commercial vehicle service networks.
Tire Vulcanizer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision pumps, valves, and metallurgical frames to final assemblers. The vendor base organizes around three strategic archetypes: European engineering houses with hydraulic heritage, Chinese automation-integrated builders serving manufacturing clusters, and Japanese metallurgical specialists. Competitive moves concentrate on geographic expansion through localized service networks and technology partnerships for hybrid heating architectures.
Within the European engineering tier, HF TireTech Group occupies a position exemplifying hydraulic system premium positioning. Among Asia-Pacific fabricators, MESNAC and Kobe Steel represent contrasting archetypes—integrated automation solutions versus metallurgical durability expertise. These three anchors illustrate how competitive differentiation maps to technical heritage rather than scale alone.
| Leading Market Players |
|---|
| HF TireTech Group |
| Larsen & Toubro |
| Guilin Rubber Machinery |
| Alfred Herbert |
| MESNAC |
| Kobe Steel |
| Beijing BAMTRI Dingsheng Technology |
| Qingdao Yadong Rubber Machinery Group |
| McNeil & NRM |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam container freight corridors transmit steel alloy and hydraulic component cost volatility directly into vulcanizer pricing tiers, compressing margins for standard-configuration builders while amplifying premiums for configured-to-order electric platforms serving EU Ecodesign compliance deadlines.
Pricing Analysis
The customization-premium spread separates configured-to-order electric vulcanizers with induction heating modules from standard steam-hydraulic configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under CE marking and China's GB standards, with volume scale discounts concentrating among Shandong tire manufacturing clusters. Cost compression in standard tiers is intensifying because Japanese and South Korean metallurgical supply constraints transmit alloy price pressure downstream. Fleet operators in Texas and São Paulo exhibit highest price sensitivity through direct-procurement bargaining, while German premium tire OEMs prioritize curing precision over unit cost.
Supply Chain Analysis
Extended payment terms from German and Italian hydraulic component specialists to Asian press assemblers reveal supply-chain finance facilities sustaining working capital through 90-120 day production cycles. Manufacturing concentrates in China, Germany, and Japan, with specialized alloy press frame fabrication drawing from Japanese metallurgical expertise and precision pump production anchored in German engineering clusters. Single-source vulnerability concentrates in Italian valve manufacturing, where geographic clustering creates lead time exposure for vulcanizer assembly schedules. Distribution runs through direct sales relationships displacing traditional distributor intermediaries, with captive service agreements capturing aftermarket revenue from consolidated fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tire vulcanizer procurement is shifting toward platform-economics logic as electric heating architectures and predictive maintenance software create interoperable production ecosystems, with MESNAC's integrated automation solutions illustrating how control-system compatibility drives vendor lock-in across Chinese manufacturing clusters.
For Market Incumbents: Harden service network density in Shandong province to defend against captive maintenance contracts from fleet operators. Deepen backward integration into induction heating module production to reduce dependency on German RF engineering partnerships. Prioritize programmable logic controller compatibility investments to neutralize emerging automation-integrated competitors threatening OEM tire plant relationships. For New Entrants and Emerging Players: Mid-size tire producers in Gujarat and Tamil Nadu lacking in-house technical staff represent the most penetrable entry point, as PLI scheme incentives attract greenfield capacity ahead of domestic equipment supply. Outcome-based service contracts using vibration and thermal sensors enable pricing separation from capital equipment sales. Target predictive maintenance platform partnerships with Indian distributors to bypass established direct-sales channels. For Investors and Strategic Acquirers: Specialized RF engineering firms with microwave-assisted curing patents present acquisition targets as hybrid heating systems converge. Long-term viability favors platform integrators over component specialists as tire plants prioritize automation compatibility. Watch for GB standard enforcement intensity as the signal indicating acceleration or delay in China's electric vulcanizer replacement cycle.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Induction Heating | Captive supply of RF modules reduces dependency on German engineering partnerships and compresses lead times. |
| Captive Service Network Expansion | Localized maintenance infrastructure in Shandong captures aftermarket revenue from coastal tire exporters. |
| Hybrid Heating Architecture Partnership | Technology licensing with microwave specialists enables cycle time compression for premium tire manufacturers. |
| Predictive Maintenance Platform Launch | Sensor-based outcome pricing targets mid-size producers lacking in-house technical capabilities. |
| PLC Compatibility Certification Investment | Automation integration credentials secure OEM tire plant specifications against emerging competitors. |
Methodological Framework
Initial hypotheses were tested against primary input from tire plant maintenance directors, OEM procurement teams, aftermarket service heads, and hydraulic component engineering leads, and refined through secondary validation against customs trade data, SAMR GB standard filings, SEC equipment manufacturer disclosures, and tire industry production databases. Bottom-up installed base estimates triangulated with top-down energy efficiency mandate impact modeling.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning heating architecture, press frame metallurgy grade, automation integration depth, and regional regulatory compliance tier. CAGRs derived from replacement cycle compression under EU Ecodesign deadlines and China's dual carbon goals, cross-referenced with steel alloy price elasticity and fleet electrification tire specifications.
Practitioners should monitor GB standard enforcement intensity, EU carbon border adjustment implementation, and microwave curing technology maturation for early signals of platform migration acceleration. Forecasts reflect assumptions regarding regulatory deadline adherence and alloy supply stabilization. Macroeconomic volatility in steel markets, regulatory timeline slippage, or breakthrough curing technology commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Electric Parking Brake Actuator Components Market