
 Automotive Weatherstrips Market | 2026-2036
Automotive Weatherstrips Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Weatherstrips Market Analysis
EPDM rubber is realigning cost-performance benchmarks across door and window seal applications as manufacturers balance weather resistance against lightweighting targets. Cooper Standard leverages its North American manufacturing footprint to sustain OEM supply relationships for light vehicle platforms. Toyoda Gosei anchors its position through deep integration with Japanese automotive parent networks and regional EV programs. Hutchinson competes on material science breadth, offering polyurethane and silicone alternatives for thermal-critical sealing zones.
Automotive weatherstrips are elastomeric sealing components, typically extruded from rubber compounds with specific Shore A hardness ratings between 50 and 80, designed to prevent water ingress, air leakage, and noise transmission at vehicle closure interfaces. Their primary purpose spans cabin comfort management, structural corrosion protection, and aerodynamic efficiency optimization across passenger and commercial vehicle architectures. Door seals occupy the largest volume position due to universal fitment requirements across all vehicle classes, while silicone formulations represent the fastest-expanding material category driven by thermal stability needs in electric vehicle battery enclosures. OEM channel concentration reflects the capital-intensive nature of co-development programs with vehicle assemblers, though aftermarket providers capture margin pools in aging fleet maintenance segments.
The EPA and NHTSA jointly shape product standards through Corporate Average Fuel Economy enforcement and crash safety sealing requirements, compelling suppliers to validate flame-retardant and low-permeability specifications. REACH and RoHS frameworks in Europe restrict hazardous substance content in rubber compounding, directly affecting material sourcing decisions for exporters serving multiple regulatory jurisdictions. Stakeholders must monitor evolving battery enclosure sealing protocols as thermal runaway containment standards become decisive in supplier qualification processes.
Market Dynamics
Electric vehicle thermal management requirements are forcing a complete redesign of sealing architectures, as battery enclosure protection standards displace legacy door-and-window specifications as the primary engineering priority for compound development.
Growth Catalysts
- EPA-NHTSA CAFE enforcement:Corporate Average Fuel Economy mandates in the United States compel automakers to adopt lighter EPDM formulations that reduce vehicle mass while maintaining compression set resistance.
- China EV production concentration:Domestic battery electric vehicle assembly volumes in China pull specialized silicone weatherstrip procurement toward local supply chain hubs serving BYD, NIO, and Xpeng platforms.
- Thermal runaway containment protocols:Battery enclosure sealing specifications from UN ECE R100 and China's GB/T standards create mandatory upgrade cycles for flame-retardant compound validation.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene monomer prices fluctuate with crude oil benchmarks, compressing margin predictability for EPDM compounders serving long-term OEM contracts.
- East Asian supply concentration:Silicone rubber precursor manufacturing clusters in Japan and South Korea create geographic single-point vulnerability for thermal-grade weatherstrip producers.
- Polymer substitution in non-critical zones:Thermoplastic vulcanizates from Celanese and Mitsui displace conventional rubber in secondary sealing applications where temperature extremes are absent.
Strategic Opportunities
- India passenger vehicle localization:Maruti Suzuki and Hyundai Motor India expansion programs create demand for domestic weatherstrip manufacturing capacity to serve sub-4-meter compact platforms.
- Vehicle-to-grid integration standards:Bidirectional charging hardware sealing requirements open new specification categories for moisture-resistant compounds in outdoor electrical connection points.
- Direct-to-fleet aftermarket channels:Commercial vehicle leasing companies in Germany and the United States consolidate maintenance procurement, bypassing traditional distributor networks for high-volume seal replacement programs.
Industry Challenges
- Multiphysics simulation talent scarcity:Finite element analysis expertise combining fluid dynamics, thermal transfer, and material creep behavior remains concentrated among senior engineers at Tier-1 suppliers.
- Homologation timeline compression:OEM platform development cycles now demand weatherstrip validation in 18-month windows versus historical 36-month programs, straining testing laboratory capacity.
- Bonding process IP fragmentation:Co-extrusion adhesion between EPDM substrates and thermoplastic carriers involves patent thickets held by chemical specialists, complicating formulation freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Weatherstrips Market |
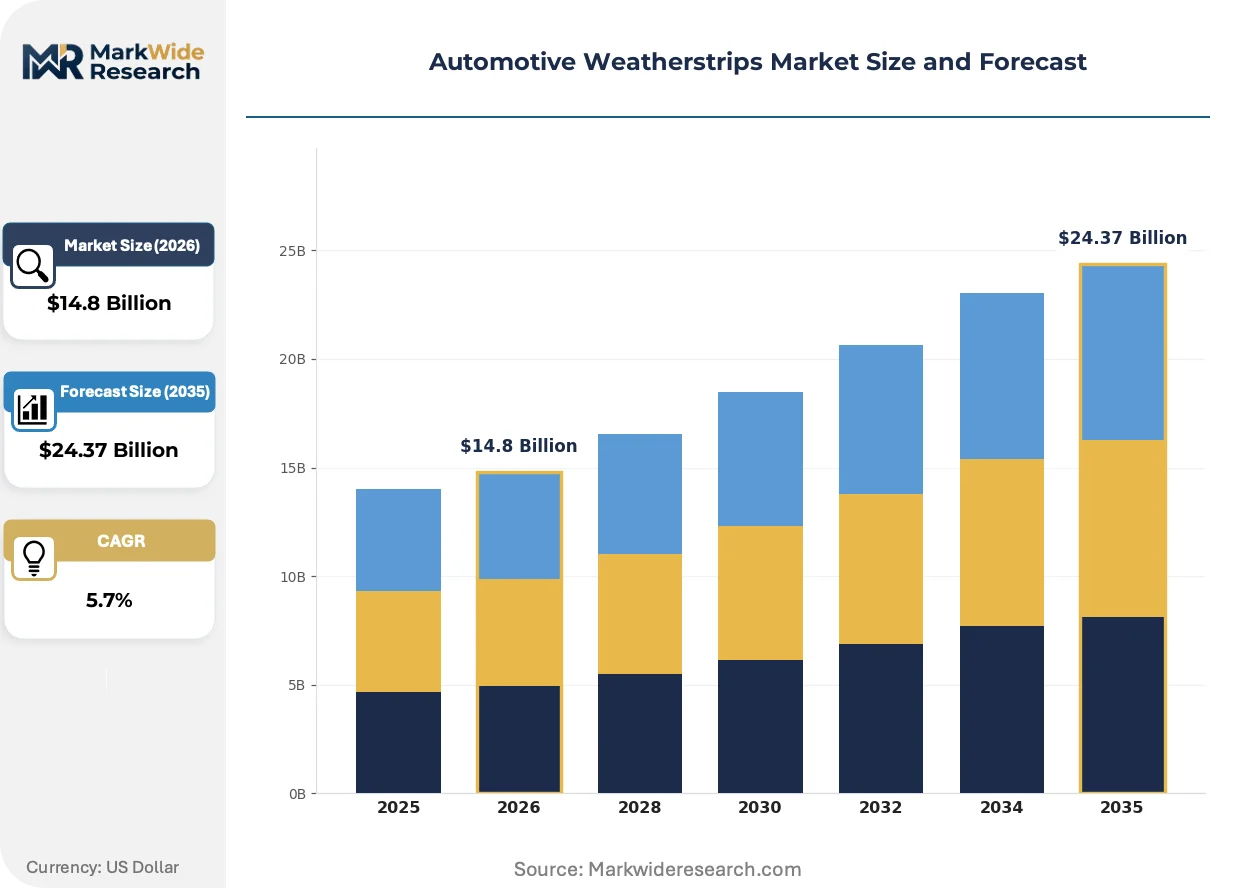
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Door Seals, Window Seals, Sunroof Seals, Hood Seals Material: Rubber, Polyurethane, PVC, Silicone Application: Light Vehicles, Heavy-Duty Vehicles, Commercial Vehicles, Electric Vehicles End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers |
| Companies Covered | Cooper Standard, Toyoda Gosei, Hutchinson, Trelleborg, Henninges Automotive, Nishikawa, SaarGummi, KACO, Dura Automotive Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Weatherstrips Market Emerging Trajectories
Material science convergence with vehicle electrification is collapsing the traditional boundary between cabin comfort sealing and critical battery protection, forcing compounders to serve dual thermal and mechanical performance specifications simultaneously.
Multi-hardness co-extrusion technology is modularizing weatherstrip construction by enabling discrete functional zones within single continuous profiles. Battery enclosure manufacturers at LG Energy Solution and SK On facilities specify these architectures to isolate high-temperature zones near power electronics from ambient-temperature mounting interfaces. The approach is modularizing supplier relationships as compound specialists partner with extrusion equipment makers to deliver integrated production cells rather than standalone material shipments.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber compounding are eliminating legacy oil plasticizers from European-sourced formulations. Compounders serving Stellantis and Volkswagen Group platforms have completed transitions to paraffinic and naphthenic alternatives, with validation costs absorbed through multi-year supply agreements. The regulatory pressure is most acute in Germany, where KBA type-approval documentation now requires explicit PAH content declarations for all elastomeric sealing components.
Fleet operators are consolidating aftermarket procurement through integrated maintenance management platforms that specify component performance metrics rather than manufacturer part numbers. Samsara and Geotab telematics systems track door seal degradation through cabin humidity sensors, triggering replacement orders before failure. This specification-driven purchasing is most advanced in United States commercial vehicle segments, where Penske and Ryder leasing divisions negotiate direct supply relationships with weatherstrip manufacturers for standardized across-make replacement programs.
Automotive Weatherstrips Market Segmentation
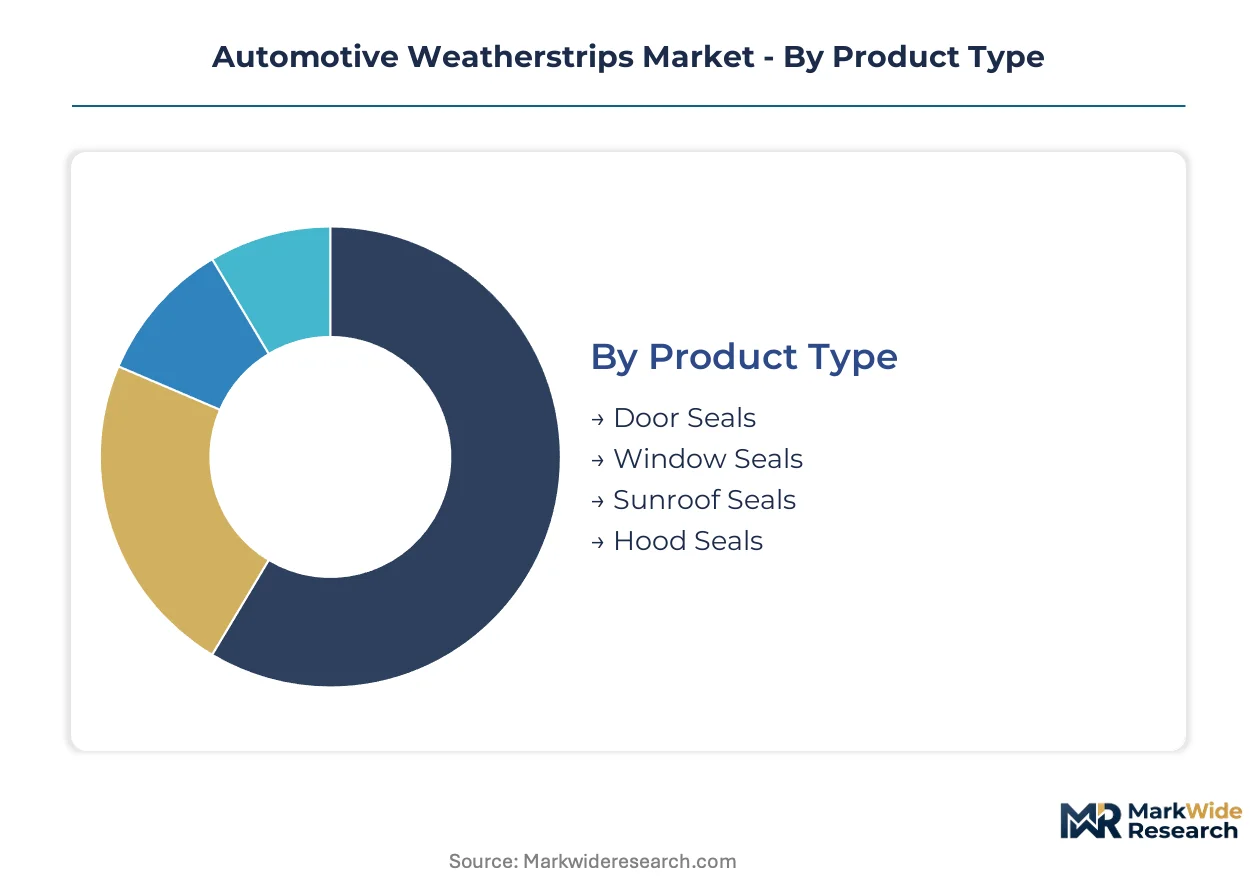
Automotive weatherstrip segmentation reveals how upgrade cycles concentrate procurement decisions across distinct technical specifications and vehicle architectures. Material science evolution and electrification mandates are fragmenting traditional supply relationships as compound requirements diverge across thermal-critical and comfort-oriented applications.
Product Type:
Door seal replacement cycles anchor aftermarket revenue stability, while thermal management demands are compressing development timelines for battery-adjacent sealing architectures.
- Door Seals:Extruded EPDM profiles with co-molded corner joints form the primary cabin barrier against water and noise intrusion. Demand concentrates in China and the United States where high-volume passenger platforms require standardized compression set specifications across multiple model generations.
- Window Seals:Dual-durometer constructions combine rigid mounting sections with flexible sealing lips to accommodate glass channel tolerances. European OEMs at Stellantis and Volkswagen Group facilities specify these for frameless door designs where aerodynamic drag reduction targets exceed 5% improvement thresholds.
- Sunroof Seals:Peroxide-cured silicone formulations resist UV degradation across panoramic glass expanses exceeding 1.5 square meters.
- Hood Seals:Dense EPDM sponge constructions manage engine bay thermal cycling between -40°C and 150°C operational extremes.
Door Seals sits at the top of the volume ranking, with Sunroof Seals climbing the fastest as panoramic roof penetration expands across premium electric platforms.
Material:
Cost tier differentiation separates commodity EPDM formulations from thermal-grade silicone compounds, with intermediate polyurethane and PVC categories capturing price-sensitive volume applications.
- Rubber:EPDM terpolymer formulations dominate through sulfur or peroxide vulcanization routes delivering Shore A hardness between 50 and 80. Chinese domestic suppliers at Shandong and Jiangsu manufacturing clusters serve BYD and NIO procurement programs with localized compound development.
- Silicone:VMQ and FVMQ polymers withstand continuous service temperatures exceeding 200°C in battery enclosure applications. SK On and LG Energy Solution facilities in South Korea specify these for thermal runaway containment zones where flame retardancy to UL 94 V-0 standards is mandatory.
- Polyurethane:Castable systems offer abrasion resistance for sliding door applications with mechanical wear exposure.
- PVC:Plasticized formulations retain position in cost-optimized commercial vehicle secondary sealing where temperature extremes remain moderate.
Rubber commands the highest absolute volume position, with Silicone expanding most quickly as battery protection specifications displace legacy cabin comfort priorities.
Application:
Customer type concentration separates capital-intensive OEM co-development programs from specification-driven fleet maintenance procurement.
- Light Vehicles:Passenger car platforms under 3.5 tonnes gross vehicle weight require multi-cavity sealing profiles integrating primary and secondary compression lips. Maruti Suzuki and Hyundai Motor India expansion programs are pulling localized manufacturing capacity toward sub-4-meter compact architectures.
- Electric Vehicles:Battery electric platforms demand dual-function sealing architectures combining cabin comfort with power electronics thermal management. Chinese GB/T and UN ECE R100 standards mandate flame-retardant compound validation for enclosure sealing, creating qualification barriers for conventional EPDM suppliers.
- Heavy-Duty Vehicles:Commercial truck specifications prioritize durability across million-kilometer service intervals.
- Commercial Vehicles:Fleet operators consolidate procurement through telematics-integrated maintenance platforms tracking seal degradation.
Light Vehicles maintains volume leadership, with Electric Vehicles gaining share fastest as thermal management specifications redirect engineering resources.
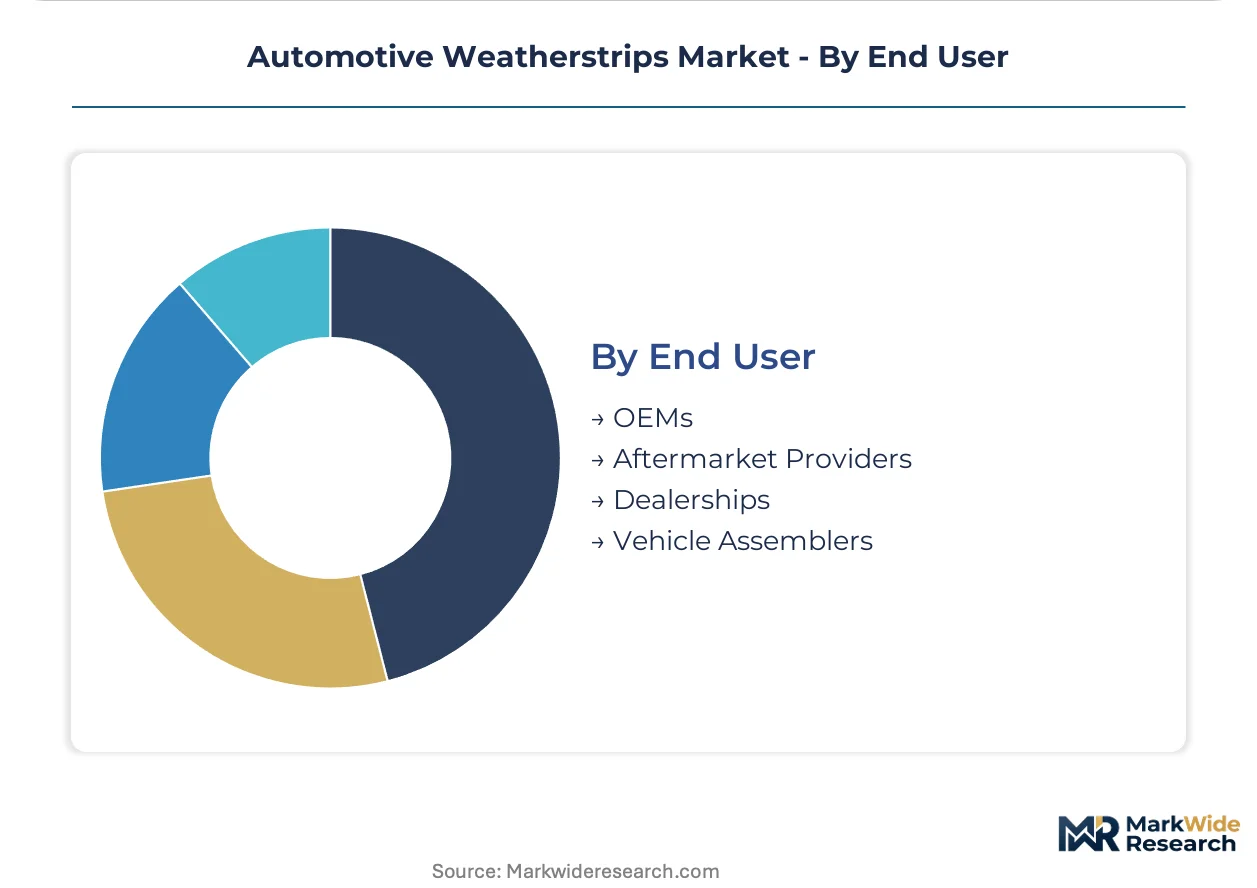
End User:
Supply concentration patterns favor direct OEM relationships for new platform development, while aftermarket channels fragment across distributor networks and emerging fleet-direct models.
- OEMs:Original equipment manufacturers specify weatherstrips through 36- to 48-month co-development cycles involving CAD integration and prototype validation. NHTSA crash safety and EPA fuel economy mandates in the United States compel lightweight EPDM adoption through multi-year supply agreements.
- Aftermarket Providers:Independent distributors and service chains capture replacement demand from aging vehicle fleets. Samsara and Geotab telematics systems enable predictive maintenance procurement in United States commercial segments.
- Dealerships:Authorized service networks handle warranty-related seal replacement under manufacturer service programs.
- Vehicle Assemblers:Contract manufacturing operations at Magna Steyr and Valmet Automotive facilities specify weatherstrips for multi-brand assembly programs.
OEMs occupy the dominant procurement position, with Aftermarket Providers expanding fastest as fleet telematics enable specification-driven replacement scheduling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu manufacturing clusters anchor the global supply base for EPDM weatherstrip compounds. Domestic EV production volumes in China pull procurement toward localized supply chains. Regulatory divergence across major automotive markets forces compounders to maintain parallel formulation portfolios.
China
BYD and NIO platforms drive specialized silicone weatherstrip demand for battery enclosure sealing. GB/T standards mandate flame-retardant compound validation for thermal runaway containment. Shandong and Jiangsu manufacturing clusters serve domestic OEM procurement programs with localized EPDM development.
United States
EPA CAFE enforcement compels automakers toward lighter EPDM formulations reducing vehicle mass. NHTSA crash safety mandates require validated flame-retardant and low-permeability specifications. Detroit-area manufacturing corridors sustain Cooper Standard and Tier-1 supply relationships for light vehicle platforms.
Germany
KBA type-approval documentation now requires explicit PAH content declarations for all elastomeric sealing components. REACH Annex XVII restrictions eliminate legacy oil plasticizers from European-sourced formulations. Stuttgart and Wolfsburg engineering centers validate multi-hardness co-extrusion architectures for Stellantis and Volkswagen Group platforms.
South Korea
SK On and LG Energy Solution facilities specify VMQ and FVMQ polymers for battery thermal management zones. UN ECE R100 standards drive flame-retardant compound qualification to UL 94 V-0 benchmarks. Gyeonggi-do and Ulsan industrial complexes concentrate precursor manufacturing for thermal-grade silicone weatherstrips.
India
Maruti Suzuki and Hyundai Motor India expansion programs create demand for domestic weatherstrip manufacturing capacity. BIS certification requirements shape compound specifications for sub-4-meter compact platforms. Tamil Nadu and Haryana automotive corridors pull localized sealing component production toward OEM assembly hubs.
Automotive Weatherstrips Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers position production cells near battery manufacturing clusters. The vendor base separates into three tiers: integrated rubber compounders with extrusion capabilities, specialized silicone formulators serving thermal-critical applications, and regional EPDM suppliers capturing cost-optimized volume segments. Strategic archetypes include material science generalists, automotive parent-integrated suppliers, and battery-focused thermal specialists. Geographic expansion and portfolio diversification represent the dominant competitive moves as compound requirements diverge across cabin comfort and battery protection specifications.
Within the automotive parent-integrated tier, Toyoda Gosei exemplifies deep OEM network alignment. Among diversified material science groups, Hutchinson occupies a position spanning polyurethane and silicone alternatives. At the North American manufacturing end, Cooper Standard anchors regional supply relationships through localized production footprint. These three represent distinct strategic postures: parent-network integration, material breadth, and geographic proximity to OEM assembly.
| Leading Market Players |
|---|
| Cooper Standard |
| Toyoda Gosei |
| Hutchinson |
| Trelleborg |
| Henninges Automotive |
| Nishikawa |
| SaarGummi |
| KACO |
| Dura Automotive Systems |
| Others |
Supply Flow & Price Mechanics
Finite element analysis expertise concentrated in senior engineers at Tier-1 suppliers in Germany and Japan creates labor-cost differentials that widen pricing-tier spreads between thermal-grade silicone formulations and commodity EPDM compounds.
Pricing Analysis
Input-cost pass-through from ethylene and propylene monomer volatility compresses margin predictability for EPDM compounders serving long-term OEM contracts. Three-tier pricing structure across premium silicone, standard EPDM, and economy PVC levels separates battery enclosure specifications from cabin comfort applications. Pricing pressure stems from thermoplastic vulcanizate substitution in non-critical sealing zones where temperature extremes are absent. Fleet operators through telematics-integrated platforms exhibit lowest price sensitivity due to specification-driven procurement, while independent aftermarket distributors face highest compression.
Supply Chain Analysis
Dual-sourcing requirements mandated by OEM platform engineers at Stellantis and Volkswagen Group facilities force qualification of multiple compounders for each thermal-grade specification. Supply concentrates in China for EPDM manufacturing clusters, South Korea for silicone precursor production, and Germany for polyurethane formulation expertise. Raw material dependencies span petroleum-derived ethylene-propylene feedstocks, silicon metal for VMQ polymers, and isocyanates for polyurethane systems. Single-source vulnerability persists in East Asian silicone precursor manufacturing. Distribution runs through Tier-1 supplier direct delivery to OEM assembly plants, with aftermarket channels fragmenting across distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Chinese domestic EV procurement programs and European REACH-compliant formulation requirements, where regulatory compliance cost differentials exceed raw material spreads.
For Market Incumbents: Lock in multi-year supply agreements with battery manufacturers at LG Energy Solution and SK On facilities before thermal runaway containment standards harden qualification barriers. Secure backward integration into silicone precursor production to offset East Asian supply concentration risks. Prioritize co-extrusion equipment partnerships that deliver integrated production cells rather than standalone material shipments. For New Entrants and Emerging Players: Begin with India passenger vehicle localization opportunities as Maruti Suzuki and Hyundai Motor India expansion programs create demand for domestic manufacturing capacity. Target sub-4-meter compact platform specifications where BIS certification requirements remain less stringent than battery enclosure protocols. Pursue direct-to-fleet aftermarket channels bypassing traditional distributor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional EPDM suppliers capturing cost-optimized volume segments, while specialized silicone formulators serving thermal-critical applications command scarcity premiums. Long-term viability hinges on qualification for electric vehicle battery enclosure specifications as thermal management requirements displace legacy door-and-window priorities. Monitor UN ECE R100 and China GB/T standard evolution as the decisive inflection signal for compound validation barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Hardness Co-Extrusion Technology Deployment | Enables LG Energy Solution and SK On to isolate high-temperature battery zones from ambient mounting interfaces. |
| Silicone Precursor Backward Integration | Reduces geographic single-point vulnerability in Japan and South Korea thermal-grade supply clusters. |
| India Manufacturing Footprint Expansion | Positions capacity near Maruti Suzuki and Hyundai Motor India sub-4-meter compact assembly hubs. |
| REACH-Compliant Formulation Transition | Eliminates polycyclic aromatic hydrocarbons for Stellantis and Volkswagen Group KBA type-approval compliance. |
| Fleet-Direct Aftermarket Channel Development | Bypasses traditional distributors for Penske and Ryder telematics-integrated replacement programs. |
Methodological Framework
Direct dialogue with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and compound R&D directors grounded qualitative findings in operational reality. Secondary validation drew from EPA CAFE enforcement documentation, NHTSA crash safety filings, REACH Annex XVII restriction updates, UN ECE R100 technical specifications, and vehicle production databases. Bottom-up and top-down triangulation cross-checked segment assumptions against aggregate market trajectories.
Bottom-up modeling aggregated content-per-vehicle estimates across door seal, window seal, sunroof seal, and hood seal configurations by vehicle class and propulsion architecture. Top-down analysis calibrated total market scale against regional production cluster outputs and OEM supply agreement disclosures. CAGRs derived from regression against historical correlation patterns with automotive production volumes and electrification penetration rates. Forecast inputs incorporated battery enclosure sealing specification evolution and thermal runaway containment protocol adoption curves.
Several conditions sit outside the modeled scope, including sudden petrochemical feedstock price shocks, unilateral tariff impositions on East Asian silicone precursors, and accelerated thermoplastic vulcanizate substitution in secondary applications. Deviation in battery thermal management standard enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
Automotive Electric Drivetrain Components Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Global Automotive Leaf Spring Market