
 Brake Lathe Machine Market | 2026-2036
Brake Lathe Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Brake Lathe Machine Market Analysis
Buyer concentration across fleet services is broadening as logistics operators internalize brake maintenance to reduce downtime and vendor dependency. AMMCO leverages its established distribution network to serve independent repair chains across North America. Hunter Engineering Company sustains technology leadership through precision alignment integration with brake service workflows. Hofmann Megaplan anchors European demand with bench-mounted systems tailored to compact workshop footprints.
A brake lathe machine resurfaces brake discs and drums by removing material to restore flatness and parallelism within tolerances typically measured in thousandths of an inch. These machines employ either manual feed mechanisms or CNC-controlled cutting paths to achieve specified surface finishes critical to braking performance. CNC lathe systems command premium positioning due to repeatability requirements in high-volume fleet environments. Bench-mounted installations dominate urban repair shops where floor space constraints dictate equipment selection. Automotive repair shops represent the core demand pool, though manufacturing plants are expanding in-house resurfacing capacity to support just-in-time assembly lines.
OSHA machine guarding standards and EPA metalworking fluid disposal regulations shape equipment specifications and operating costs for brake lathe operators across the United States. The EU Machinery Directive and CE marking requirements govern European market access, compelling manufacturers to certify emergency stop functionality and electrical safety. Stakeholders must weigh compliance investment against automation returns as regulatory thresholds tighten and labor scarcity intensifies.
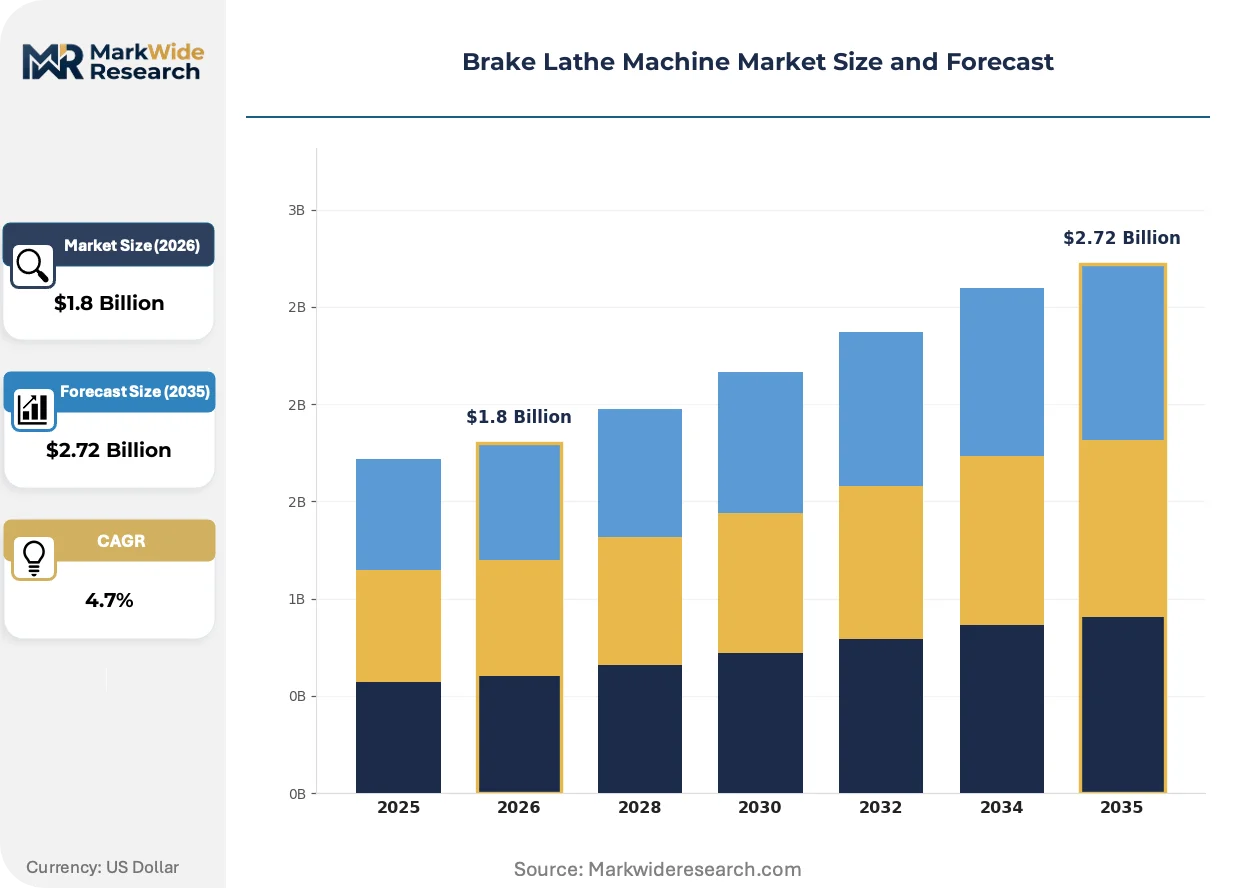
Market Dynamics
Fleet operators are internalizing brake maintenance to eliminate third-party downtime, forcing equipment vendors to reconfigure service models around captive shop networks and predictive resurfacing schedules.
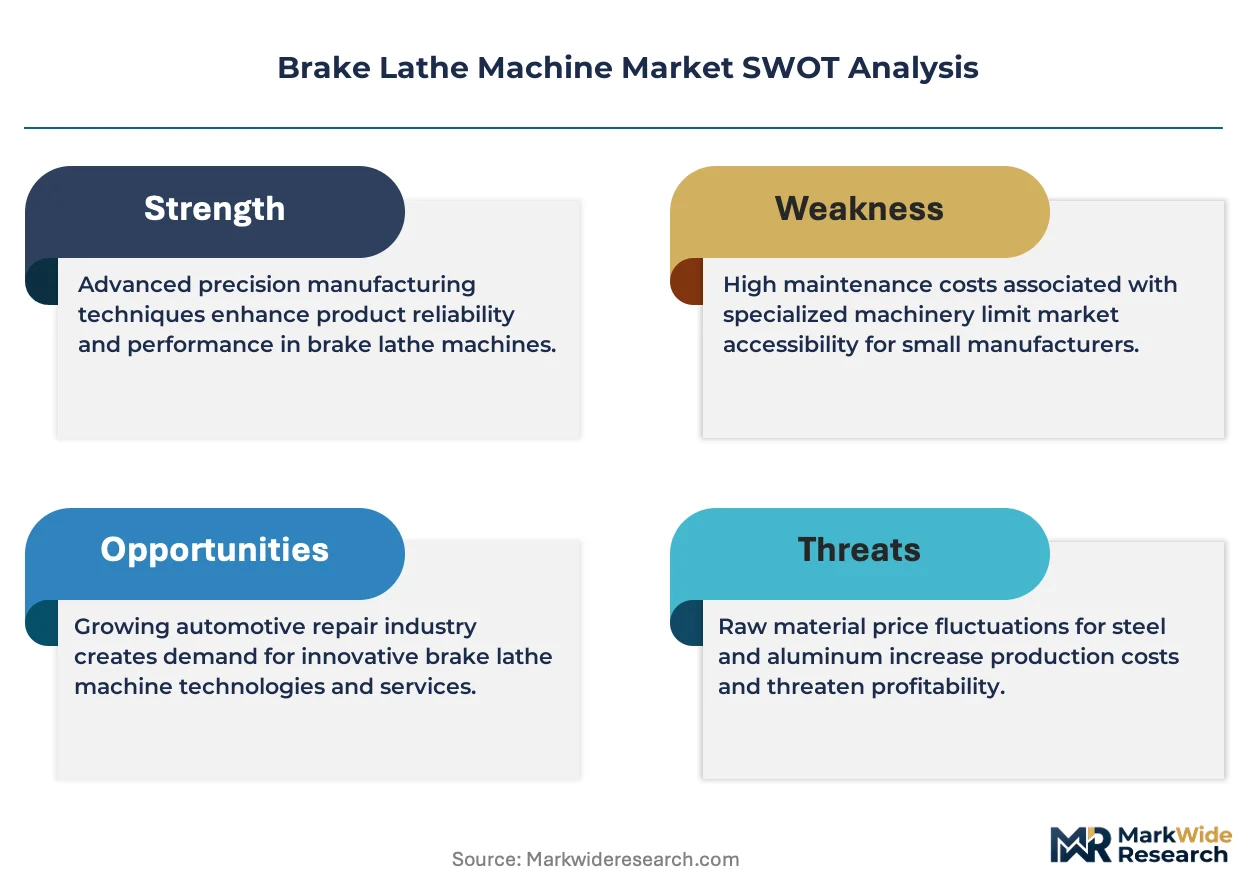
Growth Catalysts
- OSHA Machine Guarding Standards:Workplace safety mandates in the United States are compelling repair facilities to upgrade from open-belt manual lathes to enclosed CNC systems with interlocked guards.
- Commercial Vehicle Density:Heavy-duty truck fleets in Germany and the United States are expanding in-house brake shops to maintain uptime guarantees on just-in-time logistics contracts.
- Dual-Carbon Policy Framework:China's MEE regulations on metalworking waste recovery are accelerating adoption of closed-loop coolant systems integrated with CNC brake lathes.
Market Restraints
- Input Cost Volatility:Tungsten carbide cutting insert prices fluctuate with rare earth supply constraints from concentrated Chinese processing facilities.
- Technical Limitation:Conventional bench-mounted lathes cannot achieve the runout tolerances required for carbon-ceramic brake discs on performance electric vehicles.
- Regulatory Friction:The EU Machinery Directive's CE marking timeline adds six to nine months to product launch cycles for non-European manufacturers.
Strategic Opportunities
- Underpenetrated Fleet Segment:Owner-operator trucking networks in India lack centralized maintenance infrastructure, creating whitespace for mobile brake lathe service units.
- Technology Convergence:Integration of laser measurement systems with CNC cutting paths enables automated compensation for disc thickness variation without operator intervention.
- Regulatory Tailwind:The US IRA's commercial vehicle electrification incentives are expanding electric truck fleets that require specialized low-dust brake resurfacing protocols.
Industry Challenges
- CNC Programming Skill Gap:Independent repair shops struggle to recruit operators capable of G-code editing and toolpath optimization for variable disc geometries.
- Integration Complexity:Legacy shop management software lacks API connectivity to modern lathe telemetry systems, forcing manual data reconciliation for compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brake Lathe Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Lathe, CNC Lathe, Semi-Automatic Lathe, Electric Lathe Installation Type: Floor-mounted, Bench-mounted, Portable, Wall-mounted End User: Automotive Repair Shops, Manufacturing Plants, Fleet Services, DIY Enthusiasts Power Rating: High Power, Medium Power, Low Power, Variable Power |
| Companies Covered | AMMCO, Hofmann Megaplan, Hunter Engineering Company, RELS, Accu-Turn, Hennessy Industries, Multipro Machines, Ammco 4000E, Pro-Cut International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brake Lathe Machine Market Emerging Trajectories
Digital measurement integration and predictive maintenance protocols are compressing brake service cycles while regulatory pressure on particulate emissions reshapes equipment specifications across major automotive markets.
Automated tool presetting systems with RFID-tagged cutting heads are electrifying setup workflows in high-volume fleet environments. Major logistics operators in the United States are deploying these systems to eliminate manual offset measurements. The technology is electrifying throughput benchmarks that previously required dedicated setup technicians.
The EPA's National Emission Standards for Hazardous Air Pollutants for metal finishing operations are mandating mist collection efficiency above 99 percent for new equipment installations. This is forcing manufacturers to redesign spindle enclosures and vacuum extraction architectures. High-volume shops in California and Texas are responding by pre-filtering installations to grandfather existing equipment under phased compliance deadlines.
Service contract unbundling is fragmenting traditional equipment-plus-maintenance bundles into subscription-based cutting tool programs and standalone software licenses. Independent repair chains are adopting per-disc pricing models that shift capital risk to distributors. This pattern is most visible in Germany's Mittelstand workshop segment, where liquidity constraints favor operational expenditure structures.
Brake Lathe Machine Market Segmentation
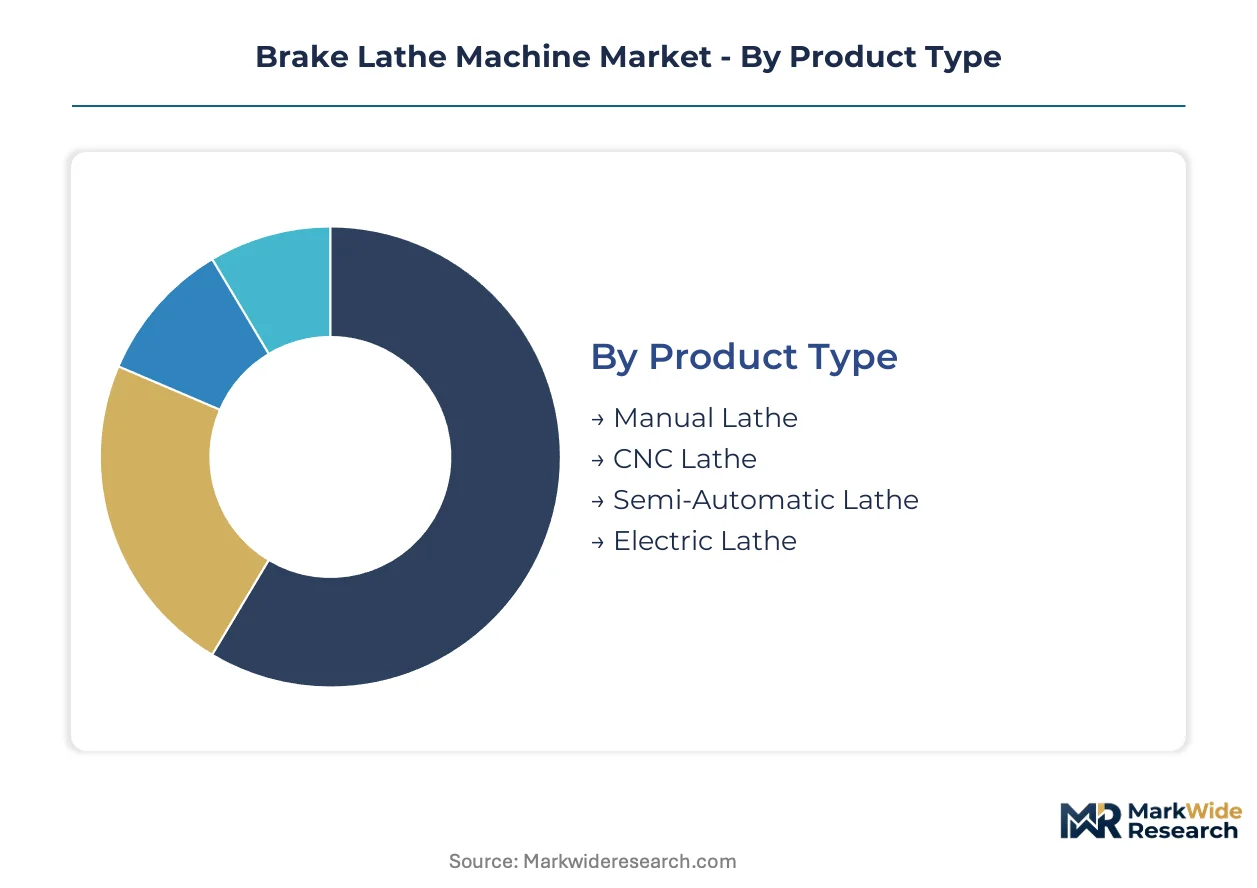
Brake lathe procurement patterns diverge sharply across operational contexts. Fleet operators prioritize automation and throughput, while independent shops balance floor space constraints against capital budgets. Equipment specifications cascade from these fundamental trade-offs.
Product Type:
CNC-controlled cutting paths separate high-volume fleet operations from intermittent repair workflows.
- CNC Lathe:Computer-numerical control systems execute repeatable cutting paths with minimal operator intervention. Heavy-duty truck fleets in Germany and the United States specify these systems to maintain uptime guarantees on just-in-time logistics contracts.
- Manual Lathe:Open-belt mechanical feed mechanisms demand skilled operator judgment for depth-of-cut decisions. Independent repair shops in India's owner-operator trucking networks favor these units where labor costs offset automation premiums.
- Semi-Automatic Lathe:Hybrid systems combine manual setup with automated feed cycles for mid-volume operations.
- Electric Lathe:Brushless motor architectures deliver torque consistency without pneumatic infrastructure requirements.
Mature deployment sits with Manual Lathe systems. Newer deployment is concentrated in CNC Lathe configurations.
Installation Type:
Physical footprint constraints dictate architectural selection across workshop real estate profiles.
- Bench-mounted:Compact spindle assemblies bolt to existing work surfaces, preserving floor space in urban repair facilities. Germany's Mittelstand workshop segment specifies Hofmann Megaplan systems tailored to these spatial limitations.
- Floor-mounted:Rigid column constructions absorb vibration from heavy disc resurfacing. Fleet maintenance depots in Texas and California deploy these for continuous-duty cycles on commercial vehicle brake drums.
- Portable:Mobile units service remote equipment without workshop infrastructure.
- Wall-mounted:Vertical spindle orientations reclaim floor space in converted retail locations.
Volume concentration favors Floor-mounted installations. Fastest expansion is occurring in Portable configurations for field service applications.
End User:
Maintenance economics and capital access shape demand intensity across customer categories.
- Fleet Services:Captive maintenance operations internalize brake resurfacing to eliminate third-party downtime. Logistics operators in the United States are expanding procurement to support predictive resurfacing schedules.
- Automotive Repair Shops:Independent facilities serve retail customers with intermittent demand patterns. These operations favor bench-mounted manual systems where OSHA machine guarding upgrades are pending.
- Manufacturing Plants:Just-in-time assembly lines demand in-house resurfacing capacity for production continuity.
- DIY Enthusiasts:Consumer-grade units address hobbyist restoration projects with limited precision requirements.
Capital deployment is heaviest in Fleet Services. Technology adoption is climbing the fastest in Manufacturing Plants integrating lathe telemetry with shop management software.
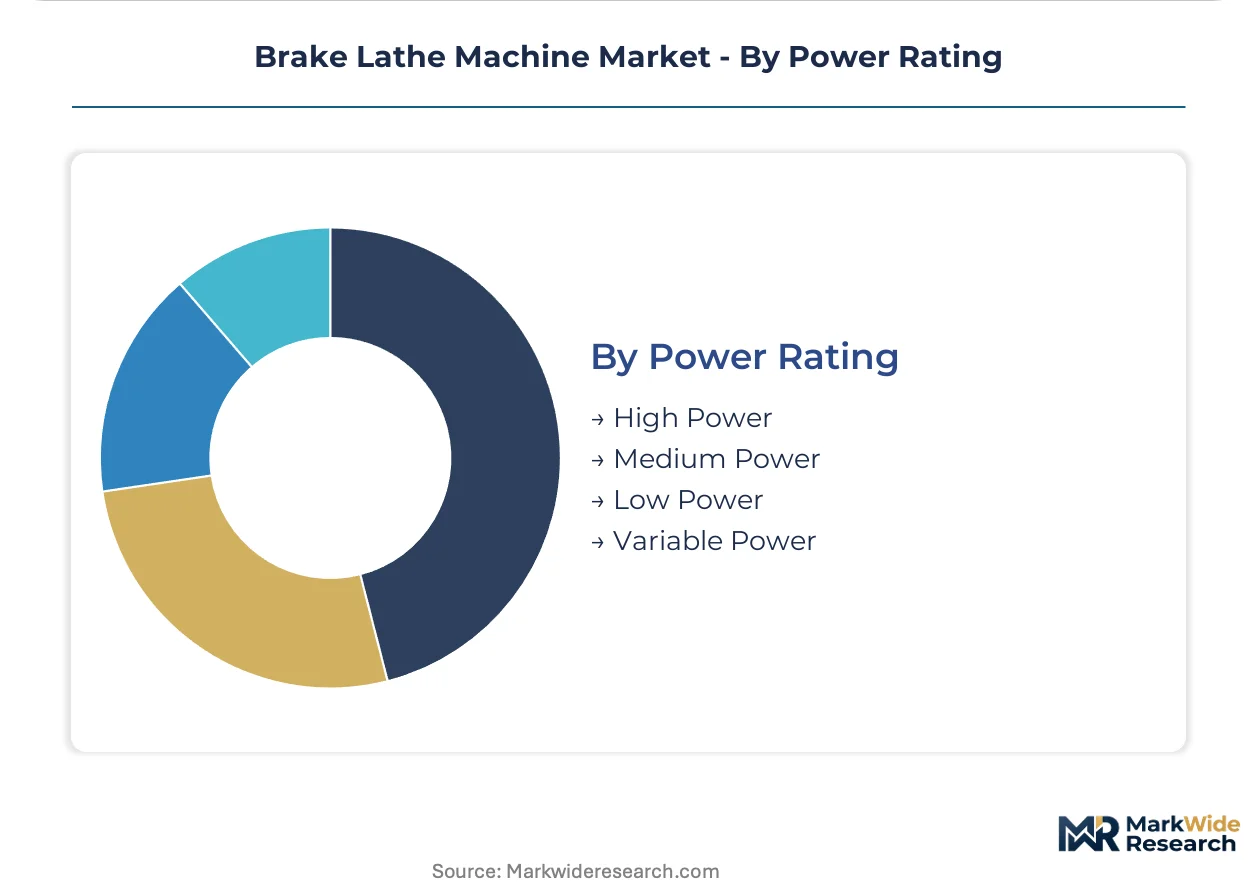
Power Rating:
Spindle torque specifications align with workpiece diameter and material removal rates.
- High Power:Heavy-duty motor configurations handle commercial vehicle brake drums exceeding 15-inch diameters. These systems dominate fleet maintenance depots serving Class 8 truck populations.
- Variable Power:Adjustable spindle drives accommodate mixed passenger and light commercial workloads. Urban repair shops specify these for flexibility across customer vehicle mixes.
- Medium Power:Fixed-output systems target standard passenger vehicle applications.
- Low Power:Reduced torque ratings suit compact car and motorcycle brake maintenance.
Installed base concentrates in Medium Power equipment. Steepest expansion trajectory belongs to Variable Power systems enabling operational flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten carbide cutting insert supply chains concentrate in Chinese rare earth processing facilities, while commercial vehicle fleet density drives aftermarket tooling procurement across three distinct industrial clusters.
United States
Class 8 truck fleet operators in Texas and California are expanding captive brake shops to maintain just-in-time logistics uptime guarantees. OSHA machine guarding standards are compelling facilities to upgrade from open-belt manual lathes to enclosed CNC systems with interlocked guards. Fleet maintenance depots in the Dallas-Fort Worth metroplex are deploying floor-mounted installations for continuous-duty drum resurfacing cycles.
Germany
Mittelstand workshop networks favor bench-mounted systems tailored to compact urban footprints where real estate constraints dictate equipment selection. The EU Machinery Directive and CE marking requirements govern market access, compelling emergency stop functionality and electrical safety certification. Industrial clusters in North Rhine-Westphalia anchor European demand through precision-focused aftermarket tooling procurement.
China
Dual-carbon policy frameworks from the MEE are accelerating adoption of closed-loop coolant systems integrated with CNC brake lathes. Rare earth processing concentration in Inner Mongolia and Jiangxi provinces creates input cost volatility for tungsten carbide cutting insert supply. Manufacturing plants in the Yangtze River Delta are expanding in-house resurfacing capacity to support just-in-time assembly lines for electric vehicle production.
India
Owner-operator trucking networks lack centralized maintenance infrastructure, creating whitespace for mobile brake lathe service units in underpenetrated fleet segments. The country's national industrial standards body is developing localized certification protocols for workshop equipment safety. Logistics corridors connecting Maharashtra and Gujarat are seeing emergent demand for portable field-service configurations serving remote equipment without fixed workshop infrastructure.
Brake Lathe Machine Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital measurement integration and predictive maintenance protocols. The vendor base stratifies across three tiers: precision-focused European specialists, North American fleet-service incumbents, and cost-optimized Asian fabricators. Competitive moves concentrate on technology licensing agreements and geographic distribution partnerships rather than direct capacity expansion.
Within the precision-integration tier, Hunter Engineering Company and Hofmann Megaplan exemplify contrasting regional approaches to equipment specification. AMMCO occupies a position bridging independent repair chain distribution with fleet-service automation requirements. These three anchors represent distinct strategic archetypes: alignment-integrated workflow systems, compact-footprint European bench engineering, and established North American aftermarket distribution networks.
| Leading Market Players |
|---|
| AMMCO |
| Hofmann Megaplan |
| Hunter Engineering Company |
| RELS |
| Accu-Turn |
| Hennessy Industries |
| Multipro Machines |
| Ammco 4000E |
| Pro-Cut International |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap fabricators across Germany and the United States anchor brake lathe manufacturing, translating generational capital discipline into stable pricing architectures and selective capacity expansion. These ownership structures resist margin-eroding volume plays, instead calibrating output to OEM service contract renewals and fleet operator upgrade cycles.
Pricing Analysis
Volume concentration in fleet services compresses margins on CNC systems while bench-mounted manual lathes retain pricing power in fragmented independent repair channels. Three-tier pricing structure across CNC automation, semi-automatic hybrids, and economy manual systems separates buyers by certification requirements and throughput guarantees. Pricing pressure stems from rare earth supply volatility elevating tungsten carbide insert costs passed through to mid-tier equipment. Fleet operators exhibit lowest price sensitivity due to uptime guarantee penalties, whereas India's owner-operator networks demand aggressive per-unit negotiation.
Supply Chain Analysis
Domestic-content mandates in China's dual-carbon framework and India's emerging industrial standards are reshaping sourcing patterns for spindle motors and control systems. Component manufacturing concentrates in China, Germany, and the United States, with rare earth processing anchored in Chinese Inner Mongolia and Jiangxi provinces. Supply chains draw from tungsten carbide inserts, brushless motor assemblies, and precision ball screws, resting on single-source vulnerability in rare earth refining. Distribution runs through OEM-authorized service networks and independent aftermarket distributors serving regional repair clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brake lathe supply is tightening around certified CNC spindle capacity, with OSHA compliance deadlines and fleet electrification timelines propping equipment pricing through the analysis window.
For Market Incumbents: Hedge against carbon-ceramic disc incompatibility by acquiring laser measurement specialists capable of sub-thousandth-inch runout compensation. Prioritize backward integration into tungsten carbide insert recycling to offset Chinese rare earth supply volatility. Defend installed base through predictive maintenance telemetry bundled with cutting tool subscription programs. For New Entrants and Emerging Players: Enter via mobile service units targeting India's unconsolidated owner-operator trucking corridors between Maharashtra and Gujarat. Exploit whitespace in portable configurations for field brake resurfacing without fixed workshop infrastructure. Lead with per-disc operational expenditure models that shift capital risk to liquidity-constrained fleet operators. For Investors and Strategic Acquirers: OSHA enforcement intensification against open-belt manual lathes is the leading indicator that compliance-driven replacement cycles will concentrate demand among certified CNC suppliers. Position for five-to-ten year viability around precision-integration specialists with API-connected telemetry platforms. Monitor EPA hazardous air pollutant enforcement in California and Texas as the signal for accelerated equipment pre-filtering investments.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Coolant Integration | MEE regulations in China mandate waste recovery systems that CNC lathe vendors must bundle to maintain market access. |
| Laser Measurement Acquisition | Automated disc thickness compensation addresses carbon-ceramic tolerance requirements in electric vehicle fleet specifications. |
| Mobile Service Unit Deployment | Portable configurations penetrate India's logistics corridors lacking centralized brake maintenance infrastructure. |
| Telemetry API Development | Shop management software connectivity resolves compliance documentation gaps plaguing independent repair chains. |
| Cutting Tool Subscription Model | Per-disc pricing shifts capital burden to distributors, matching Germany's Mittelstand liquidity constraints. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fleet maintenance directors, automotive repair shop owners, OEM procurement specialists, and aftermarket distribution managers validated demand patterns. OSHA enforcement databases, EPA hazardous air pollutant compliance records, EU Machinery Directive certification registries, and Chinese MEE environmental filings supplied regulatory trajectory inputs. Bottom-up equipment shipment analysis triangulated against top-down fleet operator capital expenditure surveys.
Granularity-level modeling distinguished CNC, semi-automatic, and manual product configurations across bench-mounted, floor-mounted, and portable installation types. End-user segmentation captured fleet services, independent repair shops, manufacturing plants, and DIY enthusiast demand pools with distinct pricing elasticities. Power rating tiers and regional regulatory clusters shaped volume and value outputs across the projection horizon. CAGRs derived from equipment replacement cycles, fleet electrification penetration curves, and compliance deadline clustering.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export restriction scenarios or accelerated carbon-ceramic brake adoption in performance electric vehicles. Forecasts reflect assumptions around OSHA enforcement intensity, EU Machinery Directive CE marking timelines, and Chinese dual-carbon policy implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Singapore Automotive Engine Oils Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Odometer Market