
 Garage Body Shop Equipment Market | 2026-2036
Garage Body Shop Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Garage Body Shop Equipment Market Analysis
Aftermarket service revenue is reconfiguring how equipment suppliers capture lifetime value from body shop operators. Snap-on Incorporated leverages its tool and equipment ecosystem to sustain recurring maintenance contracts across North American independent shops. Robert Bosch GmbH anchors its position through diagnostic-integrated repair systems that link measurement with frame straightening workflows. Vehicle Service Group competes by dominating the lift and alignment equipment segment with broad SKU coverage for multi-bay operations.
Garage body shop equipment encompasses fixed and mobile machinery used for collision repair, vehicle restoration, and custom refinishing, including paint booths with filtered airflow systems rated at 0.3 micron efficiency, hydraulic frame machines with 10-ton pulling capacity, and spot welders operating at 8,000-ampere output for OEM-specification joint reconstruction. Paint booths and frame machines command the largest installed base, though spot welders represent the fastest-growing category as aluminum-intensive vehicle architectures proliferate across collision repair bays. Independent shops and franchised outlets split the customer base unevenly, with insurance-directed repair networks concentrating procurement volume among fewer large-format operators.
OSHA ventilation standards, EPA NESHAP rules for hazardous air pollutants from surface coating, and EU F-Gas Regulation compliance for refrigerant handling during repair collectively shape equipment specification and facility upgrade cycles. California Air Resources Board mandates on waterborne basecoat conversion have created a template adopted by several other state environmental agencies. Stakeholders must monitor how OEM repair procedure subscriptions and certification requirements reshape equipment compatibility standards between vehicle generations.
Market Dynamics
Aluminum-intensive vehicle architectures are forcing collision repair shops to retool their welding and joining capabilities, compressing equipment replacement cycles and reshaping supplier relationships across the installed base.
Growth Catalysts
- Waterborne Paint Mandates:California Air Resources Board regulations on basecoat conversion have triggered paint booth upgrade waves across multiple state environmental agencies, pulling demand for filtered airflow systems.
- OEM Certification Requirements:Tightening repair procedure subscriptions from vehicle manufacturers are compelling independent shops to acquire diagnostic-integrated frame measurement systems to maintain insurance network access.
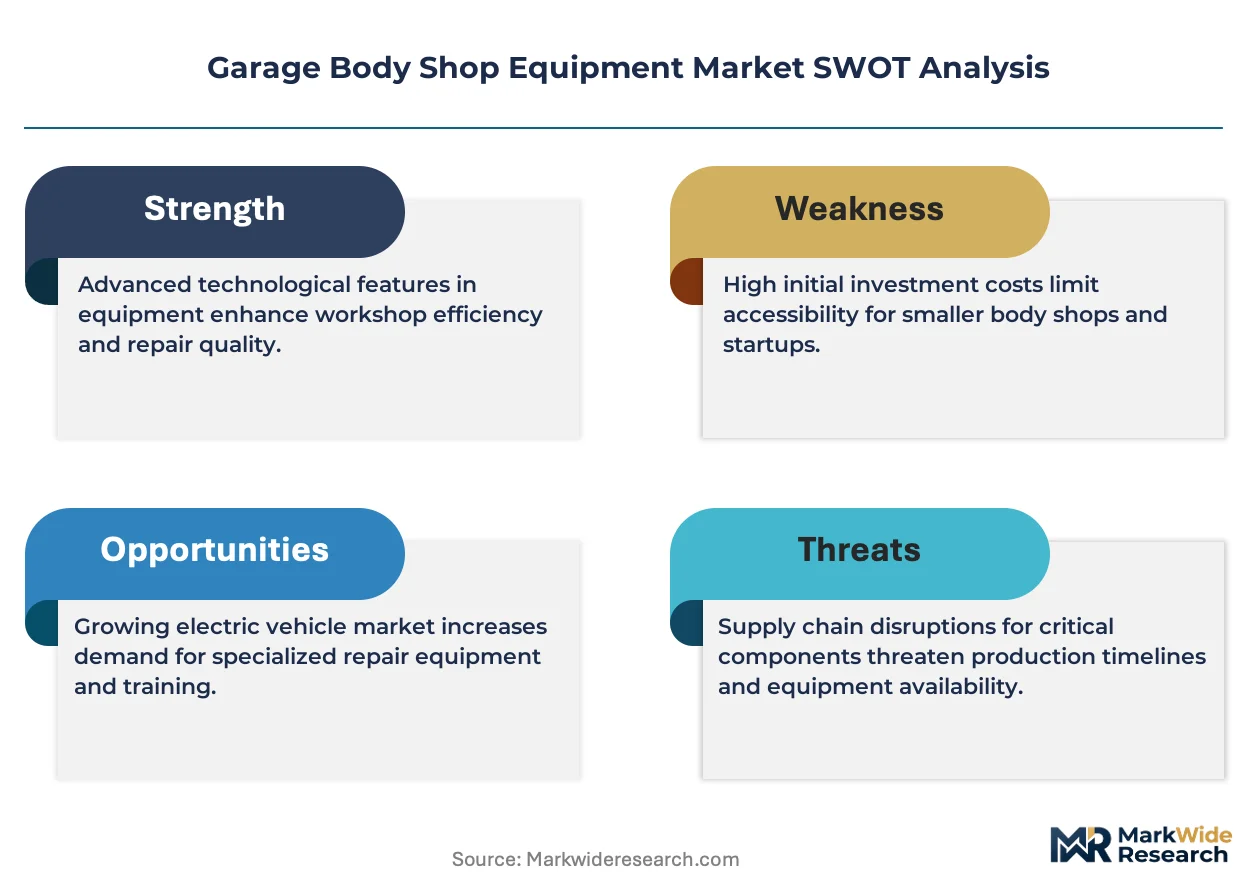
- Aluminum Proliferation:Spot welding equipment rated for 8,000-ampere output is displacing traditional steel repair methods as automakers expand aluminum body-in-white construction.
Market Restraints
- Capital Intensity:Hydraulic frame machines with 10-ton pulling capacity require substantial facility investments that constrain smaller independent operators from certification compliance.
- Supply Concentration:Filter media and ventilation component manufacturing clusters in Germany create vulnerability for North American paint booth assemblers facing extended lead times.
- Technical Limitation:Existing spot welders lack programmable heat control algorithms needed for multi-material joints in newer vehicle architectures, forcing premature obsolescence.
Strategic Opportunities
- Underpenetrated Geography:China's expanding collision repair network presents equipment deployment potential as the country's environmental ministry enforces stricter refinish emissions standards.
- Technology Convergence:Integration of 3D measurement systems with automated frame pulling is collapsing cycle times for structural repairs in high-throughput shops.
- Regulatory Tailwind:EU F-Gas Regulation compliance requirements for refrigerant handling during repair are creating demand for certified recovery equipment retrofits across member states.
Industry Challenges
- Skill Gap:Certified aluminum welding technicians remain scarce relative to equipment deployment, constraining utilization rates for high-amperage spot welders.
- Capex Timing:Synchronized OSHA ventilation standard updates with EPA NESHAP hazardous air pollutant rules compress facility upgrade windows and strain financing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garage Body Shop Equipment Market |
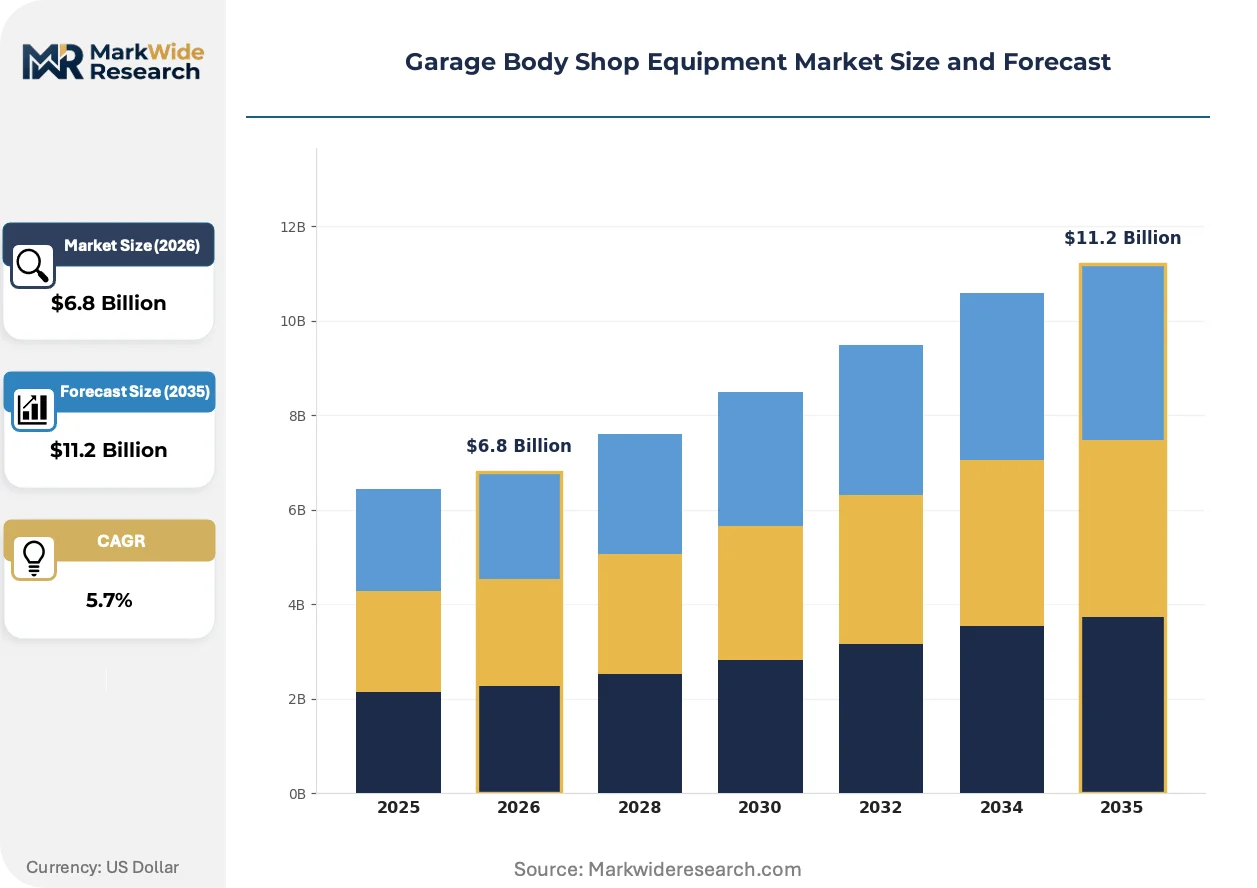
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Paint Booths, Frame Machines, Spot Welders, Sanding Machines Application: Collision Repair, Vehicle Restoration, Customization, Painting Customer Type: Independent Shops, Franchised Outlets, Insurance Shops, Specialty Shops Installation Type: Fixed Equipment, Mobile Units, Integrated Systems, Portable Solutions |
| Companies Covered | Snap-on Incorporated, Robert Bosch GmbH, Vehicle Service Group, Continental AG, MAHA Maschinenbau Haldenwang GmbH & Co. KG, Car-O-Liner, BendPak, Hunter Engineering Company, Gray Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garage Body Shop Equipment Market Emerging Trajectories
Digital measurement and automated pulling systems are compressing traditional repair workflows while environmental compliance mandates accelerate equipment refresh cycles across mature markets.
Infrared curing technology is collapsing bake cycle durations for waterborne basecoats, enabling throughput gains in space-constrained shops. High-volume collision repair networks in Germany and the United States are retrofitting existing booths with catalytic oxidizer add-ons rather than full replacement. The structural consequence is collapsing the revenue model for traditional convection-dominated paint booth suppliers.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are mandating recovery equipment upgrades in collision repair facilities handling HVAC repairs. Equipment distributors in France and Germany report bundling refrigerant handlers with ventilation system packages to simplify compliance. Frame machine manufacturers are responding by integrating refrigerant circuit isolation capabilities into their repair bay configurations.
Insurance-directed repair networks are consolidating procurement authority among fewer large-format operators with multi-bay footprints. Independent shops in California and Texas face exclusion from direct repair programs unless they maintain current OEM certification equipment suites. This concentration is most visible in metropolitan clusters where insurer-owned facilities command preferred vendor status for total-loss adjacency work.
Garage Body Shop Equipment Market Segmentation
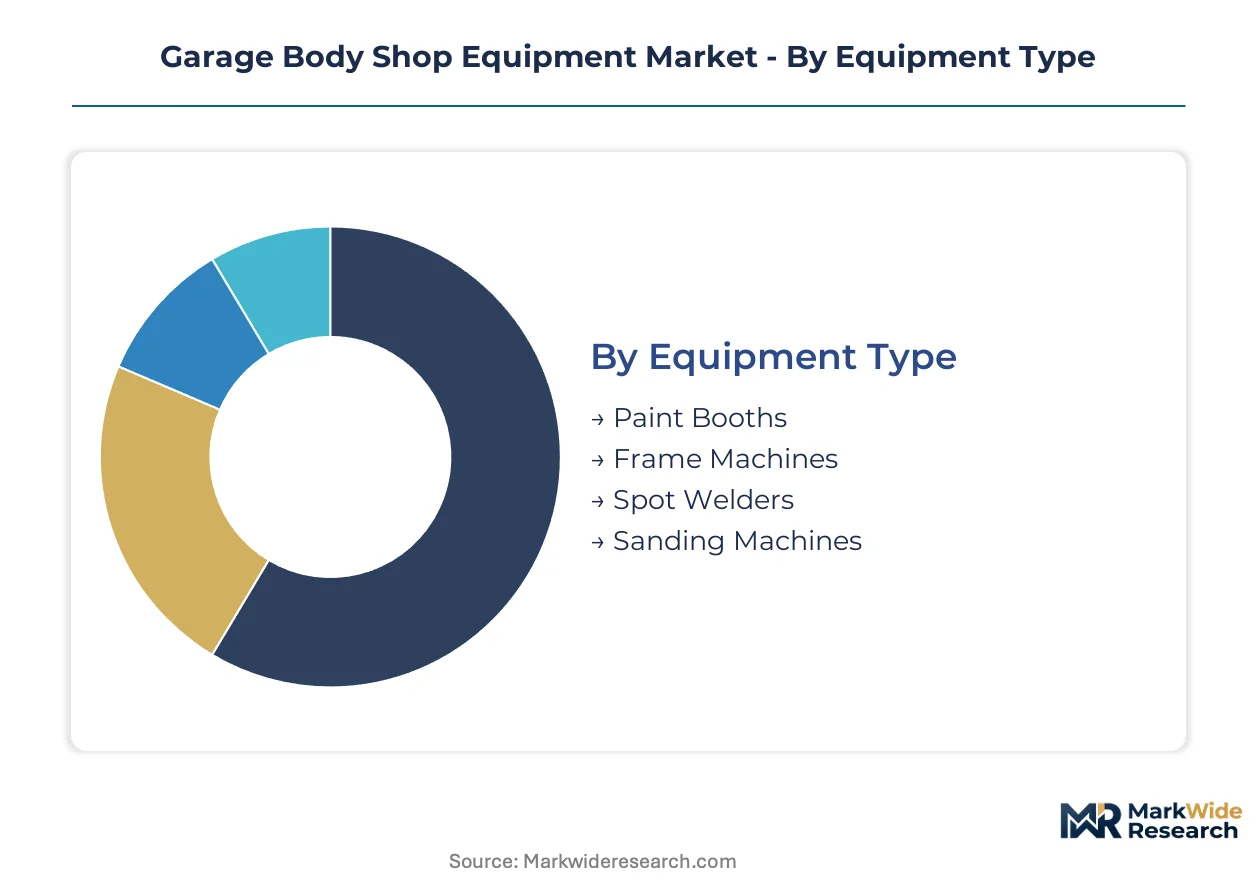
Equipment segmentation in the garage body shop market reveals how capital allocation priorities diverge between high-volume collision networks and specialized restoration operators. Understanding these splits enables suppliers to align product development with distinct procurement rhythms and certification requirements.
Equipment Type:
Paint booths and frame machines anchor the installed base, while aluminum repair capabilities are forcing rapid equipment refresh cycles.
- Paint Booths:Filtered airflow systems rated at 0.3 micron efficiency dominate facility upgrade budgets as California Air Resources Board waterborne basecoat mandates spread to additional state environmental agencies. Demand concentrates in Germany and the United States where EPA NESHAP hazardous air pollutant rules enforce ventilation compliance.
- Frame Machines:Hydraulic systems with 10-ton pulling capacity require substantial facility investments that constrain smaller independent operators from OEM certification compliance. Insurance-directed repair networks concentrate procurement volume among large-format operators with multi-bay footprints.
- Spot Welders:Equipment rated for 8,000-ampere output is displacing traditional steel repair methods as automakers expand aluminum body-in-white construction.
- Sanding Machines:Dust extraction-integrated units address OSHA ventilation standards for particulate exposure in high-throughput refinishing bays.
The dominant share belongs to paint booths, while spot welders are expanding most quickly as vehicle architectures shift toward aluminum-intensive designs.
Application:
Collision repair commands the largest revenue pool, though restoration and customization segments sustain premium pricing for specialized equipment configurations.
- Collision Repair:OEM-certified repair requirements tighten procedure subscriptions, compelling shops to acquire diagnostic-integrated frame measurement systems to maintain insurance network access.
- Vehicle Restoration:Custom fabrication demands sustain niche suppliers serving collector markets with period-correct equipment specifications.
- Customization:Aftermarket modification shops require flexible equipment configurations for non-standard vehicle geometries.
- Painting:Waterborne compliance mandates in the European Union and California accelerate booth upgrades for refinish operations.
Collision repair absorbs the majority of capital expenditure, while vehicle restoration generates the highest margin per equipment dollar deployed.
Customer Type:
Procurement authority concentrates among fewer large-format operators as insurance networks consolidate direct repair program participation.
- Independent Shops:Operators in California and Texas face exclusion from direct repair programs unless they maintain current OEM certification equipment suites.
- Franchised Outlets:Corporate procurement standardizes equipment specifications across multi-location networks.
- Insurance Shops:Insurer-owned facilities command preferred vendor status for total-loss adjacency work in metropolitan clusters.
- Specialty Shops:Aluminum-certified repair centers command premium labor rates that justify high-amperage welding equipment investments.
Independent shops retain the broadest geographic footprint, though insurance shops are capturing procurement volume fastest through network consolidation.
Installation Type:
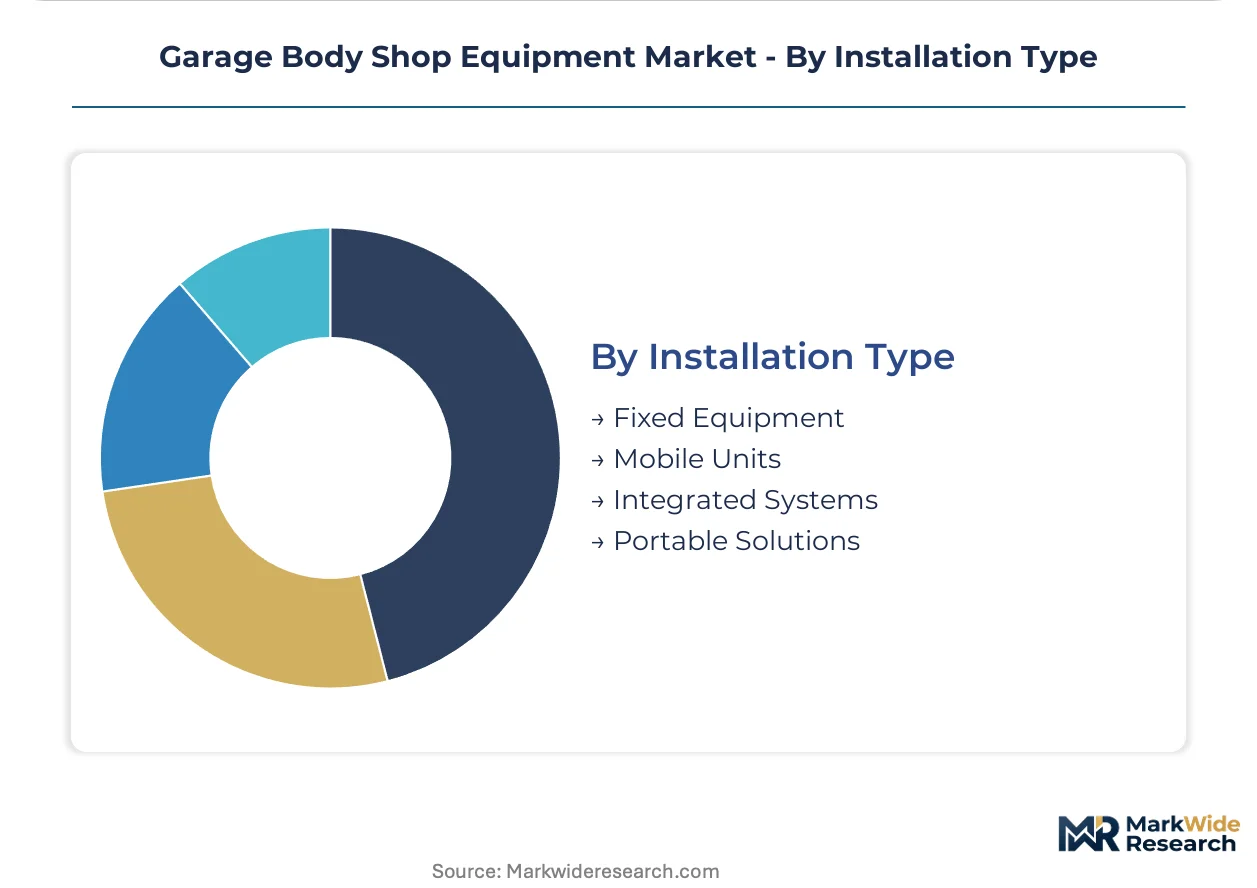
Fixed equipment dominates certified repair facilities, while mobile units serve underpenetrated rural markets and catastrophe response teams.
- Fixed Equipment:Permanent installations anchor OEM-certified facilities requiring calibrated measurement and pulling systems for structural repairs.
- Mobile Units:Portable frame pulling and paint systems serve remote locations and temporary repair capacity during weather events.
- Integrated Systems:3D measurement systems combined with automated frame pulling collapse cycle times in high-throughput shops.
- Portable Solutions:Compact welding and sanding equipment enables field repairs for fleet maintenance operations.
Fixed equipment holds the largest installed base, while integrated systems are climbing the fastest as throughput optimization becomes critical for network survival.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. German facilities prioritize precision measurement integration, while Chinese operators emphasize rapid throughput scaling. United States shops balance insurance network compliance with environmental retrofit investments.
United States
Collision repair networks concentrate procurement among multi-bay operators in Texas and California. OSHA ventilation standards and EPA NESHAP hazardous air pollutant rules compress facility upgrade windows. Metropolitan clusters in Dallas-Fort Worth and Los Angeles anchor equipment deployment for insurance-directed repair programs.
Germany
Filter media manufacturing clusters in Baden-Württemberg supply North American paint booth assemblers. EU F-Gas Regulation compliance requirements drive refrigerant recovery equipment retrofits. Industrial concentration around Stuttgart supports diagnostic-integrated frame measurement system development.
China
Environmental ministry enforcement of stricter refinish emissions standards accelerates paint booth upgrades. Yangtze River Delta collision repair networks expand aluminum-certified repair capacity. Shanghai and Jiangsu province facilities import European ventilation component designs for localized assembly.
Japan
OEM repair procedure subscriptions from domestic automakers tighten equipment compatibility requirements. METI industrial standards influence spot welder specifications for aluminum-intensive vehicle architectures. Nagoya-area suppliers integrate 3D measurement systems with automated pulling workflows.
United Kingdom
Independent shops in Greater London face exclusion from direct repair programs without current OEM certification suites. ECHA chemical safety regulations align with REACH compliance for surface coating operations. Midlands manufacturing heritage sustains niche equipment fabrication for restoration specialists.
Garage Body Shop Equipment Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Premium-tier suppliers integrate diagnostic-integrated repair systems while volume-oriented fabricators dominate lift and alignment equipment categories. Two strategic archetypes emerge: multi-product ecosystem builders and single-category specialists. Competitive moves center on technology licensing partnerships and geographic expansion through distributor networks.
Within the diagnostic-integrated systems tier, Robert Bosch GmbH and Snap-on Incorporated exemplify ecosystem approaches that sustain recurring revenue relationships. Vehicle Service Group occupies a position representing scale-driven specialization in lift and alignment equipment. Among German fabricators, MAHA Maschinenbau Haldenwang GmbH & Co. KG anchors precision measurement equipment supply for OEM-certified facilities.
| Leading Market Players |
|---|
| Snap-on Incorporated |
| Robert Bosch GmbH |
| Vehicle Service Group |
| Continental AG |
| MAHA Maschinenbau Haldenwang GmbH & Co. KG |
| Car-O-Liner |
| BendPak |
| Hunter Engineering Company |
| Gray Manufacturing Company |
| Others |
Supply Flow & Price Mechanics
Filter media manufacturing clusters in Baden-Württemberg and Lower Saxony concentrate upstream supply for paint booth ventilation systems, anchoring margin capture with German component suppliers while North American assemblers absorb logistics premiums and currency exposure on cross-Atlantic procurement.
Pricing Analysis
Long-term offtake contracts dominate procurement between large-format collision networks and frame machine OEMs, insulating buyers from spot volatility in steel and hydraulic component markets. Pricing stratifies across OEM-certified premium tiers, standard insurance-compliant configurations, and economy-grade equipment for independent rural operators. Cost compression in standard-tier spot welders intensifies as Chinese manufacturers expand export capacity. Franchise networks and insurer-owned facilities exhibit lowest price sensitivity due to bundled financing, while independent single-bay operators in secondary US markets face acute budget constraints.
Supply Chain Analysis
Extended payment terms from 90 to 120 days strain working capital for tier-two paint booth assemblers sourcing German filter media and Chinese control systems. Manufacturing concentrates in Germany, China, and the United States for structural repair equipment, with Italy and Japan supplying specialized measurement and welding components. Aluminum alloy feedstock and high-efficiency filtration media constitute critical input dependencies. Single-source vulnerability runs through Baden-Württemberg for HEPA-rated filter elements. Distribution runs through authorized dealer networks with regional service obligations, though direct OEM relationships are consolidating among multi-location operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified aluminum welding technicians remain scarce relative to equipment deployment rates, constraining utilization and creating asymmetric returns for stakeholders who control training pipelines or captive technical labor pools.
For Market Incumbents: Insulate recurring revenue streams by embedding diagnostic software subscriptions into frame measurement systems, creating switching costs against emerging entrants offering discounted hardware-only packages. Deepen backward integration into filter media production through partnerships with German manufacturing clusters, reducing exposure to extended lead times that threaten OEM certification compliance timelines. For New Entrants and Emerging Players: Pursue aluminum repair equipment retrofit packages targeting independent shops in Texas and Florida facing exclusion from insurance direct repair programs. China's Yangtze River Delta collision networks present the most penetrable geography as environmental ministry enforcement accelerates paint booth replacement cycles. A certified technician training bundled with equipment financing addresses the skill gap barrier that constrains incumbent utilization rates. For Investors and Strategic Acquirers: Capital is best deployed toward diagnostic-integrated equipment platforms with recurring software revenue components rather than pure hardware fabricators exposed to commodity input volatility. The long-term viability window favors suppliers with captive technical certification programs and multi-product ecosystem coverage. Monitor California Air Resources Board rulemaking expansion to additional state agencies as the inflection signal for paint booth replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Program Development | Captures scarce aluminum welding labor pools before competitors lock training pipelines. |
| Filter Media Backward Integration | Reduces lead time exposure from German manufacturing clusters for North American assemblers. |
| Diagnostic Software Subscription Bundling | Creates switching costs against hardware-only entrants in insurance-compliant repair networks. |
| China Distribution Network Expansion | Positions for environmental ministry enforcement of stricter refinish emissions standards. |
| Refrigerant Recovery Equipment Retrofit Packaging | Captures EU F-Gas Regulation compliance spending across member state collision facilities. |
Methodological Framework
Desk research of equipment manufacturer technical specifications, EPA and OSHA regulatory filings, and EU F-Gas Regulation implementation guidance preceded structured interviews with collision repair facility operators, OEM certification program managers, and insurance network procurement directors. Primary fieldwork with paint booth assemblers and frame machine distributors in Germany, the United States, and China validated secondary trade flow data and capacity announcements. Bottom-up equipment shipment tracking triangulated against top-down collision repair market sizing from vehicle registration and insurance claim databases.
Assumptions held fixed include prevailing California Air Resources Board waterborne basecoat mandates and EU F-Gas phase-down schedules, while aluminum vehicle architecture penetration rates and insurance network consolidation trajectories were stress-tested across scenarios. Segmentation modeling incorporated equipment type, customer archetype, installation configuration, and regional regulatory cluster dimensions. CAGRs were derived from equipment replacement cycle analysis and certification-driven upgrade propensity scoring, with aluminum-intensive vehicle production forecasts and environmental compliance deadline calendars serving as industry-specific demand inputs.
Macroeconomic conditions sit as an overlay; deviation in collision repair claim frequency, automotive production volumes, or capital equipment financing availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM certification requirement diffusion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Singapore Automotive Engine Oils Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Automotive Steering System Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Drum Brake Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market