
 Global Plastics for Passenger Cars Market | 2026-2036
Global Plastics for Passenger Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastics for Passenger Cars Market Outlook
Software-defined vehicle feature licensing is consolidating what automakers procure as recurring plastic-intensive modules rather than one-time hardware. BASF SE leverages its polyurethane formulations to anchor cockpit and seating contracts with European OEMs. SABIC sustains dominance in engineered thermoplastics for electric vehicle battery housings through its specialty compounds portfolio. Covestro AG competes aggressively on polycarbonate glazing and transparent polymer solutions that replace conventional glass.
Plastics for passenger cars encompass engineered polymer compounds formulated to achieve specific mechanical, thermal, and aesthetic properties for automotive integration, typically requiring melt flow indices between 5-50 g/10min and heat deflection temperatures exceeding 100°C for under-hood deployment. These materials reduce vehicle mass, improve fuel efficiency, and enable complex geometries unattainable with metals or glass. Polypropylene dominates interior component volumes due to its cost position and recyclability, while polycarbonate captures premium margin pools in exterior lighting and glazing applications. Polyurethane maintains structural importance in seating, insulation, and bumper systems where energy absorption specifications are critical.
The US EPA and NHTSA enforce corporate average fuel economy standards that directly incentivize polymer substitution for heavier materials, while the EU REACH regulation and F-Gas Framework restrict specific plasticizers and blowing agents used in automotive foam production. China's MIIT and GB standards mandate recyclability thresholds that reshape material selection for vehicles sold in that market. Stakeholders must monitor how evolving extended producer responsibility frameworks across Germany, Japan, and the United States alter polymer sourcing economics and supplier qualification requirements.
Market Dynamics
Electric vehicle platform redesigns are forcing polymer specification changes at unprecedented velocity, as battery thermal management requirements collide with crashworthiness mandates to reshape material selection criteria across OEM engineering departments.
Growth Catalysts
- EU Green Deal recyclability mandates:Automotive-grade plastics must achieve higher post-consumer content thresholds, accelerating investment in chemical recycling infrastructure for polypropylene and polycarbonate streams.
- Battery enclosure engineering thermoplastics:Electric vehicle OEMs specify flame-retardant polymer compounds for battery housings, creating dedicated demand for high-heat polycarbonate blends and polyamide formulations.
- German supplier ecosystem density:Stuttgart, Munich, and Wolfsburg anchor concentrated polymer compounding and injection molding capacity, reducing logistics costs for interior and exterior component sourcing.
Market Restraints
- Propylene feedstock volatility:Polypropylene pricing tracks naphtha and propylene monomer markets, compressing compounder margins during upstream petrochemical disruptions.
- REACH plasticizer restrictions:Phthalate-based additives face ECHA authorization hurdles, forcing reformulation of flexible PVC and polyurethane foam applications with higher-cost bio-based alternatives.
- Glass substitution limits in structural glazing:Polycarbonate optical clarity degradation and scratch resistance gaps constrain penetration beyond lighting lenses into windshield applications.
Strategic Opportunities
- India automotive polymer localization:PLI scheme incentives for domestic manufacturing attract compounding investments to serve Maruti Suzuki and Tata Motors assembly networks.
- Chemical recycling of mixed automotive plastics:Pyrolysis and depolymerization technologies enable recovery of engineering thermoplastics from shredder residue currently routed to energy recovery.
- Software-defined vehicle module recurring revenue:Subscription-enabled cockpit and lighting systems shift procurement from one-time hardware sales to multi-year polymer component service contracts.
Industry Challenges
- Automotive polymer recycling certification timelines:ISO 14021 and EPD verification for post-industrial and post-consumer content claims require 12-18 month qualification cycles, delaying contract awards.
- Multi-material bonding expertise gaps:Joining dissimilar polymers to metals and composites in lightweight assemblies demands adhesive formulation and process engineering capabilities scarce in tiered supply bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastics for Passenger Cars Market |
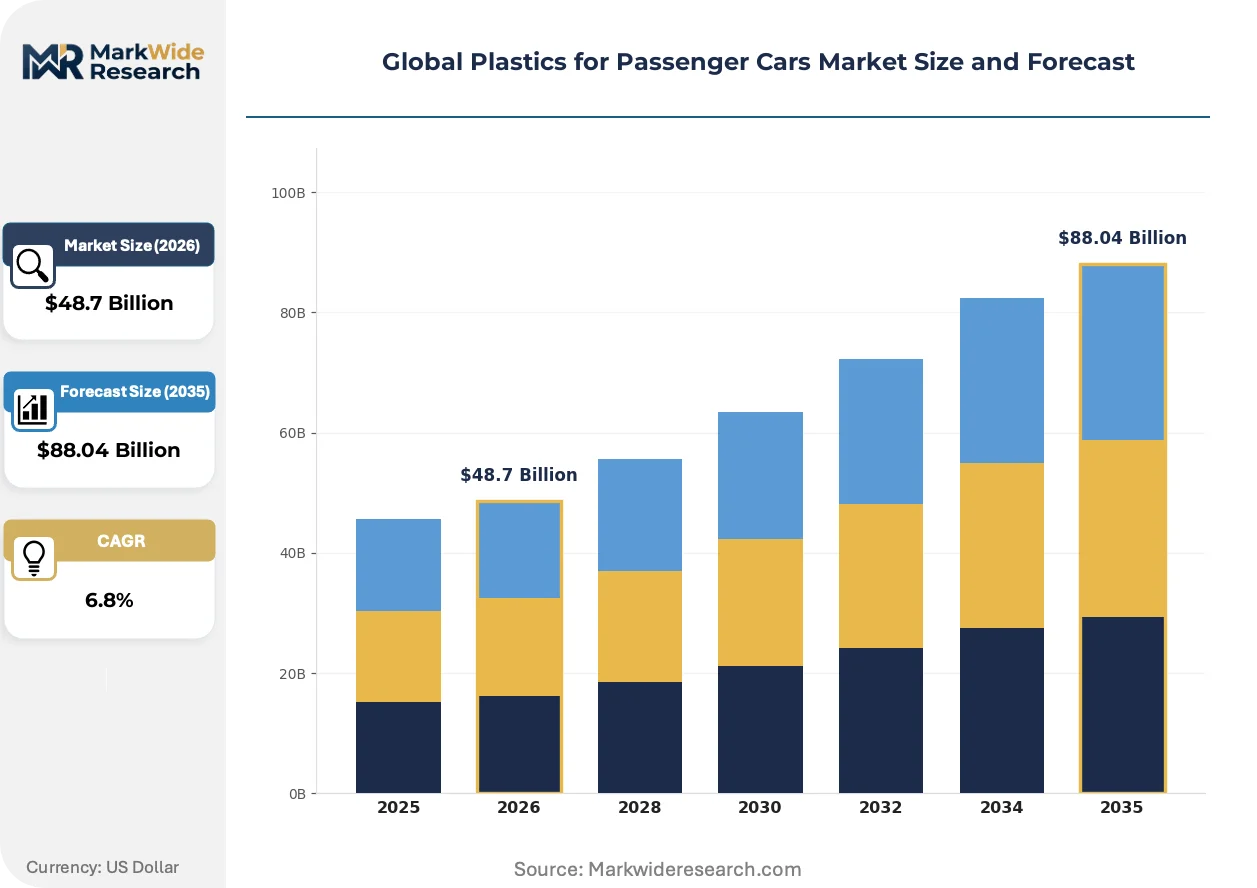
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyurethane, PVC, Polycarbonate Application: Interior Components, Exterior Components, Under-the-Hood Parts, Fuel System End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Blow Molding, Thermoforming, 3D Printing |
| Companies Covered | BASF SE, SABIC, LyondellBasell Industries Holdings BV, Covestro AG, DuPont, Evonik Industries AG, LG Chem, Borealis AG, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastics for Passenger Cars Market Strategic Shifts
Polymer architectures for passenger vehicles are converging around thermal management, optical performance, and circularity specifications that exceed legacy automotive material standards. Three distinct vectors dominate current development priorities.
Continuous fiber-reinforced thermoplastic composites are integrating into structural battery enclosures and floor pans, replacing stamped aluminum at equivalent strength-to-weight ratios. European OEMs specify these materials for electric vehicle platforms launching through 2027. The technology is integrating chassis engineering with polymer processing, collapsing traditional metal-stamping and plastic-injection supply chain boundaries into single-source structural module contracts.
REACH F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon blowing agents in polyurethane seating and insulation foams. German automotive suppliers reformulate with water-blown and hydrocarbon alternatives, accepting density and dimensional stability trade-offs. Under-hood acoustic foam applications face the steepest compliance cost increases, accelerating adoption of alternative fiber-based insulation in engine bay packaging.
Fleet operators and mobility service providers now specify total-cost-of-ownership material durability guarantees rather than upfront component pricing. Leasing companies and ride-hail platforms in China demand 300,000-kilometer interior wear warranties, shifting supplier selection toward compounded polypropylene with enhanced UV and abrasion resistance. Tier 1 interior integrators respond with material-as-a-service contracting models that bundle polymer supply, component manufacturing, and end-of-life takeback obligations.
Global Plastics for Passenger Cars Market Segmentation
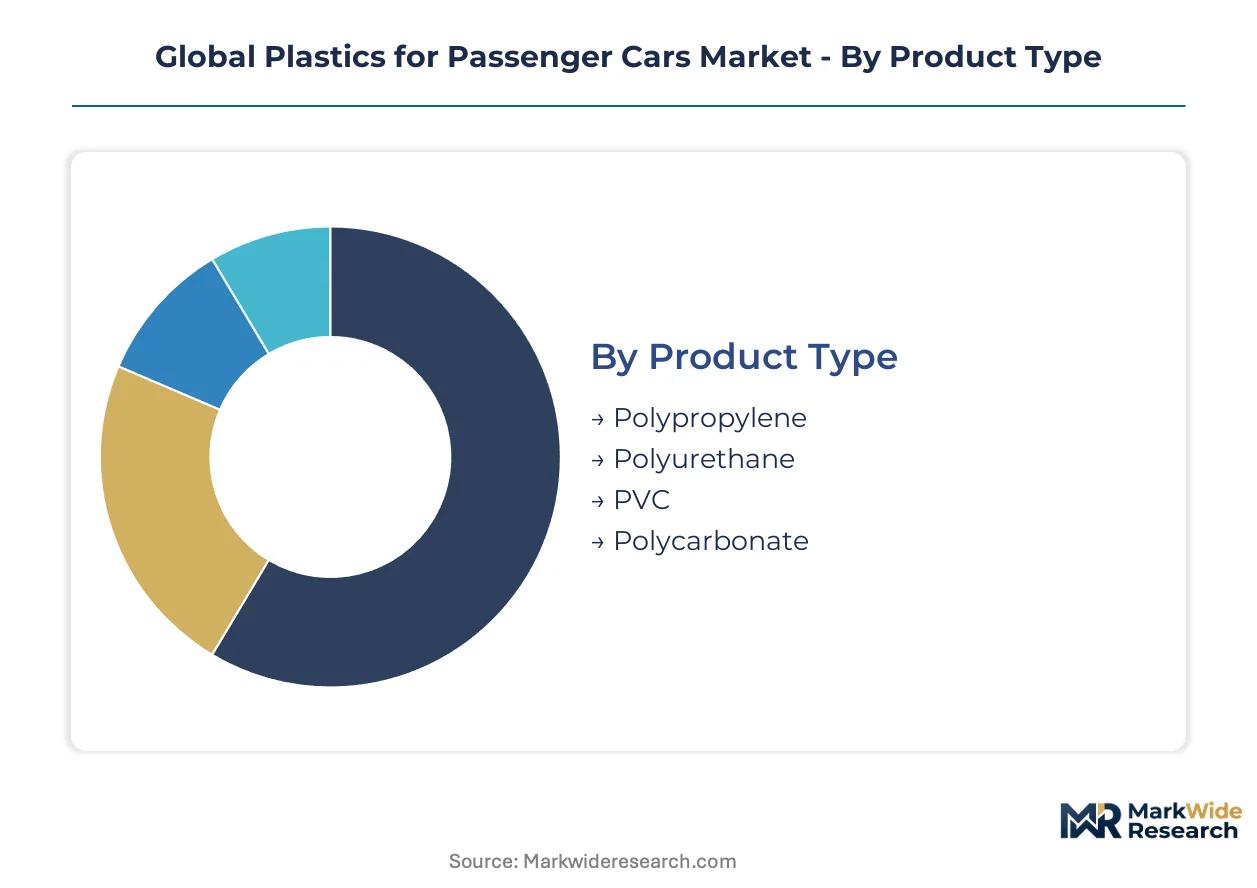
Material selection in automotive plastics follows divergent capital requirements across polymer families and processing technologies. Understanding where investment concentrates reveals which segments command supplier priority and pricing leverage.
Product Type:
Capital deployment varies dramatically across polymer families, with polypropylene and polycarbonate requiring the heaviest upfront commitments in compounding infrastructure and specialty formulation labs.
- Polypropylene:Semi-crystalline thermoplastic with melt flow indices of 10-50 g/10min dominates interior panels and bumper substrates. German OEMs specify high-impact copolymers for instrument panels, driving compounding capacity concentration around Stuttgart and Wolfsburg supplier parks. REACH recyclability mandates favor polypropylene's established mechanical recycling streams over competing polymers.
- Polycarbonate:Amorphous engineering thermoplastic delivers optical clarity and heat deflection temperatures exceeding 130°C for lighting lenses and glazing applications. Battery enclosure specifications from electric vehicle platforms in China and Germany absorb growing volumes of flame-retardant grades. Covestro and SABIC anchor supply through integrated monomer-to-compound production networks.
- Polyurethane:Reaction-injection systems for seating foam and structural bumper cores require dedicated blending equipment and isocyanate handling infrastructure. Water-blown formulations are displacing F-Gas restricted blowing agents under EU regulation.
- PVC:Plasticized grades for wire insulation and interior skin layers face ECHA authorization pressure on phthalate additives, forcing reformulation investments.
Most installed capacity flows through polypropylene. Expansion is steepest in polycarbonate.
Application:
Component location determines thermal and mechanical specifications, with under-hood and battery-adjacent applications imposing the most severe material performance thresholds.
- Interior Components:Dashboard assemblies, door panels, and seating substrates prioritize low VOC emissions and tactile surface quality. Polypropylene compounds with 20-40% talc or glass fiber reinforcement capture the majority of instrument panel structural applications. Chinese fleet operators now demand 300,000-kilometer wear warranties, forcing material-as-a-service contracting models.
- Under-the-Hood Parts:Engine covers, air intake manifolds, and cooling module housings require continuous service temperatures above 120°C and resistance to automotive fluids. Polyamide and polyphenylene sulfide compounds displace metals in charge air cooler housings. Thermal management integration with electric vehicle battery systems extends polymer specifications into previously metal-exclusive zones.
- Exterior Components:Bumpers, fenders, and body panels balance aesthetic Class A surface requirements with pedestrian impact energy absorption. Paintable thermoplastic olefin formulations dominate bumper fascia production.
- Fuel System:Tank modules and fuel lines demand permeation resistance to hydrocarbon vapors, with multi-layer blow-molded constructions meeting EPA evaporative emission standards.
Interior applications absorb the highest polymer volumes. Under-the-hood specifications are climbing fastest.
End User:
Procurement authority concentrates differently across the value chain, with OEM direct sourcing expanding for critical battery and cockpit modules while commodity interior parts flow through tiered structures.
- OEMs:Volkswagen, BMW, and Mercedes-Benz maintain direct polymer compounding relationships for proprietary color and performance specifications. Battery enclosure engineering thermoplastics increasingly bypass tiered suppliers for OEM-direct material qualification.
- Tier-1 Suppliers:Faurecia, Lear, and Magna negotiate multi-year polymer supply agreements covering seating, interior, and lighting module production. Software-defined vehicle feature licensing is shifting some procurement toward recurring service contracts rather than discrete hardware purchases.
- Aftermarket Providers:Collision repair and refurbishment channels source color-matched polypropylene and polycarbonate through distributor networks rather than direct mill relationships.
- Vehicle Assemblers:Contract manufacturers and emerging electric vehicle entrants rely on tier-1 integrators for polymer specification and supply chain management.
Tier-1 suppliers handle the majority of polymer volume. OEM direct sourcing is expanding most quickly.
Technology:
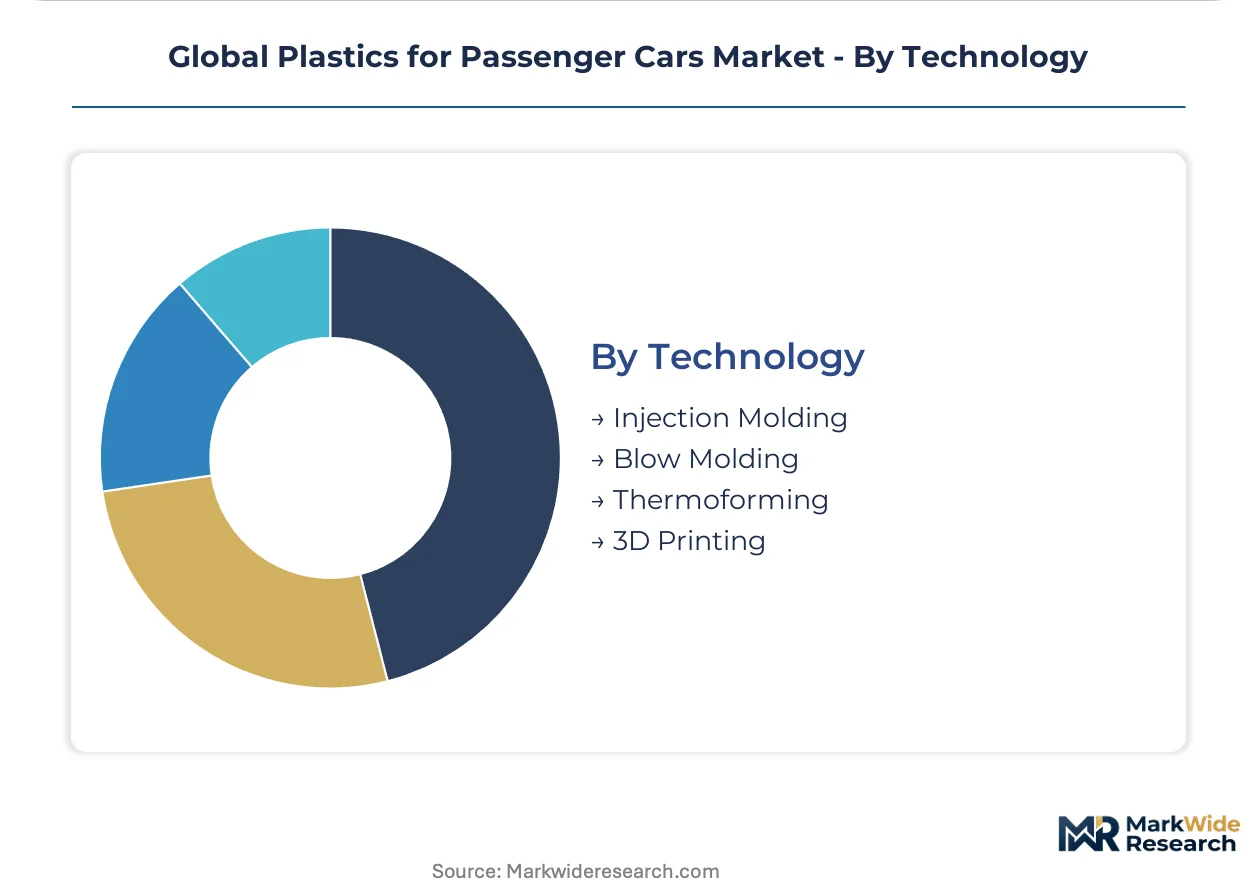
Processing method selection locks in equipment amortization schedules and labor intensity profiles, with injection molding dominating high-volume production while additive methods capture prototyping and service part niches.
- Injection Molding:Clamping forces from 500 to 4,000 tons process polypropylene and polycarbonate into complex interior and exterior components. Multi-material machines with rotary platens enable overmolding of soft-touch surfaces onto structural substrates. German automotive supplier parks concentrate the densest injection molding capacity globally.
- Blow Molding:Extrusion and injection blow processes form fuel tanks, air ducts, and fluid reservoirs from polyethylene and polyamide. Multi-layer coextrusion technology integrates EVOH barrier layers for fuel system permeation compliance.
- Thermoforming:Vacuum and pressure forming of ABS and polycarbonate sheet produces door panels, trunk liners, and exterior cladding with lower tooling costs than injection alternatives.
- 3D Printing:Fused filament fabrication and selective laser sintering of engineering thermoplastics serve prototyping, jigs, fixtures, and low-volume end-use parts for specialty vehicle applications.
Injection molding commands the greatest installed capital base. 3D printing is gaining share fastest in tooling and prototyping workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting compounding investments toward regions with harmonized recyclability standards and dense OEM assembly networks. Suppliers chase regulatory clarity as much as manufacturing scale.
Germany
BMW, Volkswagen, and Mercedes-Benz operate concentrated supplier ecosystems for interior and exterior polymer assemblies. The EU Green Deal and REACH compliance frameworks enforce stringent recyclability mandates for automotive-grade plastics. Stuttgart, Munich, and Wolfsburg anchor dense polymer compounding and injection molding capacity that reduces logistics costs for tier-1 integrators.
China
Electric vehicle platforms from BYD, NIO, and XPeng specify flame-retardant engineering thermoplastics for battery housings at unprecedented scale. MIIT and GB standards mandate recyclability thresholds that reshape material selection for domestic and export-bound vehicles. The Yangtze River Delta and Pearl River Delta concentrate the majority of polycarbonate and polyamide compounding capacity serving these OEMs.
United States
EPA and NHTSA corporate average fuel economy standards directly incentivize polymer substitution for heavier materials in Detroit Three vehicle programs. Battery enclosure engineering from Rivian, Lucid, and GM's Ultium platform absorbs growing volumes of high-heat polycarbonate blends. The Midwest manufacturing corridor spanning Michigan, Ohio, and Indiana hosts legacy injection molding infrastructure now retooling for EV architectures.
India
Maruti Suzuki and Tata Motors assembly networks drive polymer demand for compact vehicle interiors and structural components. The PLI scheme for domestic manufacturing attracts compounding investments from multinational suppliers seeking tariff-advantaged positions. Gujarat and Maharashtra host emerging supplier parks where tier-1 integrators localize polypropylene supply chains.
Japan
Toyota, Honda, and Nissan maintain exacting material specifications for hybrid and electric vehicle platforms that prioritize thermal management performance. METI circular economy guidelines and JIS standards govern post-industrial plastic recovery from automotive shredder residue. The Nagoya-Toyota industrial corridor sustains specialized compounding relationships between OEMs and domestic chemical conglomerates.
Global Plastics for Passenger Cars Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates dominating engineered thermoplastics while regional compounders capture commoditized polypropylene volumes. The market structure concentrates around three to five European and Asian chemical majors possessing monomer-to-compound integration. Strategic archetypes include integrated petrochemical giants with captive resin supply, independent compounders serving tier-1 automotive suppliers, and regional specialists focused on recycled-content formulations. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure qualification positions on electric vehicle platforms.
Among European-based integrated suppliers, BASF SE, SABIC, and Covestro AG exemplify distinct positioning archetypes within the engineered polymer tier. BASF SE represents the polyurethane-centric cockpit and seating specialist with deep OEM direct relationships. SABIC occupies a position as the dominant engineered thermoplastics supplier for electric vehicle battery housing applications through its specialty compounds portfolio. Covestro AG anchors the polycarbonate glazing and transparent polymer segment where optical-grade materials displace conventional glass in lighting and potential structural applications.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| LyondellBasell Industries Holdings BV |
| Covestro AG |
| DuPont |
| Evonik Industries AG |
| LG Chem |
| Borealis AG |
| Celanese Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal recyclability mandates gate both qualified supply and premium-tier pricing access, forcing compounders to invest in chemical recycling infrastructure before securing contracts with BMW, Volkswagen, and Mercedes-Benz. OEMs now pay material-as-a-service premiums for verified post-consumer content while excluding uncertified suppliers from battery enclosure and cockpit module sourcing.
Pricing Analysis
Capacity additions in China are reshaping price floors for flame-retardant polycarbonate blends used in electric vehicle battery housings. Three-tier pricing structure across premium, standard, and economy levels separates OEM-direct compound formulations from tier-1 distributed grades and spot-market commodity polypropylene. Cost compression in standard-grade interior polypropylene is intensifying because of naphtha feedstock volatility. Fleet operators and leasing companies show highest price sensitivity for upfront component costs, while OEM platform engineers prioritize thermal performance over unit economics.
Supply Chain Analysis
Freight cost differentials between German supplier parks and Asian compounding hubs influence procurement decisions for European OEMs. Supply concentrates in Germany, China, and the United States, with Stuttgart, Munich, and Wolfsburg anchoring dense injection molding capacity. Raw material flows draw from Saudi Arabian propylene, Korean polycarbonate monomer, and Belgian polyurethane isocyanate streams. Single-source vulnerability in battery-grade flame-retardant additives creates qualification bottlenecks. Distribution runs through tier-1 integrator networks rather than direct mill relationships for commodity interior components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
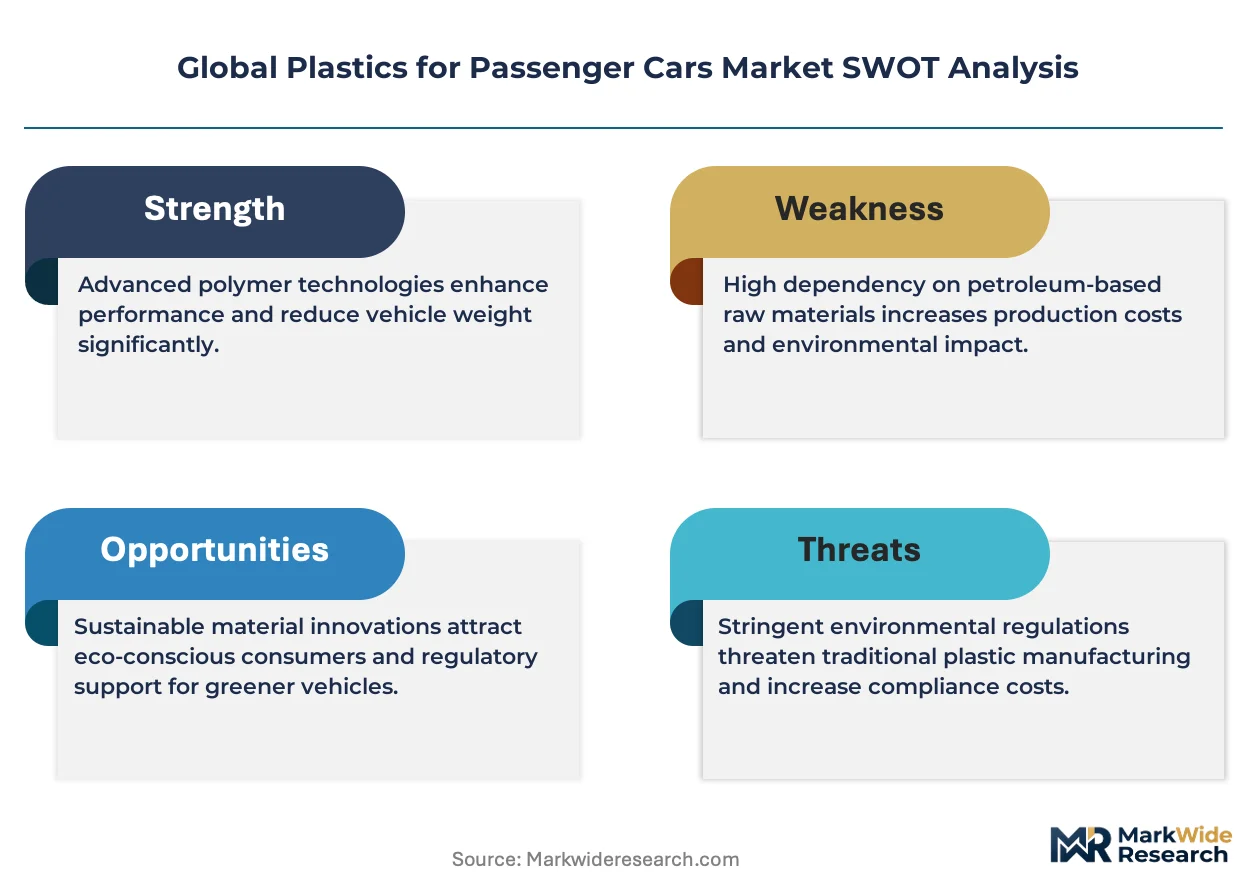
This market functions as a geographic-arbitrage play where India's PLI scheme incentives compounder margins against REACH compliance costs in Germany.
For Market Incumbents: Cement qualification positions on electric vehicle platforms by securing battery enclosure engineering thermoplastics contracts with Chinese OEMs. Deepen backward integration into chemical recycling infrastructure to meet EU Green Deal post-consumer content thresholds. Defend against emerging recycled-content specialists by locking OEMs into multi-year material-as-a-service agreements.
For New Entrants and Emerging Players: Chemical recycling technology-first wedge opens white-space in mixed automotive plastics recovery from German and Japanese shredder residue. Target India automotive polymer localization where Maruti Suzuki and Tata Motors assembly networks lack qualified domestic compounders. Pursue joint-venture structures with established tier-1 integrators to bypass 12-18 month OEM qualification timelines.
For Investors and Strategic Acquirers: Roll-up economics work for regional recycled-content compounders because ISO 14021 certification scarcity creates acquisition premiums. Five-to-ten year viability hinges on chemical recycling technology maturation rather than mechanical reprocessing alone. Watch for battery thermal management specification changes as inflection indicator for polycarbonate blend demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Investment | Pyrolysis capacity enables EU Green Deal compliance for BASF and SABIC contract retention. |
| Battery Enclosure Material Qualification | Flame-retardant polycarbonate blends secure OEM-direct sourcing bypassing tier-1 integrators. |
| India Manufacturing Localization | PLI scheme tariff advantages attract compounding investments to serve Maruti Suzuki networks. |
| Material-as-a-Service Contracting | Bundled polymer supply and end-of-life takeback align with Chinese fleet operator durability guarantees. |
| Water-Blown Polyurethane Reformulation | REACH F-Gas Regulation compliance protects seating foam contracts with German automotive suppliers. |
Study Parameters
Direct dialogue with OEM platform engineers, tier-1 supplier procurement leads, chemical compounding plant managers, and automotive shredder operators grounded qualitative findings. Secondary validation drew from SEC 10-K filings of integrated petrochemical majors, EU ECHA authorization databases, China MIIT vehicle production statistics, and German KBA registration data. Bottom-up polymer consumption estimates triangulated against top-down automotive production forecasts.
Installed base and replacement demand outputs across the analysis window reflect segmented modeling by vehicle propulsion architecture, content per vehicle by component location, and regional production cluster. CAGRs derived from regression against historical polymer intensity trends and electric vehicle platform penetration curves. Key inputs included battery thermal management specification evolution and REACH plasticizer restriction implementation timelines.
The model holds under stable regulatory enforcement; deviation in EU Green Deal recyclability threshold acceleration or China dual carbon goal advancement would shift compounder investment priorities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Rammer Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Africa Passenger Vehicles Lubricants Market
Automotive Parts
Auxiliary Oil Cooler Market