
 Passenger Tire Market | 2026-2036
Passenger Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Tire Market Intelligence
A shift from single-source to multi-source procurement by automotive OEMs is recalibrating the competitive landscape for tire manufacturers, a strategy aimed at mitigating supply chain risks. Michelin leverages its strong brand and OEM relationships to secure premium fitments. Goodyear competes on its extensive aftermarket distribution network and global manufacturing footprint. Continental differentiates through its integration of tire technology with its broader automotive systems expertise.
Passenger tires are composite pneumatic structures, typically made from natural and synthetic rubber, carbon black, and silica, reinforced with fabric and steel belts. Their primary function is to provide traction, support vehicle load, and absorb road shocks. The All-Season tire segment constitutes the largest volume category, serving a broad base of drivers. In contrast, the OEM channel provides a crucial entry point for new models, while the Aftermarket segment dominates overall sales volume.
Regulatory frameworks establish critical performance and safety benchmarks for market participants. In the United States, the NHTSA enforces standards for treadwear and traction, while EU tire labeling mandates disclosures on fuel efficiency and wet grip. China's GB standards govern market access for all tires sold domestically. The key decision for manufacturers now centers on balancing raw material volatility with investments in sustainable materials and circular economy models.
Market Dynamics
The central tension in the passenger tire market is the conflict between volatile raw material costs, primarily for natural and synthetic rubber, and the immense capital investment required to pivot production toward sustainable materials and EV-specific designs.
Growth Catalysts
- EV-Specific Tires:The transition to electric vehicles necessitates tires with low rolling resistance to maximize battery range and reinforced structures to handle higher torque and vehicle weight, creating a premium replacement and OEM segment.
- Regulatory Mandates:EU tire labeling rules, which grade tires on fuel efficiency, wet grip, and noise, directly influence consumer purchasing decisions and compel manufacturers to improve specific performance metrics to remain competitive.
- Replacement Cycles in China:China's enormous and maturing domestic vehicle parc drives a massive and consistent demand for replacement tires, forming the largest single-country volume market globally.
Market Restraints
- Raw Material Volatility:Price fluctuations in natural rubber, petroleum-based synthetic rubber, and carbon black create significant margin pressure and complicate long-term financial planning for tire manufacturers.
- Geographic Supply Concentration:The heavy reliance on natural rubber sourced predominantly from a few countries in Southeast Asia exposes the entire supply chain to risks from climate events, disease, and regional political instability.
- Technical Trade-offs:Tire engineering involves inherent compromises; for example, improving rolling resistance for fuel efficiency can sometimes come at the expense of wet grip or tread life, a challenge for R&D teams.
Strategic Opportunities
- Sustainable Materials:Developing commercially viable tires using non-petroleum-based materials like guayule, dandelion rubber, and recycled plastics opens new product categories and appeals to environmentally conscious consumers and regulators.
- Embedded Sensor Technology:Integrating sensors into tires to create "smart tires" that provide real-time data on pressure, temperature, and wear creates new service-based revenue streams for fleet management and autonomous vehicles.
- Circular Economy Models:Building business models around advanced retreading for commercial fleets and chemical recycling of end-of-life tires into base components offers a path to reduce raw material dependency and meet sustainability goals.
Industry Challenges
- High Capital Expenditure:Re-tooling manufacturing plants to produce next-generation tires, such as those for EVs or with sustainable content, requires substantial upfront investment in new molds, mixers, and curing presses.
- OEM Homologation Process:Securing fitments on new vehicle models involves a long and resource-intensive homologation process with each automaker, creating high barriers to entry for new players in the OEM channel.
- Talent Scarcity:A shortage of material scientists and data analysts with expertise in polymer chemistry and predictive analytics hinders the pace of innovation in compound development and smart tire services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Tire Market |
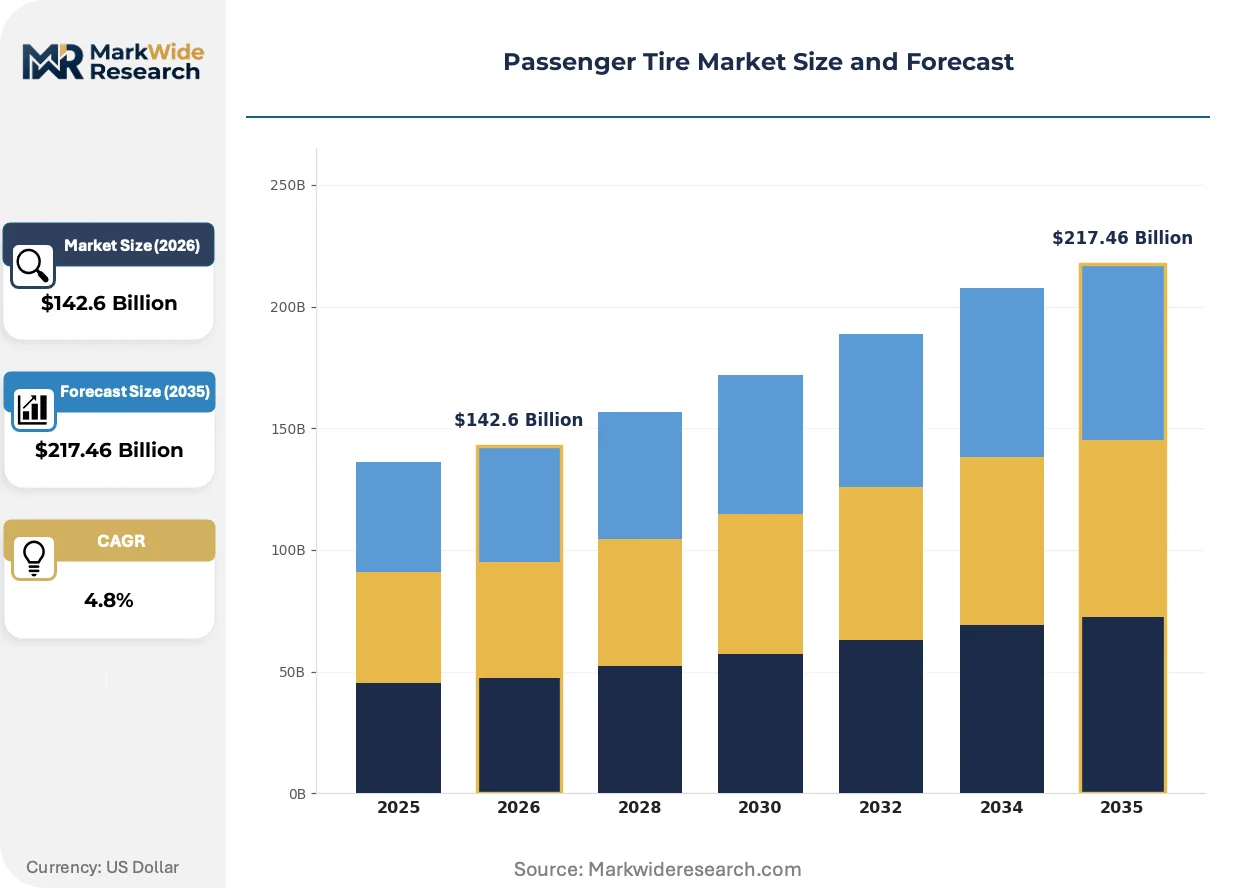
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $217.46 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Season, Summer, Winter, Performance End User: OEMs, Aftermarket Providers, Retail Drivers, Fleets Size: 16 Inch, 17 Inch, 18 Inch, 19 Inch Technology: Radial, Bias Ply, Tubeless, Runflat |
| Companies Covered | Bridgestone, Yokohama, Michelin, Falken, Toyo, Goodyear, Pirelli, BF Goodrich, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Tire Market Strategic Shifts & Innovations
Material science and data integration are the primary forces driving product evolution. The industry is moving from a focus on purely mechanical performance to creating intelligent, sustainable products that function as key components within a connected vehicle ecosystem.
Smart tire technology, which embeds sensors and RFID chips into the tire structure, provides real-time data on pressure, temperature, and tread wear. Premium EV owners and commercial fleet operators are the principal adopters of this innovation. This direct integration with vehicle telematics is automating predictive maintenance alerts and optimizing the entire tire lifecycle for fleet managers.
The European Union's upcoming Euro 7 standards will, for the first time, regulate non-exhaust particulate emissions from tires and brakes. This industrial consequence compels manufacturers to reformulate tread compounds to minimize abrasion and particle release. Winter and high-performance tire segments, which typically use softer compounds for grip, are most affected and must re-engineer products to meet these new environmental benchmarks.
A gradual shift toward tire-as-a-service (TaaS) models is underway, especially within commercial and fleet segments. This approach disrupts the traditional transactional sale in the aftermarket channel by bundling tires with ongoing monitoring and replacement services for a recurring fee. This demand-side evolution is most pronounced in North America and Europe, where large logistics firms use it to manage total cost of ownership.
Passenger Tire Market Segmentation
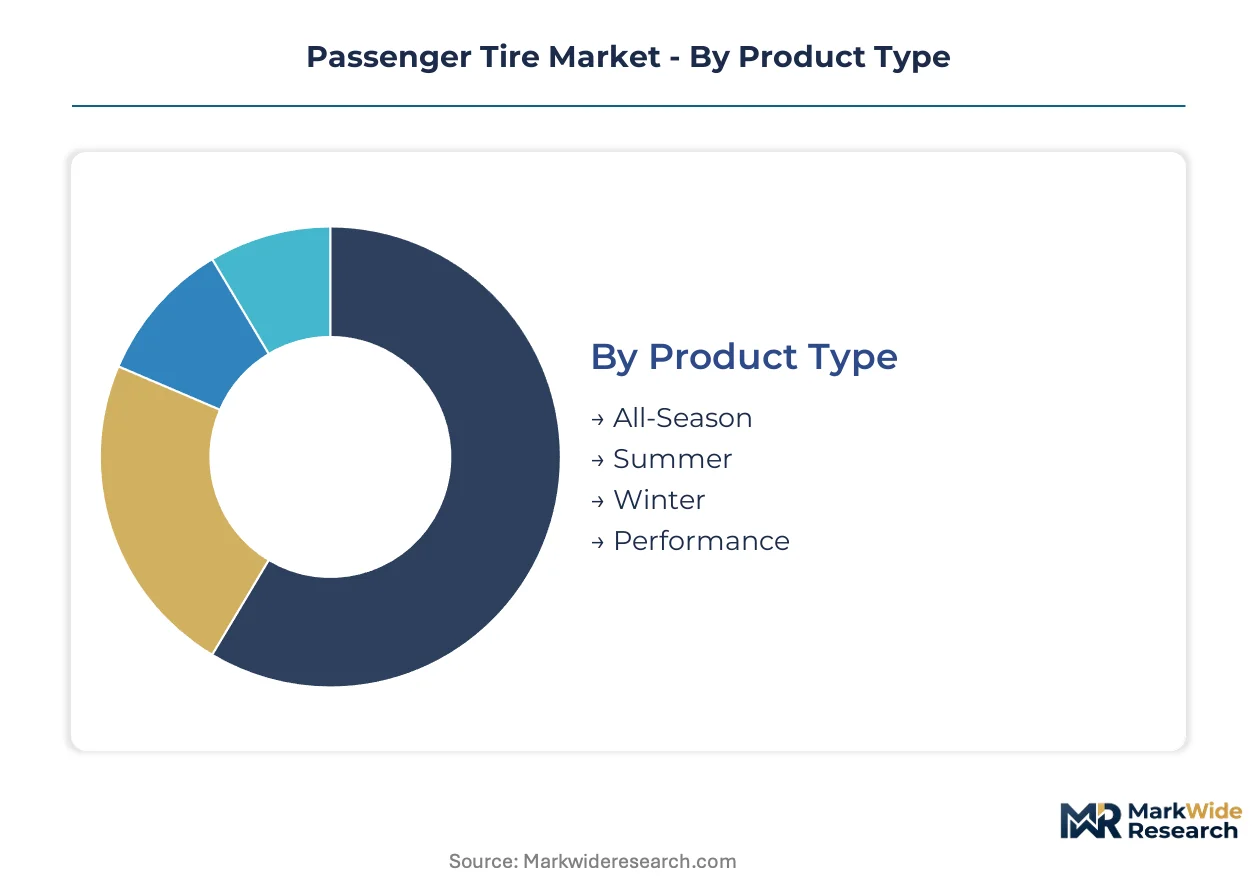
The passenger tire market is a complex ecosystem, and understanding its segmentation is crucial for manufacturers to align product development with specific consumer needs and regulatory demands. Each segment reflects distinct performance requirements, end-user preferences, and technological advancements. This detailed breakdown highlights the diverse landscape of tire offerings.
Product Type:
Buyer decisions for product type are primarily driven by anticipated weather conditions and desired vehicle performance characteristics.
- All-Season:These tires feature a balanced tread compound and design, offering reliable performance across a range of temperatures and light weather conditions. Demand for All-Season tires is concentrated among general consumer vehicles in temperate climates, driven by their versatility and convenience.
- Summer:These tires use softer rubber compounds for optimal grip and handling in warm, dry conditions, providing precise steering response for many passenger cars.
- Winter:Winter tires feature deeper tread patterns and specialized rubber compounds, maintaining flexibility and providing superior traction on snow and ice.
- Performance:Designed for high-speed stability and enhanced grip, these tires often incorporate specialized compounds and stiff sidewalls for responsive handling. The Performance segment sees demand from premium vehicle manufacturers and enthusiasts, particularly with the rise of high-torque electric vehicles requiring robust tire structures.
Volume sits with All-Season; growth tilts toward Performance.
End User:
Tire distribution and sales patterns are shaped significantly by the application channel, dictating procurement strategies and service requirements.
- OEMs:This segment involves direct supply of tires to vehicle manufacturers for installation on new vehicles at the factory, requiring rigorous homologation processes. The OEM channel is a critical entry point for new tire models and technologies, especially for EV-specific designs.
- Aftermarket Providers:This channel supplies replacement tires through a vast network of distributors, independent garages, and online retailers, serving the majority of vehicles already on the road. Demand through Aftermarket Providers is driven by routine replacement cycles and consumer choice, dominating overall sales volume.
- Retail Drivers:Individual consumers purchasing tires for their personal vehicles through various sales channels constitute this direct end-user segment.
- Fleets:Commercial vehicle operators manage tire procurement for their entire vehicle pools, prioritizing durability, fuel efficiency, and service agreements.
This category's sales are heavily concentrated in the Aftermarket segment, while the OEM channel dictates initial fitments.
Size:
The volume of tire sales in different size categories directly correlates with prevailing vehicle manufacturing trends and consumer preferences for vehicle types.
- 16 Inch:Smaller diameter tires are typically found on entry-level vehicles or older models, emphasizing ride comfort and cost-effectiveness.
- 17 Inch:Tires of this diameter are a common fitment for a broad range of compact and mid-size passenger vehicles, balancing ride comfort with handling characteristics. Demand for 17-inch tires remains substantial across global markets, driven by the enduring popularity of conventional sedans and smaller SUVs.
- 18 Inch:This size increasingly features on larger sedans, SUVs, and many new electric vehicle models, offering a balance of aesthetic appeal and improved performance. The 18-inch segment experiences strong growth, particularly as automakers standardize larger wheel options and EV adoption expands.
- 19 Inch:Larger diameter tires are characteristic of premium vehicles, sports cars, and high-performance EVs, prioritizing handling and visual impact.
The 17-inch and 18-inch segments collectively account for a significant share of passenger tire volume.
Technology:
The maturity of tire technologies influences their market penetration, performance benchmarks, and suitability for modern vehicle requirements.
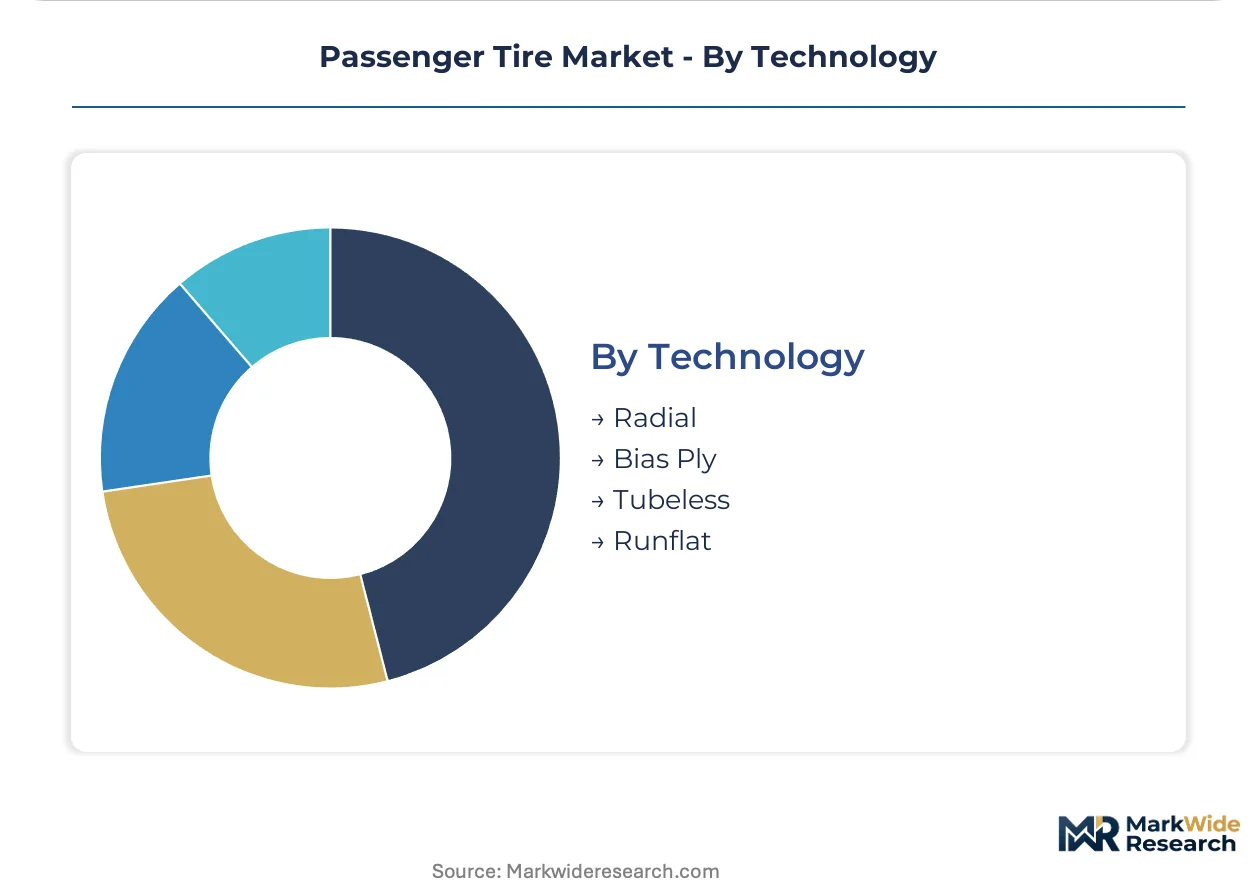
- Radial:Characterized by cord plies running perpendicular to the tread, radial tires offer superior flexibility, longer tread life, and better fuel economy compared to older designs. Radial technology dominates the passenger tire market due to its performance benefits and widespread adoption by vehicle manufacturers globally.
- Bias Ply:An older construction method with crisscrossing cord plies, bias ply tires are now largely confined to niche applications.
- Tubeless:Tubeless tires eliminate the inner tube, relying on a tight seal between the tire bead and wheel rim to retain air.
- Runflat:These tires are designed with reinforced sidewalls to support the vehicle's weight even after a puncture, allowing continued driving for a limited distance. Runflat technology is increasingly adopted by premium vehicle brands and for enhanced safety features, providing drivers with emergency mobility.
Radial construction remains the industry standard, while runflat technology represents a premium safety innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asia's natural rubber production anchors global tire manufacturing, influencing regional market dynamics and supply chain stability. This concentration impacts pricing and strategic sourcing decisions for tire producers worldwide. Several key countries exhibit distinct demand drivers and regulatory landscapes for passenger tires.
China
China's enormous and maturing domestic vehicle parc drives massive and consistent demand for replacement tires. The country's GB standards strictly govern market access for all tires sold domestically. The Yangtze River Delta region, a major automotive hub, sees significant tire production and consumption.
United States
The United States represents a substantial aftermarket, driven by routine replacement cycles and significant EV adoption. NHTSA enforces standards for treadwear and traction, impacting product design. Major automotive hubs like Detroit experience consistent demand for both OEM and aftermarket tires.
Germany
Germany's market is characterized by strong demand from premium vehicle manufacturers and high-performance EVs. EU tire labeling regulations influence consumer purchasing decisions and compel product improvement. The Stuttgart region, home to major automotive players, drives demand for advanced tire technologies.
Japan
Japan possesses an advanced automotive industry, focusing on material science and high-quality OEM fitments. JIS standards govern product quality and performance benchmarks for domestic sales. Tokyo and its surrounding industrial areas host significant R&D centers for tire innovation.
India
India's growing vehicle ownership and developing road infrastructure contribute to increasing tire demand. BIS standards ensure product quality and safety for all tires sold within the country. Chennai and Pune automotive clusters fuel both OEM and replacement tire demand.
Passenger Tire Market Key Industry Players
Global majors compete with regional champions across product innovation and distribution networks. The passenger tire market exhibits a tiered structure, with established global players dominating premium segments and numerous regional manufacturers serving local aftermarket needs. Strategic archetypes include technology innovators focused on EV-specific tires, volume producers emphasizing cost efficiency, and niche players specializing in performance or sustainable materials. Dominant competitive moves involve strategic partnerships with OEMs for new model fitments and continuous investment in R&D for advanced material compounds.
Within the premium and technology-driven segments, Michelin and Continental exemplify manufacturers leveraging strong OEM relationships and integrated automotive systems expertise. Goodyear, a US-based entity, represents a global player with an extensive aftermarket distribution network and broad manufacturing footprint. These companies, alongside others, occupy positions across the value chain, from initial vehicle fitments to the vast replacement market. Their strategies reflect the industry's focus on brand strength, technological differentiation, and global reach.
| Leading Market Players |
|---|
| Bridgestone |
| Yokohama |
| Michelin |
| Falken |
| Toyo |
| Goodyear |
| Pirelli |
| BF Goodrich |
| Continental |
| Others |
Cost & Logistics Intelligence
OEM multi-source procurement strategies are recalibrating the competitive landscape for tire manufacturers, influencing supply chain resilience and driving pricing adjustments. This strategic shift aims to mitigate supply risks while impacting material sourcing and production costs.
Pricing Analysis
Warranty and service bundling increasingly differentiate offerings, particularly with emerging Tire-as-a-Service models for commercial fleets. Per-unit transactional pricing remains dominant for retail replacement tires. Price differentiation stems from brand premium, specialized technology, and after-sales service quality. Pricing pressure stems from volatile raw material costs and intense competition in the aftermarket. Retail drivers remain highly price-sensitive, while OEM and fleet buyers prioritize performance and total cost of ownership.
Supply Chain Analysis
Dual-sourcing requirements from major automotive OEMs are reshaping procurement strategies for tire components. Natural rubber supply concentrates heavily in Southeast Asia, creating a geographic dependency for tire manufacturers. Key raw material dependencies include natural rubber, synthetic rubber, carbon black, and silica. This reliance exposes the supply chain to commodity price volatility and regional instability. Distribution runs through extensive aftermarket networks and direct supply agreements with vehicle manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The passenger tire market is increasingly a vertical-integration race, with players pursuing greater control over sustainable material sourcing to meet evolving environmental mandates.
For Market Incumbents: Anticipate continued investment in advanced material science R&D to reformulate tread compounds, addressing upcoming Euro 7 non-exhaust particulate regulations. Secure long-term contracts for sustainable raw materials, mitigating the threat of supply chain disruptions and volatile commodity prices. Streamline OEM homologation processes for EV-specific tires, leveraging established relationships. Expand manufacturing capacity for next-generation tires, particularly in regions with high EV adoption.
For New Entrants and Emerging Players: Online retailers and specialized service providers represent viable channel partners for new entrants targeting niche segments. Focus on the high-growth EV-specific tire segment, offering enhanced performance and sustainability features. Penetrate commercial fleet markets in North America and Europe with Tire-as-a-Service models, emphasizing predictive maintenance. Differentiate through embedded sensor technology, providing real-time data for fleet optimization and safety.
For Investors and Strategic Acquirers: The window for entry favors technology-agnostic investors seeking long-term value in specialized tire innovations. Long-term viability centers on the transition to sustainable materials and smart tire technologies over the next decade. Target acquisition archetypes include startups specializing in polymer chemistry for non-petroleum compounds or sensor integration. A key signal to watch is the successful commercialization of circular economy models for end-of-life tire recycling.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Material R&D | Reformulating compounds reduces environmental impact and meets evolving regulatory benchmarks like Euro 7. |
| Smart Tire Technology Integration | Embedding sensors provides real-time data for predictive maintenance and new service-based revenue streams. |
| EV Tire Production Capacity Expansion | Scaling manufacturing for specialized EV tires addresses the demand from high-torque, heavier electric vehicles. |
| Circular Economy Model Development | Investing in advanced recycling reduces raw material dependency and aligns with sustainability goals. |
| OEM Homologation Streamlining | Accelerating product qualification with automakers secures critical fitments for new vehicle models. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. Primary interviews with tire manufacturers' R&D leads, automotive OEM procurement managers, aftermarket distributors, and material scientists provided crucial qualitative insights. This fieldwork validated quantitative findings derived from vehicle production databases, NHTSA standards, EU tire labeling mandates, and China's GB standards. A rigorous bottom-up and top-down triangulation approach reconciled discrepancies.
Data-stream reconciliation across multiple sources informed the analytical framework for market projections. The forecast framework analyzed market dynamics across the projection horizon by product type, end user, size, technology, and regional regulatory landscapes. Compound Annual Growth Rates were derived using regression analysis and market share projections, incorporating inputs like global EV adoption rates and raw material price forecasts.
Caveats apply where rapid shifts in geopolitical events or unexpected regulatory mandates could materially shift the outlook. Forecasts reflect assumptions about technology adoption and economic stability. Deviation in raw material supply or EV policy changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
EV Tire Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
Automotive Smart Tire Market