
 Mexico Automotive Parts Aluminum Die Casting Market | 2026-2036
Mexico Automotive Parts Aluminum Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive Parts Aluminum Die Casting Market Foresight
Tier-1 Suppliers is bifurcating from traditional OEM-direct relationships toward specialized sub-tier partnerships for complex structural castings. Nemak leverages its integrated aluminum recycling and casting operations across northern Mexico to secure long-term supply agreements with vehicle assemblers. Bocar Group anchors its competitive position through dedicated high-pressure die-casting capacity serving transmission housing programs for domestic and export-bound platforms.
Automotive parts aluminum die casting is a metal-forming process wherein molten aluminum alloys—typically A380, ADC12, or Silafont-36 with silicon content of 9-12%—are injected under controlled pressure into precision steel molds to produce net-shape or near-net-shape components with wall thicknesses as low as 2.5 millimeters. The process serves primarily to reduce vehicle mass while maintaining structural integrity for powertrain, chassis, and safety-critical assemblies. Structural Parts command the deepest margin pools as crashworthiness requirements and multi-material joining complexity elevate engineering premiums. High Pressure Die Casting dominates volume throughput for engine components and transmission housings where cycle-time economics govern competitiveness. Electric Vehicles application is gaining fastest traction as battery enclosure castings and motor housing designs demand novel alloy formulations and larger machine footprints.
SEMARNAT enforces NOM-085-ECOL atmospheric emissions standards that constrain foundry energy intensity and particulate discharge rates across Mexican production zones. PROSEC tariff relief programs administered by SE require documented regional value content thresholds that shape supplier localization decisions for export-oriented die-casting operations. The central bank and economy ministry coordinate industrial policy incentives that influence capital deployment timing for new press installations. Stakeholders must monitor evolving USMCA rules-of-origin deliberations and their potential to redefine qualifying aluminum transformation thresholds for duty-free automotive trade.
Market Dynamics
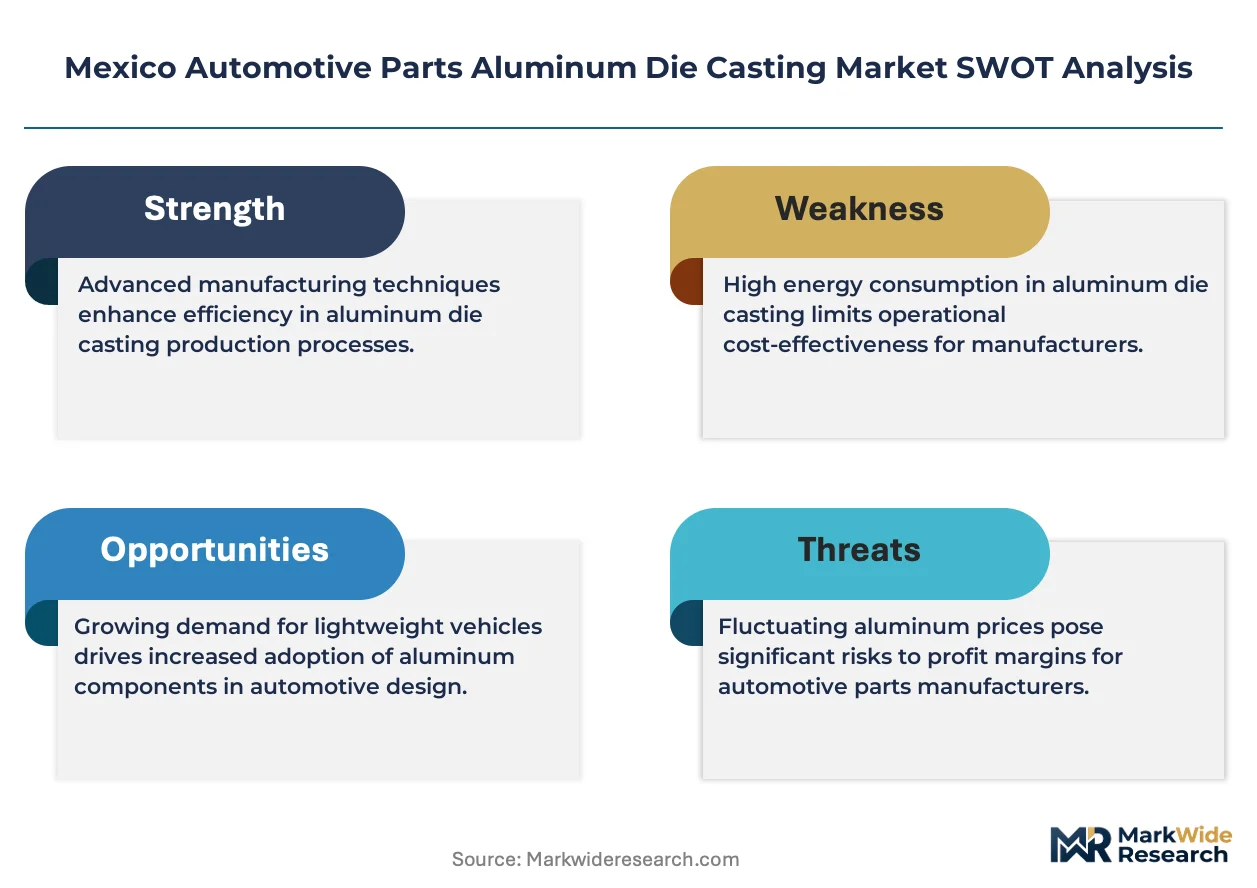
USMCA rules-of-origin deliberations are forcing Tier-1 suppliers to requalify aluminum transformation thresholds, compressing sourcing radii around Bajío foundries and accelerating sub-tier consolidation for structural chassis programs.
Growth Catalysts
- NOM-085-ECOL atmospheric standards:SEMARNAT's emissions framework is retrofitting foundry energy systems, creating demand for low-intensity melting technologies and particulate capture equipment across Guanajuato production zones.
- Battery enclosure castings:Electric vehicle platform architectures are pulling novel aluminum-silicon alloys into high-pressure die-casting footprints previously sized for transmission housings.
- PROSEC tariff relief:SE-administered regional value content thresholds are localizing export-oriented die-casting capacity within tight supply radii of OEM assembly plants.
Market Restraints
- Primary aluminum price volatility:LME benchmark swings transmit directly into foundry margin compression, constraining multi-year contract pricing for structural component programs.
- Machine tool supply concentration:Large-tonnage high-pressure die-casting press availability concentrates with German and Italian equipment builders, extending lead times for Bajío capacity expansions.
- Multi-material joining complexity:Crashworthiness-rated aluminum-to-steel weld protocols remain technically constrained, limiting structural casting penetration in mixed-material vehicle platforms.
Strategic Opportunities
- Querétaro precision machining cluster:Untapped sub-tier capacity for post-cast CNC finishing and surface treatment sits adjacent to existing foundry infrastructure.
- Silafont-36 alloy adoption:High-ductility formulations are enabling thin-wall battery tray designs that merge structural and thermal management functions.
- Industrial policy incentives:Economy ministry-coordinated capital deployment programs are accelerating press installation timelines for qualified greenfield projects.
Industry Challenges
- Tooling engineer scarcity:Precision steel mold design and thermal management expertise concentrates with aging specialists, constraining new product introduction velocity.
- USMCA qualification timelines:Documented aluminum transformation audits for duty-free automotive trade are extending supplier onboarding cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive Parts Aluminum Die Casting Market |
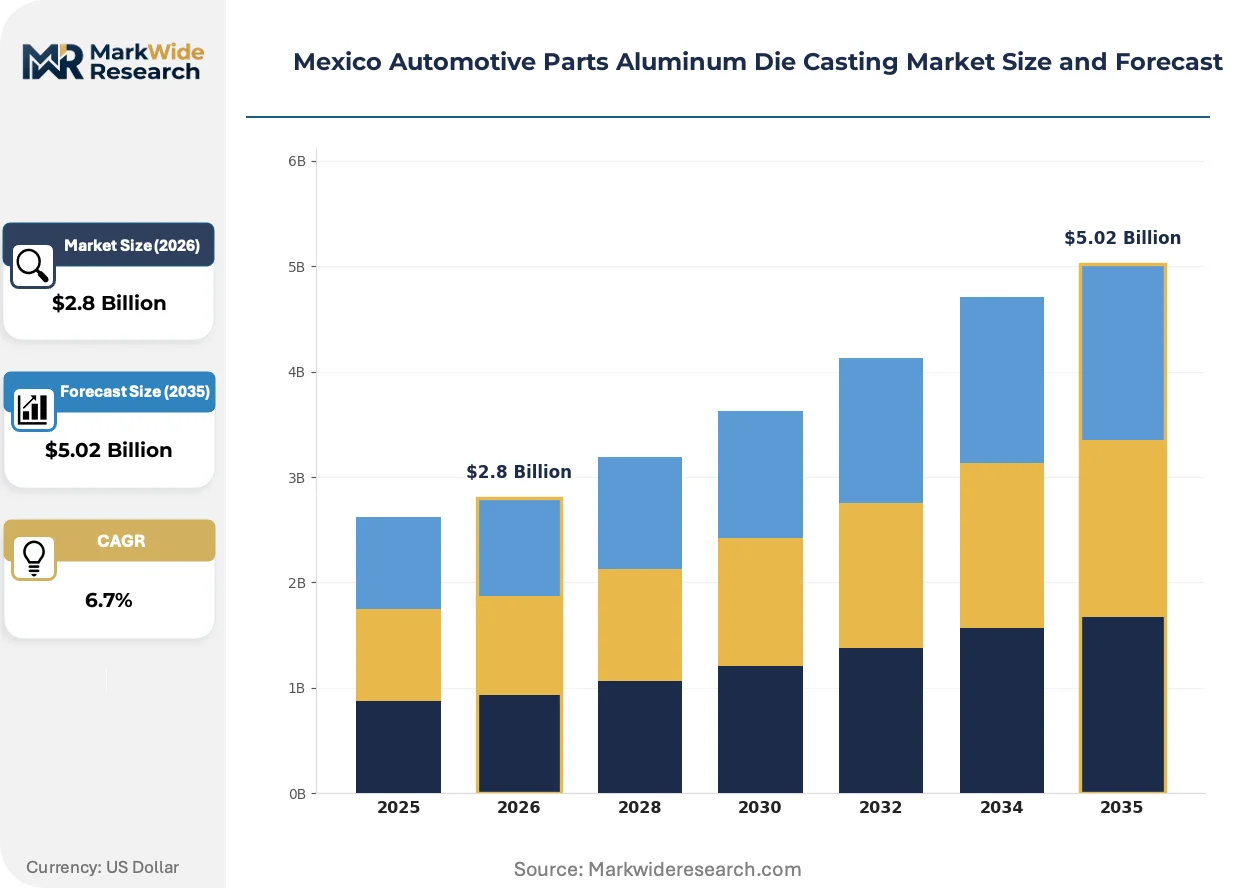
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Structural Parts, Chassis Components End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: High Pressure Die Casting, Low Pressure Die Casting, Gravity Die Casting, Vacuum Die Casting Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles |
| Companies Covered | Linamar Corporation, Dynacast International, Nemak, Sandhar Technologies Limited, Ryobi Limited, Bocar Group, GF Casting Solutions, Empire Casting Co., Magna International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive Parts Aluminum Die Casting Market Shifts & Advancements
Process-intelligent foundries are integrating real-time thermal monitoring with predictive maintenance algorithms, compressing defect rates and enabling just-in-sequence delivery to OEM assembly lines.
Large-part high-pressure die casting is decomposing the traditional stamping-and-welding paradigm for electric vehicle rear floor assemblies. Tier-1 suppliers in Querétaro are adopting 4,000-ton-plus machine footprints to produce single-piece aluminum castings that previously required 70-90 stamped components. This consolidation is decomposing legacy supply chain node counts and collapsing logistics coordination costs for platform-scale programs.
SEMARNAT's escalating NOM-085-ECOL enforcement is retrofitting atmospheric emissions controls across Guanajuato foundry zones. The regulation mandates continuous particulate monitoring and energy intensity benchmarking, compelling capital allocation toward electric melting furnaces and regenerative thermal oxidizers. Structural parts producers face the steepest compliance premiums given their longer cycle times and higher melt volumes per part.
Buyer concentration around dedicated platform engineering teams is displacing traditional commodity purchasing for aluminum chassis castings. OEM technical sourcing groups in Aguascalientes and San Luis Potosí are embedding die-casting specialists into vehicle development programs from concept phase, compressing traditional RFQ-to-award cycles and locking in foundry capacity 36-48 months ahead of production launch.
Mexico Automotive Parts Aluminum Die Casting Market Segmentation
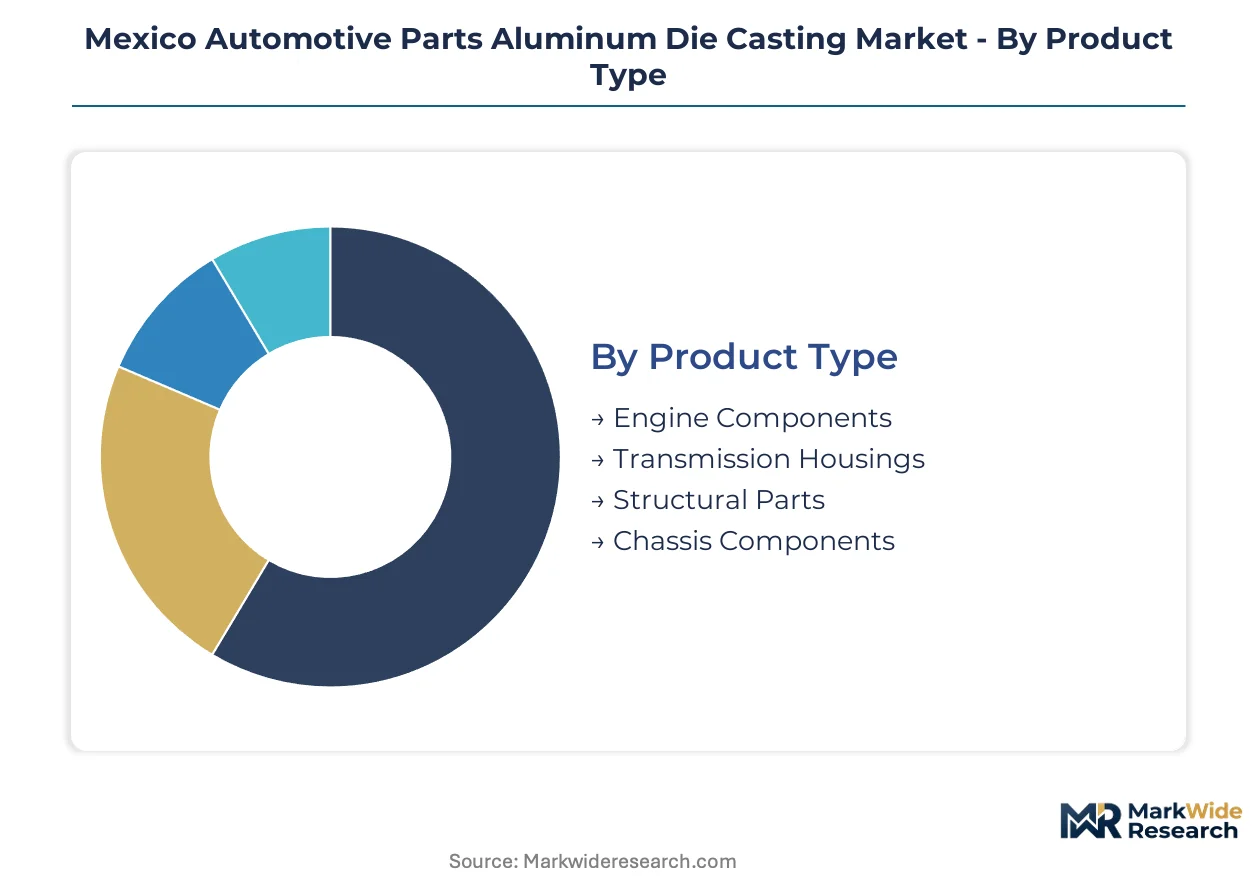
Aluminum die-casting procurement flows through distinct channel configurations depending on component criticality and assembly timing. Each segmentation dimension reveals how material specifications, tooling investments, and regulatory compliance reshape supplier-buyer relationships across the Bajío industrial corridor.
Product Type:
Engine and transmission castings move through long-term OEM-direct channels with 36-month qualification cycles, while structural chassis components increasingly route through Tier-1 integrators seeking localized sub-tier consolidation.
- Structural Parts:Crash-rated aluminum castings for subframes and cradles carry silicon-modified alloy specifications demanding heat treatment protocols. Demand clusters around Querétaro assembly plants where multi-material joining complexity justifies premium engineering margins.
- Transmission Housings:High-pressure die-cast A380 aluminum enclosures with integrated cooling channels and mounting bosses. Bajío foundries serving Ford and Stellantis transmission programs dominate volume throughput through dedicated platform supply agreements.
- Engine Components:Cylinder heads and blocks requiring porosity control below 0.5 percent for combustion pressure integrity.
- Chassis Components:Control arms and knuckles with thin-wall specifications down to 2.5 millimeters.
By volume, Transmission Housings leads. By growth pace, Structural Parts is expanding most quickly.
End User:
Cost tiers separate capital-intensive foundry relationships: OEMs and vehicle assemblers anchor high-volume, low-margin transmission work, while Tier-1 suppliers capture structural component premiums through engineering integration services.
- Tier-1 Suppliers:Integrated aluminum specialists like Nemak and Bocar Group combine in-house recycling with high-pressure die-casting capacity. These firms are consolidating sub-tier sourcing radii around Guanajuato foundries to satisfy PROSEC regional value content thresholds for export-bound platforms.
- Vehicle Assemblers:OEM manufacturing complexes in Aguascalientes and San Luis Potosí operate captive die-casting for powertrain components. Direct foundry ownership allows just-in-sequence delivery coordination with assembly line takt times.
- OEMs:Brand-holding manufacturers specifying component designs while outsourcing production.
- Aftermarket Providers:Independent distributors serving replacement part demand with shorter lead time requirements.
Vehicle Assemblers command the largest procurement volumes. Tier-1 Suppliers are gaining share fastest through structural casting integration.
Technology:
Maturity gradients separate established process economics from emerging capability investments: high-pressure die casting dominates current revenue, while vacuum-assisted variants capture battery enclosure growth.
- High Pressure Die Casting:Cold-chamber machines injecting molten aluminum at 1,000-1,500 bar into hardened steel dies. Guanajuato foundries deploy 4,000-ton-plus presses for electric vehicle rear floor castings that consolidate 70-90 stamped components into single-piece structures.
- Vacuum Die Casting:Evacuated die cavities reducing gas porosity for heat-treatable structural alloys. Silafont-36 formulations enabling thin-wall battery tray designs are pulling this technology into Querétaro capacity expansions.
- Low Pressure Die Casting:Permanent mold filling under controlled pressure for wheel and suspension components.
- Gravity Die Casting:Tilt-pour or static casting for thick-section parts with lower mechanical property requirements.
High Pressure Die Casting retains volume leadership. Vacuum Die Casting shows the steepest expansion trajectory as thermal management castings proliferate.
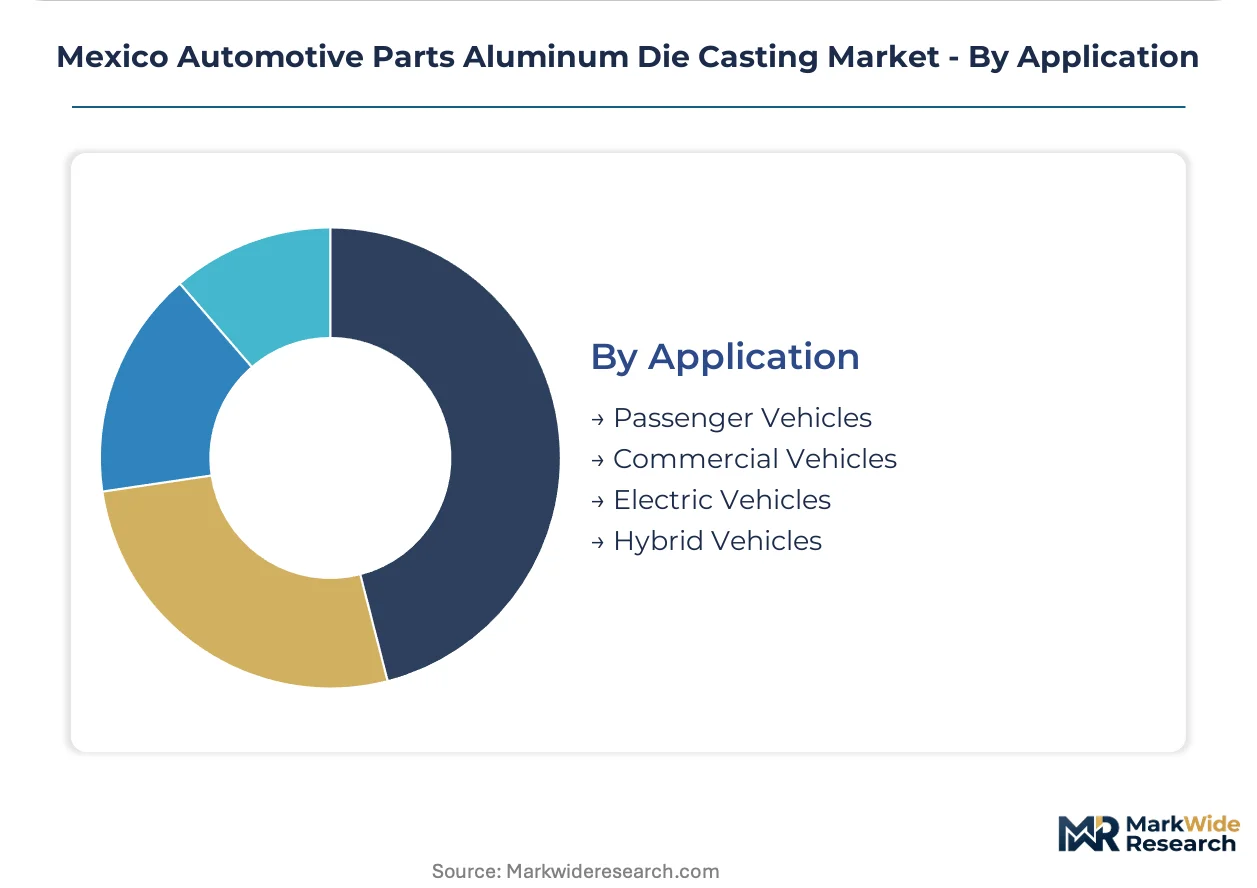
Application:
Customer type segmentation separates legacy internal combustion platforms from electrification-driven demand: passenger and commercial vehicle programs maintain incumbent supplier relationships, while electric vehicle architectures disrupt traditional casting specifications.
- Electric Vehicles:Battery enclosure castings and motor housings demanding novel aluminum-silicon alloys with enhanced thermal conductivity. SEMARNAT NOM-085-ECOL emissions standards are retrofitting foundry energy systems to serve this segment's larger machine footprints and longer cycle times.
- Passenger Vehicles:Light-duty platforms consuming transmission housings and engine brackets through established supply agreements. Mexican production of compact and mid-size models sustains baseline die-casting demand across Bajío supplier networks.
- Commercial Vehicles:Heavy-duty powertrain and chassis castings with thicker wall sections.
- Hybrid Vehicles:Dual powertrain architectures combining internal combustion and electric motor castings.
Passenger Vehicles maintains volume dominance. Electric Vehicles is climbing the fastest as platform architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Die-casting capacity clusters within tight supply radii of OEM assembly plants across central Mexico. SEMARNAT emissions enforcement and PROSEC tariff rules are reshaping foundry investment patterns toward localized sub-tier networks.
Bajío Region
Transmission housing programs for Ford and Stellantis anchor demand in Guanajuato and Querétaro. NOM-085-ECOL atmospheric standards are retrofitting foundry energy systems with electric melting furnaces. Querétaro's precision machining cluster supplies post-cast CNC finishing adjacent to Nemak and Bocar Group casting operations.
Nuevo León
Monterrey's industrial base supports captive die-casting for heavy-duty powertrain components serving commercial vehicle platforms. The state's economy ministry coordinates capital deployment incentives for qualified greenfield press installations. Apodaca and Santa Catarina host dedicated high-pressure die-casting capacity for export-bound transmission programs.
Mexico City Metro
Aftermarket distribution channels concentrate in Tlalnepantla and Ecatepec for replacement engine components. Federal environmental permits for atmospheric emissions constrain foundry expansion in the capital zone. Suppliers are relocating primary casting operations to Guanajuato while maintaining logistics coordination offices in the metro area.
Jalisco
Guadalajara's automotive supplier ecosystem feeds secondary machining and surface treatment for Bajío-sourced castings. State-level industrial policy incentives accelerate sub-tier consolidation for structural chassis programs. El Salto and Tlajomulco host tooling engineering services supporting mold design for Querétaro foundries.
Northern Border States
Chihuahua and Coahuila coordinate just-in-sequence delivery with US assembly plants across the Texas border. USMCA rules-of-origin deliberations are extending supplier qualification timelines for duty-free aluminum transformation. Ciudad Juárez and Ramos Arizpe maintain dedicated logistics corridors for powertrain component exports.
Mexico Automotive Parts Aluminum Die Casting Market Competitive Landscape
Concentration sits with integrated Tier-1 specialists combining captive aluminum recycling with high-pressure die-casting capacity. The supplier base organizes around three archetypes: vertically integrated recyclers-casters, dedicated transmission housing specialists, and diversified automotive component conglomerates. Competitive moves center on sub-tier sourcing radius compression and multi-year platform supply agreement lock-ins.
Among North American-integrated fabricators, Linamar Corporation and Magna International exemplify diversified automotive component conglomerates with die-casting capacity embedded within broader powertrain and chassis portfolios. Nemak anchors the vertically integrated recycler-caster archetype through northern Mexico aluminum operations. Bocar Group occupies a position within the dedicated transmission housing specialist tier. Dynacast International represents precision die-casting specialists with multi-continental footprint patterns. GF Casting Solutions sits within European-headquartered casting technology providers serving Mexican OEM platforms through regional production nodes.
| Leading Market Players |
|---|
| Linamar Corporation |
| Dynacast International |
| Nemak |
| Sandhar Technologies Limited |
| Ryobi Limited |
| Bocar Group |
| GF Casting Solutions |
| Empire Casting Co. |
| Magna International |
| Others |
Supply & Pricing Matrix
PROSEC regional value content thresholds gate both supplier qualification and price differentiation simultaneously across Mexican die-casting operations, forcing export-bound foundries to document transformation audits before accessing tariff relief and premium contract tiers.
Pricing Analysis
NOM-085-ECOL atmospheric standards dictate the pricing tier structure across Guanajuato and Querétaro production zones. Three-tier pricing structure across premium, standard, and economy levels separates heat-treatable structural alloys with full SEMARNAT compliance from baseline transmission housings and aftermarket replacement castings. Cost compression in standard-tier transmission programs is intensifying because LME aluminum volatility transmits directly into multi-year contract renegotiations. Aftermarket distributors exhibit the highest price sensitivity, while OEM platform engineering teams prioritize qualification speed over unit cost for crash-rated chassis castings.
Supply Chain Analysis
Machine tool lead times stretching 14-18 months for 4,000-ton-plus presses have compressed inventory buffers across Bajío foundry networks. Primary aluminum supply draws from Canadian smelters and domestic recycling streams, while precision steel die tooling sources from German and Italian equipment builders. Single-source vulnerability concentrates in large-tonnage press availability, constraining capacity expansion timing for electric vehicle battery enclosure programs. Distribution runs through dedicated platform supply agreements with just-in-sequence delivery coordination to OEM assembly plants in Aguascalientes and San Luis Potosí.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against magnesium and carbon fiber composite substitution in structural chassis applications, where weight reduction targets are pulling alternative materials into vehicle platform engineering discussions.
For Market Incumbents: Fortify captive aluminum recycling operations to buffer LME price volatility and secure PROSEC qualification through documented regional value content. Expand high-pressure die-casting capacity in Querétaro's precision machining cluster to capture battery enclosure growth from electric vehicle platform launches. Lock in 36-48 month platform supply agreements before tooling engineer scarcity extends new product introduction timelines further. For New Entrants and Emerging Players: Accelerated SEMARNAT environmental certification pathways offer entry points for foundries deploying electric melting furnaces and regenerative thermal oxidizers from greenfield construction. Target vacuum die-casting capacity for Silafont-36 battery tray programs, where thin-wall thermal management specifications outpace incumbent capability expansion. Pursue sub-tier partnerships with Tier-1 integrators seeking localized structural casting consolidation rather than direct OEM qualification cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric vehicle battery enclosure casting as 4,000-ton-plus machine footprints and novel alloy R&D requirements reshape investment thresholds. Prioritize acquisition targets combining captive recycling with vacuum die-casting capability in Guanajuato's emissions-compliant zones. Monitor USMCA rules-of-origin deliberations as the signal for duty-free aluminum transformation threshold adjustments that would revalue export-oriented capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Recycling | Captive scrap processing insulates margins from LME volatility and satisfies PROSEC regional content rules. |
| Vacuum Die Casting Capacity Expansion | Silafont-36 battery tray demand pulls this technology into Querétaro as thermal management castings proliferate. |
| Platform Supply Agreement Lock-ins | Multi-year contracts with Ford and Stellantis secure throughput for dedicated transmission housing programs. |
| Precision Machining Cluster Proximity | Post-cast CNC finishing adjacent to Nemak and Bocar operations collapses logistics coordination costs. |
| Environmental Compliance Retrofit | NOM-085-ECOL electric furnace upgrades qualify foundries for SEMARNAT permits and OEM sustainability sourcing. |
Research Methodology
Desk research of customs/trade data, vehicle production databases, and SEC filings preceded structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, foundry operations managers, and aftermarket distribution heads across the Bajío industrial corridor. Primary fieldwork combined facility assessments in Guanajuato and Querétaro with technical validation from aluminum alloy specialists and die-casting equipment manufacturers. Bottom-up volume modeling triangulated against top-down OEM production forecasts and IHS Markit registration data.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within segment-level forecasts. Modeled dimensions span product type, propulsion architecture, casting technology, and regional production cluster. CAGRs derive from trend extrapolation of OEM platform launch schedules, alloy formulation adoption curves, and press installation timelines. Industry-specific inputs include SEMARNAT enforcement intensity projections and USMCA rules-of-origin threshold scenarios.
Underlying assumptions cover stable PROSEC tariff relief continuity and aluminum-silicon alloy supply availability, with deviation risk concentrated in primary aluminum price volatility and German-Italian machine tool delivery delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Fluid Couplings Market