
 Argentina Automotive Parts Aluminium Die Casting Market | 2026-2036
Argentina Automotive Parts Aluminium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Automotive Parts Aluminium Die Casting Market Outlook
Software-defined thermal management is decoupling die-cast aluminium component sales from traditional hardware-only contracts. Nemak leverages its integrated casting-machining footprint to anchor long-term supply agreements with domestic vehicle assemblers. Ryobi Die Casting sustains technical leadership through precision high-pressure cell deployment, while ALUAR Aluminio Argentino S.A.I.C. dominates feedstock security with its captive smelting and rolling operations.
Automotive parts aluminium die casting refers to the metal-forming process wherein molten aluminium alloys—typically A380, ADC12, or Silafont-36 with silicon contents between 9-12%—are injected under pressures exceeding 1,000 bar into hardened steel molds to produce net-shape or near-net-shape vehicle components. The process yields parts with wall thicknesses below 2.5mm, delivering the strength-to-weight ratios essential for powertrain and structural applications where mass reduction directly improves fleet efficiency. Engine Components and Transmission Cases represent the mature revenue base, with margin pools shifting toward Structural Parts as OEMs consolidate multi-piece weldments into single castings for crash-management assemblies. High Pressure Die Casting leads technology deployment due to its cycle-speed advantages, though Thin Wall Die Casting is gaining fastest among Tier-1 Suppliers serving hybrid vehicle platforms requiring complex cooling jacket geometries.
Argentina's national automotive regulator enforces Mercosur technical standards that mandate progressive emissions reductions, directly stimulating aluminium substitution in engine blocks and transmission housings. The country's central bank and industry ministry coordinate import-substitution incentives that condition market access on local content thresholds, pressuring foreign suppliers to establish domestic die-casting capacity. Stakeholders must monitor whether pending revisions to Mercosur automotive trade rules preserve or erode the cost competitiveness of Argentine-produced castings relative to Brazilian and Mexican supply alternatives.
Market Dynamics
Software-defined thermal management is decoupling die-cast aluminium component sales from traditional hardware-only contracts, forcing foundries to bundle casting, machining, and sensor integration into single-source agreements with Argentine vehicle assemblers.
Growth Catalysts
- Mercosur Emissions Standards:Progressive CO2 reduction mandates are accelerating aluminium substitution in powertrain housings as OEMs seek mass reduction to meet fleet efficiency benchmarks.
- Buenos Aires Industrial Corridor:Concentrated foundry investment in this province draws Tier-1 suppliers toward integrated casting-machining facilities with established logistics infrastructure.
- Thin Wall Die Casting:This process variant enables sub-2.5mm wall thicknesses for complex cooling jacket geometries demanded by hybrid vehicle platforms entering local assembly lines.
Market Restraints
- Primary Aluminium Price Volatility:Feedstock cost swings tied to London Metal Exchange pricing compress foundry margins and complicate long-term contract negotiations with domestic assemblers.
- Brazilian Import Competition:Established die-casting capacity in São Paulo state threatens Argentine suppliers when Mercosur trade rules permit duty-free component flows.
- High-Pressure Cell Technical Limitations:Existing equipment constraints on shot weights above 40kg restrict participation in emerging structural battery housing segments.
Strategic Opportunities
- Structural Battery Enclosures:Giga-casting demand from electric vehicle platforms offers margin expansion beyond traditional engine and transmission applications.
- Córdoba Province Expansion:Underdeveloped foundry infrastructure in this automotive manufacturing hub presents greenfield investment potential for Tier-1 suppliers.
- Import-Substitution Incentives:Argentina's industry ministry conditions market access on local content thresholds, pressuring foreign suppliers to establish domestic die-casting capacity.
Industry Challenges
- Multi-Axis Machining Skill Gap:Shortage of CNC programmers capable of finishing complex cast geometries limits throughput at integrated casting-machining facilities.
- Giga-Press Capex Requirements:6,000-tonne-plus high-pressure cells demand capital commitments exceeding established supplier balance sheet capacity.
- Mercosur Homologation Timelines:Extended certification cycles for new casting alloys delay product launches and tie up engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Automotive Parts Aluminium Die Casting Market |
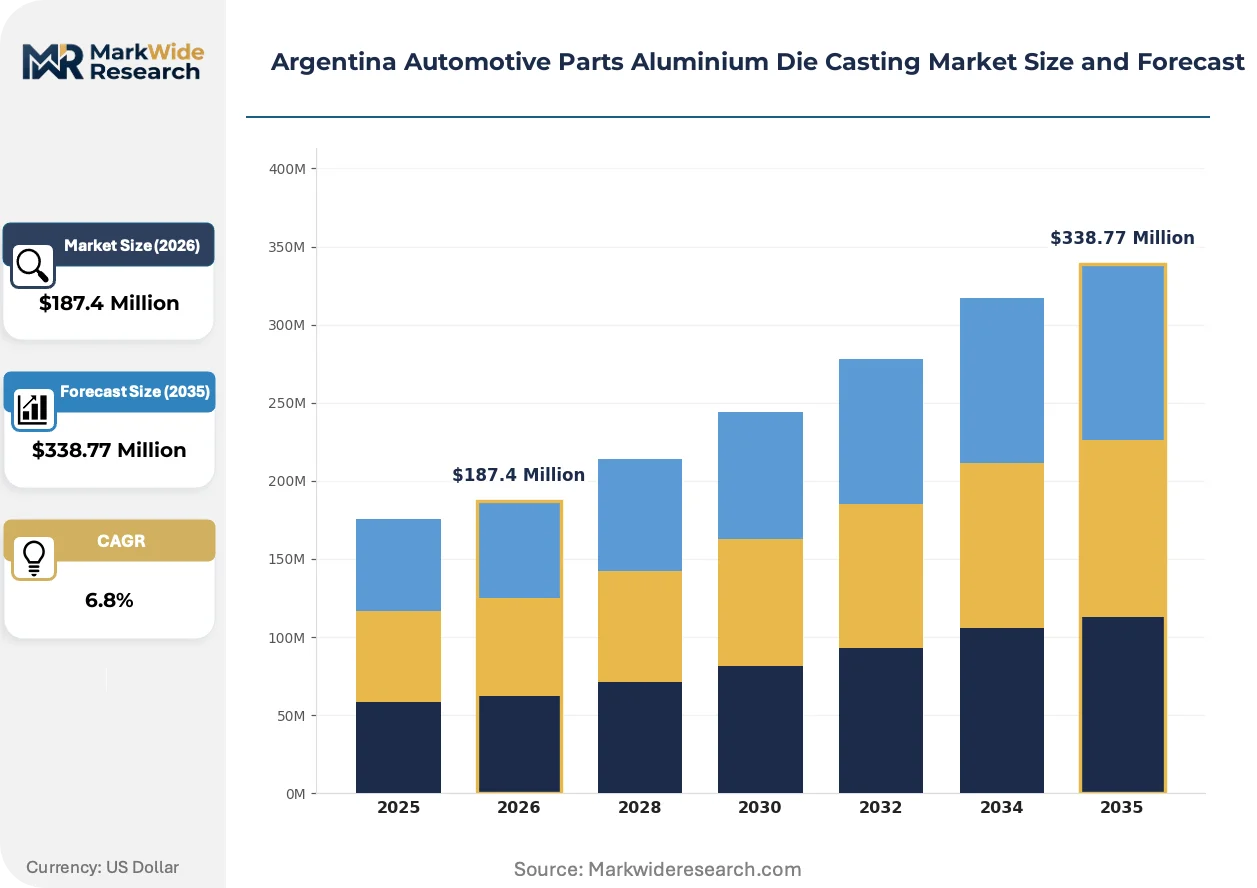
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Cases, Structural Parts, Chassis Parts End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Stage: Primary Manufacturing, Secondary Processing, Surface Treatment, Assembly Technology: Thin Wall Die Casting, High Pressure Die Casting, Cold Chamber Die Casting, Hot Chamber Die Casting |
| Companies Covered | Nemak, Ryobi Die Casting, KSPG AG, Interplex Holdings Ltd, ALCOA Inc, ALUAR Aluminio Argentino S.A.I.C., Fabrica Argentina de Aluminio, Metalsa, Grupo Sodecar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Automotive Parts Aluminium Die Casting Market Strategic Shifts
Active thermal management integration is reshaping component specifications across Argentine supply chains. Foundries now compete on embedded sensor capability rather than pure casting geometry.
Silafont-36 alloy formulations are integrating silicon-content optimization with in-mold temperature monitoring to eliminate porosity in thin-wall transmission cases. Domestic hybrid vehicle assemblers are adopting these specifications for 2026 platform launches. The technology is integrating casting simulation software with real-time process control, compressing prototype-to-production cycles from eighteen months to under ten.
Argentina's national automotive regulator enforces Mercosur technical standards that mandate progressive emissions reductions, directly stimulating aluminium substitution in engine blocks and transmission housings. Local content requirements tied to import-substitution incentives pressure foreign suppliers to establish domestic die-casting capacity rather than serve the market through Brazilian export channels. Engine Components and Transmission Cases segments are responding by consolidating multi-piece weldments into single castings that satisfy both weight and crash-management requirements.
Buyer concentration among three domestic vehicle assemblers is compressing supplier negotiation leverage and extending payment terms toward ninety-day cycles. Tier-1 foundries are responding by embedding predictive maintenance sensors into cast components, creating recurring software revenue streams that offset hardware margin pressure. This behavioral shift is most visible in powertrain housing contracts where Nemak and Ryobi Die Casting now bundle thermal monitoring algorithms with physical component supply.
Argentina Automotive Parts Aluminium Die Casting Market Segmentation
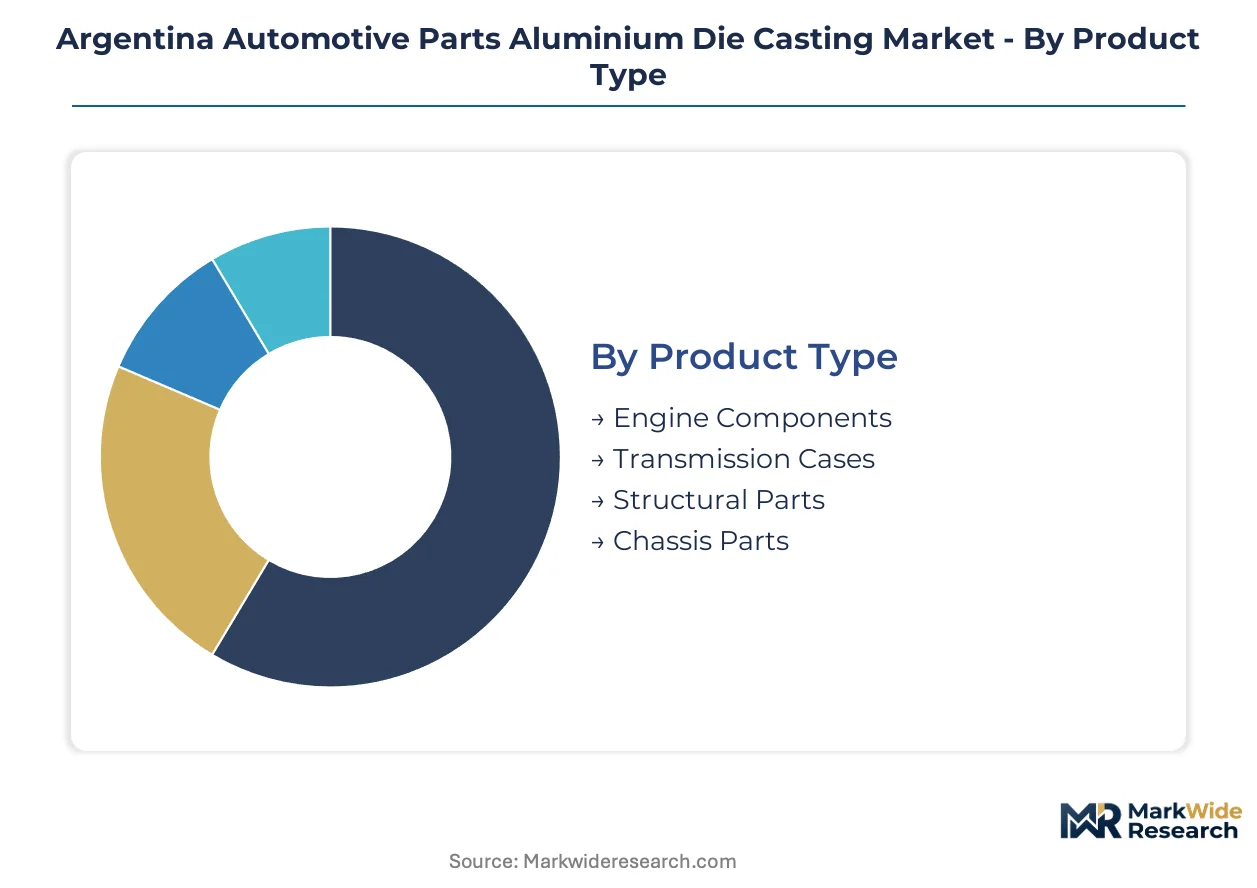
Segmentation in Argentina's aluminium die-casting market tracks how procurement power concentrates among domestic vehicle assemblers and where technology investments yield margin protection. Buyers prioritize integrated casting-machining capabilities over commodity supply, reshaping vendor selection criteria across all product categories.
Product Type:
Component selection hinges on crash-performance certification requirements and the technical feasibility of consolidating multi-piece assemblies into single castings.
- Engine Components:Cylinder heads, blocks, and oil pans fabricated from A380 or Silafont-36 alloys with 9-12% silicon content dominate foundry output in Buenos Aires province. Argentine OEMs specify these for powertrain platforms governed by Mercosur emissions standards, though margin pressure intensifies as assemblers extend payment terms toward ninety-day cycles.
- Transmission Cases:Housing assemblies for manual and automatic gearboxes demand sub-2.5mm wall thicknesses achievable through thin-wall process variants. Local hybrid vehicle programs are accelerating specifications for integrated cooling jacket geometries that reduce weight while maintaining thermal stability.
- Structural Parts:Crash-management castings consolidate former weldments into single aluminium components for side rails and cross-members.
- Chassis Parts:Suspension brackets and steering knuckles serve aftermarket replacement channels alongside OEM supply.
Volume sits with Engine Components; growth tilts toward Structural Parts.
End User:
Supply relationships stratify by technical integration depth, with the most sophisticated buyers demanding embedded sensor capability alongside physical components.
- OEMs:Original equipment manufacturers in Argentina's three-assembly-plant market wield concentrated procurement leverage, negotiating long-term agreements that bundle casting, machining, and thermal management software into single-source contracts.
- Tier-1 Suppliers:These intermediaries capture value through integrated casting-machining facilities positioned along the Buenos Aires industrial corridor, serving as technical translators between foundries and vehicle assemblers.
- Vehicle Assemblers:Final assembly operations in Córdoba and Buenos Aires provinces specify local content thresholds that condition market access under import-substitution incentives.
- Aftermarket:Replacement component demand flows through independent distributors serving Argentina's aging vehicle fleet.
Procurement authority concentrates with OEMs; capability investment clusters with Tier-1 Suppliers.
Manufacturing Stage:
Process stage selection determines capital intensity and skill requirements, with Argentine foundries competing most effectively where machining integration creates defensible positioning.
- Primary Manufacturing:Molten aluminium injection into hardened steel molds at pressures exceeding 1,000 bar yields net-shape castings with minimal post-processing requirements.
- Secondary Processing:CNC finishing of complex geometries including multi-axis machining for transmission case sealing surfaces and engine block deck faces.
- Surface Treatment:Shot blasting, chemical conversion coating, and anodizing prepare castings for assembly line integration and corrosion resistance.
- Assembly:Integration of die-cast components into sub-assemblies with sensors, fasteners, and thermal management hardware.
Margin protection resides in Secondary Processing; automation priority targets Assembly.
Technology:
Process selection balances cycle speed against geometric complexity, with Argentine foundries constrained by equipment limitations on shot weights above 40kg.
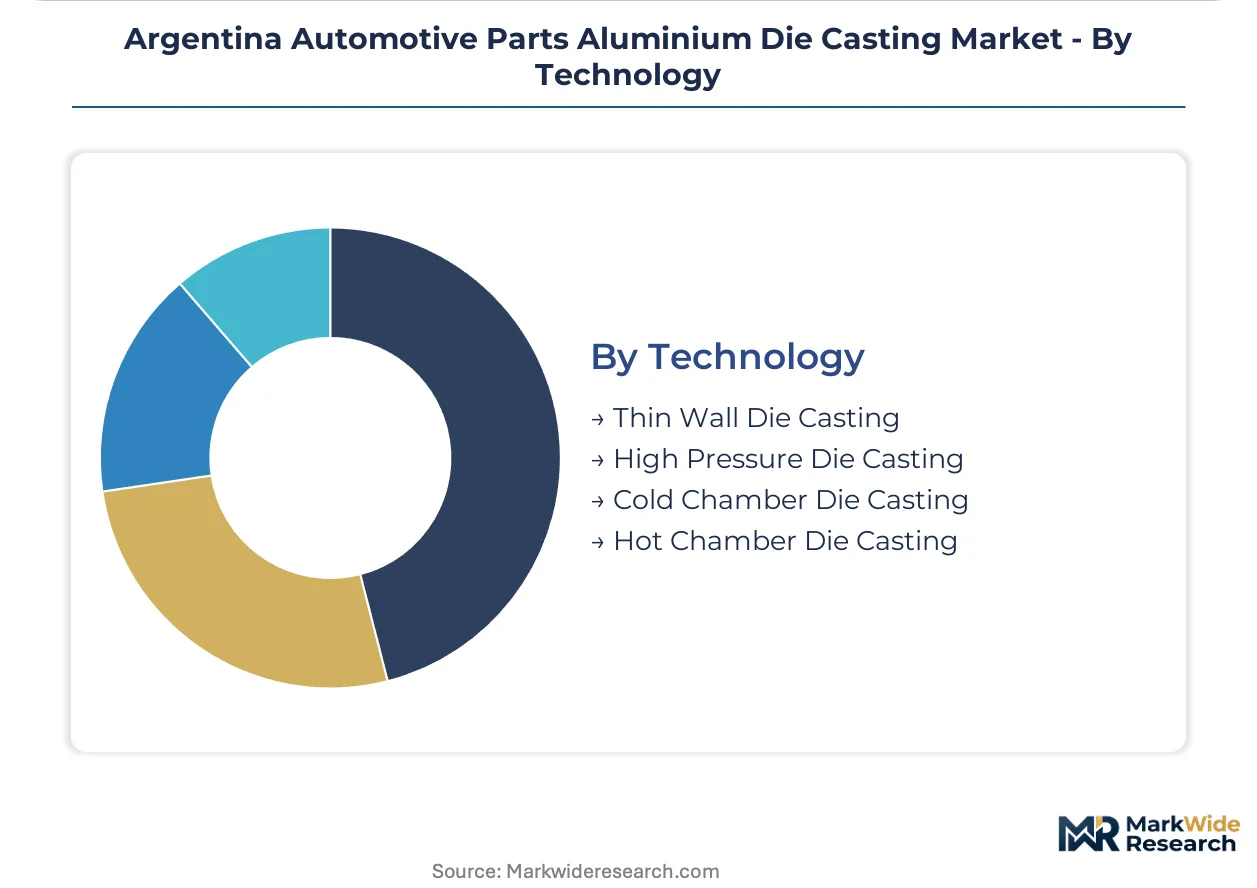
- High Pressure Die Casting:Cycle-speed advantages dominate Argentine foundry deployment, with 1,000-4,000 tonne cells serving engine and transmission applications across Buenos Aires province.
- Thin Wall Die Casting:Sub-2.5mm capability enables complex cooling jacket geometries for hybrid powertrains entering local assembly lines, representing the steepest expansion trajectory among process variants.
- Cold Chamber Die Casting:Aluminium-specific process variant prevents molten metal contamination in high-volume production environments.
- Hot Chamber Die Casting:Limited Argentine deployment due to zinc-alloy specialization; marginal relevance for automotive aluminium applications.
Installed base favors High Pressure Die Casting; capability gaps constrain Cold Chamber expansion for structural battery enclosures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's aluminium die-casting capacity concentrates in Buenos Aires province while consumption spreads across Córdoba and Santa Fe assembly corridors. This production-consumption split shapes logistics costs and supplier location decisions.
Buenos Aires Province
Engine block and transmission housing demand from Toyota and General Motors assembly plants drives foundry investment. The province's national industry ministry coordinates import-substitution incentives that condition component sourcing on local manufacturing presence. Greater Buenos Aires hosts Nemak and Ryobi Die Casting facilities clustered along Route 9 industrial corridor.
Córdoba Province
Renault and Nissan vehicle assembly operations generate structural parts demand for crash-management applications. The provincial automotive cluster receives technical support from Argentina's national automotive regulator for Mercosur emissions compliance. Córdoba city remains underdeveloped in foundry infrastructure, presenting greenfield investment gaps.
Santa Fe Province
Transmission case procurement from Ford and Volkswagen plants accelerates thin-wall die-casting specifications. Provincial industrial development agencies align with central bank financing programs for capital equipment imports. Rosario port logistics reduce aluminium feedstock delivery costs for regional suppliers.
Mendoza Province
Aftermarket distribution channels serve Chilean export markets through mountain pass corridors. The province's development corporation promotes secondary processing capabilities to capture value beyond raw casting. Godoy Cruz industrial park hosts smaller foundries specializing in chassis component replacement parts.
Argentina Automotive Parts Aluminium Die Casting Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Argentine supply chains. The market structure tilts toward consolidated Tier-1 control, with three domestic assemblers wielding concentrated procurement leverage. Strategic archetypes separate integrated casting-machining operators, captive smelter-backed fabricators, and pure-play foundries dependent on toll processing. Dominant competitive moves include backward integration into primary aluminium supply and geographic expansion toward Córdoba's underdeveloped foundry base.
Within the integrated operator tier, Nemak and Ryobi Die Casting exemplify casting-machining bundling strategies that secure long-term assembler agreements. ALUAR Aluminio Argentino S.A.I.C. occupies a distinct position through captive smelting and rolling operations that insulate feedstock costs from London Metal Exchange volatility. These three entities anchor competitive dynamics across Buenos Aires industrial corridor.
| Leading Market Players |
|---|
| Nemak |
| Ryobi Die Casting |
| KSPG AG |
| Interplex Holdings Ltd |
| ALCOA Inc |
| ALUAR Aluminio Argentino S.A.I.C. |
| Fabrica Argentina de Aluminio |
| Metalsa |
| Grupo Sodecar |
| Others |
Value Chain & Pricing Dynamics
Captive smelting operations at ALUAR Aluminio Argentino S.A.I.C. anchor both supply security and pricing power for Argentine die-casting foundries, insulating domestic producers from London Metal Exchange volatility while compressing margins for toll-dependent competitors.
Pricing Analysis
Cost-down pressure on Tier-1 suppliers accelerates because Buenos Aires assemblers consolidate procurement leverage across three domestic vehicle plants. Contract-based long-term offtake agreements dominate, with price differentiation tracking certification grade for Mercosur emissions compliance and volume scale for engine block programs. Foundries lacking backward integration into primary aluminium bear the steepest margin compression. Aftermarket distributors show highest price sensitivity; OEM platform engineers least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Toyota and General Motors assembly operations, while Tier-1 intermediaries manage technical integration for Renault-Nissan programs. Feedstock draws from domestic smelters and Brazilian primary aluminium flows through Rosario port logistics. Single-source vulnerability concentrates in high-pressure cell equipment above 4,000-tonne capacity. Distribution runs through Buenos Aires industrial corridor clusters with Córdoba greenfield expansion pending.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive aluminium supply and embedded sensor capability is reshaping competitive positioning, with upstream feedstock control and downstream software bundling as the twin levers separating sustainable margin pools from commodity pressure.
For Market Incumbents: Cement long-term supply agreements by bundling casting-machining-software into single-source contracts that lock out Brazilian import alternatives. Expand high-pressure cell capacity above 6,000-tonne threshold to capture structural battery enclosure demand before Mercosur homologation timelines close the window. Defend against pure-play foundries by embedding predictive maintenance algorithms that generate recurring revenue streams.
For New Entrants and Emerging Players: Tier-2 machining specialists present partnership pathways into Córdoba Province where foundry infrastructure remains underdeveloped and Renault-Nissan structural parts demand outstrips local supply. Target thin-wall die-casting capability for hybrid cooling jacket geometries as the most penetrable technical niche. Lead with Silafont-36 alloy expertise and in-mold temperature monitoring to differentiate from established Buenos Aires competitors.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated Tier-1 automotive suppliers seeking Argentine manufacturing presence for Mercosur local content compliance. Long-term viability favors operators with captive smelting or software-defined thermal management capability. Watch for pending revisions to Mercosur automotive trade rules as the inflection signal determining cost competitiveness of Argentine castings versus Brazilian supply alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminium | Captive smelting at ALUAR insulates margins from LME volatility and secures feedstock for Buenos Aires foundry clusters. |
| Giga-Press Capacity Expansion | 6,000-tonne-plus cells enable structural battery enclosure participation as electric vehicle platforms enter Argentine assembly lines. |
| Software-Defined Thermal Management | Embedded sensor bundles transform hardware margins into recurring revenue streams with Argentine OEM platform engineers. |
| Córdoba Province Greenfield Investment | Underdeveloped foundry infrastructure near Renault-Nissan assembly creates first-mover advantage in structural parts supply. |
| Thin Wall Die Casting Certification | Sub-2.5mm capability for hybrid cooling jackets meets 2026 platform specifications from domestic vehicle assemblers. |
Study Parameters
Document review covered customs and trade data, SEC filings from listed automotive suppliers, and vehicle production databases, complemented by interviews with Tier-1 procurement directors, OEM platform engineers, foundry operations managers, and aftermarket distribution heads. Secondary validation drew from Argentina's national automotive regulator publications, Mercosur technical standard documentation, and central bank import-substitution incentive records. Bottom-up capacity assessments across Buenos Aires, Córdoba, and Santa Fe provinces were triangulated against top-down demand projections from domestic assembly plant output.
Segmentation outputs across product type, end user, manufacturing stage, and technology dimensions were modeled over the projection horizon. CAGRs were derived from production volume trajectories at Toyota, General Motors, Renault, Nissan, Ford, and Volkswagen Argentine facilities, cross-referenced with aluminium content per vehicle assumptions for powertrain and structural applications. Mercosur emissions compliance timelines and local content threshold enforcement patterns served as scenario inputs.
Caveats apply where pending revisions to Mercosur automotive trade rules, primary aluminium price volatility, or giga-press equipment import financing constraints could materially shift the outlook. Forecasts reflect documented assumptions regarding hybrid vehicle platform adoption rates and thin-wall die-casting technology penetration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
Automotive Engine Cooling System Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Struts System Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market