
 VVT and Start-Stop Systems Market | 2026-2036
VVT and Start-Stop Systems Market Size, Share, and Industry Trends Forecast 2026-2036
VVT and Start-Stop Systems Market Outlook
Euro 7 emission standards is realigning the cost-of-entry calculus for powertrain component suppliers across Europe. BorgWarner Inc leverages its cam phaser manufacturing scale to sustain pricing power in gasoline VVT modules. Robert Bosch GmbH anchors its competitive position through integrated start-stop control software bundled with engine management systems. Continental AG competes on thermal management system integration, bundling VVT hardware with coolant valve controls for hybrid platforms.
Variable valve timing and start-stop systems encompass electromechanical actuators, cam phasers, enhanced starter motors, and control modules that modulate engine breathing or halt combustion during idle. These systems reduce fuel consumption and CO2 output by enabling cylinder deactivation, optimized valve overlap, and rapid engine restart within milliseconds. The technology dimension shows Variable Valve Timing occupying the largest installed base while Start-Stop Control captures the fastest replacement cycle in aging European and North American fleets. The application dimension reveals Passenger Vehicles as the dominant revenue pool, though Light Trucks generate higher per-unit content as towing-rated powertrains demand more robust thermal management and dual-battery architectures.
The EPA, Euro 7 framework, and China's MIIT emission directives collectively shape product standards by mandating real-world driving emission tests that expose start-stop durability gaps. NHTSA fuel-economy credits in the United States further steer OEM procurement toward systems with documented idle-reduction performance. Stakeholders must monitor how battery chemistry advances and 48V electrical architectures alter the competitive boundary between conventional start-stop and mild-hybrid systems.
Market Dynamics
EPA fuel-economy benchmarks and Euro 7 emission limits are compressing engineering timelines for powertrain suppliers, forcing simultaneous hardware miniaturization and software integration investments.
Growth Catalysts
- Euro 7 Compliance Deadlines:European OEMs accelerate VVT module procurement to meet real-world driving emission tests that expose start-stop durability gaps in legacy architectures.
- 48V Electrical Architectures:Mild-hybrid platforms in Germany and Japan demand enhanced starter motors with faster restart cycles, expanding addressable hardware content per vehicle.
- Aftermarket Retrofit Mandates:Independent workshops across India retrofit aging gasoline fleets with start-stop modules to satisfy local emission enforcement in Delhi and Mumbai.
Market Restraints
- Neodymium Magnet Cost Volatility:Rare-earth price swings constrain permanent-magnet starter motor production economics, particularly for suppliers without long-term offtake agreements.
- Foundry Capacity Concentration:Cam phaser casting operations cluster in specific Chinese industrial zones, exposing Tier-2 suppliers to localized logistics disruptions.
- High-Voltage Substitution Threat:Full-hybrid and battery-electric powertrains eliminate mechanical valve timing entirely, capping long-term gasoline system demand.
Strategic Opportunities
- Software-Defined Valve Control:Convergence of cam phaser hardware with predictive engine management algorithms creates recurring revenue streams through over-the-air calibration updates.
- Light Truck Thermal Management:Towing-rated powertrains in the United States require dual-battery start-stop architectures with higher per-unit content than passenger car baselines.
- India's Fleet Modernization Incentives:Central government scrappage policies accelerate replacement demand for emission-compliant powertrain components in commercial vehicle segments.
Industry Challenges
- Embedded Systems Integration Complexity:Start-stop control modules must synchronize with legacy engine management protocols across multiple OEM software generations.
- Functional Safety Certification Timelines:ISO 26262 ASIL-D compliance for cam phaser actuators extends validation cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VVT and Start-Stop Systems Market |
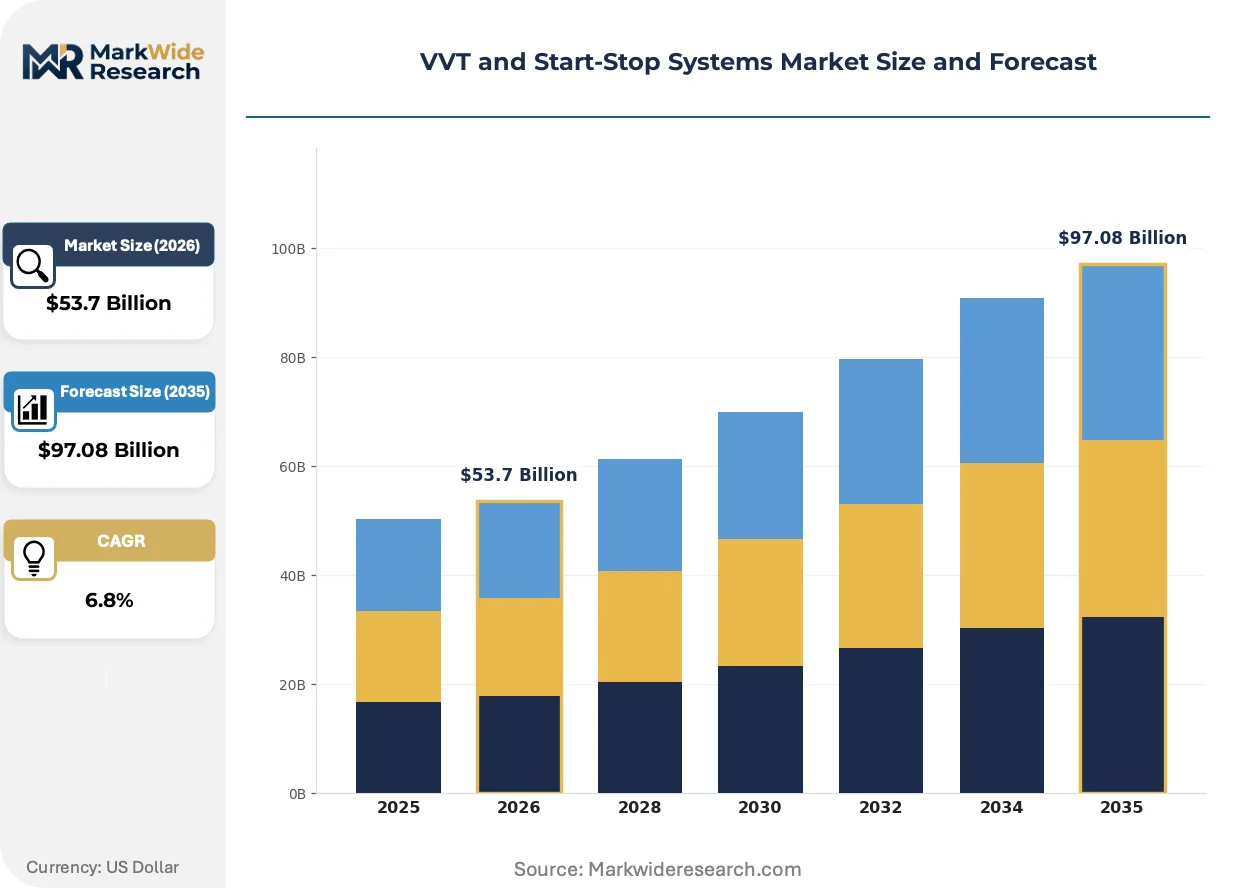
| Market Size in 2026 | $53.7 Billion |
| Market Size in 2035 | $97.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Variable Valve Timing, Cylinder Deactivation, Thermal Management, Start-Stop Control Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Light Trucks End User: OEMs, Aftermarket Providers, Fleet Operators, Independent Workshops Engine Type: Gasoline, Diesel, Hybrid, Electric |
| Companies Covered | BorgWarner Inc, Robert Bosch GmbH, Continental AG, DENSO Corporation, Aisin Seiki Co., Ltd, Valeo S.A, Mitsubishi Electric Corporation, Hitachi, Ltd., Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VVT and Start-Stop Systems Market Strategic Shifts
Electrification of auxiliary systems and predictive control algorithms are redefining the boundary between conventional start-stop and mild-hybrid architectures across gasoline and diesel platforms.
Electromechanical cam phasers with integrated position sensors are expanding into high-volume compact car segments previously served by hydraulic-only systems. Korean and Japanese OEMs specify these modules for turbocharged direct-injection engines where precise valve overlap control mitigates knock at low speeds. The technology is expanding into cost-sensitive vehicle classes by eliminating oil-pressure-dependent actuation delays.
EPA's updated idle-reduction testing protocols now require documented fuel savings under air-conditioning load, a condition that exposes starter motor durability gaps in hot-climate operation. The regulation forces suppliers to validate enhanced thermal management in battery and motor windings. US light truck manufacturers respond by specifying dual-battery architectures that isolate start-stop loads from infotainment and lighting circuits.
Fleet procurement departments now unbundle start-stop hardware from engine management system contracts, creating direct sourcing relationships with cam phaser specialists. Tier-1 integrators in Germany and the United States lose exclusivity on powertrain electronics as OEMs seek component-level cost transparency. The shift is most visible in commercial vehicle segments where lifecycle cost modeling drives purchasing decisions.
VVT and Start-Stop Systems Market Segmentation
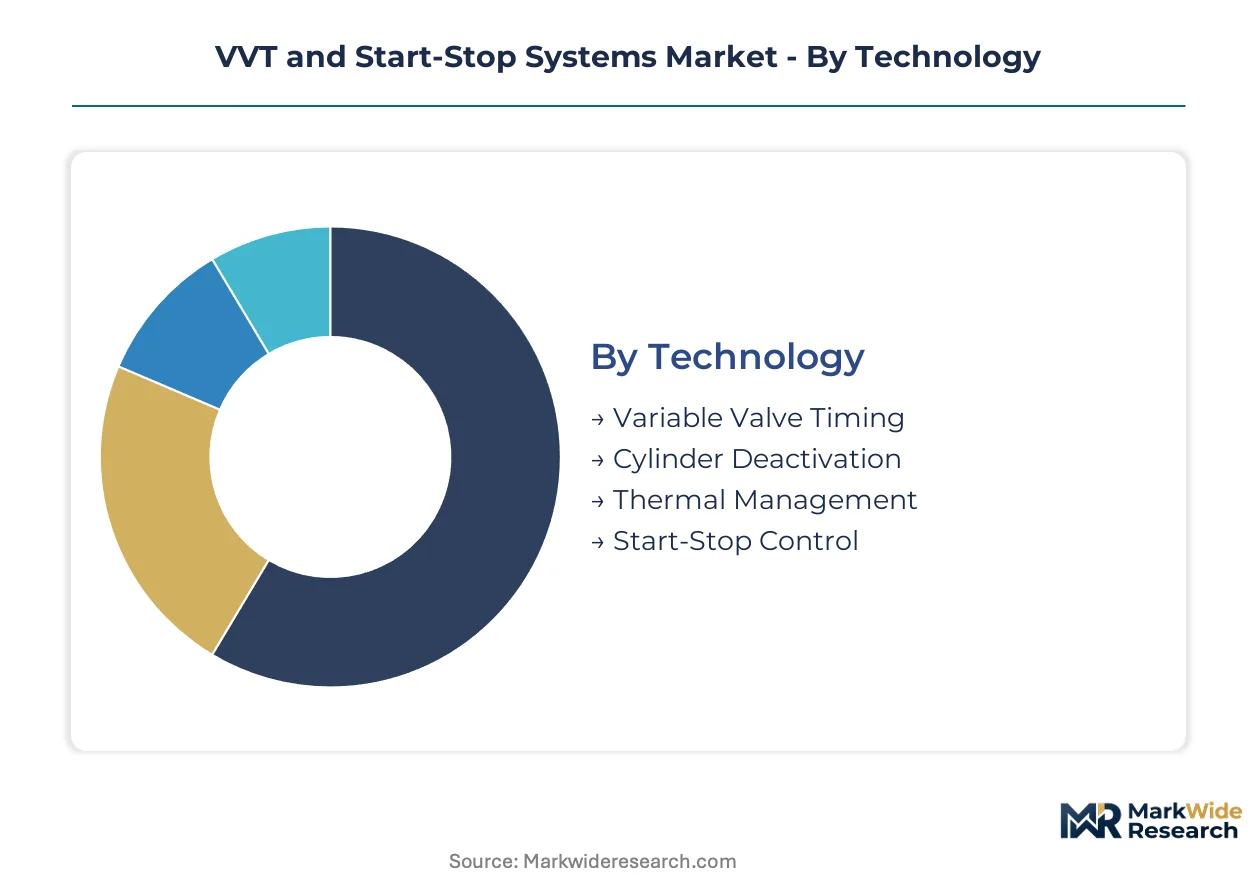
Powertrain component suppliers configure production assets around technology complexity and regulatory exposure. Segment boundaries in this market reflect divergent capital requirements, certification timelines, and aftermarket retrofit potential across gasoline, diesel, and electrified platforms.
Technology:
Variable Valve Timing demands the heaviest upfront tooling investment due to precision cam phaser machining and sensor integration requirements.
- Variable Valve Timing:Electromechanical and hydraulic cam phasers modulate intake and exhaust valve events to optimize engine breathing across RPM ranges. German and Japanese OEMs specify these modules for turbocharged direct-injection engines where precise valve overlap mitigates knock at low speeds. EPA fuel-economy benchmarks and Euro 7 emission limits compress engineering timelines, forcing simultaneous hardware miniaturization and software integration investments.
- Start-Stop Control:Enhanced starter motors and control modules halt combustion during idle and restart engines within milliseconds. Fleet procurement departments in the United States now unbundle this hardware from engine management system contracts, creating direct sourcing relationships with cam phaser specialists as OEMs seek component-level cost transparency.
- Cylinder Deactivation:Selective fuel and valve cutoff for partial engine operation during light-load cruising.
- Thermal Management:Coolant valve controls and heat exchangers that stabilize powertrain temperatures across start-stop cycles.
Variable Valve Timing absorbs the bulk of installed capacity; Start-Stop Control is expanding most quickly.
Application:
Light Trucks generate the highest per-unit hardware content due to dual-battery architectures and towing-rated thermal management requirements.
- Passenger Vehicles:High-volume compact and mid-size platforms drive baseline demand for cost-optimized VVT modules. Korean OEMs specify electromechanical cam phasers with integrated position sensors for turbocharged engines, expanding the technology into cost-sensitive vehicle classes by eliminating oil-pressure-dependent actuation delays.
- Light Trucks:Towing-rated powertrains in the United States require robust thermal management and dual-battery start-stop architectures with higher per-unit content than passenger car baselines. EPA's updated idle-reduction testing protocols now require documented fuel savings under air-conditioning load, forcing suppliers to validate enhanced thermal management in battery and motor windings.
- Commercial Vehicles:Heavy-duty cycles prioritize durability over restart speed in start-stop implementations.
- Motorcycles:Compact packaging constraints favor simplified VVT mechanisms with reduced actuator count.
Passenger Vehicles anchor current volume; Light Trucks command the steepest expansion trajectory in content-per-vehicle terms.
End User:
OEMs concentrate procurement of integrated engine management systems while aftermarket channels capture retrofit demand in emission-regulated urban centers.
- OEMs:Vehicle manufacturers specify complete powertrain electronics packages with embedded start-stop control software. Tier-1 integrators in Germany and the United States face eroding exclusivity as OEMs unbundle component sourcing to improve cost transparency.
- Independent Workshops:Repair facilities across India retrofit aging gasoline fleets with start-stop modules to satisfy local emission enforcement in Delhi and Mumbai. Central government scrappage policies accelerate replacement demand for emission-compliant powertrain components in commercial vehicle segments.
- Aftermarket Providers:Distributors supply replacement cam phasers and control modules for out-of-warranty vehicles.
- Fleet Operators:Commercial and rental fleets negotiate direct component sourcing based on lifecycle cost modeling.
OEMs dominate value capture; Independent Workshops are gaining share fastest in retrofit-intensive geographies.
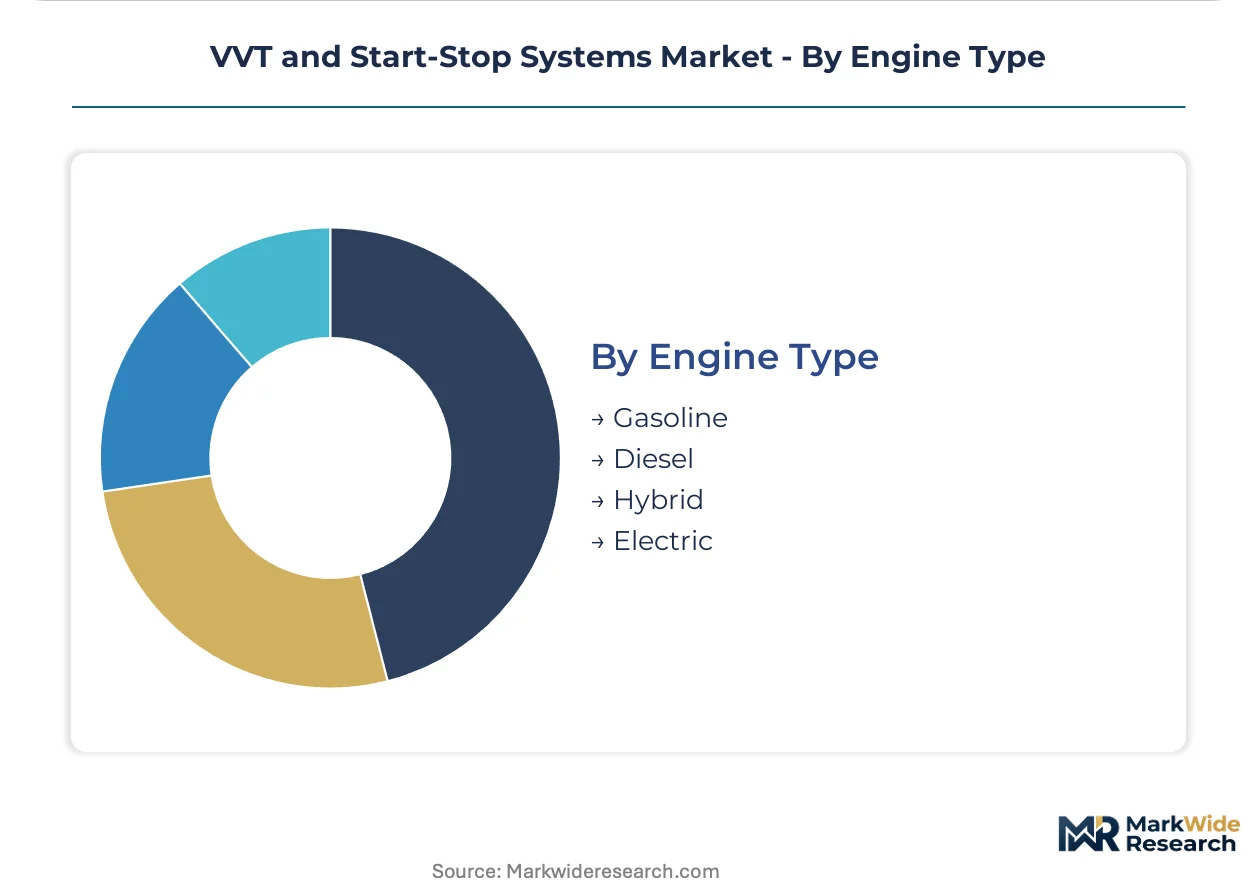
Engine Type:
Gasoline powertrains require the most sophisticated VVT hardware to manage knock and emissions across variable load conditions.
- Gasoline:Direct-injection turbocharged engines depend on precise cam phaser control to balance performance and efficiency. Electromechanical actuation eliminates oil-pressure-dependent delays, enabling expansion into high-volume compact segments previously served by hydraulic-only systems.
- Hybrid:Mild-hybrid platforms in Germany and Japan demand enhanced starter motors with faster restart cycles, expanding addressable hardware content per vehicle as 48V electrical architectures proliferate.
- Diesel:Compression-ignition engines utilize simplified VVT for EGR flow management and particulate filter regeneration timing.
- Electric:Battery-electric powertrains eliminate mechanical valve timing entirely, capping long-term addressable market for conventional VVT suppliers.
Gasoline retains the dominant installed base; Hybrid configurations are climbing the fastest as electrification intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive component manufacturing clusters concentrate in designated special economic zones where tax incentives for capital-intensive tooling anchor supplier ecosystems. EPA benchmarks in the United States, Euro 7 deadlines in Europe, and MIIT directives in China compress procurement timelines across these zones.
United States
Light truck manufacturers in Michigan and Texas drive dual-battery start-stop procurement for towing-rated powertrains. NHTSA fuel-economy credits steer OEM sourcing toward idle-reduction systems with documented air-conditioning load performance. Detroit-Warren-Dearborn MSA hosts Tier-1 integrators unbundling component contracts to improve cost transparency.
Germany
Mild-hybrid platforms from Stuttgart and Munich OEMs demand enhanced starter motors compatible with 48V architectures. KBA enforces real-world driving emission tests that expose durability gaps in legacy start-stop implementations. Baden-Württemberg's supplier corridor specializes in electromechanical cam phasers with integrated position sensors.
China
Domestic OEMs in Shanghai and Guangzhou accelerate VVT module adoption to satisfy MIIT emission directives on gasoline direct-injection engines. Foundry capacity for cam phaser castings clusters in specific industrial zones, exposing Tier-2 suppliers to localized logistics disruptions. Yangtze River Delta plants retrofit aging fleets for export markets.
Japan
Tokyo and Nagoya-based manufacturers specify precision valve overlap control for turbocharged engines to mitigate knock at low speeds. METI standards coordinate with Euro 7 testing protocols to harmonize validation requirements. Kanto region suppliers integrate predictive engine management algorithms with cam phaser hardware.
India
Independent workshops in Delhi and Mumbai retrofit gasoline fleets with start-stop modules to satisfy local emission enforcement. Central government scrappage policies accelerate replacement demand for compliant powertrain components. Tamil Nadu's automotive belt concentrates aftermarket distribution for commercial vehicle segments.
VVT and Start-Stop Systems Market Competitive Environment
German and Japanese producers anchor one tier with integrated engine management systems; American specialists hold positions in thermal management and light truck applications. The supplier base organizes around three strategic archetypes: full-system integrators bundling hardware with control software, component specialists focusing on cam phaser machining precision, and aftermarket distributors serving retrofit demand. Dominant competitive moves include geographic expansion into designated automotive zones and technology licensing arrangements for 48V-compatible architectures.
Within the full-system integrator tier, BorgWarner Inc, Robert Bosch GmbH, and Continental AG exemplify contrasting approaches to sustaining pricing power. BorgWarner occupies a position tied to manufacturing scale in gasoline VVT modules. Bosch represents the software-anchored model through bundled engine management systems. Continental sits within the thermal management specialization, integrating coolant valve controls for hybrid platforms. These three entities collectively illustrate how European and American suppliers defend margin positions against Asian competitors in emission-critical powertrain electronics.
| Leading Market Players |
|---|
| BorgWarner Inc |
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Aisin Seiki Co., Ltd |
| Valeo S.A |
| Mitsubishi Electric Corporation |
| Hitachi, Ltd. |
| Aptiv PLC |
| Others |
Value Chain & Pricing Dynamics
Neodymium magnet procurement costs cascade through permanent-magnet starter motor production economics, compressing margins for suppliers lacking long-term offtake agreements while amplifying pricing power for integrated rare-earth processors serving German and Japanese OEMs.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with 8-14 week delivery windows commanding 15-25% markups over spot inventory held in regional distribution centers. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified cam phaser modules from automotive-grade baselines and commercial-vehicle retrofit kits. Cost compression in economy tiers is intensifying because Chinese foundry capacity expansion outpaces Euro 7 certification throughput. Fleet procurement departments exhibit lowest price sensitivity due to lifecycle cost modeling, while independent workshops in India face acute margin pressure from emission enforcement deadlines.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit-Warren-Dearborn, and Shanghai anchor hub-and-spoke fulfillment patterns for cam phaser castings and electromechanical actuator assemblies. Manufacturing concentrates in Germany, China, and Japan, with foundry operations clustering in Yangtze River Delta industrial zones exposing Tier-2 suppliers to localized logistics disruptions. Permanent-magnet starter motors draw from neodymium-dysprosium-terbium supply chains concentrated in Chinese processing facilities. Single-source vulnerability in rare-earth separation capacity represents the dominant structural risk. Distribution runs through OEM Tier-1 integrators unbundling component contracts and direct aftermarket channels serving retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 compliance deadlines and 48V architecture transitions are forcing simultaneous hardware and software investments that weaker capitalized suppliers cannot absorb, creating consolidation pressure across European and North American powertrain electronics.
For Market Incumbents: Deploy backward integration into rare-earth magnet supply chains to neutralize neodymium price volatility threatening permanent-magnet starter motor economics. Anchor capacity expansion in Baden-Württemberg and Michigan to capture light truck dual-battery procurement growth while ISO 26262 ASIL-D certification investments create switching costs against emerging Asian competitors. For New Entrants and Emerging Players: Launch via direct component sourcing relationships with commercial fleet operators unbundling start-stop hardware from engine management contracts. Target India's aftermarket retrofit segment where central government scrappage policies accelerate replacement demand for emission-compliant powertrain components in Delhi and Mumbai commercial vehicle segments. For Investors and Strategic Acquirers: OEM unbundling of Tier-1 integrator contracts is the leading indicator that component-level specialists with cam phaser machining precision and predictive control software capabilities will command acquisition premiums. Focus on mid-cap suppliers with captive foundry relationships and 48V-compatible architecture licenses, watching for KBA enforcement actions exposing durability gaps in legacy start-stop implementations as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Valve Control Integration | Over-the-air calibration updates create recurring revenue streams for Bosch and Continental. |
| 48V Architecture Manufacturing Footprint | Enhanced starter motor capacity in Germany and Japan captures mild-hybrid platform demand. |
| Thermal Management System Partnership | Dual-battery architectures for US light trucks bundle VVT hardware with coolant valve controls. |
| Backward Integration into Rare-Earth Supply | Long-term offtake agreements with Chinese processors neutralize magnet cost volatility. |
| Aftermarket Distribution Channel Expansion | Independent workshops in India retrofit aging fleets to satisfy MIIT and local emission mandates. |
Study Parameters
Multi-period observation of EPA fuel-economy credit allocations, Euro 7 enforcement timelines, and MIIT emission directive implementation anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors in India, and thermal management system specialists. Secondary validation drew from NHTSA regulatory filings, KBA real-world driving test protocols, vehicle production databases, and SEC disclosures from powertrain component manufacturers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting applied technology complexity coefficients to Variable Valve Timing, Start-Stop Control, Cylinder Deactivation, and Thermal Management categories, with cross-referencing to propulsion architecture penetration rates and content-per-vehicle estimates for passenger vehicles versus light trucks. CAGRs were derived from installed base projections and replacement cycle analysis. Forecast inputs included battery chemistry advancement trajectories and 48V electrical architecture adoption curves.
Rare-earth price volatility, foundry capacity disruptions, and high-voltage substitution acceleration are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Vehicle Aluminum Die Casting Parts Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Power Liftgate Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
Brake Pad Market
Automotive Parts
Iran Automotive Engine Oils Market