
 Thailand Passenger Vehicles Lubricants Market | 2026-2036
Thailand Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Passenger Vehicles Lubricants Market Analytics
API SP and ILSAC GF-6 formulation standards is tilting blender investment toward lower-viscosity, fuel-efficient base stocks. Chevron Corporation leverages its Thailand blending facility to supply high-performance synthetics to domestic assemblers. BP PLC (Castrol) anchors its position through authorized service networks tied to Japanese OEM dealerships. PTT Lubricants dominates state-linked fleet procurement through backward integration into Group II/III base oil production at its Rayong complex.
Thailand passenger vehicles lubricants comprise formulated fluids engineered to reduce friction, transfer heat, and prevent wear in internal combustion and hybrid powertrains, with viscosity grades typically spanning 0W-16 to 10W-40 and additive packages containing detergents, dispersants, and anti-wear compounds such as zinc dialkyldithiophosphate. Engine Oil commands the largest volume pool given drain-interval frequency, though Synthetic formulations within the Performance Grade dimension capture disproportionate margin as Thai consumers extend service intervals and OEMs specify tighter tolerances. The Aftermarket channel in Distribution Channel segmentation absorbs the bulk of volume, yet Online platforms are gaining traction among younger vehicle owners in Greater Bangkok seeking price transparency and home-delivery convenience.
Thailand's Department of Industrial Works enforces waste oil handling permits under the Factory Act, while the Thai Industrial Standards Institute (TISI) mandates TIS 2612-2553 compliance for automotive lubricant labeling and performance claims. These frameworks elevate compliance costs for informal blenders while creating technical barriers that favor established players with in-house testing laboratories. Stakeholders must monitor whether Thailand's Board of Investment extends tax incentives for domestic base oil refining as electric vehicle penetration reshapes lubricant demand composition.
Market Dynamics
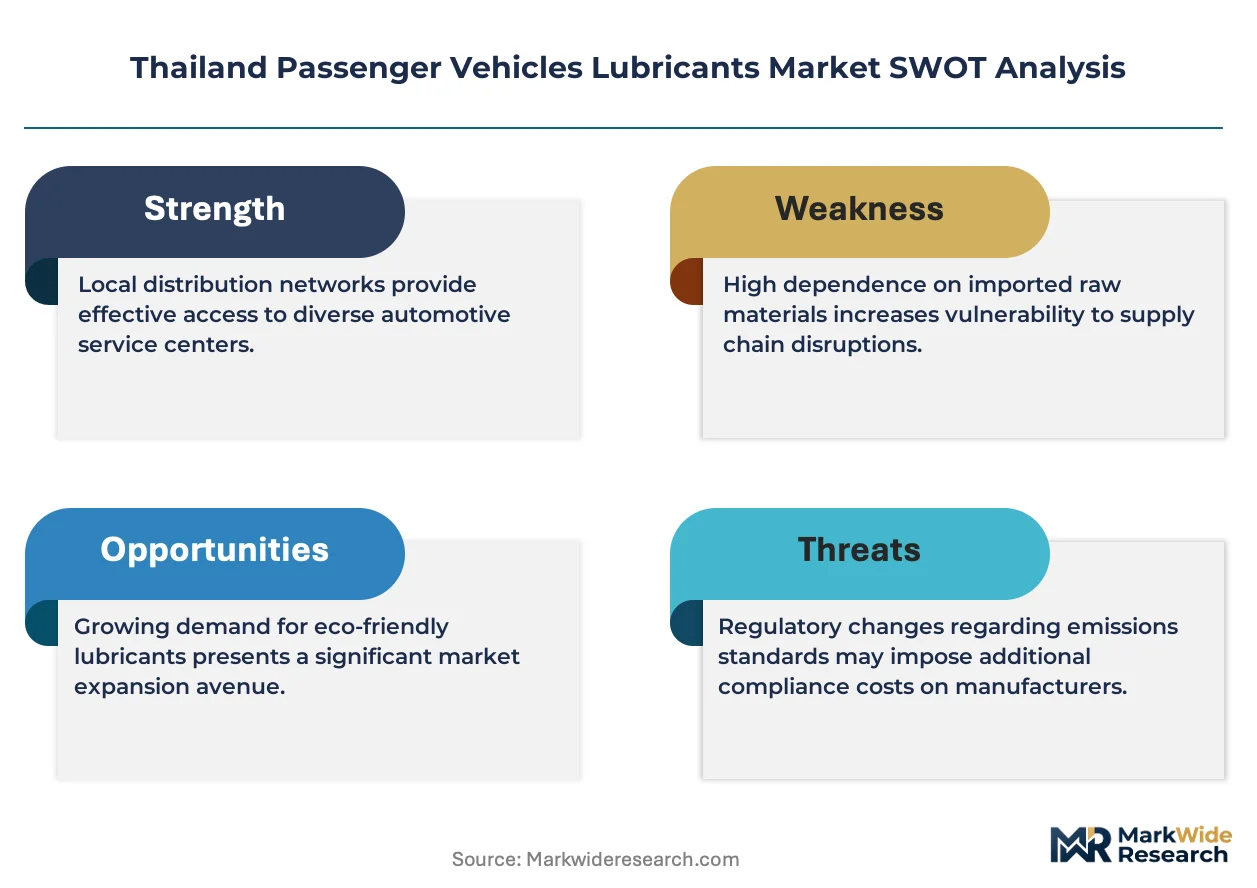
Thailand's Department of Industrial Works is tightening waste oil disposal enforcement under the Factory Act, forcing fleet operators and service networks to accelerate synthetic lubricant adoption and extend drain intervals while maintaining compliance documentation.
Growth Catalysts
- Factory Act Waste Oil Rules:Bangkok-based fleet operators face escalating permit costs for used lubricant handling, driving procurement toward longer-life synthetics that reduce disposal frequency.
- Hybrid Powertrain Density:Japanese OEM assemblers in the Central Plains corridor now specify lower-viscosity grades for turbocharged hybrid engines, expanding addressable synthetic volume.
- Rayong Base Oil Complex:Captive Group II/III production capacity enables domestic blenders to offset import dependency and shorten formulation-to-delivery lead times.
Market Restraints
- Group III Base Oil Import Concentration:Thai blenders remain exposed to Northeast Asian refinery output swings and freight rate volatility for high-viscosity-index feedstocks.
- TISI 2612-2553 Testing Burden:In-house laboratory certification requirements for performance claims create fixed cost barriers that informal blenders cannot absorb.
- Battery Electric Vehicle Displacement:Reduced friction points in full-electric powertrains threaten long-term engine oil demand intensity per vehicle-mile.
Strategic Opportunities
- Eastern Economic Corridor Fleet Electrification:Hybrid and plug-in hybrid commercial fleets in Chonburi and Rayong provinces require dedicated transmission and thermal management fluids distinct from conventional engine oils.
- Online Direct-to-Consumer Channels:Younger vehicle owners in Greater Bangkok bypass traditional service networks for price-transparent home delivery of packaged lubricants.
- Board of Investment Refining Incentives:Potential tax relief for domestic base oil capacity expansion would strengthen backward-integrated supply positions against import-reliant competitors.
Industry Challenges
- API SP/GF-6 Formulation Expertise Gap:Local blenders struggle to recruit chemists capable of balancing lower-viscosity base stocks with protective additive packages for GDI engines.
- Legacy Service Network Integration:Authorized Japanese OEM dealerships resist adopting third-party synthetic products despite superior drain-interval economics, protecting tied-house lubricant arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Passenger Vehicles Lubricants Market |
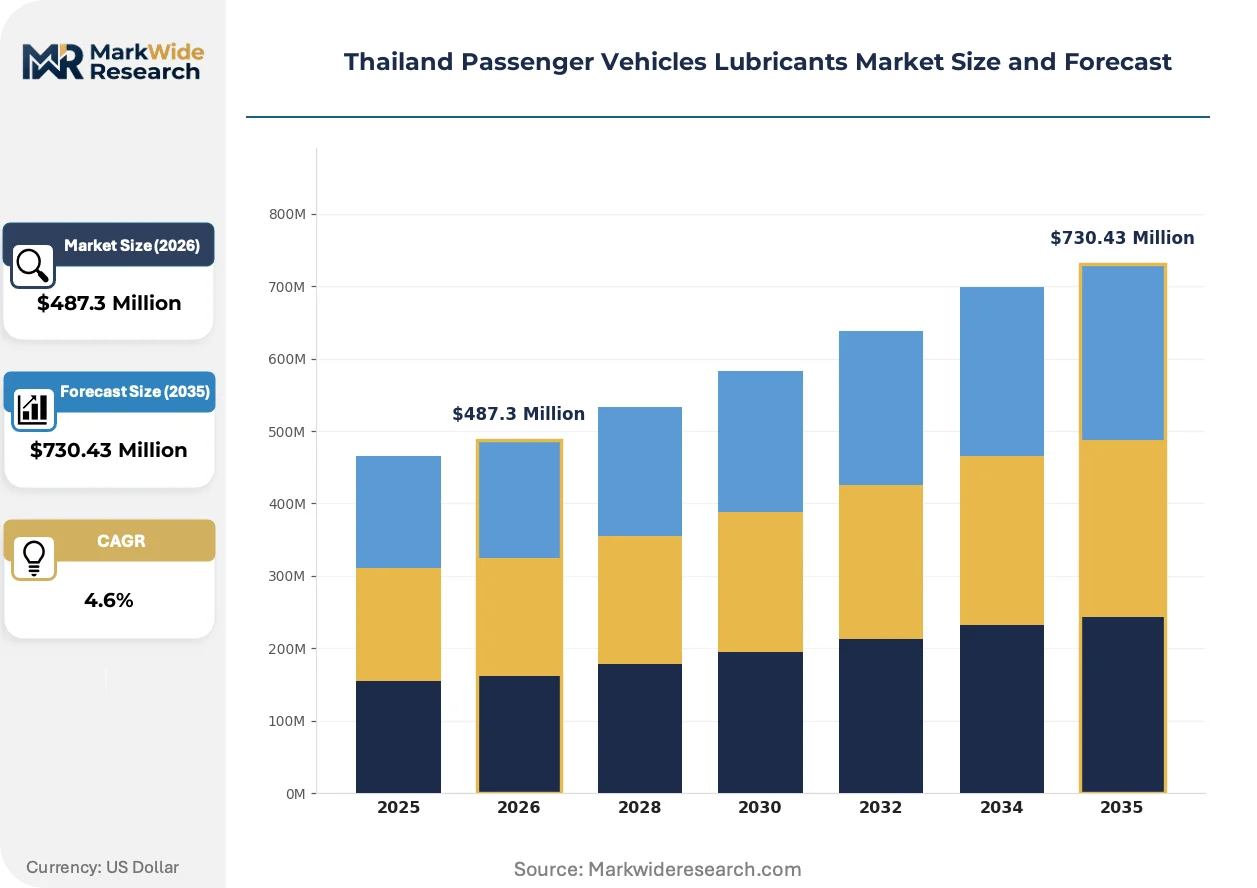
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Vehicle Type: Sedan, SUV, Hatchback, Coupe Performance Grade: Synthetic, Semi-Synthetic, Mineral, API Certified Distribution Channel: Retail, Online, Wholesale, Aftermarket |
| Companies Covered | Chevron Corporation, BP PLC (Castrol), Bangchak Corporation, Idemitsu Kosan Co Ltd, ENEOS Corporation, Royal Dutch Shell Plc, ExxonMobil Corporation, Siam Pan Group Public Co Ltd, PTT Lubricants, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Passenger Vehicles Lubricants Market Evolving Landscape
Digital diagnostic tools and predictive maintenance platforms are rewiring how Thai fleet managers specify and procure lubricants, compressing traditional specification cycles and elevating performance data over brand loyalty.
Condition-based monitoring systems using IoT sensors and cloud analytics are digitizing lubricant procurement decisions for Bangkok commercial fleets. Large operators now track oil degradation in real time rather than adhering to fixed mileage schedules. This capability is digitizing the aftermarket channel, forcing distributors to stock flexible SKU ranges and provide technical support rather than volume discounts alone.
Thailand's Department of Industrial Works is extending Factory Act enforcement to smaller service garages previously exempt from waste oil permitting. The regulation now mandates chain-of-custody documentation from drain to disposal. Independent workshops in Nonthaburi and Pathum Thani provinces are consolidating into authorized networks to share compliance infrastructure costs.
Younger vehicle owners in Greater Bangkok are abandoning bundled service packages at dealerships for unbundled maintenance sourcing. These buyers research viscosity grades and additive specifications independently, then purchase lubricants through e-commerce platforms for third-party installation. This pattern concentrates in the 25-40 age segment owning Japanese compact sedans and hybrid crossovers.
Thailand Passenger Vehicles Lubricants Market Segmentation
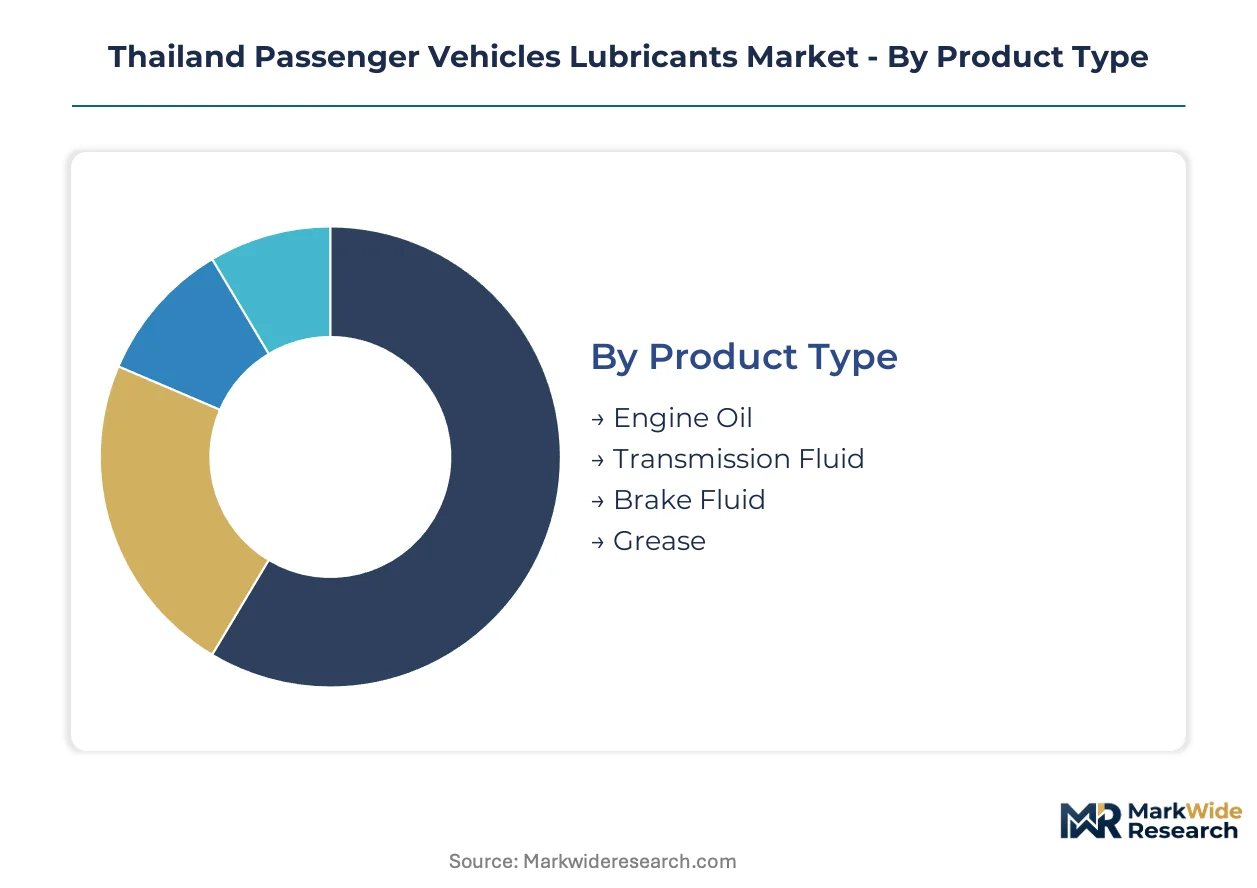
Thailand's passenger vehicle lubricants market fragments across four distinct dimensions that shape procurement patterns and margin structures. Each segmentation axis reveals divergent growth trajectories tied to powertrain evolution, regulatory compliance burdens, and channel digitization.
Product Type:
Mature formulations coexist with emerging fluid categories as powertrain complexity diversifies lubricant requirements.
- Engine Oil:Formulated fluids containing base stocks and additive packages reduce friction, transfer heat, and prevent wear in internal combustion and hybrid powertrains. Bangkok fleet operators concentrate procurement here due to drain-interval frequency, though synthetic formulations capture disproportionate margin as Thai consumers extend service intervals. Bangkok-based fleet operators face escalating permit costs for used lubricant handling under tightened Factory Act enforcement, driving procurement toward longer-life synthetics that reduce disposal frequency.
- Transmission Fluid:Specialized lubricants engineered for gear protection and thermal stability in automatic, CVT, and dual-clutch transmissions. Demand concentrates in the Central Plains corridor where Japanese OEM assemblers now specify dedicated formulations for hybrid powertrains. Eastern Economic Corridor fleet electrification in Chonburi and Rayong provinces requires transmission and thermal management fluids distinct from conventional engine oils.
- Brake Fluid:Hygroscopic hydraulic fluids meeting DOT 3, DOT 4, or DOT 5.1 specifications for brake system operation. Service networks in Greater Bangkok standardize on higher-grade formulations to reduce moisture absorption risks in tropical humidity.
- Grease:Semi-solid lubricants thickened with metallic soaps for chassis, wheel bearing, and auxiliary component protection. Independent workshops in Nonthaburi and Pathum Thani provinces consolidate into authorized networks to share compliance infrastructure costs for waste handling.
Engine Oil retains volume leadership; Transmission Fluid holds the steepest expansion curve as hybrid powertrain density climbs.
Vehicle Type:
Cost tier differentiation separates mass-market maintenance from premium service specifications.
- Sedan:Three-box passenger cars dominating Thailand's fleet composition with standardized lubricant requirements. Bangkok commercial fleets deploy condition-based monitoring systems using IoT sensors and cloud analytics, digitizing procurement decisions and compressing traditional specification cycles.
- SUV:Sport utility vehicles with elevated torque demands and all-wheel-drive transfer case requirements. Japanese OEM assemblers in the Central Plains corridor specify lower-viscosity grades for turbocharged hybrid engines, expanding addressable synthetic volume.
- Hatchback:Compact two-box vehicles with smaller sump capacities and more frequent drain intervals. Younger vehicle owners in the 25-40 age segment owning Japanese compact sedans and hybrid crossovers research viscosity grades independently and purchase through e-commerce platforms for third-party installation.
- Coupe:Performance-oriented two-door vehicles requiring high-shear-stability lubricants for spirited driving profiles. Authorized Japanese OEM dealerships resist adopting third-party synthetic products despite superior drain-interval economics, protecting tied-house lubricant arrangements.
Sedan commands the volume base; SUV generates the premium pricing differential.
Performance Grade:
Margin stratification intensifies as formulation standards elevate technical barriers.
- Synthetic:Chemically engineered base stocks with uniform molecular structure delivering extended drain intervals and thermal stability. API SP and ILSAC GF-6 formulation standards tilt blender investment toward lower-viscosity, fuel-efficient base stocks. Local blenders struggle to recruit chemists capable of balancing lower-viscosity base stocks with protective additive packages for GDI engines.
- Semi-Synthetic:Blended formulations combining synthetic and mineral base stocks for mid-tier performance positioning. PTT Lubricants dominates state-linked fleet procurement through backward integration into Group II/III base oil production at its Rayong complex.
- Mineral:Refined petroleum-derived base stocks with lower cost positioning and shorter service intervals. Thai blenders remain exposed to Northeast Asian refinery output swings and freight rate volatility for high-viscosity-index feedstocks.
- API Certified:Formulations meeting American Petroleum Institute performance standards for quality assurance. TISI 2612-2553 testing burden creates fixed cost barriers that informal blenders cannot absorb, elevating compliance costs and favoring established players with in-house testing laboratories.
Synthetic captures the margin premium; API Certified gains regulatory momentum.
Distribution Channel:
Channel geography separates legacy infrastructure from digital disruption zones.
- Retail:Branded outlets and automotive parts stores serving walk-in consumers with immediate fulfillment. Service infrastructure overlaps most densely in the Central Plains corridor where passenger vehicle density concentrates.
- Online:E-commerce platforms and direct-to-consumer digital channels. Younger vehicle owners in Greater Bangkok bypass traditional service networks for price-transparent home delivery of packaged lubricants.
- Wholesale:Bulk supply arrangements for fleet operators and institutional buyers. Distributors must stock flexible SKU ranges and provide technical support rather than volume discounts alone as digitization compresses specification cycles.
- Aftermarket:Independent service networks and third-party installation facilities. The Department of Industrial Works extends Factory Act enforcement to smaller service garages previously exempt from waste oil permitting, mandating chain-of-custody documentation from drain to disposal.
Aftermarket retains volume leadership; Online demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand exports finished lubricants and base oils to neighboring ASEAN markets, with Myanmar, Cambodia, and Laos serving as primary destination corridors for packaged passenger vehicle products.
Bangkok Metropolitan Region
Fleet electrification and hybrid powertrain density concentrate lubricant demand sophistication in Bangkok and surrounding provinces. The Department of Industrial Works enforces waste oil disposal permits under the Factory Act, elevating compliance costs for independent service garages. Urban fleet operators in Nonthaburi and Pathum Thani are consolidating into authorized networks to share documentation infrastructure.
Central Plains Corridor
Japanese OEM assemblers specify lower-viscosity synthetic grades for turbocharged hybrid engines across Ayutthaya, Chonburi, and Rayong manufacturing clusters. The Thai Industrial Standards Institute mandates TIS 2612-2553 compliance for automotive lubricant labeling and performance claims. PTT Lubricants leverages captive Group II/III base oil production at its Rayong complex to supply domestic blenders.
Eastern Economic Corridor
Commercial fleet electrification in Chonburi and Rayong provinces generates demand for dedicated transmission and thermal management fluids distinct from conventional engine oils. The Board of Investment considers tax incentives for domestic base oil refining capacity expansion. Hybrid and plug-in hybrid logistics operators require specialized lubricant procurement protocols.
Northern Region
Chiang Mai and Chiang Rai service networks face delayed synthetic adoption due to lower vehicle turnover and extended mineral oil drain intervals. Provincial environmental offices are beginning to coordinate with Bangkok on Factory Act enforcement harmonization. Independent workshops in secondary cities lack capital for in-house testing laboratory certification.
Southern Region
Tourism-dependent vehicle fleets in Phuket, Krabi, and Surat Thani prioritize rapid-turn maintenance over extended-drain synthetic formulations. Coastal humidity accelerates brake fluid degradation, driving service standardization toward higher DOT specifications. Regional distributors maintain larger grease inventories for chassis protection in salt-air environments.
Thailand Passenger Vehicles Lubricants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where backward-integrated energy majors hold procurement advantages in state-linked fleet segments. The market fragments between multinational blenders with captive base oil supply and domestic formulators dependent on imported Group III feedstocks. Three archetypes dominate: integrated oil companies with refining assets, authorized OEM service network operators, and independent distributors serving aftermarket channels. Competitive moves center on synthetic formulation capability acquisition and compliance infrastructure consolidation.
Among integrated energy majors, Chevron Corporation, BP PLC (Castrol), and PTT Lubricants occupy positions defined by supply chain control depth. Chevron leverages its Thailand blending facility to anchor high-performance synthetic supply to domestic assemblers. BP PLC (Castrol) exemplifies the OEM-tied service network archetype through authorized arrangements with Japanese dealership channels. PTT Lubricants represents backward-integrated domestic competitiveness via captive base oil production at Rayong. These three entities illustrate how feedstock security, distribution channel alignment, and regulatory compliance capacity separate market tiers.
| Leading Market Players |
|---|
| Chevron Corporation |
| BP PLC (Castrol) |
| Bangchak Corporation |
| Idemitsu Kosan Co Ltd |
| ENEOS Corporation |
| Royal Dutch Shell Plc |
| ExxonMobil Corporation |
| Siam Pan Group Public Co Ltd |
| PTT Lubricants |
| Others |
Value Network & Pricing Analysis
The Laem Chabang–Bangkok freight corridor anchors Thailand's lubricant cost structure, with container rates from Northeast Asian refineries feeding directly into blender margins and downstream price stratification across synthetic, semi-synthetic, and mineral tiers.
Pricing Analysis
Cost-plus contracts indexed to Singapore Group II/III base oil quotations dominate procurement between blenders and fleet operators. Price differentiation hinges on TISI 2612-2553 certification grade and volume scale, with state-linked fleets securing preferential terms through backward-integrated supply. Cost compression in the mineral tier is intensifying because informal blenders cannot absorb laboratory certification fixed costs. Independent workshops in provincial markets exhibit highest price sensitivity; OEM-authorized networks show lowest sensitivity due to tied-house lubricant arrangements.
Supply Chain Analysis
Upstream feedstock security centers on Group II/III base oil availability from South Korea, Singapore, and Thailand's domestic Rayong complex. Thai blenders draw from paraffinic crude derivatives, additive packages containing zinc dialkyldithiophosphate, and viscosity modifier polymers. Single-source vulnerability concentrates in high-viscosity-index Group III imports from Northeast Asian refineries. Distribution runs through authorized OEM service networks, independent aftermarket garages, and emerging direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's passenger vehicle lubricants market functions as a service-attach opportunity where fluid analysis subscriptions and predictive maintenance contracts expand faster than packaged product sales alone.
For Market Incumbents: Entrench compliance infrastructure advantages by consolidating waste oil documentation networks ahead of full Factory Act enforcement extension to provincial garages. Deepen captive base oil positions through Rayong complex capacity optimization against import-dependent competitors. Battery electric vehicle displacement threat demands accelerated thermal management fluid formulation pipelines. For New Entrants and Emerging Players: Build out digital-first distribution targeting the 25-40 age segment in Greater Bangkok with home-delivery synthetic lubricants and third-party installation partnerships. The online direct-to-consumer channel offers lowest entry barriers against entrenched OEM-tied networks. Lead with price transparency and viscosity grade education to capture unbundled maintenance sourcing behavior. For Investors and Strategic Acquirers: Regional blenders with in-house TISI testing laboratories and Eastern Economic Corridor logistics access represent the most defensible acquisition archetype. Long-term viability hinges on hybrid powertrain fluid complexity sustaining per-vehicle content against full electrification. Watch Board of Investment tax incentive announcements for domestic base oil refining as the signal for supply-side consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive Group II/III supply at Rayong insulates PTT Lubricants from Northeast Asian freight volatility. |
| Digital Diagnostic Platform Deployment | IoT-enabled condition monitoring compresses drain intervals and elevates technical service over commodity volume. |
| Authorized Service Network Consolidation | Factory Act waste oil compliance costs force independent Nonthaburi and Pathum Thani workshops into shared documentation infrastructure. |
| Synthetic Formulation Capability Acquisition | API SP/GF-6 expertise gaps among local blenders create talent arbitrage opportunities for specialized chemist recruitment. |
| E-commerce Channel Expansion | Direct-to-consumer platforms capture unbundled maintenance sourcing from younger vehicle owners seeking price transparency. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with lubricant blend plant managers, fleet procurement officers at Bangkok-based logistics operators, aftermarket service network owners, and Thai Industrial Standards Institute certification auditors. Secondary validation drew from customs import records for base oil feedstocks, Department of Industrial Works Factory Act enforcement circulars, vehicle registration databases from the Department of Land Transport, and SEC filings from listed energy majors. Bottom-up volume triangulation across product type, performance grade, and distribution channel segments was cross-checked against top-down market value reconstruction.
Calibration against historical base oil price volatility and hybrid powertrain penetration curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, vehicle class, performance tier, and channel geography alongside propulsion architecture evolution. CAGRs were derived from slope analysis of segment-level volume trajectories. Key inputs encompassed drain interval extension rates for synthetic formulations and Eastern Economic Corridor fleet electrification timelines.
Stress conditions across Group III import price spikes, accelerated battery electric vehicle adoption, and Factory Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hybrid powertrain lubricant content persistence and regulatory compliance cost pass-through. Material shifts in Board of Investment incentive structures or OEM synthetic specification mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Gear Box and Gear Motors Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Automotive Washer System Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Tire Mold Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Smart Adaptive Headlights Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Egypt Automotive Engine Oils Market