
 Tire Retreading Market | 2026-2036
Tire Retreading Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Retreading Market Intelligence
The ECE Regulation 109 for commercial vehicle tire retreading is collapsing the distinction between premium new tires and high-quality retreads. Michelin SCA leverages its extensive network of Bandag-franchised dealers to ensure consistent quality standards across different geographies. Bridgestone Corporation competes on the durability of its tire casings, which are engineered for multiple retreading cycles. In contrast, Continental AG differentiates through its ContiRe brand, offering integrated fleet management solutions alongside its retreaded products.
Tire retreading is a remanufacturing process that replaces the worn tread on a qualified, inspected tire casing. The process involves buffing the old tread away, applying a new tread compound, and vulcanizing it under heat and pressure, typically through pre-cure or mold cure methods. The truck & bus application segment commands the largest market share, driven by the economic imperative for logistics operators to lower total cost of ownership. Among service types, independent retreaders hold a significant position, though original equipment manufacturer networks are expanding their footprint.
In the United States, the Environmental Protection Agency (EPA) indirectly supports retreading via its SmartWay program, which certifies fuel-efficient tires. The European Union's End-of-Life Vehicles (ELV) Directive incentivizes circular economy models, creating a favorable environment for retreading. Similarly, China's national standards and dual carbon goals encourage resource conservation, benefiting the domestic remanufacturing industry. Securing a consistent supply of high-quality casings remains the primary operational challenge for all market participants.
Market Dynamics
The convergence of stringent quality standards, exemplified by Europe's ECE Regulation 109, and the economic imperative for fleet operators to lower costs defines the market. This dynamic elevates high-quality retreads to compete directly with new premium tires.
Growth Catalysts
- Circular Economy Policies:Government initiatives, including the European Union's End-of-Life Vehicles Directive and China's dual carbon goals, incentivize resource conservation and remanufacturing, creating a favorable regulatory environment for tire retreading.
- Logistics Sector Expansion:The continued growth of global e-commerce and road freight networks drives demand from large-scale fleet operators seeking to minimize their total cost of ownership through cost-effective tire programs.
- Technology Validation:The adoption of advanced non-destructive inspection technologies, particularly shearography, improves the quality assurance process, increasing fleet manager confidence in the safety and reliability of retreaded products.
Market Restraints
- Casing Supply Volatility:An inconsistent supply of high-quality, undamaged tire casings represents the primary structural constraint, limiting production capacity and creating procurement challenges, especially for independent retreaders without captive fleet relationships.
- End-User Perception:Lingering, often outdated, negative perceptions regarding the safety and performance of retreaded tires persist among smaller fleet operators and in certain geographic markets, hindering broader market acceptance.
- Low-Cost New Tire Competition:The influx of aggressively priced new truck and bus tires, primarily from manufacturers in Southeast Asia, presents a significant substitution threat that can erode the economic advantage of retreading.
Strategic Opportunities
- Emerging Market Penetration:Developing regions, particularly in Southeast Asia and Africa, with expanding road freight infrastructure and a lack of established retreading ecosystems, offer significant greenfield opportunities for market entry.
- Off-The-Road (OTR) Segment Focus:The high replacement cost of new tires for mining, construction, and agricultural vehicles makes the OTR segment a high-margin opportunity for specialized retreading services.
- Service Model Innovation:Developing integrated tire-as-a-service (TaaS) models that bundle retreading with proactive maintenance, monitoring, and casing management provides a path to capture greater value and build long-term customer relationships.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians skilled in modern casing inspection, buffing, and vulcanization techniques creates operational bottlenecks and poses a risk to maintaining consistent quality standards across facilities.
- Capital Investment Barriers:The high capital expenditure needed for advanced inspection equipment, such as shearography and ultrasonic systems, creates a significant barrier to entry and expansion for smaller, independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Retreading Market |
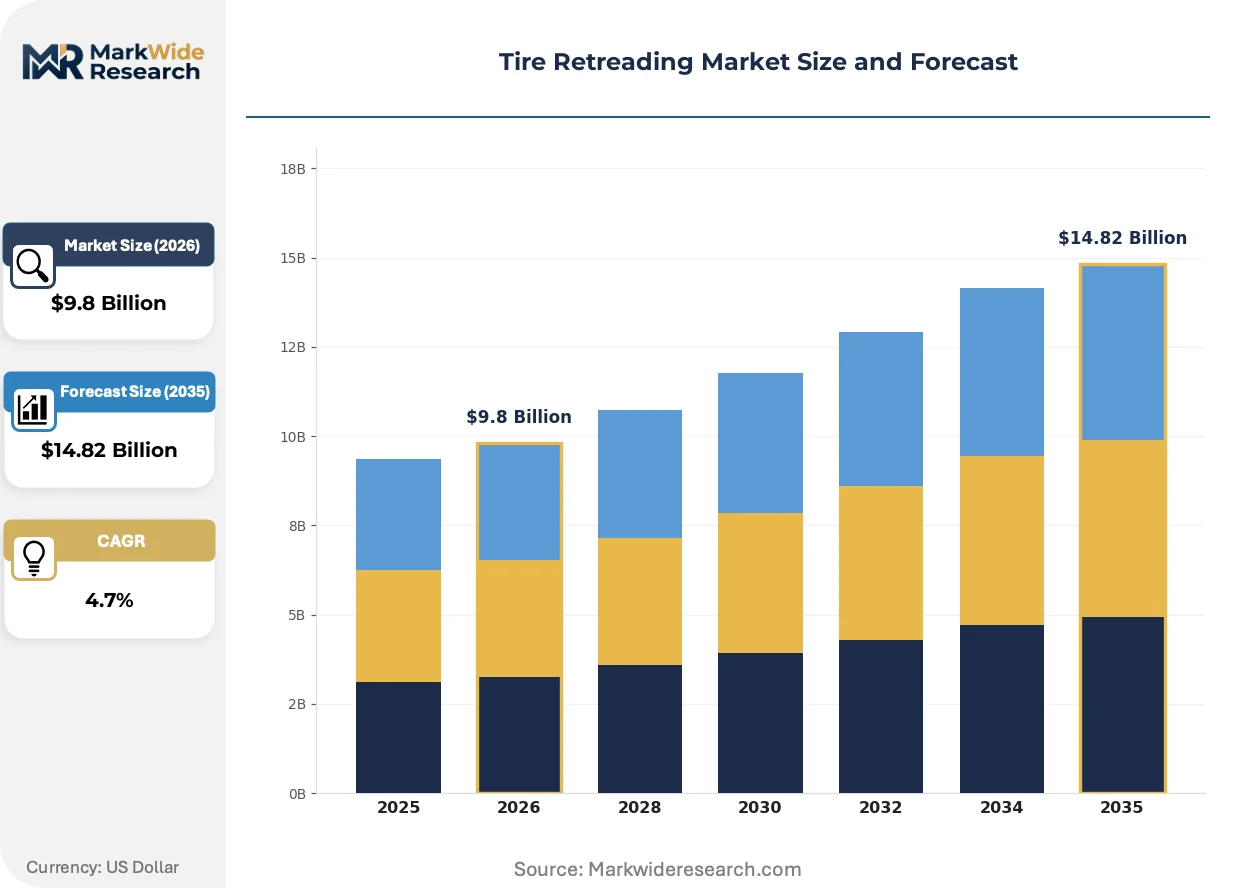
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.82 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Retreading, Hot Retreading, Mold Cure Retreading, Pre-cure Retreading Application: Truck & Bus, Light Vehicles, Aircraft, Off-Road Vehicles, Two Wheelers End User Industry: Logistics Operators, Construction Firms, Agricultural Enterprises, Aviation Services Service Type: Original Equipment Manufacturer, Independent Retreaders, Fleet Operators, Mobile Retreading Units |
| Companies Covered | Marangoni SpA, Continental AG, Bridgestone Corporation, Parrish Tire Company, Oliver Rubber Company, Goodyear Tire and Rubber Company, Southern Tire Mart, Bandag, Michelin SCA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Retreading Market Strategic Shifts & Innovations
Digitalization and material science advancements are transforming tire retreading from a purely mechanical process into a data-driven discipline. These innovations focus on maximizing casing life, ensuring verifiable quality, and integrating with digital fleet management ecosystems. This evolution improves both economic and environmental outcomes.
Embedded sensor technology provides real-time data on tire pressure, temperature, and wear patterns. Large commercial fleets are increasingly specifying sensor-equipped casings to optimize performance and predict maintenance needs. This data-driven asset management is supplanting older, reactive maintenance schedules and enabling proactive casing recovery for retreading.
The U.S. Environmental Protection Agency’s SmartWay program provides a framework for certifying fuel-efficient tires, including specific retread models. This certification validates low rolling resistance, directly translating to fuel savings for commercial fleets. Consequently, North American logistics operators focused on total cost of ownership increasingly specify SmartWay-verified retreads to meet both economic and environmental targets.
Large fleet operators are moving away from transactional, per-tire purchasing toward comprehensive tire management contracts that bundle retreading, maintenance, and casing management. This shift challenges independent retreaders who lack the scale to offer integrated services. The trend is most pronounced among major freight carriers in North America and Europe seeking simplified, predictable operational costs.
Tire Retreading Market Segmentation
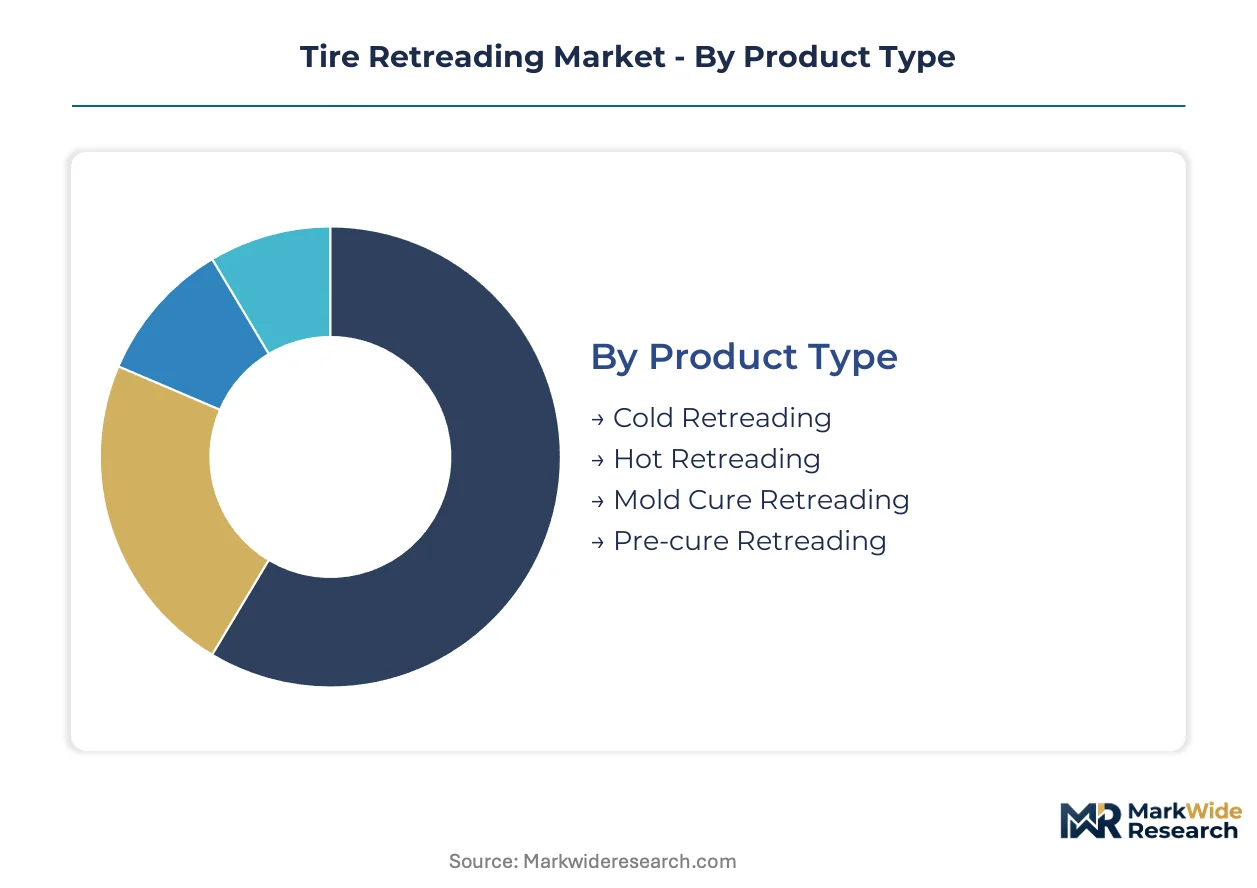
The tire retreading market's structure reflects diverse operational needs and technological applications across various end-use sectors. Understanding these distinct segments is crucial for market participants to tailor offerings and optimize resource allocation. Segmentation provides clarity on where demand originates and how different product types and service models address specific customer requirements.
Product Type:
Margin pools within product type segmentation often reflect the capital intensity and labor skill required for each retreading method.
- Pre-cure Retreading:This method involves applying a pre-vulcanized tread strip to a buffed casing, followed by curing in a chamber. Pre-cure retreads offer consistent quality and are widely adopted by large commercial fleets in North America due to their reliability.
- Mold Cure Retreading:Mold cure retreading uses an unvulcanized rubber tread compound that is applied to the casing, then cured in a heated mold. This traditional method provides a robust bond and is prevalent in markets like Brazil where infrastructure supports larger-scale operations.
- Cold Retreading:Cold retreading is a variant of the pre-cure method, often performed at lower temperatures, suitable for certain tire types.
- Hot Retreading:Hot retreading, similar to mold cure, involves vulcanizing the new tread directly onto the casing using heat and pressure.
Mold Cure Retreading holds installed capacity. Pre-cure Retreading is rotating up the share rankings.
Application:
Application segmentation highlights the diverse operational demands placed upon retreaded tires across various vehicle types.
- Truck & Bus:This segment commands the largest market share, driven by the economic imperative for logistics operators to lower total cost of ownership. Commercial fleets in Germany and the United States extensively utilize retreaded truck and bus tires for long-haul operations.
- Off-Road Vehicles:Retreading for mining, construction, and agricultural vehicles presents a high-margin opportunity due to the high replacement cost of new tires. Specialized retreading services for large OTR tires are critical for operational continuity in Australian mining operations.
- Light Vehicles:Retreaded tires for passenger cars and light commercial vehicles represent a smaller segment, primarily due to consumer perception and new tire pricing.
- Aircraft:Aircraft tires undergo multiple retreading cycles due to stringent safety standards and high operational costs.
- Two Wheelers:The two-wheeler segment for retreaded tires remains niche, primarily serving cost-sensitive markets in Southeast Asia.
Truck & Bus applications represent the largest volume segment, while Off-Road Vehicles offer specialized, high-value opportunities.
End User Industry:
End user industry classification reveals how distinct business models and operational priorities influence tire procurement and retreading strategies.
- Logistics Operators:These firms prioritize total cost of ownership and fleet uptime, making retreading an essential component of their tire management programs. Major freight carriers in the Netherlands and Canada rely on retreaded tires to manage operational expenses.
- Construction Firms:Operators in the construction sector require durable tires that can withstand harsh conditions, making retreading a cost-effective solution for heavy machinery. Construction companies in India often leverage retreading to extend tire life on their equipment.
- Agricultural Enterprises:Agricultural vehicles, including tractors and harvesters, benefit from retreaded tires designed for specific terrain and load requirements.
- Aviation Services:Airlines and aircraft maintenance providers utilize retreaded aircraft tires, adhering to strict regulatory standards for safety and performance.
Logistics Operators consistently prioritize cost efficiency, whereas Aviation Services emphasize stringent safety and performance standards.
Service Type:
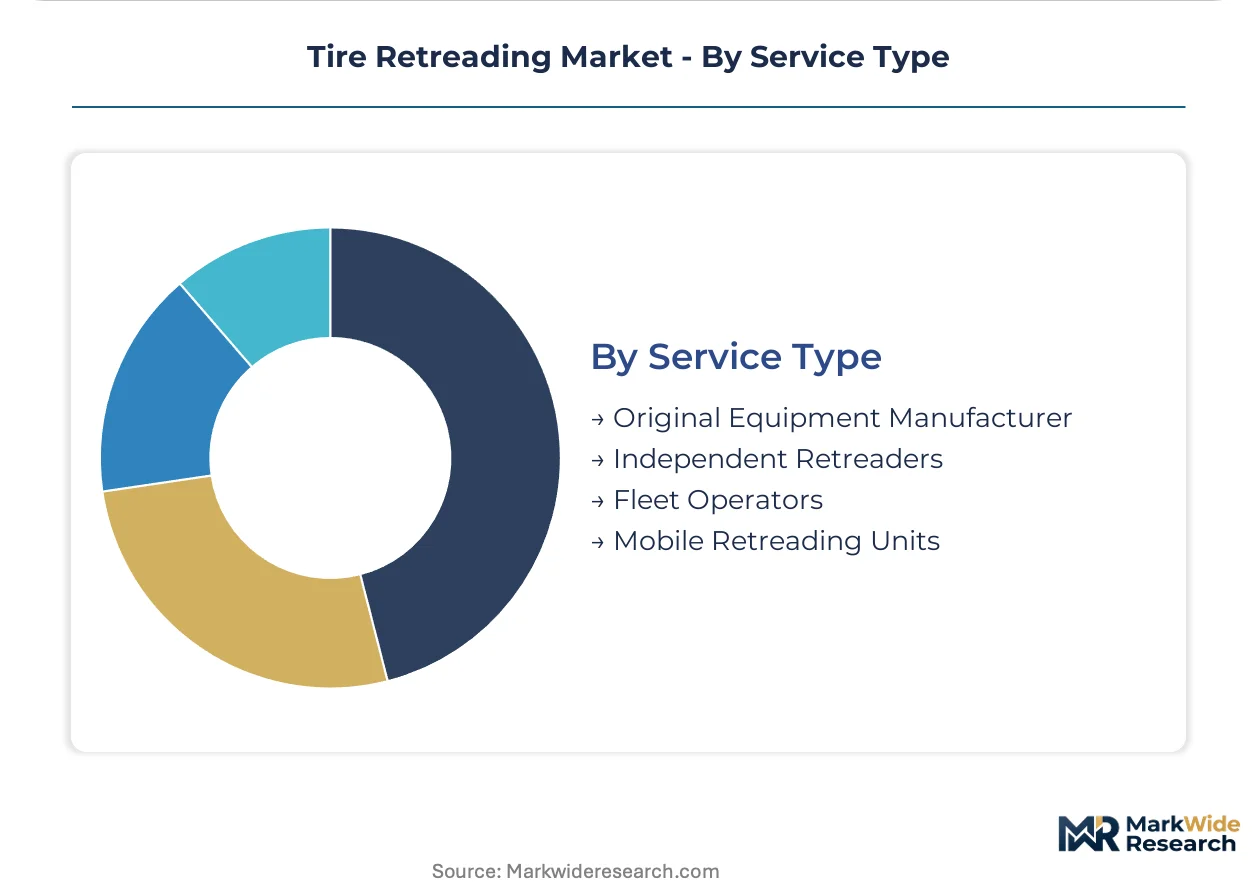
The service type breakdown illustrates the varied channels through which retreaded tires reach end-users, reflecting different levels of integration and market access.
- Independent Retreaders:These businesses operate independently, often serving a diverse customer base with localized services and specialized retreading capabilities. Independent retreaders in France often focus on regional fleets.
- Original Equipment Manufacturer:Major tire manufacturers operate their own retreading networks, ensuring consistent quality and integrating retreads into broader fleet management solutions. Michelin's Bandag network provides standardized services across the United States.
- Fleet Operators:Some large fleet operators establish in-house retreading facilities to gain greater control over quality, costs, and casing supply.
- Mobile Retreading Units:Mobile units offer on-site tire repair and retreading services, particularly beneficial for remote operations like mining sites.
Independent Retreaders maintain broad market access, while Original Equipment Manufacturer networks are expanding their comprehensive service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for retreaded tires concentrates among large-scale logistics operators and commercial fleets globally, driven by the economic imperative to lower operational costs. Regulatory frameworks across various regions increasingly support circular economy principles, further stimulating the adoption of retreading solutions. This regional overview highlights key markets where these dynamics are most pronounced.
Brazil
Extensive road freight networks and economic factors create a mature retreading ecosystem in Brazil, where logistics operators seek cost-effective tire management. The country's national transport policies indirectly support tire longevity and remanufacturing to reduce waste. Major freight hubs like São Paulo and Rio de Janeiro exhibit high demand for retreaded truck and bus tires.
United States
Logistics operators in the United States prioritize total cost of ownership and fleet uptime, making retreading an essential component of their tire programs. The Environmental Protection Agency’s (EPA) SmartWay program certifies fuel-efficient retreads, validating their performance. Commercial fleets in the Midwest and Southeast extensively utilize retreaded tires for long-haul operations.
Germany
Commercial vehicle fleets in Germany extensively utilize retreaded truck and bus tires for long-haul operations, supported by stringent quality standards. Europe's ECE Regulation 109 for commercial vehicle tire retreading ensures high reliability. The Rhine-Ruhr region, a major industrial and logistics hub, shows significant retreading activity.
China
China's dual carbon goals and national standards encourage resource conservation, benefiting the domestic remanufacturing industry for tires. The continued growth of road freight networks drives demand from large-scale fleet operators seeking to minimize total cost of ownership. Industrial clusters in the Yangtze River Delta actively integrate retreaded tires into their logistics operations.
Australia
Retreading for mining and construction vehicles presents a high-margin opportunity in Australia, given the high replacement cost of new tires for heavy equipment. Specialized retreading services for large Off-The-Road (OTR) tires are critical for operational continuity in the country's mining operations. The Pilbara region, with its extensive mining activities, relies heavily on these specialized retreads.
Tire Retreading Market Key Industry Players
Player mix skews toward established tire manufacturers with extensive retreading networks, alongside specialized independent retreaders. The market structure exhibits a tiered approach, with premium manufacturers focusing on integrated solutions and independent players serving localized needs. Dominant competitive moves include geographic expansion through franchised networks and the integration of advanced inspection technologies to enhance product reliability.
Among established tire manufacturers, Michelin SCA leverages its extensive network of Bandag-franchised dealers to ensure consistent quality standards across different geographies. Bridgestone Corporation competes on the durability of its tire casings, which are engineered for multiple retreading cycles, representing a focus on core product strength. Continental AG differentiates through its ContiRe brand, exemplifying an integrated fleet management solutions approach alongside its retreaded products.
| Leading Market Players |
|---|
| Marangoni SpA |
| Continental AG |
| Bridgestone Corporation |
| Parrish Tire Company |
| Oliver Rubber Company |
| Goodyear Tire and Rubber Company |
| Southern Tire Mart |
| Bandag |
| Michelin SCA |
| Others |
Cost & Logistics Intelligence
Long-term fleet contracts, often bundling retreading services, lock in both supply access and price visibility for large logistics operators. This contractual stability underpins the economic model for high-volume retread providers.
Pricing Analysis
Cost-plus contract patterns, frequently indexed to raw material rubber prices, dominate pricing for high-volume retread services. Price differentiation stems from the quality grade of the casing, as validated by advanced inspection technologies like shearography, and the brand premium associated with OEM networks such as Michelin's Bandag. Pricing pressure intensifies from the influx of aggressively priced new truck and bus tires from Southeast Asian manufacturers. Large logistics operators, focused on total cost of ownership, exhibit high price sensitivity for volume contracts, while specialized OTR segments prioritize durability over marginal cost savings.
Supply Chain Analysis
Inbound logistics costs, particularly the consistent supply of high-quality casings, represent a critical supply chain challenge. Geographic supply concentration for retreadable casings draws from regions with extensive road freight networks like Brazil, the United States, and Germany. The primary raw material dependency is on sound tire casings, which underpin the entire remanufacturing process, alongside specialized rubber compounds. Casing supply volatility represents a significant structural risk, limiting production capacity for many market participants. Distribution runs through a mix of independent retreaders and expanding original equipment manufacturer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tire retreading market presents a defensive-moat story, primarily justified by the regulatory entrenchment of circular economy policies and the high switching costs for fleet operators integrated into comprehensive tire management programs.
For Market Incumbents:
Compound existing network advantages by expanding franchised dealer footprints in high-growth emerging markets like Southeast Asia and Africa. Invest heavily in advanced casing inspection technologies, such as shearography, to further differentiate quality and reliability against low-cost new tire competition. Integrate tire-as-a-service (TaaS) models to capture greater value and deepen relationships with major logistics operators. Leverage certification investments, like the EPA's SmartWay program, to reinforce performance claims and meet evolving environmental targets.
For New Entrants and Emerging Players:
Differentiate on specialized service offerings, particularly within the high-margin Off-The-Road (OTR) segment for mining and construction vehicles. Target developing regions with expanding road freight infrastructure and nascent retreading ecosystems, offering greenfield opportunities for market entry. A focused go-to-market angle involves bundling advanced inspection and predictive maintenance with retreading, appealing to fleet managers seeking integrated solutions. Prioritize investment in skilled labor training to ensure consistent quality standards and build trust in new markets.
For Investors and Strategic Acquirers:
Specialized independent retreaders with advanced inspection capabilities or strong regional footprints represent an attractive acquisition target archetype for long-term value creation. These firms benefit from the market's shift towards circular economy models and fleet cost optimization over the next 5-10 years. A key signal to watch is the increasing adoption rate of integrated tire management contracts, indicating a consolidation of demand around comprehensive service providers. Investments in material science for new tread compounds also present a compelling opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Franchised Retreading Networks | Ensures consistent quality standards and broad market reach for major tire manufacturers. |
| Invest in Advanced Casing Inspection | Enhances product reliability and fleet manager confidence in retreaded tires. |
| Develop Tire-as-a-Service Models | Captures greater value by bundling retreading with maintenance and monitoring for fleets. |
| Target Off-The-Road (OTR) Segment | Addresses high replacement costs for specialized vehicles in mining and construction. |
| R&D in Sustainable Tread Compounds | Supports circular economy goals and improves performance metrics for retreaded products. |
Research Approach
The analysis maps retreading product types, application segments, and end-user industries, each validated through extensive interviews with fleet managers, retreading plant operators, and tire manufacturers. This primary research combines with a thorough review of secondary sources, including EPA SmartWay program data, ECE Regulation 109 guidelines, and national transport statistics, employing both bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated all volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, service type, and regional regulatory frameworks. Compound annual growth rates were derived from historical data analysis and projected market drivers, using inputs such as new tire sales volumes and road freight growth rates.
Decision-makers should treat outputs as directional under base assumptions regarding casing supply stability and new tire pricing; material deviation would warrant model refresh. Forecasts reflect these underlying assumptions, acknowledging specific risk factors like sudden shifts in raw material costs or unforeseen regulatory changes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Tire Bead Wire Market
Tires and Wheels
Europe Agricultural Tires Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Tubeless Tire Market