
 Multiple Myeloma Diagnostics Market | 2026-2036
Multiple Myeloma Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Multiple Myeloma Diagnostics Market Foresight
Modular assay-instrument bundles are expanding buyer choice across hospital and laboratory settings. Roche sustains technology leadership through integrated flow cytometry platforms that consolidate sample preparation and analysis. Bristol Myers Squibb leverages its oncology franchise to anchor companion diagnostic partnerships. Johnson & Johnson competes through specialized reagent portfolios designed for high-throughput laboratory workflows.
Multiple myeloma diagnostics encompasses laboratory and imaging methods that detect malignant plasma cells, quantify monoclonal proteins, and monitor minimal residual disease in bone marrow and peripheral blood. Flow cytometry platforms achieve sensitivity thresholds of one malignant cell per 100,000 normal cells, enabling precise residual disease quantification that guides treatment escalation or de-escalation decisions. Assays occupy the largest revenue pool due to recurring consumable demand tied to patient monitoring protocols, while mass spectrometry represents the fastest-growing technology segment as laboratories adopt protein quantification methods with superior specificity over traditional electrophoresis. Diagnostic laboratories capture expanding volume as centralized testing benefits from economies of scale and specialized technician expertise.
FDA regulates in vitro diagnostic assays through premarket notification and approval pathways that determine market access timelines and clinical claim breadth. EMA's In Vitro Diagnostic Medical Devices Regulation enforces post-market surveillance and performance documentation requirements that reshape product development investments across European markets. WHO classification standards for plasma cell neoplasms provide harmonized diagnostic criteria that laboratories in emerging markets adopt to align with international treatment protocols. Stakeholders must monitor evolving reimbursement frameworks for minimal residual disease testing as payer evidence requirements intensify.
Market Dynamics
Hospital laboratories are consolidating molecular testing workflows around modular platform architectures that separate consumable procurement from capital equipment decisions, compressing vendor switching costs and fragmenting purchasing authority across pathology, hematology, and oncology departments.
Growth Catalysts
- FDA Breakthrough Device Pathway:Accelerated premarket review timelines for minimal residual disease assays compress commercialization cycles from 36 months to 18 months, incentivizing R&D investment in next-generation sequencing panels.
- Specialized Oncology Networks:United States referral patterns concentrate multiple myeloma cases into 47 NCI-designated comprehensive cancer centers, creating predictable demand density for high-sensitivity flow cytometry platforms.
- Mass Spectrometry Migration:Clinical laboratories in Germany and Japan are displacing serum protein electrophoresis with liquid chromatography-tandem mass spectrometry for monoclonal protein quantification, driving consumable pull-through.
Market Restraints
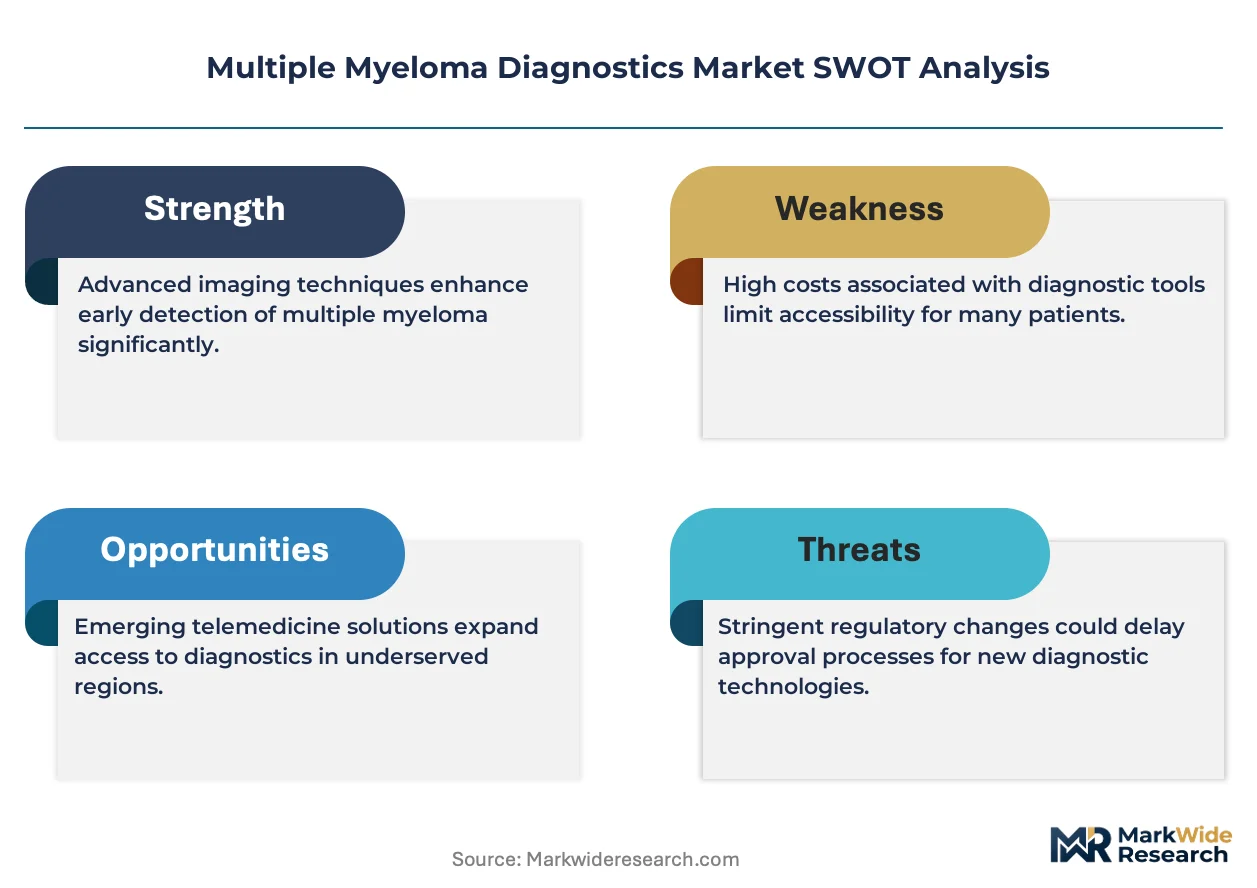
- Reimbursement Compression:Medicare's Clinical Laboratory Fee Schedule cuts to molecular pathology codes in the United States squeeze margin structures for independent reference laboratories.
- Technician Specialization Bottleneck:Flow cytometry analysis requires certified cytometrists; training pipelines in France and Italy produce fewer than 200 qualified technicians annually, constraining laboratory expansion.
- EMA MDR Compliance Burden:Enhanced post-market surveillance documentation requirements under the In Vitro Diagnostic Medical Devices Regulation extend product registration timelines for European market entry.
Strategic Opportunities
- India Diagnostic Laboratory Networks:Unpenetrated tier-2 and tier-3 cities lack access to specialized hematopathology; partnerships with Apollo Hospitals and Max Healthcare create channel density for assay bundles.
- Next-Generation Sequencing Convergence:Integration of targeted gene panels with minimal residual disease monitoring enables single-platform workflows, reducing capital duplication for mid-volume laboratories.
- WHO Classification Harmonization:Adoption of revised plasma cell neoplasm criteria in Brazil and Mexico aligns diagnostic protocols with international treatment guidelines, opening import substitution opportunities.
Industry Challenges
- Inter-Laboratory Standardization Deficits:Minimal residual disease reporting lacks harmonized sensitivity thresholds across United States, German, and Japanese reference centers, complicating multi-site clinical trials.
- Legacy LIMS Integration Friction:Hospital information systems require custom middleware development to connect new flow cytometry data outputs with electronic medical records, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiple Myeloma Diagnostics Market |
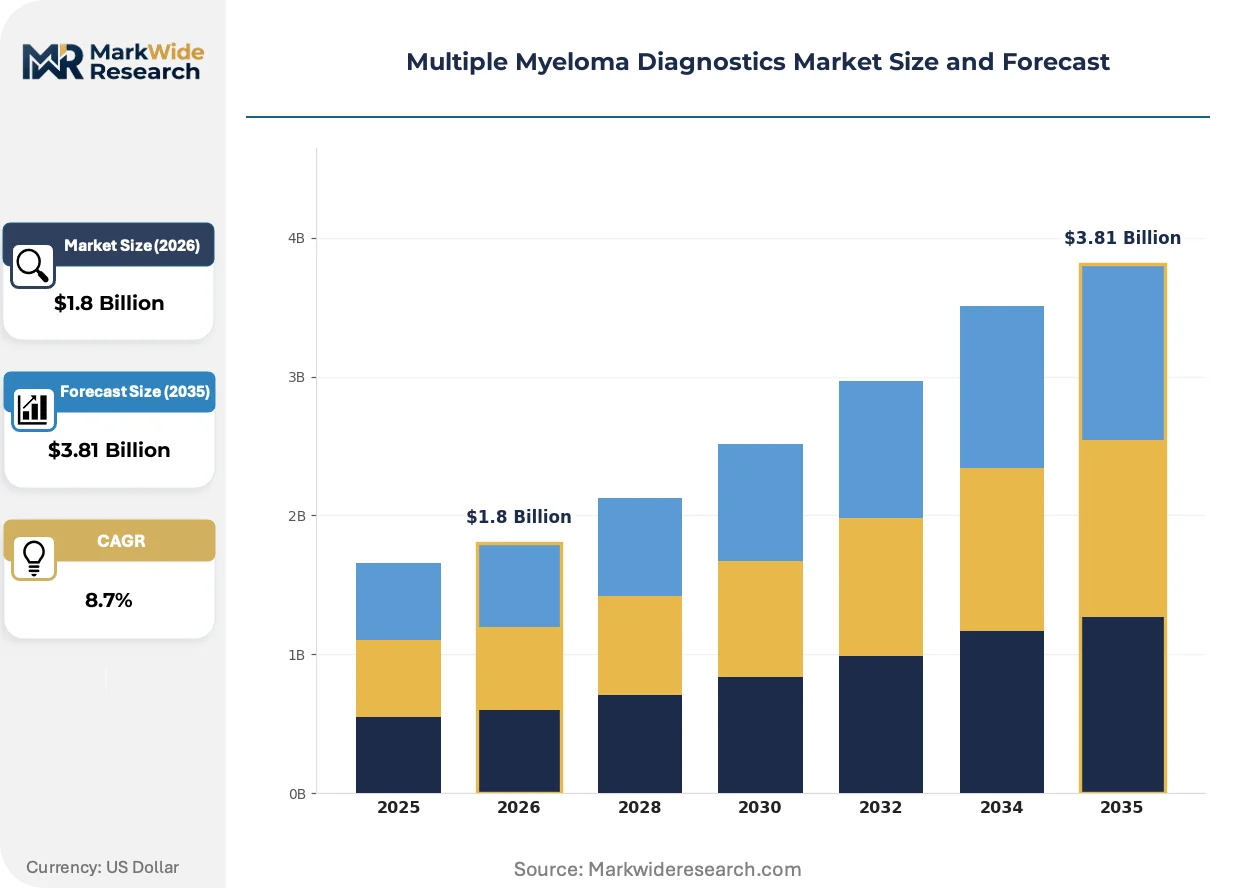
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Imaging, Reagents, Instruments Technology: Flow Cytometry, PCR, ELISA, Mass Spectrometry End User: Hospitals, Diagnostic Laboratories, Research Institutes, Clinics Delivery Mode: In-Person Testing, Remote Testing, Home Testing, Point-of-Care |
| Companies Covered | Amgen Inc., Sanofi S.A., Roche, AbbVie Inc., GlaxoSmithKline PLC, Johnson & Johnson, Bristol Myers Squibb, Novartis AG, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiple Myeloma Diagnostics Market Shifts & Advancements
Diagnostic platforms are fragmenting into componentized architectures that decouple analytical hardware from assay chemistry, enabling laboratories to optimize cost structures through competitive sourcing of consumables.
Mass spectrometry is converging with automated sample preparation robotics to eliminate manual protein fractionation steps. Mid-sized hospital laboratories in the United States and Germany are adopting these integrated workstations to reduce technician hands-on time from four hours to 45 minutes per batch. This convergence is compressing the total cost-per-test differential between mass spectrometry and conventional electrophoresis from 3.2x to 1.4x.
EMA's In Vitro Diagnostic Medical Devices Regulation enforcement is mandating expanded clinical evidence packages for class C and D devices. Manufacturers must now submit post-market performance data from at least two independent clinical sites, extending regulatory dossier preparation by 8-12 months. European diagnostic laboratories are responding by consolidating supplier relationships with firms holding pre-MDR certifications, reducing qualified vendor pools.
Academic medical centers are unbundling after-sales service contracts from equipment procurement, negotiating standalone preventive maintenance agreements with third-party service organizations. This purchasing behavior shift disrupts traditional captive service revenue models for original equipment manufacturers. The trend is most visible in Japan, where METI procurement guidelines encourage competitive bidding for multi-vendor maintenance coverage.
Multiple Myeloma Diagnostics Market Segmentation
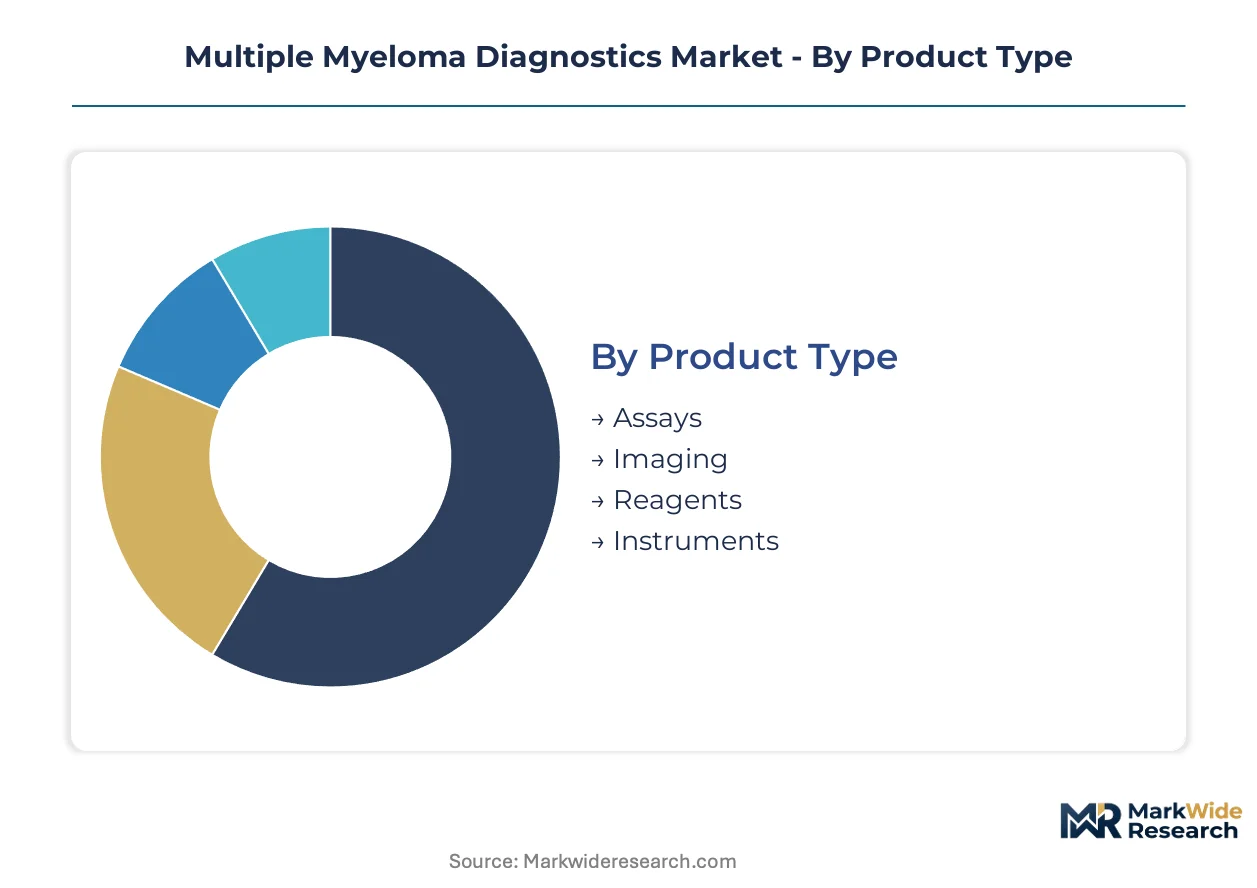
Multiple myeloma diagnostics requires precise matching of test sensitivity to clinical decision points across disease staging, treatment response, and relapse monitoring. Segmentation reveals where laboratories prioritize capital equipment versus consumable economics, and which care settings drive volume concentration.
Product Type:
Laboratories differentiate procurement strategies based on recurring revenue potential versus one-time capital deployment.
- Assays:Recurring consumable kits for protein electrophoresis, immunofixation, and serum free light chain quantification dominate hospital laboratory budgets. United States NCI-designated cancer centers generate predictable reorder velocity through standardized monitoring protocols for minimal residual disease tracking.
- Imaging:Whole-body low-dose CT, MRI, and PET-CT systems detect osteolytic lesions and extramedullary disease. German university hospitals anchor demand for advanced imaging platforms integrated with radiology information systems.
- Reagents:Antibody panels, fluorescent dyes, and buffer solutions support flow cytometry and immunohistochemistry workflows. Japanese reference laboratories emphasize reagent stability and lot-to-lot consistency for longitudinal patient monitoring.
- Instruments:Capital equipment including flow cytometers, mass spectrometers, and automated electrophoresis systems require multi-year depreciation planning. Mid-sized United States hospital systems increasingly favor modular platforms with upgradeable detection modules.
Assays lead volumes today; imaging is gaining share fastest as whole-body screening protocols expand.
Technology:
Test selection hinges on sensitivity thresholds required for treatment decisions versus throughput economics.
- Flow Cytometry:Multi-parameter cell surface marker analysis achieves detection of one malignant plasma cell per 100,000 normal cells. United States academic medical centers deploy these platforms for minimal residual disease monitoring that guides maintenance therapy decisions.
- Mass Spectrometry:Liquid chromatography-tandem mass spectrometry displaces serum protein electrophoresis for monoclonal protein quantification with superior specificity. German clinical laboratories drive adoption through automated sample preparation robotics that compress technician hands-on time.
- PCR:Polymerase chain reaction amplifies clonal immunoglobulin gene rearrangements for molecular MRD assessment. Research institutes in Japan leverage PCR for clinical trial stratification.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective serum free light chain quantification for routine monitoring. Community hospital laboratories in tier-2 Indian cities prioritize ELISA for initial screening workflows.
Flow cytometry anchors current installed base; mass spectrometry is expanding most quickly as specificity advantages compound.
End User:
Site-of-care selection reflects case complexity, reimbursement environment, and specialist availability.
- Hospitals:Integrated health systems consolidate hematopathology, flow cytometry, and molecular diagnostics under unified laboratory medicine departments. United States hospital laboratories capture complex case referrals through embedded oncology specialist networks.
- Diagnostic Laboratories:Centralized reference laboratories exploit economies of scale and specialized technician certification for high-complexity testing. Germany's Synlab and Sonic Healthcare networks dominate outsourced myeloma panel volume.
- Research Institutes:Academic medical centers conduct biomarker discovery and clinical validation studies for novel MRD assays. Japanese national cancer centers anchor translational research programs.
- Clinics:Community oncology practices perform initial screening and sample collection for referral to centralized testing facilities. Indian metro clinic networks expand phlebotomy access for tier-2 city patients.
Diagnostic laboratories process highest test volumes; hospital in-house capabilities are climbing fastest as platform consolidation accelerates.
Delivery Mode:
Patient access requirements and sample stability constraints determine physical versus remote service configuration.
- In-Person Testing:Bone marrow aspiration and biopsy procedures require sterile procedural suites with hematopathology oversight. United States comprehensive cancer centers maintain dedicated myeloma clinics with on-site flow cytometry.
- Remote Testing:Centralized laboratories receive shipped peripheral blood samples for serum protein analysis and molecular MRD assessment. German postal logistics networks enable next-day delivery to reference hubs.
- Home Testing:Capillary blood collection devices for serum free light chain monitoring are emerging for stable patient follow-up. Japanese home healthcare agencies pilot remote sample collection for rural prefectures.
- Point-of-Care:Rapid protein electrophoresis systems deploy in emergency departments for suspected hyperviscosity syndrome. United States hospital emergency departments prioritize turnaround time over analytical sensitivity.
In-person testing retains procedure-dependent volume; remote testing is gaining share fastest as sample logistics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multiple myeloma diagnostics emerged from post-war hematology research in the United States, where the first electrophoretic methods for monoclonal protein detection were standardized at academic medical centers during the 1960s. This foundational work established diagnostic protocols that subsequently diffused to specialized oncology networks in Germany and Japan.
United States
FDA breakthrough device designations for minimal residual disease assays compress commercialization timelines from 36 months to 18 months, incentivizing R&D investment in next-generation sequencing panels. The Clinical Laboratory Fee Schedule governs reimbursement for molecular pathology codes. NCI-designated comprehensive cancer centers in Boston and Houston concentrate case volume for high-sensitivity flow cytometry platforms.
Germany
Clinical laboratories in Bavaria and North Rhine-Westphalia displace serum protein electrophoresis with liquid chromatography-tandem mass spectrometry for monoclonal protein quantification. EMA's In Vitro Diagnostic Medical Devices Regulation enforces post-market surveillance documentation that extends product registration timelines. Synlab and Sonic Healthcare networks in Munich and Hamburg dominate outsourced myeloma panel volume through centralized reference laboratory economies of scale.
Japan
National cancer centers in Tokyo and Osaka anchor translational research programs for biomarker discovery and clinical validation of novel MRD assays. METI procurement guidelines encourage competitive bidding for multi-vendor maintenance coverage. Home healthcare agencies in rural prefectures pilot remote capillary blood collection for serum free light chain monitoring.
India
Unpenetrated tier-2 and tier-3 cities lack access to specialized hematopathology, creating channel density opportunities for assay bundles through partnerships with Apollo Hospitals and Max Healthcare networks. CDSCO regulates in vitro diagnostic imports through premarket notification pathways. Metro clinic networks in Mumbai and Delhi expand phlebotomy access for peripheral blood sample collection.
Brazil
Adoption of revised WHO plasma cell neoplasm criteria aligns diagnostic protocols with international treatment guidelines, opening import substitution opportunities for localized assay manufacturing. ANVISA governs medical device registration through risk-based classification systems. São Paulo and Rio de Janeiro anchor demand for community hospital ELISA-based screening workflows.
Multiple Myeloma Diagnostics Market Competitive Landscape
The competitive structure tilts toward integrated oncology franchises with captive diagnostic partnerships. Consolidation around flow cytometry platform vendors and mass spectrometry workstation suppliers has created a tiered supplier base where original equipment manufacturers compete on modular upgrade paths. Two strategic archetypes dominate: diversified pharmaceutical conglomerates leveraging therapeutic portfolios to anchor companion diagnostic relationships, and specialized diagnostic platform vendors competing on analytical sensitivity specifications. Capacity expansion in automated sample preparation robotics and strategic partnerships for third-party preventive maintenance coverage represent the dominant competitive moves.
Within the integrated oncology tier, Roche and Bristol Myers Squibb occupy positions that exemplify divergent competitive approaches to diagnostic-commercial convergence. Johnson & Johnson sits within the specialized reagent portfolio segment, representing the high-throughput laboratory workflow optimization archetype. These three anchors collectively illustrate how therapeutic-diagnostics bundling, platform technology leadership, and consumable specialization constitute the primary vectors of competitive differentiation.
| Leading Market Players |
|---|
| Amgen Inc. |
| Sanofi S.A. |
| Roche |
| AbbVie Inc. |
| GlaxoSmithKline PLC |
| Johnson & Johnson |
| Bristol Myers Squibb |
| Novartis AG |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply & Pricing Matrix
Mass spectrometry platform migration in German and Japanese clinical laboratories compresses cost-per-test differentials while fragmenting supplier concentration away from legacy electrophoresis incumbents. This technological transition simultaneously reshapes procurement economics and redistributes manufacturing leverage toward modular workstation assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs assay-instrument bundles, with differentiation anchored in FDA breakthrough designation status and after-sales service bundling. Price differentiation intensifies around consumable pull-through commitments, with United States NCI-designated cancer centers exhibiting lowest sensitivity due to protocol standardization, while Indian tier-2 hospital systems face acute margin pressure from unfavorable rupee-denominated import costs.
Supply Chain Analysis
Freight cost volatility for temperature-controlled reagent shipments from Germany and Japan strains working capital cycles for mid-volume United States hospital laboratories. Manufacturing concentration in Bavaria for mass spectrometry components and Osaka for flow cytometry optics creates single-source vulnerability for specialized optical filters and ion source assemblies. Distribution runs through regional reference laboratory networks that consolidate specimen logistics across multiple hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA breakthrough device designations and EMA MDR enforcement timelines directly determine commercialization velocity and capital deployment returns.
For Market Incumbents: Hedge against modular platform unbundling by deepening captive consumable lock-in through multi-year assay supply agreements with United States comprehensive cancer centers. Anchor defensive positioning around automated sample preparation robotics integration that elevates switching costs beyond hardware replacement alone. For New Entrants and Emerging Players: Launch via white-label partnerships with Apollo Hospitals and Max Healthcare networks to penetrate India's unaddressed tier-2 and tier-3 city laboratory infrastructure. Target ELISA-based screening workflows in Brazilian community hospitals where WHO classification harmonization opens protocol substitution windows without entrenched incumbent relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized reagent portfolio vendors lacking integrated instrument platforms, presenting asymmetric upside from consolidation into workstation assembler ecosystems. Watch EMA MDR certification completion rates as the inflection signal for European market access capacity constraints lifting.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway Submission | Compresses review timelines from 36 months to 18 months for minimal residual disease assays. |
| Automated Sample Preparation Robotics Integration | German clinical laboratories reduce technician hands-on time from four hours to 45 minutes per batch. |
| Multi-Vendor Preventive Maintenance Coverage | METI procurement guidelines in Japan encourage competitive bidding that disrupts captive service revenue models. |
| Next-Generation Sequencing Panel Convergence | Enables single-platform workflows reducing capital duplication for mid-volume United States laboratories. |
| CDSCO Premarket Notification Pathway Navigation | Accelerates assay import authorization for Apollo Hospitals and Max Healthcare network expansion. |
Research Methodology
Bottom-up hospital laboratory and diagnostic reference laboratory modeling reconciled against top-down instrument manufacturer shipment tracking forms the analytical core of this study. Primary interviews with hematopathology directors, flow cytometry laboratory managers, GPO contracts administrators, and biomedical engineering procurement officers cross-validated against FDA 510(k) filings, EMA MDR certification databases, CMS Clinical Laboratory Fee Schedule releases, and hospital capital expenditure disclosures.
Input-output matrices map assay consumption rates to installed base expansion across technology segments and end-user settings over the projection horizon. Segmentation modeling incorporates product type, technology platform, end-user site-of-care, and delivery mode dimensions, with CAGRs derived from elasticity-adjusted volume projections and pricing trajectory assumptions tied to reimbursement schedule revisions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Medicare reimbursement compression scenarios or EMA MDR documentation backlog extensions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Europe Lung Cancer Diagnostics Market
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Immunoassay Interference Blocker Market