
 Global Thyroid Cancer Drugs Market | 2026-2036
Global Thyroid Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thyroid Cancer Drugs Market Foresight
Next-generation kinase selectivity standards are bifurcating the competitive landscape into precision-targeted and broad-spectrum portfolios. Bayer AG leverages its radiopharmaceutical manufacturing infrastructure to sustain supply security for radioactive iodine formulations across European treatment centers. Eisai Co., Ltd differentiates through specialized R&D intensity in differentiated thyroid carcinoma subsets, while Exelixis Inc competes on kinase inhibitor specificity profiles that command premium reimbursement positioning in North American oncology clinics.
Thyroid cancer drugs comprise systemic therapeutic agents engineered to interrupt oncogenic signaling pathways, with tyrosine kinase inhibitors typically formulated as small-molecule compounds exhibiting nanomolar potency against RET, BRAF, or VEGFR mutations; these agents serve the primary commercial purpose of extending progression-free survival in patients with locally advanced or metastatic disease. Monoclonal antibodies targeting receptor tyrosine kinases occupy the highest-margin tier within the drug type dimension, whereas radioactive iodine retains structural importance in adjuvant settings despite reimbursement compression. Papillary thyroid cancer dominates the therapy area dimension by treated volume, though anaplastic thyroid cancer commands disproportionate R&D investment due to its orphan-disease designation and accelerated regulatory pathways.
The FDA's breakthrough therapy designation and the EMA's PRIME eligibility scheme are reshaping clinical trial requirements and commercial launch timelines for novel thyroid cancer therapeutics, while Japan's PMDA sakigake framework accelerates priority review for agents addressing unmet needs in rare thyroid malignancies. REACH and RoHS compliance obligations in Europe constrain radiopharmaceutical manufacturing inputs, creating differentiated supply chain complexity across geographic markets. Stakeholders must monitor evolving biomarker-driven label expansions and companion diagnostic co-development requirements that will determine portfolio relevance in the differentiated therapy landscape.
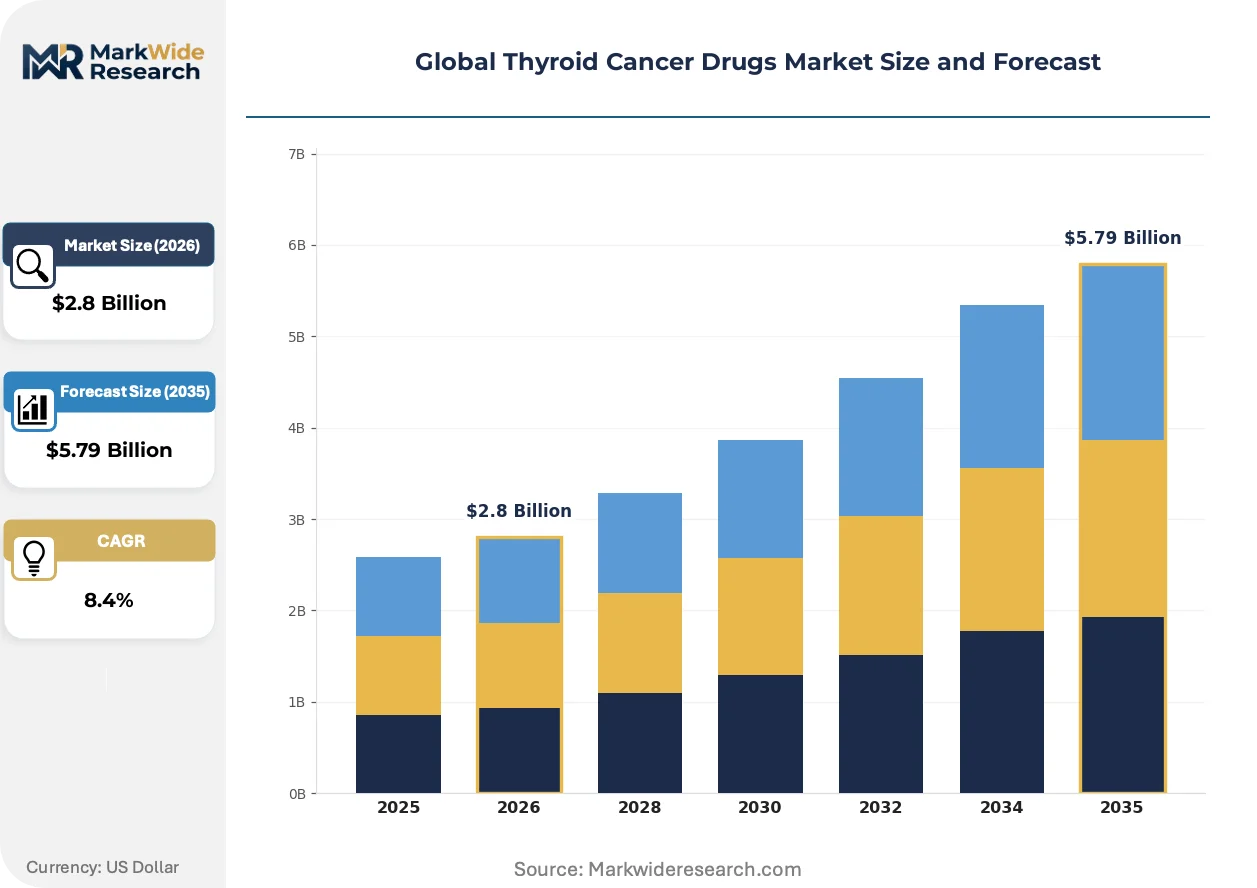
Market Dynamics
Kinase inhibitor selectivity standards are fragmenting the competitive landscape into precision-targeted versus broad-spectrum therapeutic portfolios, forcing manufacturers to choose between biomarker-driven development and volume-oriented oncology positioning.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated approval pathways compress clinical trial timelines for novel RET and BRAF inhibitors, enabling earlier commercial access for patients with locally advanced disease.
- Japan's Aging Demographics:Elevated papillary thyroid cancer incidence among patients over 65 expands the addressable pool for molecularly targeted agents in Tokyo and Osaka treatment centers.
- Companion Diagnostic Co-Development:Biomarker-driven patient stratification improves response rates and strengthens reimbursement positioning for kinase inhibitors in North American oncology clinics.
Market Restraints
- Radiopharmaceutical Supply Concentration:Radioactive iodine manufacturing depends on a limited number of European isotope production facilities, creating vulnerability to reactor maintenance schedules.
- REACH and RoHS Compliance:European chemical regulations constrain radiopharmaceutical input sourcing, adding documentation burden and qualification timelines for radioactive formulations.
- Tyrosine Kinase Inhibitor Substitution:Cross-tumor pathway targeting enables oncology drugs developed for melanoma or lung cancer to encroach on differentiated thyroid carcinoma indications.
Strategic Opportunities
- Anaplastic Thyroid Carcinoma Orphan Status:Rare disease designations unlock accelerated regulatory pathways and premium pricing for agents addressing this lethal histology subtype.
- EMA PRIME Eligibility:Priority medicines status in Europe expedites scientific advice and marketing authorization for therapies targeting unmet needs in medullary thyroid cancer.
- Telemedicine-Enabled Trial Recruitment:Virtual patient monitoring expands geographic reach for decentralized clinical studies, accessing previously underserved rural populations in the United States.
Industry Challenges
- Molecular Pathology Talent Scarcity:Shortage of trained pathologists capable of interpreting RET fusion and BRAF V600E biomarker results delays treatment initiation in community oncology settings.
- Radiopharmaceutical Cold Chain Integrity:Iodine-131's eight-day half-life demands precise logistics coordination between manufacturing sites in Belgium and dosing centers across Germany and France.
- Cross-Border Reimbursement Fragmentation:Divergent health technology assessment criteria between England's NICE and France's HAS complicates parallel market entry for novel kinase inhibitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thyroid Cancer Drugs Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Tyrosine Kinase Inhibitors, Monoclonal Antibodies, Radioactive Iodine, Chemotherapy Agents Therapy Area: Medullary Thyroid Cancer, Papillary Thyroid Cancer, Follicular Thyroid Cancer, Anaplastic Thyroid Cancer End User: Oncology Clinics, Specialty Hospitals, Research Institutions, Diagnostic Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Hospital Supply |
| Companies Covered | Novartis AG, Eisai Co., Ltd, Bayer AG, AstraZeneca, Roche, Pfizer Inc, Bristol-Myers Squibb, Exelixis Inc, Takeda Pharmaceutical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thyroid Cancer Drugs Market Shifts & Advancements
Next-generation sequencing integration is reconfiguring how oncologists match patients to targeted therapies, creating pressure for real-time biomarker infrastructure and compressing the window between diagnosis and molecularly informed treatment selection.
RET-selective inhibitors are bifurcating the precision oncology landscape. These agents demonstrate superior tolerability profiles compared to multikinase predecessors. Major cancer centers in the United States and Japan are prioritizing them for first-line metastatic disease. The technology is bifurcating clinical trial design, with sponsors now required to run separate studies for RET-fusion versus RET-mutation populations.
EMA's PRIME scheme is compressing development timelines for priority medicines in rare thyroid malignancies. Eligible sponsors receive enhanced scientific advice and accelerated assessment pathways. Small biotechnology developers targeting anaplastic histologies are restructuring regulatory strategies around this framework.
Oncology procurement is consolidating through integrated delivery networks in the United States. Hospital systems now negotiate formulary placement for entire kinase inhibitor portfolios rather than individual agents. This behavioral shift concentrates purchasing power within twenty major health systems and marginalizes independent community oncology practices.
Global Thyroid Cancer Drugs Market Segmentation
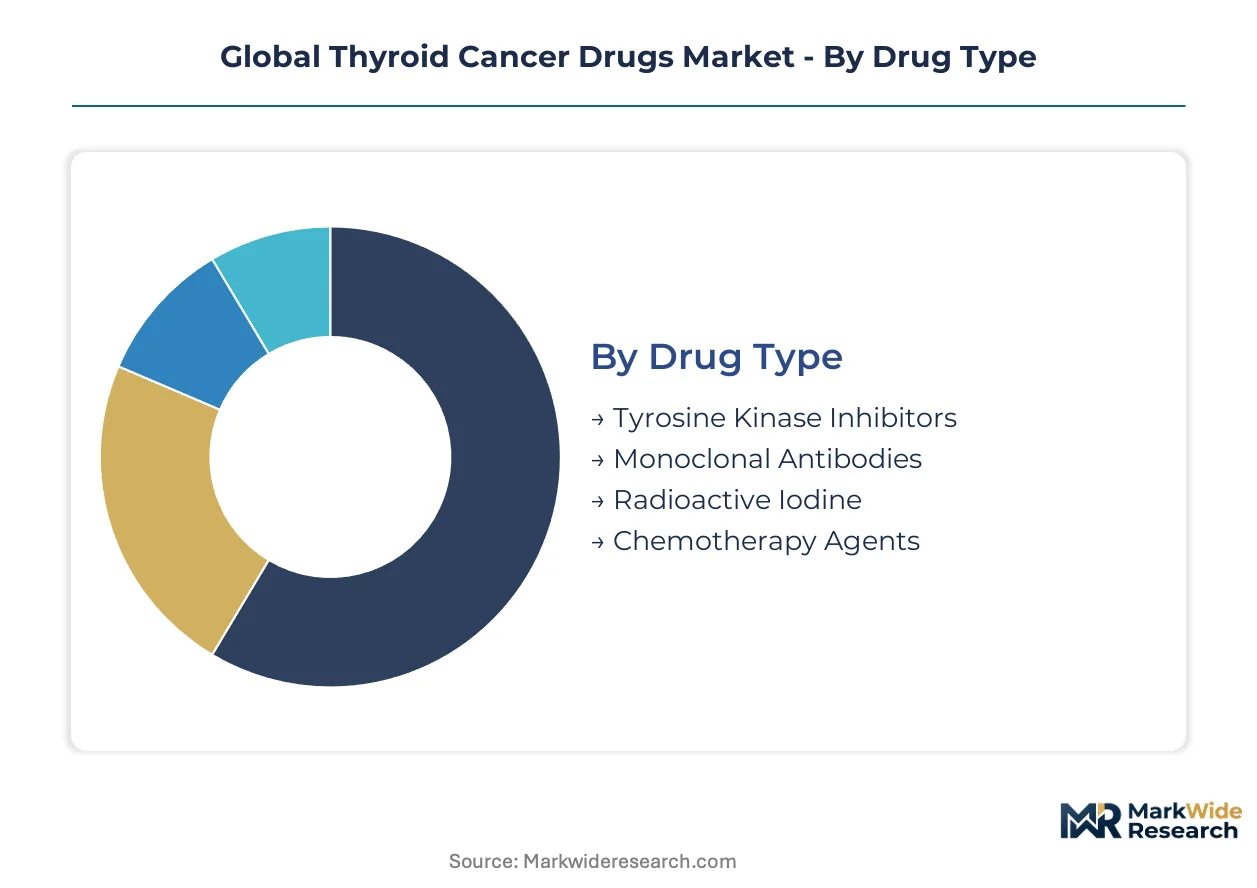
Segmentation in thyroid cancer therapeutics reveals how reimbursement dynamics, biomarker infrastructure, and treatment site capabilities allocate value across molecularly distinct patient populations. Manufacturers must align portfolio positioning with the specific clinical workflows and regulatory pathways governing each segment.
Drug Type:
Margin pools concentrate in precision-targeted small molecules commanding premium pricing in North American oncology clinics, while radiopharmaceuticals face reimbursement compression despite structural volume importance.
- Tyrosine Kinase Inhibitors:Small-molecule compounds engineered for nanomolar potency against RET, BRAF, or VEGFR mutations dominate commercial value through progression-free survival extensions in metastatic disease. Demand concentrates in Tokyo and Osaka treatment centers where Japan's PMDA sakigake framework accelerates priority review for molecularly targeted agents.
- Monoclonal Antibodies:Receptor tyrosine kinase-targeting biologics occupy the highest-margin tier within this dimension due to manufacturing complexity and infusion-based administration protocols. Reimbursement positioning strengthens in United States integrated delivery networks negotiating formulary placement for entire kinase inhibitor portfolios.
- Radioactive Iodine:Structural importance persists in adjuvant settings despite pricing pressure from European health technology assessment bodies.
- Chemotherapy Agents:Legacy cytotoxic formulations retain niche utility in anaplastic histologies where targeted options remain limited.
The dominant share belongs to Tyrosine Kinase Inhibitors, while Monoclonal Antibodies is closing the gap fastest through biosimilar competition and label expansion strategies.
Therapy Area:
Volume distribution inversely correlates with disease lethality, creating divergent R&D investment patterns between high-incidence indolent subtypes and rare aggressive malignancies.
- Papillary Thyroid Cancer:The most common histology by treated volume drives foundational revenue for radioactive iodine and kinase inhibitor portfolios alike. Patient pools expand most quickly in Japan's aging demographic clusters where elevated incidence among patients over 65 sustains addressable market growth.
- Anaplastic Thyroid Cancer:This lethal subtype commands disproportionate R&D investment due to orphan-disease designation and FDA accelerated approval pathways enabling compressed development timelines. Premium pricing potential attracts biotechnology developers restructuring regulatory strategies around EMA PRIME eligibility.
- Medullary Thyroid Cancer:RET-mutation prevalence creates targeted therapy opportunities with distinct biomarker-driven patient stratification requirements.
- Follicular Thyroid Cancer:Iodine-avid disease characteristics maintain radioactive iodine relevance despite emergence of multikinase alternatives.
Papillary Thyroid Cancer holds the volume lead, though Anaplastic Thyroid Cancer exhibits the steepest expansion trajectory in development-stage investment.
End User:
Site-of-care capabilities determine access to molecular pathology infrastructure and companion diagnostic integration essential for biomarker-informed therapy selection.
- Oncology Clinics:Outpatient infusion centers and community-based practices handle the majority of kinase inhibitor prescribing with growing next-generation sequencing adoption. United States integrated delivery networks concentrate purchasing power for targeted therapy protocols across twenty major health systems.
- Specialty Hospitals:Academic medical centers with embedded molecular tumor boards command premium positioning for complex anaplastic carcinoma cases requiring multidisciplinary coordination. Tokyo and Osaka treatment centers in Japan anchor regional referral patterns for rare thyroid malignancies.
- Research Institutions:Clinical trial enrollment sites with biomarker laboratory capabilities drive pipeline asset valuation through patient access.
- Diagnostic Centers:Independent pathology laboratories with RET fusion and BRAF V600E interpretation expertise reduce treatment initiation delays.
Oncology Clinics maintain the dominant share, while Specialty Hospitals are gaining share fastest through centralized expertise consolidation.
Distribution Channel:
Cold chain integrity requirements and radioactive material handling regulations fragment logistics capabilities across channel types.
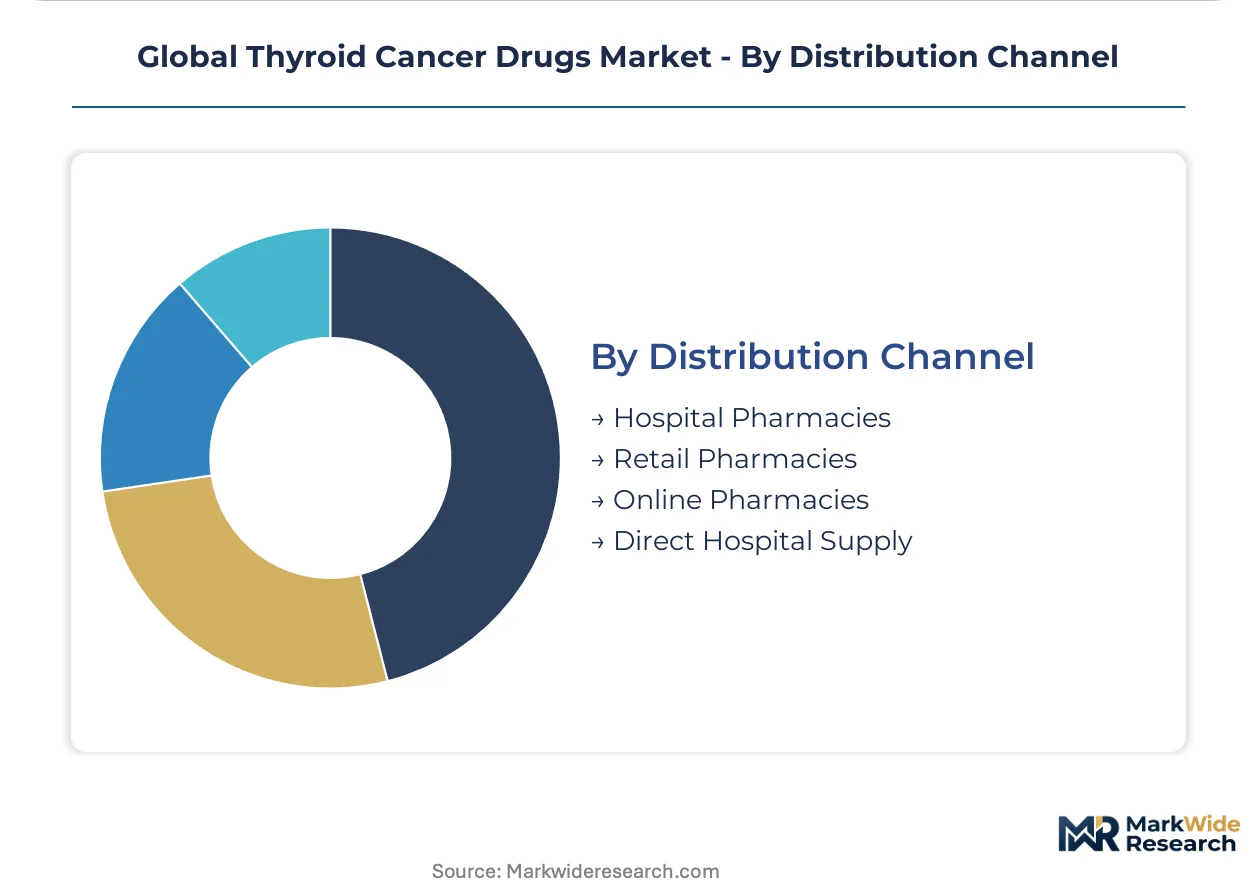
- Hospital Pharmacies:Captive dispensing within oncology centers ensures radioactive iodine handling compliance and immediate availability for time-sensitive administration. Belgian manufacturing sites coordinate with German and French dosing centers through precisely scheduled logistics networks.
- Direct Hospital Supply:Manufacturer-to-site distribution for radiopharmaceuticals bypasses wholesale intermediaries given Iodine-131's eight-day half-life constraints. REACH and RoHS compliance obligations in Europe add documentation burden unique to this channel.
- Retail Pharmacies:Oral kinase inhibitors with standard storage requirements enable community-based dispensing for stable chronic therapy.
- Online Pharmacies:Telemedicine-enabled prescription flows expand geographic reach for patients in rural United States populations.
Hospital Pharmacies command the dominant share, with Direct Hospital Supply expanding most quickly through radiopharmaceutical supply security investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of radioactive iodine formulations from European manufacturing sites balance against import dependence for kinase inhibitor APIs in several major markets. Japan and the United States absorb the highest volumes of molecularly targeted agents, while Germany and Switzerland anchor radiopharmaceutical production for cross-border supply.
United States
FDA breakthrough therapy designations for RET and BRAF inhibitors accelerate commercial timelines for novel kinase inhibitors. The IRA's drug pricing provisions create reimbursement negotiation pressure for established oncology agents. Integrated delivery networks in Texas and California consolidate formulary purchasing power across twenty major health systems.
Japan
Elevated papillary thyroid cancer incidence among patients over 65 expands demand for molecularly targeted agents in Tokyo and Osaka treatment centers. The PMDA sakigake framework accelerates priority review for therapies addressing rare thyroid malignancies. Kansai region academic medical centers anchor regional referral patterns for complex anaplastic carcinoma cases.
Germany
EMA PRIME eligibility expedites scientific advice and marketing authorization for priority medicines in medullary thyroid cancer. REACH compliance obligations constrain radiopharmaceutical input sourcing from Belgian isotope production facilities. Bavarian hospital pharmacies coordinate cold chain logistics for Iodine-131 distribution to dosing centers across Baden-Württemberg and North Rhine-Westphalia.
Switzerland
Swissmedic's alignment with EMA centralized procedures streamlines market access for kinase inhibitors developed for differentiated thyroid carcinomas. The country's radiopharmaceutical manufacturing infrastructure supports radioactive iodine supply security for neighboring European markets. Basel and Zurich treatment centers concentrate molecular pathology expertise for RET fusion interpretation.
Global Thyroid Cancer Drugs Market Competitive Landscape
Listed leaders compete with private specialists across precision-targeted and broad-spectrum therapeutic portfolios. The market structure bifurcates between large-cap pharmaceutical developers with radiopharmaceutical manufacturing capabilities and biotechnology specialists focused on kinase selectivity. Three archetypes dominate: diversified oncology majors with radioactive iodine infrastructure, precision-therapy biotechs with biomarker-driven development, and cross-tumor pathway specialists leveraging melanoma or lung cancer indications. Competitive moves concentrate on companion diagnostic co-development partnerships and radiopharmaceutical supply security investments.
Within the diversified oncology tier, Novartis AG and Bayer AG exemplify players with integrated radiopharmaceutical manufacturing capabilities. Eisai Co., Ltd occupies a position among precision-therapy specialists with differentiated thyroid carcinoma focus. Exelixis Inc represents the kinase inhibitor specificity archetype commanding premium reimbursement positioning in North American oncology clinics.
| Leading Market Players |
|---|
| Novartis AG |
| Eisai Co., Ltd |
| Bayer AG |
| AstraZeneca |
| Roche |
| Pfizer Inc |
| Bristol-Myers Squibb |
| Exelixis Inc |
| Takeda Pharmaceutical Company |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for radioactive iodine isotopes lock in supply access and price visibility for European treatment centers, while kinase inhibitor procurement through United States integrated delivery networks compresses margins through portfolio-level negotiation leverage.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing structures for precision-targeted kinase inhibitors in North American oncology clinics. Pricing stratifies across premium RET-selective agents, standard multikinase inhibitors, and economy-tier cytotoxic alternatives based on biomarker specificity and companion diagnostic bundling. Cost compression in radioactive iodine formulations is intensifying because European health technology assessment bodies impose reference pricing across Germany and France. Community oncology practices exhibit highest price sensitivity due to limited formulary autonomy, while academic medical centers with embedded molecular tumor boards command premium positioning through specialized case volume.
Supply Chain Analysis
Eight-day half-life constraints for Iodine-131 demand just-in-time inventory coordination between Belgian isotope production facilities and German dosing centers. Active pharmaceutical ingredient manufacturing for tyrosine kinase inhibitors concentrates in India, Switzerland, and the United States, with formulation finishing anchored in regional hubs serving Japan and North America. Supply chain risk centers on single-source vulnerability for radioactive iodine production, where reactor maintenance schedules at limited European facilities create dosing interruption exposure. Distribution runs through direct hospital supply channels for radiopharmaceuticals and wholesale intermediaries for oral small-molecule agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic co-development services and biomarker laboratory partnerships expand faster than standalone drug revenues, creating recurring-revenue layers that outpace hardware-style pharmaceutical manufacturing margins.
For Market Incumbents: Secure radiopharmaceutical manufacturing infrastructure through captive isotope production or exclusive reactor offtake agreements to defend against supply interruption risks from Belgian facility concentration. Deepen vertical integration into companion diagnostic development to lock in biomarker-driven patient stratification workflows and strengthen formulary positioning against cross-tumor pathway substitutes encroaching from melanoma indications. For New Entrants and Emerging Players: Differentiate on RET-selectivity profiles and anaplastic thyroid carcinoma orphan-disease focus to bypass saturated papillary cancer segments dominated by established multikinase portfolios. Target Japan's aging demographic clusters and PMDA sakigake accelerated review pathways as the most penetrable geography, leveraging telemedicine-enabled trial recruitment to access rural United States populations underserved by academic medical center concentration. For Investors and Strategic Acquirers: Capital is best deployed toward precision-therapy biotechs with biomarker-driven development capabilities and EMA PRIME eligibility positioning over broad-spectrum oncology majors facing reimbursement compression. Long-term viability hinges on portfolio durability against biosimilar entry and radiopharmaceutical supply security investments. The signal to watch is FDA breakthrough therapy designation frequency for novel kinase targets, indicating regulatory pathway efficiency and premium pricing persistence.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Biomarker integration with RET-selective agents strengthens reimbursement positioning in United States integrated delivery networks. |
| Radiopharmaceutical Supply Security Investment | Captive isotope production infrastructure mitigates Belgian reactor concentration risk for European dosing centers. |
| EMA PRIME Eligibility Restructuring | Priority medicines status accelerates scientific advice timelines for anaplastic thyroid carcinoma development programs. |
| Telemedicine-Enabled Trial Recruitment | Virtual patient monitoring expands geographic reach for decentralized studies accessing rural United States populations. |
| Next-Generation Sequencing Platform Partnership | Real-time biomarker infrastructure integration compresses diagnosis-to-treatment windows in community oncology settings. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market size estimation across the analysis window.
Segmentation dimensions modeled include drug type, therapy area, end user site-of-care capabilities, and distribution channel cold chain requirements throughout the forecast period. CAGRs were derived from treatment volume projections, pricing trajectory assumptions, and regulatory approval pathway timelines. Forecast inputs incorporated biomarker prevalence rates, companion diagnostic adoption curves, and radiopharmaceutical supply capacity utilization.
Forecasts assume regulatory continuity in FDA breakthrough therapy designations and EMA PRIME eligibility schemes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Roflumilast API Market