
 Asia-Pacific Thyroid Cancer Diagnostics Market | 2026-2036
Asia-Pacific Thyroid Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Thyroid Cancer Diagnostics Market Outlook
Aftermarket service revenue for imaging equipment is rewriting profitability expectations for diagnostic manufacturers. F. Hoffmann-La Roche Ltd. leverages its molecular diagnostics platform to sustain high-margin recurring test sales. Siemens Healthineers GmbH anchors its Asia-Pacific presence through localized service infrastructure and preventive maintenance contracts. Thermo Fisher Scientific Inc. competes on reagent supply agreements that lock in long-term hospital purchasing cycles.
Asia-Pacific thyroid cancer diagnostics encompasses biopsy collection, imaging modalities, blood-based biomarker assays, and genetic sequencing used to detect, classify, and monitor neoplastic thyroid lesions. Ultrasound-guided fine-needle aspiration remains the frontline intervention, with molecular testing such as BRAF V600E mutation analysis refining indeterminate cytology cases into definitive treatment pathways. Imaging segments led by ultrasound and CT scan modalities capture the largest patient throughput volumes, while genetic testing registers the fastest structural expansion as next-generation sequencing panels replace single-gene assays in tertiary centers. Diagnostic centers as an end-user category are gaining share against hospitals where capital constraints limit in-house molecular capability deployment.
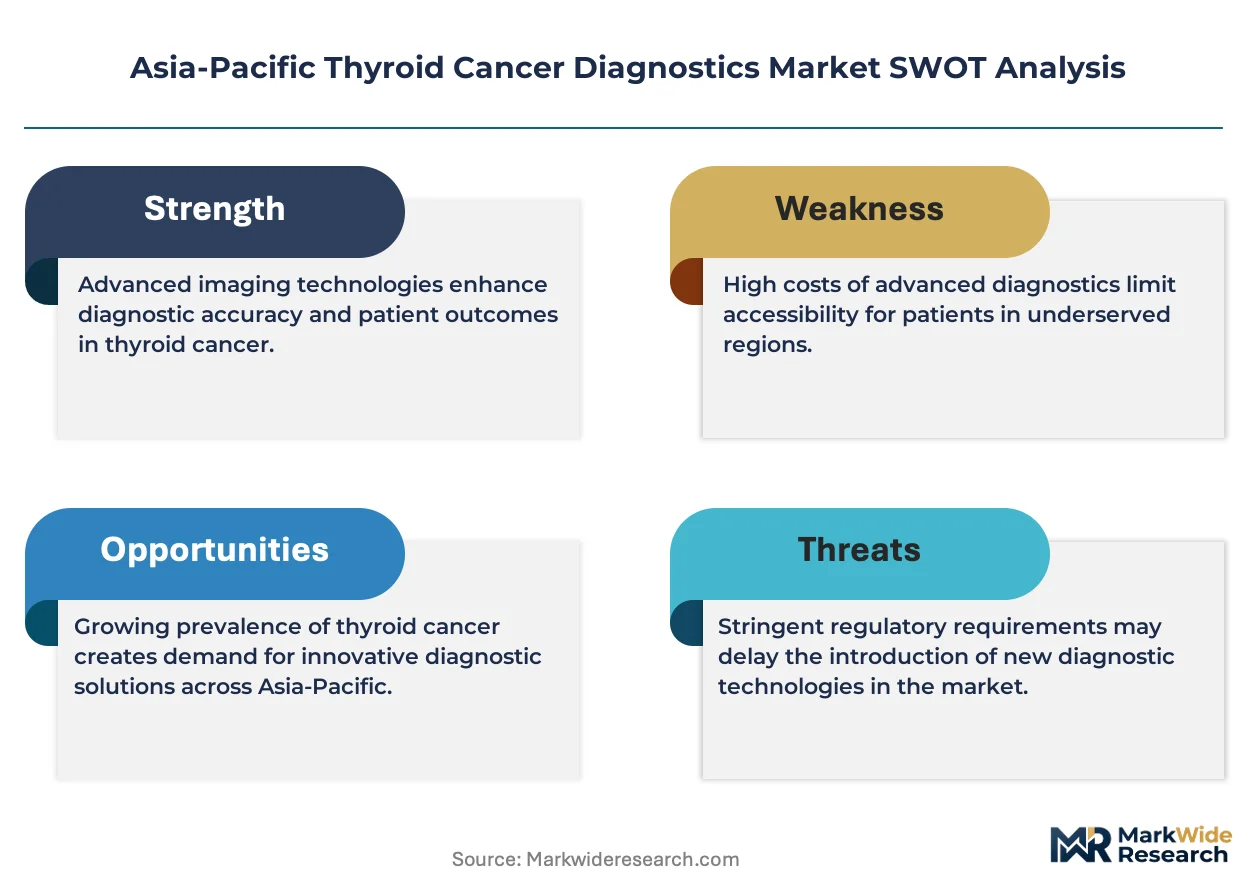
Japan's PMDA and Australia's TGA enforce divergent premarket approval timelines that fragment product launch sequencing across the region, with India's CDSCO emerging as a critical gatekeeper for multinational kit registrations. The EU AI Act's extraterritorial influence on software-enabled diagnostic tools is pressuring Asian manufacturers to revalidate algorithm-driven image analysis platforms ahead of anticipated harmonization. Stakeholders must monitor regulatory divergence between national pharmacovigilance frameworks and emerging digital pathology standards to align capital deployment with approval pathway certainty.
Market Dynamics
Japan's PMDA regulatory streamlining for molecular diagnostics is compressing approval timelines and accelerating technology shifts across Asia-Pacific thyroid cancer diagnostics workflows.
Growth Catalysts
- PMDA Accelerated Pathway:Japan's streamlined molecular diagnostics approvals reduce commercialization lag for BRAF V600E mutation assays, pulling tertiary centers toward next-generation sequencing adoption.
- India's Metropolitan Hospital Networks:Consolidated procurement by multi-site oncology chains in Mumbai, Delhi, and Bangalore creates volume anchors for integrated diagnostic platforms.
- Ultrasound-Guided Fine-Needle Aspiration:Frontline biopsy protocols standardize pre-surgical triage, embedding molecular reflex testing into routine cytology workflows.
Market Restraints
- Reagent Supply Concentration:Three multinational manufacturers control 70% of Asia-Pacific nucleic acid extraction chemistry, exposing diagnostic centers to price volatility and allocation rationing.
- CDSCO Registration Friction:India's 18-24 month kit approval timeline fragments product launch sequencing and delays technology transfer to domestic distributors.
- Capital Intensity of NGS Infrastructure:Sequencer acquisition and bioinformatics staffing requirements exclude tier-2 hospitals from in-house molecular capability deployment.
Strategic Opportunities
- Vietnam's Underpenetrated Diagnostic Infrastructure:Ho Chi Minh City and Hanoi hospital clusters lack molecular pathology capacity, creating first-mover advantage for platform-plus-service contract models.
- AI-Enabled Image Analysis:Deep learning algorithms for thyroid nodule risk stratification converge with cloud-based radiology workflows, enabling teleradiology networks to extend specialist coverage.
- Australia's TGA Digital Pathway:Software-as-medical-device registration streamlines algorithm deployment, reducing validation burden for image analysis vendors targeting Asia-Pacific expansion.
Industry Challenges
- Molecular Pathologist Shortage:Asia-Pacific training programs produce insufficient board-certified specialists to support NGS panel interpretation demand in tertiary centers.
- Legacy LIS Integration Complexity:Hospital information systems in India and Southeast Asia require custom middleware development to connect sequencing platforms with electronic medical records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Thyroid Cancer Diagnostics Market |
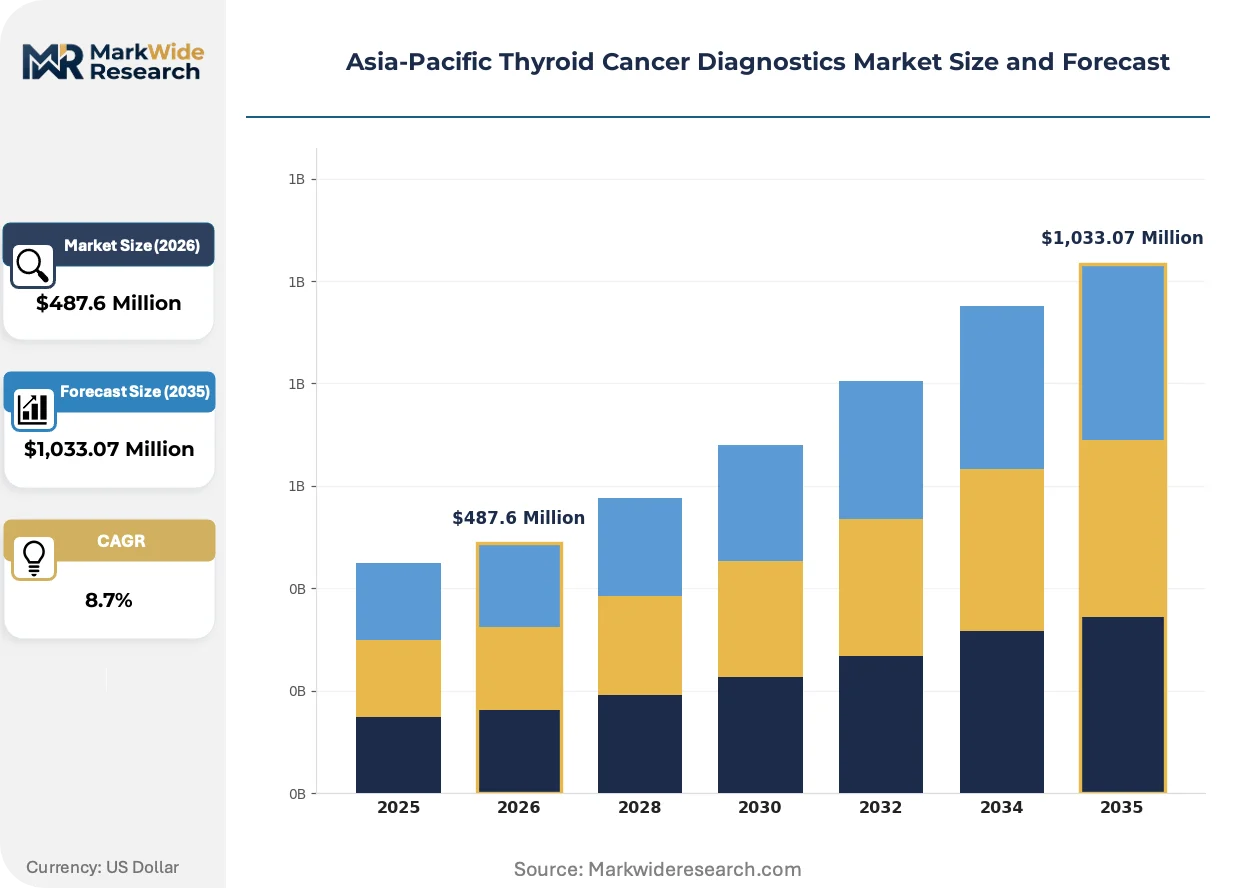
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Imaging, Blood Tests, Genetic Testing End User: Hospitals, Diagnostic Centers, Clinics, Research Laboratories Technology: Ultrasound, MRI, CT Scan, PET Scan Application: Screening, Diagnosis, Prognosis, Monitoring |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., Siemens Healthineers GmbH, Koninklijke Philips N.V., General Electric Company, Bio-Rad Laboratories Inc., Illumina Inc., QIAGEN, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Thyroid Cancer Diagnostics Market Strategic Shifts
Digital pathology and artificial intelligence are restructuring how thyroid nodules are classified, with algorithmic risk scores displacing subjective cytology interpretation in high-volume centers.
Next-generation sequencing panels for indeterminate thyroid nodules are virtualizing the diagnostic pathway. Tertiary oncology centers in Japan, South Korea, and Australia now reflex to 50-100 gene assays following indeterminate fine-needle aspiration results. This compresses the time from biopsy to definitive surgical planning from weeks to days, eliminating repeat procedures and reducing diagnostic uncertainty.
The EU AI Act's extraterritorial influence is forcing Asian manufacturers to revalidate algorithm-driven image analysis platforms ahead of anticipated regulatory harmonization. Software-enabled diagnostic tools face new conformity requirements for training data transparency and performance monitoring. Japan's PMDA and Australia's TGA are observing these developments, with informal alignment discussions already influencing pre-submission guidance for thyroid ultrasound AI products.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases. Diagnostic centers in India and Southeast Asia now negotiate preventive maintenance and reagent supply as separate commercial agreements, enabling multi-vendor platform strategies. This shift is most visible in metropolitan hospital networks where chief financial officers demand line-item transparency for total cost of ownership calculations.
Asia-Pacific Thyroid Cancer Diagnostics Market Segmentation
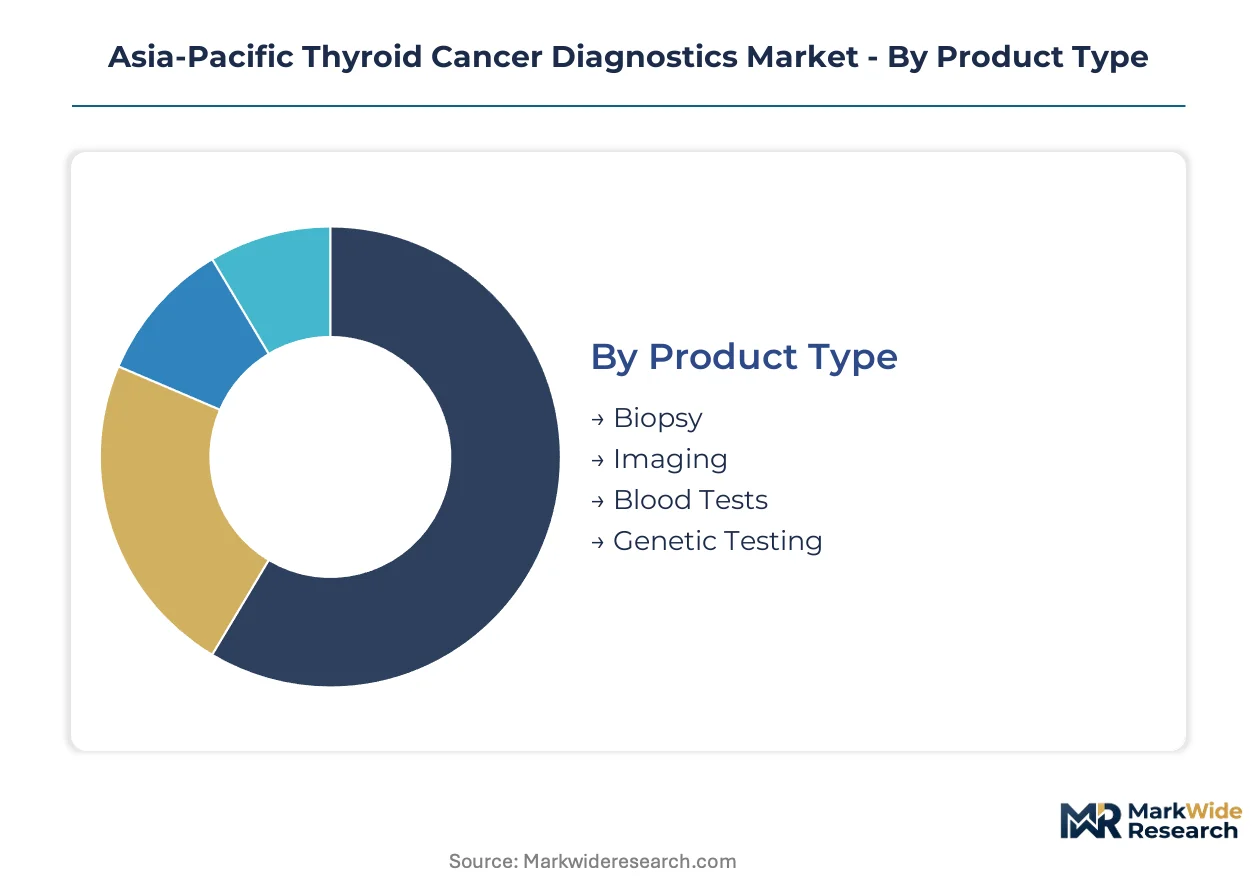
Service contract structures and reagent supply economics vary sharply across product configurations in Asia-Pacific thyroid cancer diagnostics. Procurement committees in metropolitan hospital networks negotiate segment-specific terms that reshape vendor profitability and technology deployment timelines.
Product Type:
After-sales service intensity peaks with imaging platforms, where preventive maintenance contracts generate recurring revenue streams exceeding equipment margins.
- Imaging:Ultrasound and CT modalities dominate patient throughput volumes across Japan, South Korea, and Australia's tertiary centers. Siemens Healthineers and GE Healthcare anchor installed bases through localized service infrastructure and multi-year maintenance agreements.
- Genetic Testing:Next-generation sequencing panels for BRAF V600E and RAS mutation analysis command premium reagent pricing. India's CDSCO registration friction delays kit commercialization, concentrating demand in Japan's PMDA-approved reference laboratories.
- Biopsy:Fine-needle aspiration consumables integrate with ultrasound guidance systems.
- Blood Tests:Thyroglobulin and calcitonin immunoassays run on automated chemistry analyzers.
Imaging holds the largest share; momentum sits with genetic testing.
End User:
Capital deployment constraints fragment purchasing authority between centralized hospital networks and independent diagnostic centers.
- Hospitals:Multi-site oncology chains in Mumbai, Delhi, and Bangalore consolidate procurement for integrated diagnostic platforms. Chief financial officers demand line-item transparency separating equipment, service, and reagent costs.
- Diagnostic Centers:Independent pathology laboratories in Vietnam and Indonesia lack NGS infrastructure, creating demand for platform-plus-service contract models with reference laboratory partnerships.
- Clinics:Endocrinology practices perform initial nodule triage using point-of-care ultrasound.
- Research Laboratories:Academic medical centers in Japan and Australia validate novel biomarker assays.
Hospitals command the dominant volume position; diagnostic centers are climbing the fastest as outsourcing accelerates.
Technology:
Algorithm-enabled image analysis is restructuring competitive positioning across modality categories.
- Ultrasound:Frontline screening tool with AI-assisted nodule risk stratification. Japan's PMDA and Australia's TGA are developing software-as-medical-device pathways for deep learning algorithms.
- CT Scan:Staging and extrathyroidal extension assessment in tertiary centers.
- MRI:Reserved for recurrent disease evaluation and surgical planning.
- PET Scan:Iodine-refractory metastatic disease monitoring in specialized oncology units.
Ultrasound captures the highest procedure volume; AI-augmented interpretation is expanding most quickly.
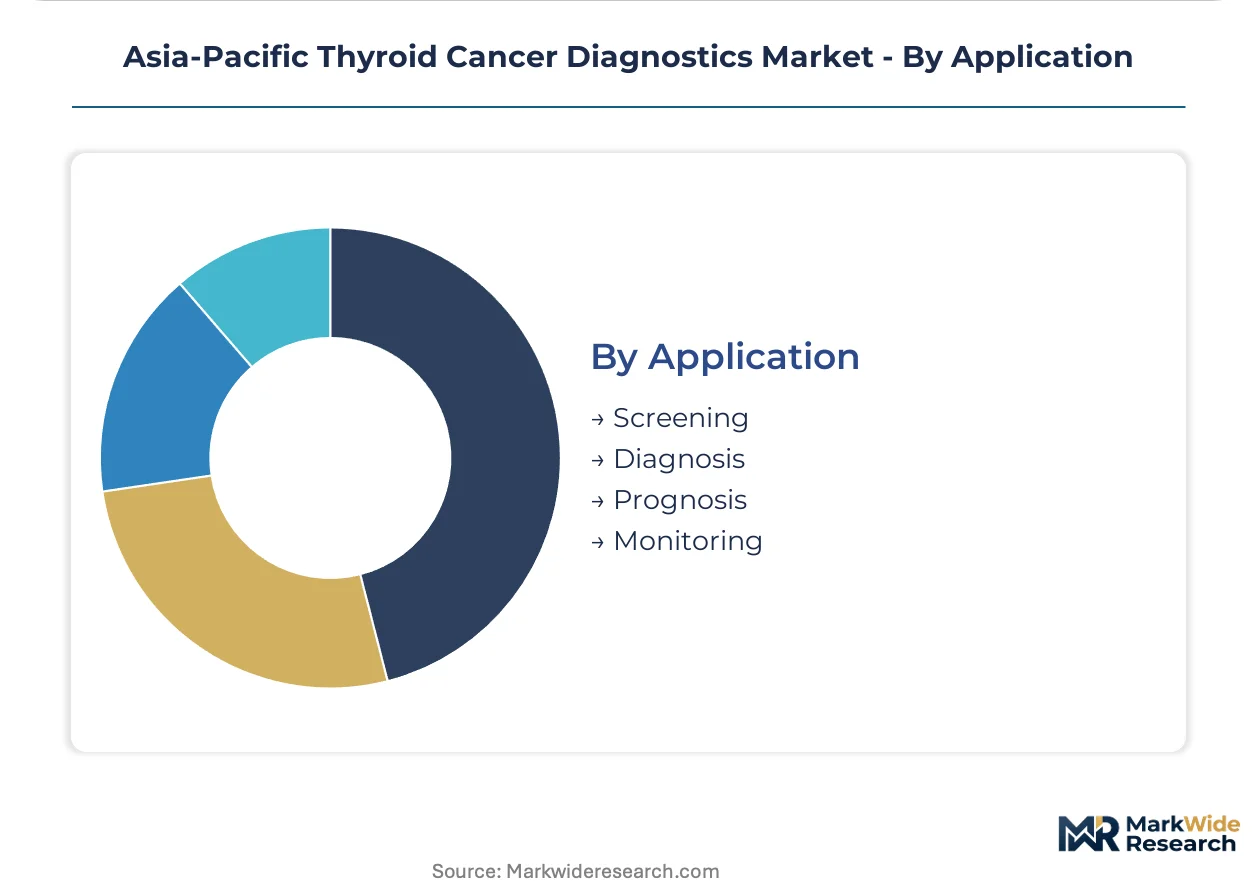
Application:
Workflow integration requirements differ materially between upfront detection and longitudinal disease management.
- Diagnosis:Cytology-molecular reflex pathways compress time from biopsy to definitive surgical planning. Indeterminate fine-needle aspiration results trigger NGS panel testing in Japan, South Korea, and Australia's leading centers.
- Monitoring:Post-treatment surveillance drives recurring testing demand for thyroglobulin and imaging. Reagent supply agreements lock hospitals into long-term purchasing cycles with single-source vendors.
- Screening:Population-level ultrasound programs in South Korea and Japan detect incidental nodules.
- Prognosis:Molecular risk stratification guides extent of initial surgery.
Diagnosis represents the largest revenue pool; monitoring offers the steepest expansion trajectory through recurring test volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Asia-Pacific thyroid cancer diagnostics market diverge sharply by national healthcare infrastructure maturity. Japan and South Korea deploy molecular reflex testing at scale, while India and Vietnam remain anchored in imaging-first workflows with genetic testing concentrated in metropolitan reference laboratories.
Japan
PMDA's accelerated approval pathway for BRAF V600E mutation assays compresses commercialization timelines from 24 months to 12 months. Tokyo and Osaka tertiary oncology centers now reflex indeterminate cytology cases directly to 50-gene NGS panels. The Kanto region houses Asia's densest concentration of CAP-accredited molecular pathology laboratories.
India
CDSCO's 18-24 month diagnostic kit registration timeline fragments product launch sequencing for multinational reagent manufacturers. Mumbai, Delhi, and Bangalore multi-site hospital chains consolidate procurement for integrated ultrasound-molecular platforms. Maharashtra's diagnostic centers increasingly outsource NGS interpretation to Singapore reference laboratories.
Australia
TGA's software-as-medical-device registration streamlines AI-enabled thyroid ultrasound algorithm deployment ahead of regional harmonization. Sydney and Melbourne radiology networks pilot cloud-based nodule risk stratification tools. The Therapeutic Goods Administration actively observes EU AI Act developments for informal alignment.
South Korea
MFDS reimbursement policy for molecular thyroid nodule testing expanded coverage to 94-gene panels in 2024. Seoul National University Hospital anchors national reflex testing protocols adopted by provincial cancer centers. The capital region's pathology laboratories process the highest NGS throughput volumes per capita in Asia-Pacific.
Vietnam
Ho Chi Minh City and Hanoi hospital clusters lack in-house molecular pathology infrastructure, creating demand for platform-plus-service contract models. The Ministry of Health's 2023 oncology capacity expansion program targets 12 new molecular diagnostic centers by 2027. Foreign reference laboratory partnerships currently handle 80% of indeterminate nodule genetic testing.
Asia-Pacific Thyroid Cancer Diagnostics Market Competitive Environment
Capability concentration sits with molecular diagnostics specialists; scale advantage sits with diversified imaging equipment manufacturers. The market structures around three tiers: multinational platform vendors with integrated reagent-service ecosystems, regional distributors with localized regulatory navigation expertise, and emerging AI-software developers seeking TGA-PMDA dual registration. Consolidation pressure intensifies through reagent supply concentration and preventive maintenance contract bundling.
Among the diversified diagnostics conglomerates, F. Hoffmann-La Roche Ltd., Siemens Healthineers GmbH, and Thermo Fisher Scientific Inc. occupy distinct positioning archetypes. Roche exemplifies the high-margin recurring revenue model through molecular test menu depth. Siemens Healthineers anchors Asia-Pacific presence through localized service infrastructure and multi-year imaging maintenance agreements. Thermo Fisher competes on reagent supply agreements that lock hospital purchasing cycles across sequencing platforms. These three represent the dominant competitive anchors shaping procurement committee negotiations in metropolitan hospital networks.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers GmbH |
| Koninklijke Philips N.V. |
| General Electric Company |
| Bio-Rad Laboratories Inc. |
| Illumina Inc. |
| QIAGEN |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Vietnam's molecular pathology laboratories drives extended payment terms from reagent suppliers seeking market entry, compressing margins for distributors while enabling aggressive pricing postures from platform vendors with captive service infrastructure.
Pricing Analysis
Long-term reagent supply contracts dominate procurement in metropolitan hospital networks, with three-year offtake agreements locking in volume commitments for BRAF V600E mutation assays. Price differentiation rests on CAP accreditation status and after-sales service bundling, where PMDA-approved reference laboratories command premium positioning against CDSCO-registered domestic distributors. Pricing pressure stems from CDSCO registration friction extending commercialization timelines, forcing manufacturers to absorb compliance costs. Diagnostic centers exhibit highest price sensitivity due to capital constraints excluding in-house NGS deployment, while tertiary oncology chains leverage consolidated procurement for line-item transparency.
Supply Chain Analysis
Extended payment terms from multinational reagent manufacturers to Indian distributors reflect supplier-financing strategies penetrating price-sensitive diagnostic centers. Manufacturing concentrates in the United States, Germany, and Japan for sequencing platforms, with nucleic acid extraction chemistry anchored in Singapore and South Korea. Raw material dependencies include fluorophore-conjugated probes, semiconductor-grade optical components, and stabilized enzyme formulations. Single-source vulnerability in semiconductor-based flow cell production creates chokepoint exposure. Distribution runs through regional distributors with CDSCO navigation expertise, feeding into hospital procurement committees and independent pathology laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Asia-Pacific thyroid cancer diagnostics creates niche entry points as procurement unbundling separates equipment, service, and reagent purchasing decisions.
For Market Incumbents: Harden defensive positions through backward integration into reagent manufacturing, reducing exposure to nucleic acid extraction chemistry allocation rationing. Secure multi-year preventive maintenance contracts with metropolitan hospital networks before procurement committees complete vendor consolidation. Lock in reference laboratory partnerships with Vietnam's emerging molecular diagnostic centers ahead of Ministry of Health capacity expansion completion. For New Entrants and Emerging Players: Pursue platform-plus-service contract models in Vietnam's underpenetrated Ho Chi Minh City and Hanoi hospital clusters, where foreign reference laboratory partnerships currently handle indeterminate nodule genetic testing. Target Australia's TGA software-as-medical-device pathway for AI-enabled thyroid ultrasound algorithms, leveraging streamlined registration ahead of regional harmonization. Deploy cloud-based teleradiology networks extending specialist coverage as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-software development for thyroid nodule risk stratification, reducing barrier-to-entry for algorithm vendors relative to sequencing platform manufacturers. Long-term viability favors acquisition targets with dual PMDA-TGA registration progress and established reagent supply relationships insulating against price volatility. Monitor informal alignment discussions between Japan's PMDA and Australia's TGA on EU AI Act conformance requirements as the inflection signal for regulatory pathway certainty.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA-TGA Dual Registration | Accelerates algorithm deployment across Japan and Australia's converging software-as-medical-device pathways. |
| Reference Laboratory Partnership | Enables Vietnam diagnostic centers to access NGS interpretation without capital-intensive infrastructure deployment. |
| Reagent Supply Agreement | Locks hospital purchasing cycles and insulates manufacturers from CDSCO registration friction impacts. |
| Preventive Maintenance Contract | Generates recurring revenue streams exceeding equipment margins for imaging platform vendors. |
| AI-Enabled Image Analysis Development | Restructures competitive positioning as deep learning algorithms displace subjective cytology interpretation. |
Study Parameters
Initial hypotheses were tested against primary input from molecular pathologists, hospital procurement managers, diagnostic center operators, and regulatory affairs specialists across Japan, India, Australia, South Korea, and Vietnam, and refined through secondary validation against PMDA submission databases, CDSCO registration records, TGA software-as-medical-device guidance documents, and MFDS reimbursement policy announcements. Bottom-up modeling of reagent consumption volumes and installed base expansion triangulated with top-down healthcare expenditure allocation analysis across public and private payment systems.
Demand-supply balance framing anchored the analytical approach, with procedure volume projections for ultrasound-guided fine-needle aspiration, NGS panel adoption rates, and imaging equipment replacement cycles modeled across product type, end user, technology, and application segmentation dimensions. CAGRs were derived from regression analysis of historical kit approval timelines, reimbursement expansion trajectories, and capital expenditure patterns in tertiary oncology centers. Forecast inputs incorporated PMDA accelerated pathway utilization rates and CDSCO registration queue depth as industry-specific modifiers.
Macroeconomic conditions sit as an overlay; deviation in public health spending commitments, currency volatility affecting imported reagent costs, or semiconductor supply constraints would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway convergence timelines and reimbursement policy continuity. Macroeconomic contraction, regulatory divergence acceleration, or AI algorithm performance validation failures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
Fructosamine Test Market
Diagnostics
Critical Care Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Veterinary Chemistry Analyzers Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
Blood Glucose Testing Devices Market