
 Thrombosis and Hemostasis Biomarkers Market | 2026-2036
Thrombosis and Hemostasis Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Thrombosis and Hemostasis Biomarkers Market Analytics
Multi-source procurement of hemostasis reagents is shifting toward consolidated vendor agreements as health systems seek volume pricing and interoperability guarantees. Thermo Fisher Scientific leverages its clinical chemistry installed base to bundle coagulation assays with core laboratory platforms. Abbott competes through point-of-care coagulation devices that extend testing from central labs into emergency departments and surgical suites. Siemens Healthineers anchors its position in high-volume hospital laboratories through automated hemostasis analyzers with random-access throughput.
Thrombosis and hemostasis biomarkers comprise measurable molecular indicators—encompassing D-dimer, prothrombin fragment 1+2, thrombin-antithrombin complexes, and platelet activation markers—that quantify coagulation cascade activity, fibrinolytic status, or endothelial dysfunction in biological specimens. These biomarkers serve primarily to stratify thrombotic risk, monitor anticoagulant therapy, and diagnose disseminated intravascular coagulation or pulmonary embolism in acute care settings. Anticoagulant biomarker assays occupy the largest revenue share within product categories, reflecting chronic warfarin and direct oral anticoagulant monitoring needs, while immunoassay technology leads instrument placements due to its sensitivity for low-abundance coagulation fragments. Mass spectrometry applications in hemostasis represent the fastest-growing technology segment, driven by multiplexed protein quantification for research and specialized coagulation disorder panels.
The FDA regulates hemostasis diagnostics as Class II medical devices requiring 510(k) premarket notification, while the Clinical Laboratory Improvement Amendments mandate proficiency testing for laboratories performing moderate- and high-complexity coagulation assays. The European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements on coagulation biomarker kits, extending conformity assessment timelines for manufacturers seeking CE marking. Stakeholders must monitor how evolving premarket submission requirements on both sides of the Atlantic reshape competitive barriers and partnership strategies between assay developers and platform manufacturers.
Market Dynamics
Hospital laboratories are consolidating hemostasis testing into integrated core lab platforms, compressing vendor relationships and forcing assay developers to embed their reagents into closed-system architectures controlled by major platform manufacturers.
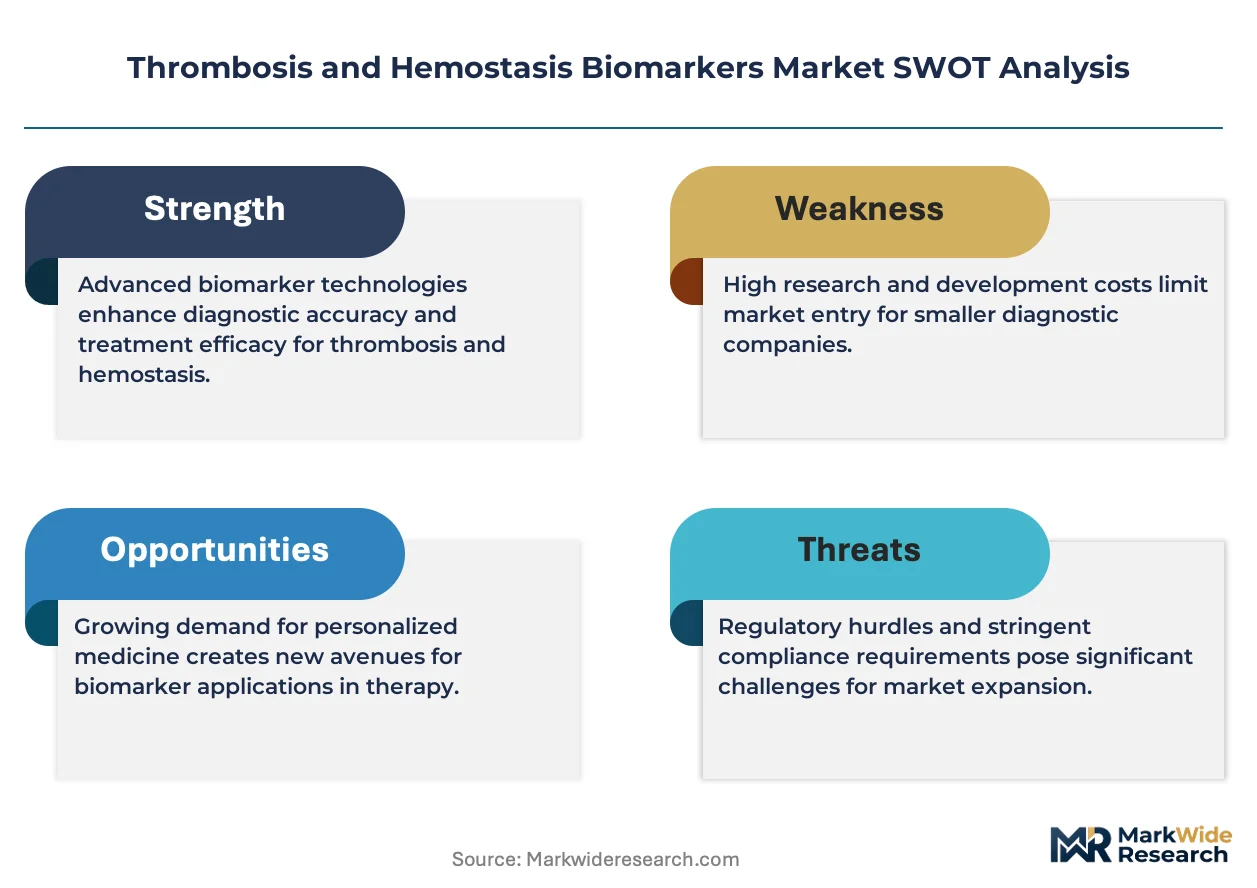
Growth Catalysts
- Anticoagulant therapy expansion:Direct oral anticoagulant monitoring protocols are proliferating across emergency medicine and perioperative care, creating sustained demand for rapid-turnaround coagulation panels.
- IVDR compliance mandates:The European Union's In Vitro Diagnostic Regulation is accelerating replacement of legacy hemostasis assays with CE-IVDR-certified alternatives, opening procurement windows for validated kit suppliers.
- Point-of-care decentralization:Surgical suites and catheterization laboratories are installing cartridge-based coagulation analyzers to bypass central lab bottlenecks during critical bleeding events.
Market Restraints
- Reagent supply concentration:High-purity antibody and recombinant protein inputs for D-dimer and thrombin-complex assays depend on a limited supplier base concentrated in Germany and Switzerland.
- Platform lock-in effects:Automated hemostasis analyzers from Siemens Healthineers and Sysmex operate on proprietary reagent protocols, creating switching costs that entrench incumbent positions.
- Clinical validation burden:FDA 510(k) submissions for novel coagulation biomarkers require extensive analytical and clinical studies, extending time-to-market by 18-36 months for assay developers.
Strategic Opportunities
- Mass spectrometry multiplexing:Liquid chromatography-tandem mass spectrometry is unifying protein quantification workflows for rare coagulation disorder research, opening specialized reference laboratory contracts.
- India's diagnostic infrastructure buildout:The country's PLI scheme for medical devices is incentivizing local manufacturing of coagulation consumables to serve tier-2 and tier-3 hospital networks.
- Integrated health network consolidation:United States-based IDNs are negotiating enterprise-wide hemostasis contracts spanning 50-200 hospital sites, rewarding vendors with interoperability guarantees and volume pricing frameworks.
Industry Challenges
- Specialized hematopathology staffing:Interpretation of complex coagulation profiles requires board-certified specialists, and recruitment lags instrument installation rates across community hospital systems.
- Laboratory information system integration:Middleware connectivity between point-of-care coagulation devices and electronic health records demands customized HL7/FHIR mapping, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thrombosis and Hemostasis Biomarkers Market |
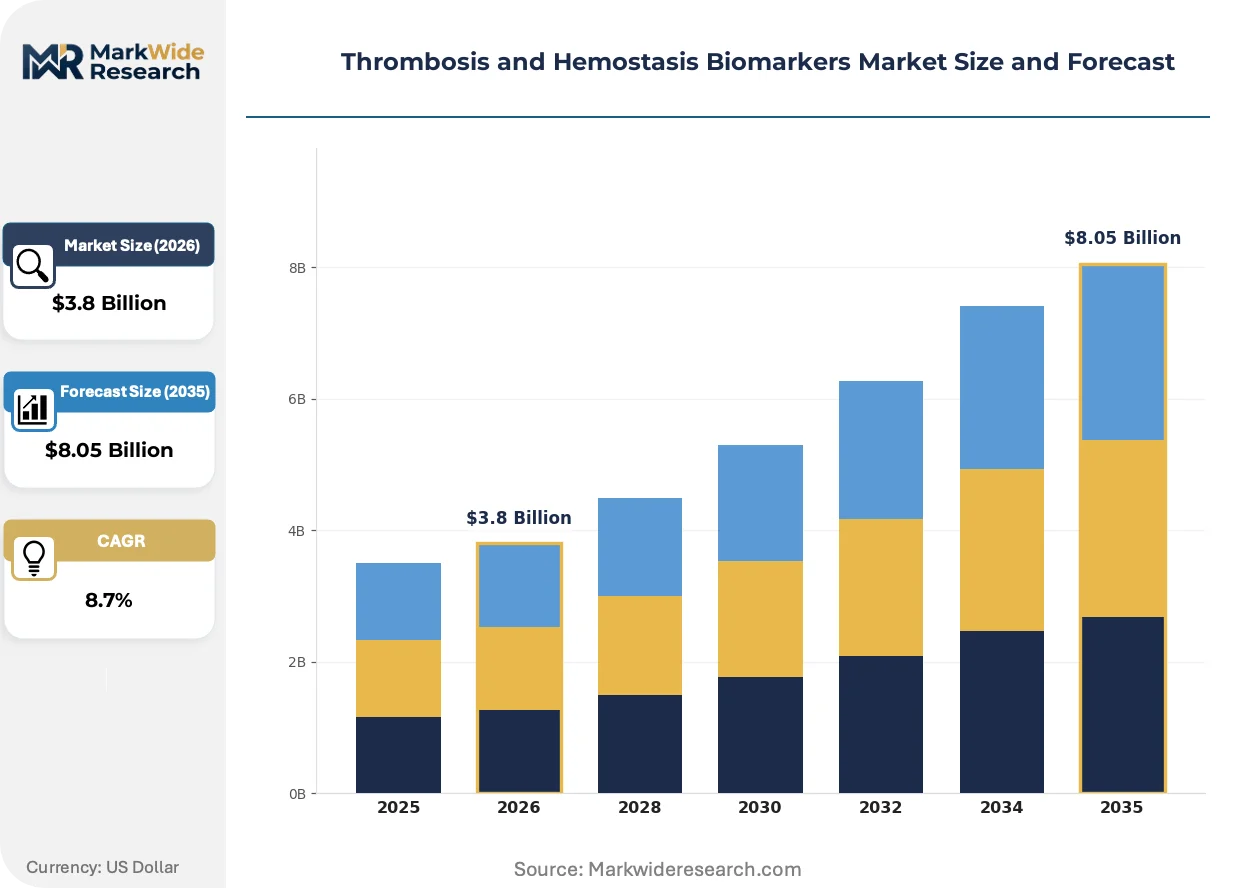
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Thrombolytics, Platelet Aggregation Inhibitors, Fibrinogen Assays Application: Cardiology, Neurology, Hematology, Emergency Medicine End User: Hospitals, Diagnostic Laboratories, Research Institutions, Blood Banks Technology: ELISA, PCR, Immunoassays, Mass Spectrometry |
| Companies Covered | Thermo Fisher Scientific, Inc., F. Hoffmann-La Roche Ltd., Siemens Healthineers, Abbott, bioMérieux SA, Werfen, HORIBA Ltd., QuidelOrtho Corporation, BioMedica Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thrombosis and Hemostasis Biomarkers Market Evolving Landscape
Digital pathology and artificial intelligence are converging with automated hemostasis workflows to compress diagnostic decision cycles and reduce manual slide review burdens in high-volume coagulation laboratories.
Mass spectrometry platforms are unifying hemostasis biomarker quantification by enabling simultaneous measurement of multiple coagulation fragments and fibrinolytic markers in a single analytical run. Academic medical centers and specialized coagulation reference laboratories are adopting these systems to support rare bleeding disorder research and personalized anticoagulant dosing protocols. This technology is unifying previously fragmented immunoassay workflows into consolidated analytical pipelines, reducing sample volume requirements and reagent costs per test.
The FDA's evolving guidance on laboratory-developed tests is tightening analytical validation requirements for hemostasis assays developed and performed within single institutions. Manufacturers of commercial coagulation kits must now demonstrate equivalence to predicate devices through expanded precision and accuracy studies. High-complexity hospital laboratories in the United States are responding by outsourcing esoteric coagulation testing to national reference laboratories with established LDT validation infrastructures.
Integrated delivery networks are consolidating hemostasis reagent procurement through single-source or dual-source vendor agreements that bundle consumables with analyzer service contracts. Independent community hospitals and regional reference laboratories are losing negotiating leverage as health system purchasing committees centralize decision-making. This concentration is most visible in the United States, where IDNs now control 60-70 percent of hospital-based coagulation testing volume and demand interoperability across multi-site instrument fleets.
Thrombosis and Hemostasis Biomarkers Market Segmentation
Segmentation in thrombosis and hemostasis biomarkers reveals divergent capital requirements and margin profiles across testing modalities. Product type and technology dimensions drive the steepest investment gradients, while application and end-user splits determine procurement concentration and contract scalability.
Product Type:
Anticoagulant assay platforms demand the heaviest upfront instrumentation investment, with automated analyzer systems requiring seven-figure capital deployment per installation site.
- Anticoagulants:These assays monitor warfarin, heparin, and direct oral anticoagulants through clotting time measurements and anti-factor activity quantification. Hospital laboratories in the United States are consolidating procurement around closed-system analyzers that lock in reagent contracts through proprietary calibrator protocols.
- Thrombolytics:Biomarker panels tracking tissue plasminogen activator efficacy and fibrin degradation products require specialized substrate chemistry. Academic medical centers deploy these assays in stroke centers and catheterization laboratories where rapid turnaround guides interventional decisions.
- Platelet Aggregation Inhibitors:Light transmission aggregometry and flow cytometry methods quantify aspirin and P2Y12 inhibitor response. Cardiology service lines drive demand concentration.
- Fibrinogen Assays:Clauss and PT-derived methods measure functional and total fibrinogen in trauma and obstetric hemorrhage protocols. Emergency departments prioritize cartridge-based implementations.
Most installed capacity flows through anticoagulant testing platforms. Expansion is steepest in thrombolytic biomarker panels as stroke network certification requirements proliferate.
Application:
Clinical volume concentrates in settings where anticoagulant therapy decisions carry immediate mortality consequences, creating procurement leverage for high-throughput assay formats.
- Cardiology:Atrial fibrillation management and post-percutaneous coronary intervention monitoring generate sustained demand for INR and anti-Xa assays. Integrated delivery networks in the United States negotiate enterprise contracts spanning 50-200 hospital sites for these applications.
- Neurology:Stroke triage protocols rely on D-dimer exclusion thresholds and rapid coagulation screening to determine thrombolysis eligibility. Mobile stroke units and telestroke networks are dispersing point-of-care testing into ambulances and community access hospitals.
- Hematology:Specialized coagulation reference laboratories handle rare bleeding disorder workups and pre-surgical evaluations for hemophilia patients. These assays demand factor activity quantification and inhibitor detection capabilities.
- Emergency Medicine:Pulmonary embolism rule-out criteria and trauma-induced coagulopathy panels require 30-minute turnaround targets that central laboratories struggle to meet.
Cardiology applications command the largest reagent contract values. Neurology is gaining share fastest as stroke system of care mandates expand across state-level health departments.
End User:
Customer type determines pricing tolerance and service contract structure, with hospital systems extracting steepest volume discounts through multi-year agreements.
- Hospitals:Core laboratories and point-of-care testing coordinators manage hemostasis portfolios spanning routine coagulation panels and specialized perioperative monitoring. The United States-based IDNs centralize procurement decisions at system level, compressing vendor relationships.
- Diagnostic Laboratories:National reference laboratories process esoteric coagulation send-outs that hospital laboratories lack analytical validation infrastructure to support. These facilities compete on turnaround time and interpretive reporting.
- Research Institutions:Mass spectrometry platforms and multiplexed protein quantification workflows support rare coagulation disorder discovery and personalized anticoagulant pharmacokinetic studies.
- Blood Banks:Donor screening and component processing quality control rely on rapid fibrinogen and factor assays with high throughput requirements.
Hospital laboratories absorb the majority of analyzer placements. Research institutions are expanding capacity most aggressively as mass spectrometry applications mature.
Technology:
Technology selection locks laboratories into reagent ecosystems and determines regulatory pathway complexity for new biomarker introductions.
- ELISA:Enzyme-linked immunosorbent assays provide standardized quantification of D-dimer, von Willebrand factor, and platelet activation markers with established FDA 510(k) predicate pathways. Community hospital laboratories favor these formats for their lower capital barriers.
- PCR:Genetic testing for factor V Leiden, prothrombin G20210A, and MTHFR variants supports thrombophilia risk stratification. Molecular diagnostics laboratories with existing nucleic acid extraction infrastructure extend into hemostasis genetics.
- Immunoassays:Chemiluminescent and electrochemiluminescent platforms dominate high-volume coagulation testing through random-access automation. Siemens Healthineers and Sysmex anchor this segment with closed-system architectures.
- Mass Spectrometry:Liquid chromatography-tandem mass spectrometry enables multiplexed protein quantification and peptide biomarker discovery for research and specialized reference applications. Academic medical centers lead adoption.
Immunoassay technology carries the broadest installed base. Mass spectrometry is climbing the fastest as proteomics pipelines consolidate previously fragmented workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as diagnostic producers relocate kit assembly to jurisdictions with streamlined medical device pathways. Cost-of-compliance gaps between the FDA's 510(k) framework and the EU's IVDR are accelerating this geographic redistribution.
United States
Integrated delivery networks in Texas and Florida are consolidating reference laboratory contracts across 50-200 hospital sites, compressing vendor relationships into enterprise-wide agreements. The FDA's evolving laboratory-developed test guidance is prompting manufacturers to strengthen clinical validation protocols. Boston's medical technology corridor anchors specialized coagulation reference laboratory capacity.
Germany
High-purity antibody and recombinant protein suppliers cluster in Baden-Württemberg and Bavaria, creating concentrated input dependencies for D-dimer and thrombin-complex assays. The EU's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements, extending conformity assessment timelines for CE marking. Siemens Healthineers anchors automated hemostasis analyzer production in Erlangen.
India
Tier-2 and tier-3 hospital networks in Maharashtra and Karnataka are expanding diagnostic infrastructure under the PLI scheme for medical devices. The country's national pharmaceutical regulator is streamlining import substitution pathways for coagulation consumables. Hyderabad's life sciences cluster is attracting contract manufacturing for hemostasis reagents.
Switzerland
Specialized protein chemistry and diagnostic substrate suppliers concentrate in Basel and Zurich, serving global assay manufacturers with limited alternative sourcing. Swissmedic maintains alignment with EU regulatory standards while offering accelerated review pathways for innovative biomarkers. The Basel biotech corridor sustains captive supply relationships with major platform producers.
China
Domestic diagnostic manufacturers in Shanghai and Suzhou are scaling chemiluminescent immunoassay platforms to displace imported hemostasis systems. The NMPA's medical device registration reforms are compressing approval timelines for Class II diagnostics. The Yangtze River Delta is consolidating reagent manufacturing for regional hospital procurement.
Thrombosis and Hemostasis Biomarkers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mass spectrometry multiplexing and point-of-care decentralization. The market structure reflects tiered consolidation around closed-system analyzer architectures and fragmented competition in specialized reference applications. Three archetypes dominate: platform-integrated conglomerates with captive reagent ecosystems, point-of-care specialists extending testing into emergency workflows, and proteomics-focused reference laboratories. Competitive moves concentrate on strategic partnerships between assay developers and platform manufacturers, alongside geographic expansion through IDN enterprise contracts.
Among platform-integrated conglomerates, Thermo Fisher Scientific leverages its clinical chemistry installed base to bundle coagulation assays with core laboratory systems. Siemens Healthineers exemplifies the high-volume hospital laboratory anchor position through automated analyzer deployments. Abbott occupies a distinct point-of-care vector, extending coagulation testing from central laboratories into emergency departments and surgical suites.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers |
| Abbott |
| bioMérieux SA |
| Werfen |
| HORIBA Ltd. |
| QuidelOrtho Corporation |
| BioMedica Diagnostics |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in the United States extract steep volume discounts through enterprise-wide hemostasis reagent contracts spanning 50-200 hospital sites, compressing vendor relationships into long-term agreements that bundle consumables with analyzer service contracts. This buyer concentration enables three-tier pricing structure across premium, standard, and economy levels, where closed-system analyzer manufacturers command premium positioning through proprietary calibrator protocols while independent reagent suppliers compete on price in open-system configurations.
Pricing Analysis
Distributor margins on hemostasis reagents typically range from 15-25 percent for regional laboratory supply distributors serving community hospitals, while direct-to-IDN contracts eliminate intermediary markups entirely in exchange for multi-year exclusivity commitments. Price differentiation hinges on FDA 510(k) clearance tier and IVDR certification status, with CE-IVDR-certified assays commanding 10-15 percent premiums over legacy CE-marked alternatives during the transition window. Pricing pressure stems from India's PLI scheme incentivizing local manufacturing of coagulation consumables, which is displacing imported reagent volumes in tier-2 and tier-3 hospital networks. Research institutions exhibit lowest price sensitivity due to grant-funded procurement, while independent diagnostic laboratories face acute margin compression from reference laboratory consolidation.
Supply Chain Analysis
CE-IVDR certification and FDA 510(k) clearance function as gating mechanisms that constrain supplier entry, with only a limited base of German and Swiss manufacturers qualified to produce high-purity antibodies and recombinant proteins for D-dimer and thrombin-complex assays. Supply concentrates in Baden-Württemberg and Bavaria for specialized protein chemistry, in Basel and Zurich for diagnostic substrates, and in Hyderabad's life sciences cluster for emerging contract manufacturing capacity. Raw material dependencies include monoclonal antibodies, recombinant coagulation factors, and specialized chromogenic substrates with limited alternative sourcing. Single-source vulnerability pervades the high-purity antibody tier, where sole-qualified suppliers serve multiple platform manufacturers simultaneously. Distribution runs through regional laboratory supply distributors in North America, direct manufacturer relationships with IDNs in the United States, and government procurement channels in India's tier-2 hospital expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thrombosis and hemostasis biomarkers market functions as a stable compounder anchored by chronic anticoagulant therapy expansion, where direct oral anticoagulant monitoring protocols generate recurring reagent demand with limited substitution risk.
For Market Incumbents: Acquire mass spectrometry proteomics capabilities to preempt displacement of immunoassay workflows in academic medical center reference laboratories. Consolidate backward integration into high-purity antibody production to reduce dependency on German and Swiss sole-source suppliers. Siemens Healthineers and Sysmex must defend their closed-system analyzer installed base against point-of-care decentralization by embedding cartridge-based coagulation testing into emergency department workflows. For New Entrants and Emerging Players: Regional reference laboratories in India's tier-2 and tier-3 networks represent the most penetrable channel partner type, with PLI scheme incentives reducing capital barriers for local manufacturing. Stroke center certification requirements in United States state health departments create white-space demand for rapid-turnaround thrombolytic biomarker panels that bypass entrenched central lab vendors. A go-to-market angle through telestroke network partnerships enables bypass of IDN procurement consolidation. For Investors and Strategic Acquirers: Platform-integrated diagnostic conglomerates are the most active acquirer in this space, seeking specialized coagulation reference laboratory capabilities to complete enterprise hemostasis portfolios. Long-term viability rests on mass spectrometry multiplexing adoption curves and IVDR compliance cost amortization across expanded assay menus. The signal to watch is FDA laboratory-developed test guidance enforcement intensity, which determines outsourcing velocity from hospital laboratories to national reference laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | Accelerates market access in European Union member states ahead of legacy assay replacement windows. |
| Hospital System Partnership | Secures multi-year reagent supply contracts with IDN purchasing committees controlling 60-70 percent of United States hospital volume. |
| Software Companion Development | Enables HL7/FHIR middleware connectivity between point-of-care coagulation devices and electronic health records systems. |
| Reimbursement Strategy | Establishes CPT code coverage for novel biomarker panels in stroke triage and perioperative monitoring protocols. |
| Backward Integration | Captures high-purity antibody supply through in-house production or captive relationships with Baden-Württemberg substrate suppliers. |
Research Methodology
Coverage spans the United States, Germany, India, Switzerland, and China, with primary inputs from each market's hospital procurement landscape and regulatory environment. The approach combines structured interviews with laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at hemostasis diagnostic manufacturers with secondary validation against FDA 510(k) filings, EMA IVDR submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up triangulation of analyzer installation counts and reagent consumption rates cross-references against top-down spending estimates from integrated delivery network annual reports.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including product type (anticoagulant assays, thrombolytic panels, platelet aggregation inhibitors), technology tier (immunoassay, mass spectrometry, ELISA), and end-user archetype (hospital core laboratory, point-of-care coordinator, national reference laboratory, research institution). CAGRs derive from instrument placement trajectories, reagent annuity per installed analyzer, and test menu expansion coefficients. Industry-specific forecast inputs include IVDR transition timelines for legacy assay replacement and PLI scheme capacity buildout curves in Indian manufacturing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA laboratory-developed test guidance enforcement, IVDR conformity assessment backlog resolution, and mass spectrometry platform adoption in academic medical centers. The analysis reflects assumptions regarding anticoagulant therapy expansion rates and health system consolidation velocity. A model refresh is warranted upon material change in United States IDN procurement centralization or European Union IVDR implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Global Liver Cancer Diagnostics Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
In-Vitro Diagnostics Enzymes Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Rapid Plasma Reagin Test Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market