
 Remote Diagnosis of Electric Vehicle Market | 2026-2036
Remote Diagnosis of Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Diagnosis of Electric Vehicle Market Insights
Market Context
Over-the-air diagnostic architectures is rewriting how automakers engineer vehicle health systems from the ground up. Robert Bosch GmbH leverages its embedded software heritage to anchor diagnostic tool development across European OEM supply chains. Denso Corporation sustains manufacturing scale advantages in sensor-integrated hardware modules for Japanese and North American automakers. Autel Intelligent Technology Corp competes aggressively on price-performance in aftermarket diagnostic interfaces for independent service networks.
Technical Definition and Segments
Remote diagnosis of electric vehicles encompasses the continuous or periodic assessment of battery state-of-health, motor controller performance, thermal management efficiency, and power electronics integrity through wireless data transmission to centralized analysis platforms, with primary commercial purpose of minimizing unplanned downtime and extending component service life. Software Solutions and AI Algorithms segments are capturing disproportionate margin pools as automakers prioritize predictive capability over reactive fault code retrieval. Hardware Modules and Telematics infrastructure remain volume-heavy categories where supply contracts tie to multi-year platform commitments and manufacturing scale determines unit economics.
Regulatory Frame
The EU AI Act, UNECE WP.29 cybersecurity regulations, and China's MIIT connected-vehicle standards collectively mandate encrypted data pipelines and standardized diagnostic reporting formats that reshape product development roadmaps for every supplier serving regulated markets. The U.S. NHTSA and EPA are separately advancing rulemakings on EV battery safety monitoring and emissions-related diagnostic communication protocols that will determine market access requirements. Stakeholders must monitor which regulatory jurisdiction's certification timeline becomes the pacing constraint for their next-generation platform launches.
Market Dynamics
Over-the-air mandate architectures are forcing automakers to rebuild vehicle health systems around continuous telemetry rather than intermittent workshop visits, compressing development cycles and supplier qualification timelines.
Growth Catalysts
- Fleet digitization:Commercial vehicle operators now require predictive uptime guarantees, embedding remote diagnostic modules into procurement specifications for heavy-duty electric trucks.
- EU Cyber Resilience Act:Mandatory software update capabilities for all connected products sold in Europe compels automakers to maintain live diagnostic channels throughout vehicle life cycles.
- Battery degradation modeling:Machine learning algorithms trained on cell-level voltage telemetry enable residual value forecasting that underpins leasing and secondary market liquidity.
Market Restraints
- Semiconductor supply concentration:Telematics control unit production clusters in Taiwan and South Korea create single-point vulnerability for diagnostic hardware availability.
- Cellular connectivity cost structure:Recurring data plan expenses for high-frequency sensor transmission erode margins in price-sensitive vehicle segments.
- Cross-border data friction:China's Data Security Law and Personal Information Protection Law impose localization requirements that fragment cloud-based diagnostic architectures.
Strategic Opportunities
- India's PLI scheme for automotive:Manufacturing incentives for advanced automotive technology create localized production pathways for diagnostic module suppliers.
- Second-life battery assessment:Remote state-of-health verification enables certified resale of retired EV packs into stationary storage applications.
- Insurance-telematics convergence:Usage-based coverage models require real-time driving behavior and battery stress data, opening direct channels between diagnostic platforms and underwriters.
Industry Challenges
- Embedded systems cybersecurity certification:UNECE WP.29 R155 compliance timelines strain engineering resources at tier-two suppliers lacking dedicated security teams.
- Legacy fleet retrofit complexity:First-generation EVs with limited CAN bus bandwidth resist cost-effective hardware upgrades for remote monitoring capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Diagnosis of Electric Vehicle Market |
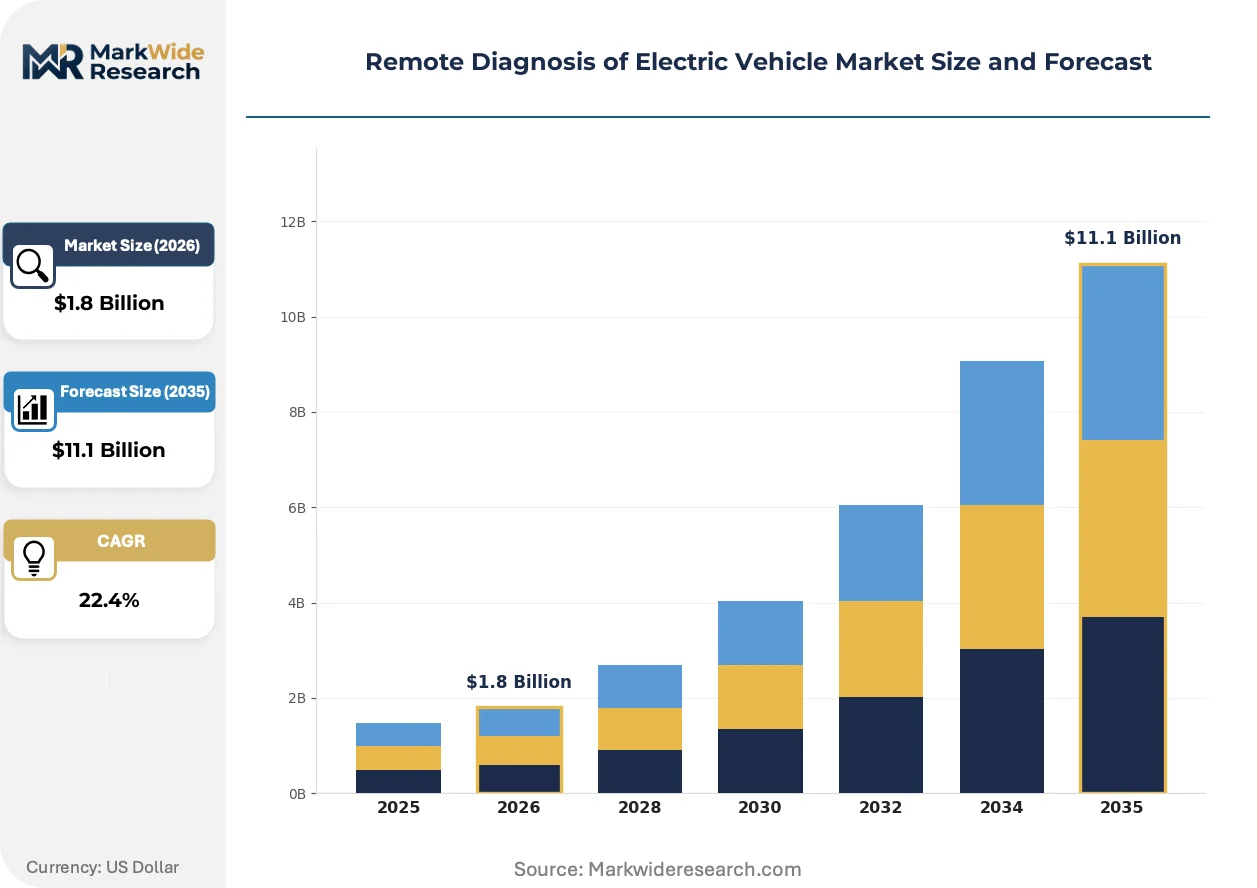
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Software Solutions, Hardware Modules, Data Analytics Platforms Technology: Telematics, IoT Integration, Cloud Computing, AI Algorithms End User: Automakers, Fleet Operators, Service Centers, Consumers Application: Real-Time Monitoring, Fault Detection, Performance Analysis, Predictive Maintenance |
| Companies Covered | Denso Corporation, Autel Intelligent Technology Corp, Robert Bosch GmbH, AVL DiTEST GmbH, Aptiv PLC, Continental AG, ZF Friedrichshafen AG, Snap-on Incorporated, Vector Informatik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Diagnosis of Electric Vehicle Market Trends and Innovations
Diagnostic intelligence is migrating from centralized cloud servers toward edge-computing architectures within vehicle gateways, reducing latency for safety-critical fault detection.
Digital twin technology is virtualizing physical battery assets, creating synchronized virtual replicas that simulate thermal runaway scenarios and cycle-life degradation without physical testing. Automotive engineers at major OEMs deploy these twins during platform development to compress validation schedules. The approach is virtualizing traditional destructive testing workflows and displacing physical prototype builds.
The EU AI Act's risk-based classification system subjects predictive maintenance algorithms to conformity assessments when they influence vehicle safety decisions. Tier-one suppliers now embed explainability requirements into neural network architectures for European market entry. Battery state-of-health prediction models face heightened documentation burdens that extend product launch timelines.
Service contract unbundling is fragmenting traditional dealership revenue streams, with fleet operators procuring diagnostic subscriptions directly from technology vendors rather than through OEM captive finance arms. Independent repair networks leverage aftermarket telematics interfaces to intercept maintenance revenue. This pattern concentrates in Germany and the Netherlands where block exemption regulations preserve multi-brand service competition.
Remote Diagnosis of Electric Vehicle Market Segmentation
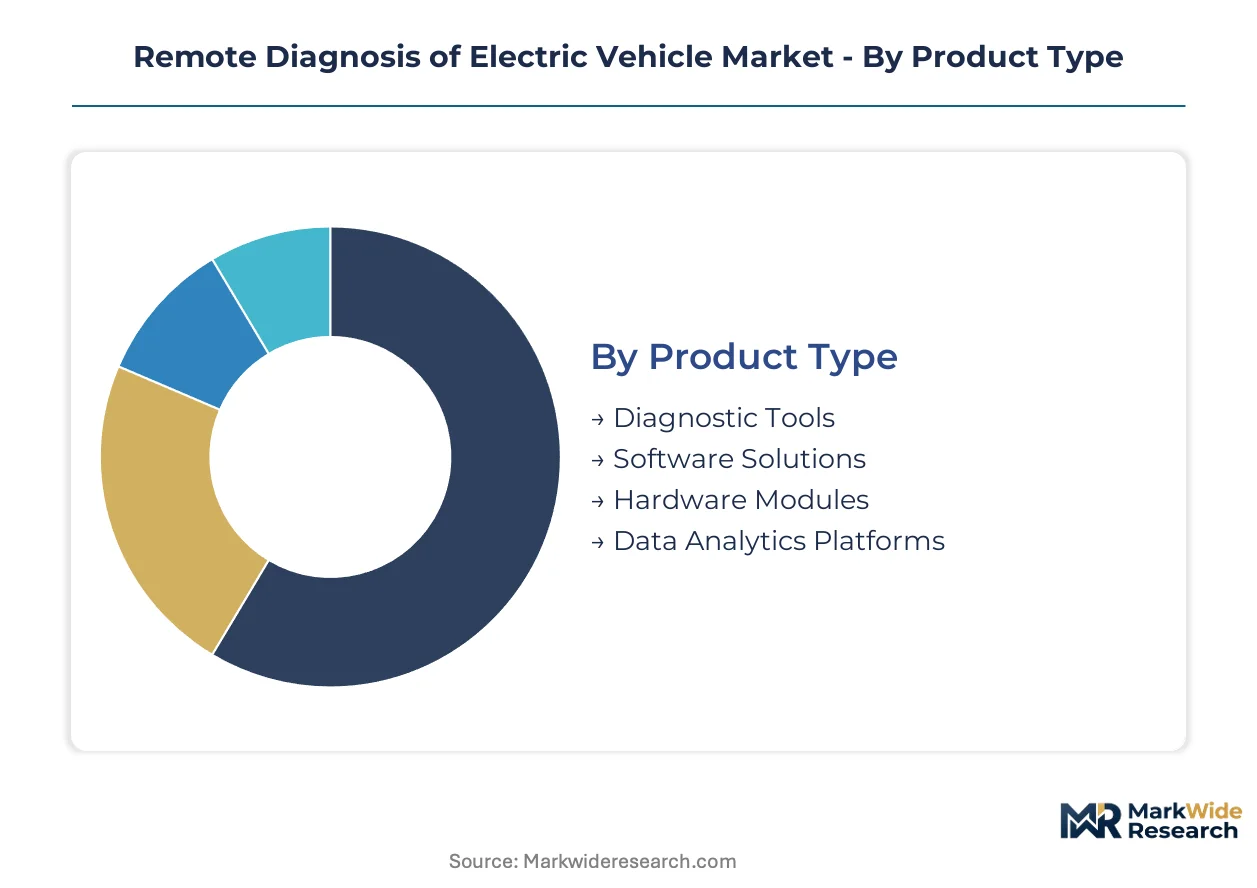
Segmentation in remote EV diagnosis reveals divergent investment cycles across product layers. Hardware modules lock in multi-year platform commitments while software solutions iterate quarterly. Understanding these temporal mismatches shapes supplier cash flow planning and R&D allocation priorities.
Product Type:
Diagnostic Tools refresh every 3-4 years alongside vehicle platform cycles, while Software Solutions deploy continuous updates. Hardware Modules carry 7-10 year design locks, and Data Analytics Platforms scale subscription revenue with minimal incremental infrastructure.
- Software Solutions:Embedded diagnostic algorithms process battery telemetry, motor controller signals, and thermal data through over-the-air pipelines. Fleet operators in China demand predictive modules that forecast cell degradation 18-24 months ahead of failure, compressing procurement evaluation timelines to under 90 days.
- Hardware Modules:Sensor-integrated telematics control units combine cellular modems, GPS receivers, and CAN bus interfaces in sealed automotive-grade enclosures. Japanese automakers specify these for 15-year vehicle life cycles, creating captive supply relationships with single-source qualification protocols that extend 24-36 months.
- Diagnostic Tools:Handheld and workshop-based interfaces retrieve fault codes and execute calibration routines through OBD-II and proprietary EV protocols. Independent service networks in Germany leverage aftermarket variants to intercept warranty-period maintenance revenue from OEM captives.
- Data Analytics Platforms:Cloud-native architectures aggregate multi-vehicle telemetry streams for cross-fleet pattern recognition. European Union Cyber Resilience Act mandates drive automakers to maintain these channels as permanent infrastructure rather than optional services.
Hardware Modules dominate installed base. Software Solutions is where expansion concentrates.
Technology:
AI Algorithms command premium pricing through predictive accuracy differentiation, while Telematics infrastructure commoditizes around cellular module cost curves. Cloud Computing scales with data volume; IoT Integration fragments across proprietary OEM protocols.
- AI Algorithms:Neural networks trained on voltage, temperature, and current signatures identify incipient battery faults before safety thresholds trigger. UNECE WP.29 cybersecurity regulations require explainability documentation for European market entry, extending validation schedules 6-12 months.
- Telematics:Cellular and satellite communication stacks transmit encrypted diagnostic packets to centralized servers. Production concentrates in Taiwan and South Korea, creating supply vulnerability that fleet procurement specifications now address through dual-source mandates.
- Cloud Computing:Distributed storage and compute resources process petabyte-scale vehicle telemetry for pattern detection and fleet optimization. China's Data Security Law forces localization of these architectures, fragmenting previously unified global platforms.
- IoT Integration:Edge gateways coordinate sensor data collection from battery management systems, motor controllers, and thermal loops. Protocol fragmentation across NIO, BYD, and XPeng proprietary stacks resists standardization, elevating integration costs for multi-brand service networks.
Telematics anchors current infrastructure spend. AI Algorithms is climbing the fastest.
End User:
Fleet Operators concentrate procurement volume through centralized RFP processes, while Consumers disaggregate across fragmented aftermarket channels. Automakers internalize development costs; Service Centers capture recurring subscription revenue.
- Fleet Operators:Commercial vehicle pools specify predictive uptime guarantees in procurement contracts, embedding remote diagnostic modules as non-negotiable line items. Heavy-duty electric truck deployments in California and the Netherlands require 99.5% availability commitments that only continuous health monitoring can underwrite.
- Automakers:OEM engineering organizations specify diagnostic architectures during platform development, locking supplier relationships 4-5 years before production launch. European Union AI Act conformity assessments now extend these timelines for algorithms influencing safety-critical decisions.
- Service Centers:Multi-brand repair networks subscribe to aftermarket diagnostic platforms to intercept maintenance revenue from OEM captives. Germany's block exemption regulations preserve this channel against vertical integration pressure.
- Consumers:Individual vehicle owners access diagnostic data through mobile applications with limited technical depth. Price sensitivity constrains subscription willingness to under $15 monthly, compressing margin pools relative to fleet contracts.
Automakers control architecture specification. Fleet Operators is gaining share fastest.
Application:
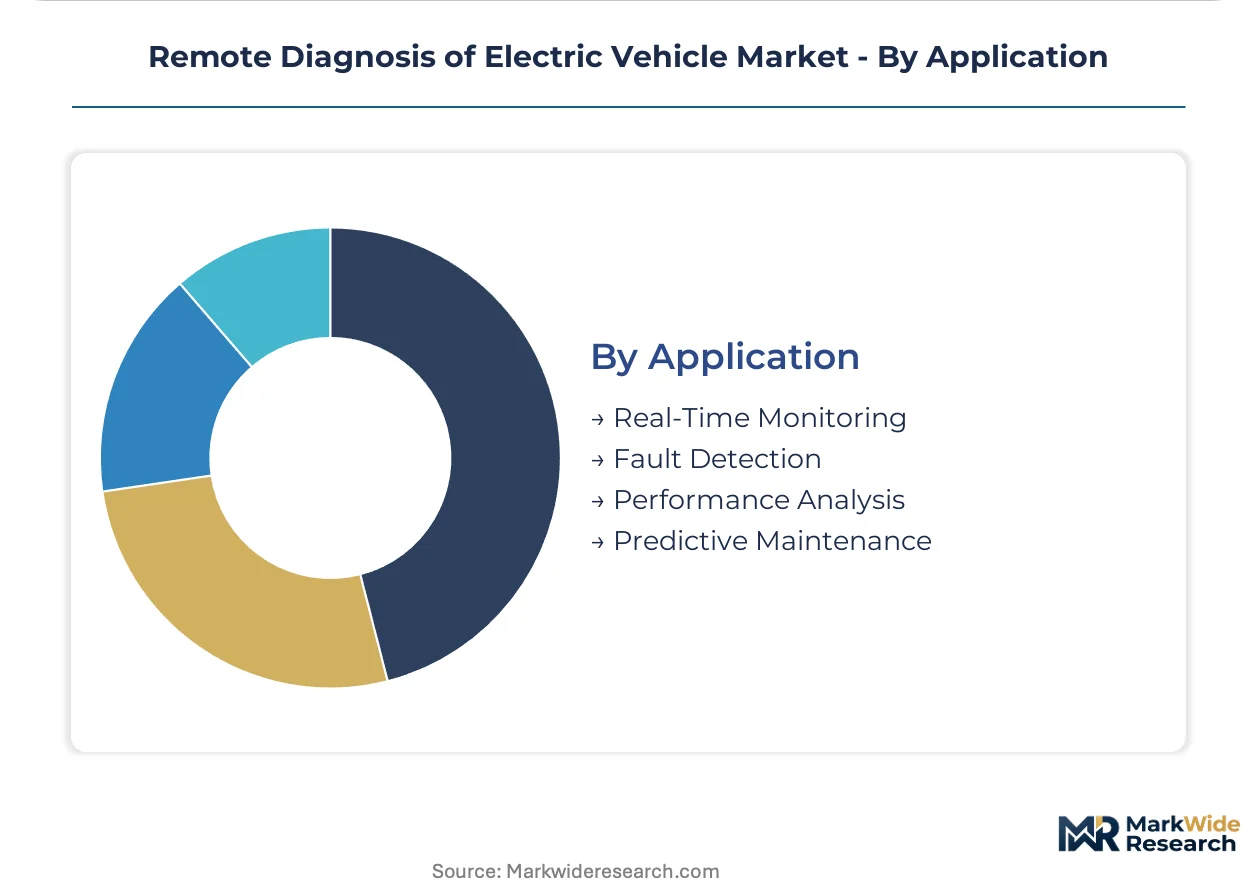
Predictive Maintenance generates recurring subscription revenue, while Real-Time Monitoring incurs continuous data transmission costs. Fault Detection triggers immediate intervention; Performance Analysis supports longer-cycle optimization decisions.
- Predictive Maintenance:Machine learning models forecast component failures from degradation pattern signatures, enabling scheduled replacement before unplanned downtime. Battery residual value forecasting for leasing and secondary markets depends on these predictions, creating direct linkage to financial services revenue.
- Real-Time Monitoring:Continuous telemetry streams enable immediate operator notification of thermal anomalies, insulation faults, and power electronics degradation. Cellular data plan costs erode margins in price-sensitive segments, driving edge-computing migration to reduce transmission frequency.
- Fault Detection:Automated alert generation triggers service scheduling and parts pre-positioning when threshold breaches occur. Integration with insurance-telematics platforms opens direct billing channels for usage-based coverage models.
- Performance Analysis:Aggregated fleet data identifies efficiency optimization opportunities across charging patterns, route selection, and driver behavior. Long-haul electric truck operators in China deploy these insights to maximize battery cycle life across 500,000+ kilometer service intervals.
Real-Time Monitoring dominates current deployment. Predictive Maintenance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese diagnostic module suppliers export heavily into European fleet operator procurement channels, while German engineering houses license embedded software architectures to Japanese automakers. Regulatory fragmentation across data localization mandates and cybersecurity certification timelines is forcing suppliers to maintain parallel development tracks for major destination markets.
China
MIIT connected-vehicle standards mandate encrypted diagnostic pipelines for all new energy vehicles sold domestically. NIO, BYD, and XPeng operate proprietary telemetry stacks that resist cross-brand standardization. The Yangtze River Delta hosts concentrated telematics hardware production serving both domestic OEMs and export markets.
Germany
EU Cyber Resilience Act compliance deadlines compress supplier qualification timelines for diagnostic software vendors. KBA type-approval processes for over-the-air update systems extend platform development cycles 6-12 months. Stuttgart and Munich anchor embedded systems engineering clusters where Bosch and Continental maintain captive diagnostic tool development.
United States
NHTSA advancing EV battery safety monitoring rulemakings creates certification requirements for predictive health algorithms. California Air Resources Board emissions diagnostic protocols influence national standard-setting. Detroit engineering centers specify diagnostic architectures for heavy-duty electric truck platforms requiring 99.5% uptime guarantees.
Japan
METI subsidies for connected vehicle infrastructure accelerate fleet operator adoption of predictive maintenance platforms. JIS standards for automotive cybersecurity create documentation burdens for foreign diagnostic suppliers. Nagoya manufacturing corridors produce sensor-integrated telematics control units under 15-year vehicle lifecycle specifications.
South Korea
MFDS-equivalent automotive cybersecurity frameworks align with UNECE WP.29 R155 timelines for embedded systems certification. Seoul Capital Area semiconductor fabrication clusters supply cellular modems for telematics control units. Domestic automakers specify dual-source procurement mandates to mitigate Taiwan supply concentration risk.
Remote Diagnosis of Electric Vehicle Market Competitive Landscape
On the supply side, the industry is tiered between integrated automotive electronics conglomerates and specialized diagnostic tool vendors. Tier-one suppliers leverage multi-year platform commitments to lock in hardware module supply relationships. Three strategic archetypes dominate: embedded software licensors, sensor-integrated hardware fabricators, and aftermarket interface specialists. Competitive moves concentrate on strategic partnerships for regulatory certification and portfolio diversification into battery second-life assessment tools.
Among German-based engineering conglomerates, Robert Bosch GmbH and Continental AG exemplify the embedded software licensor archetype, supplying diagnostic architectures across European OEM supply chains. Denso Corporation anchors the sensor-integrated hardware tier through Japanese and North American automaker relationships. Autel Intelligent Technology Corp occupies the aftermarket specialist position, competing on price-performance for independent service network procurement.
| Leading Market Players |
|---|
| Denso Corporation |
| Autel Intelligent Technology Corp |
| Robert Bosch GmbH |
| AVL DiTEST GmbH |
| Aptiv PLC |
| Continental AG |
| ZF Friedrichshafen AG |
| Snap-on Incorporated |
| Vector Informatik GmbH |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's containerized electronics logistics costs cascade through diagnostic hardware pricing tiers, amplifying margin compression for Taiwan-sourced telematics modules while enabling European software vendors to command certification-linked premiums.
Pricing Analysis
Next-generation AI-powered predictive algorithms extract 40-60% price premiums over current-generation rule-based diagnostic tools, while prior-generation OBD-II interfaces commoditize below $200 per unit. Three-tier pricing structure across premium, standard, and economy levels stratifies by cybersecurity certification grade and fleet contract volume scale. Pricing pressure stems from cellular data plan cost absorption eroding SaaS margins in price-sensitive consumer segments. Fleet operators exhibit lowest price sensitivity due to uptime guarantee requirements, while independent service networks negotiate aggressively on hardware module procurement.
Supply Chain Analysis
US semiconductor export controls on advanced AI accelerators constrain next-generation edge-computing diagnostic chip flows to Chinese telematics module assemblers. Supply concentrates in Taiwan for cellular modems, South Korea for automotive-grade memory, and China for battery management system integration. Raw material dependencies span lithium-ion cells, rare-earth magnets for motor sensors, and high-temperature ceramics for power electronics. Single-source vulnerability in Taiwan semiconductor fabrication creates procurement risk for European automakers. Distribution runs through OEM captive supply chains for hardware modules and direct SaaS subscriptions for predictive analytics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Cyber Resilience Act's mandatory over-the-air update infrastructure is compressing supplier qualification timelines and rewriting competitive dynamics across diagnostic value chains.
For Market Incumbents: Harden embedded software architectures against UNECE WP.29 R155 cybersecurity certification requirements through dedicated security engineering teams. Acquire edge-computing semiconductor specialists to reduce dependency on Taiwan-sourced telematics control units. Lock in 7-10 year platform commitments with Japanese automakers before next-generation EV architectures finalize.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-scheme subsidized automotive manufacturing corridor for localized diagnostic module production. Target aftermarket retrofit opportunities for first-generation EVs with limited CAN bus bandwidth through cost-optimized hardware interfaces. Pursue direct fleet operator relationships bypassing OEM captive finance arms in Germany and the Netherlands.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates' non-core automotive electronics divisions lacking AI algorithm development capabilities. Five-to-ten year viability hinges on predictive maintenance software margin expansion outpacing hardware commoditization. Monitor EU AI Act explainability documentation burdens as the inflection signal for algorithm-centric valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Bosch and Continental drive unified diagnostic architectures across European OEM supply chains. |
| Battery Supply Agreement | Second-life battery assessment tools require certified cell health data partnerships with leasing arms. |
| Software-Defined Vehicle Investment | Edge-computing migration reduces latency for safety-critical fault detection in NIO and XPeng fleets. |
| Geographic Manufacturing Footprint | India's PLI incentives attract localized telematics module production away from Taiwan concentration. |
| Charging Infrastructure Partnership | Real-time battery stress data from fast-charging cycles feeds predictive degradation models. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, fleet operator maintenance heads, and aftermarket service network managers; and secondary validation against vehicle production databases, MIIT connected-vehicle standard filings, EU Cyber Resilience Act implementation guidance, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Forecast inputs span battery electric vehicle production volumes, telematics penetration rates by vehicle class, software subscription attach rates, and regional regulatory adoption timelines across the projection horizon. Segmentation modeling incorporates product type, technology layer, end-user archetype, and application purpose. CAGRs derive from logistic diffusion curves fitted to historical connected vehicle deployment patterns and battery degradation model adoption rates.
Sensitivities concentrate around semiconductor supply disruption duration, cellular data cost trajectories, and cross-border data localization enforcement intensity. Forecasts reflect documented assumptions on regulatory compliance timelines and fleet digitization investment cycles. Material shifts in EU AI Act enforcement rigor or US-China technology trade restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
US Influenza Diagnostics Market
Diagnostics
India Molecular Diagnostic Controls Market
Diagnostics
Breast Cancer Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
North America Antinuclear Antibody Test Market